
 Laminated Woven PP Bags Market | 2026-2036
Laminated Woven PP Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Woven PP Bags Market Foresight
Aftermarket custom printing and branding services is reconfiguring margin distribution across the laminated woven PP bags value chain. LC Packaging International BV leverages its European distribution network to sustain premium positioning in agricultural bulk packaging. Mondi Group anchors its competitive stance through integrated film extrusion and lamination capabilities. Emmbi Industries Limited specializes in food-grade certified constructions for domestic Indian grain procurement.
Laminated woven PP bags consist of polypropylene tapes woven into a tubular or flat fabric, subsequently bonded with BOPP, PE, or specialized barrier films through extrusion lamination, yielding tensile strengths exceeding 50 kg/cm² and moisture vapor transmission rates below 5 g/m²/day for extended agricultural storage. Heavy-duty bags dominate volume shipments for fertilizer and cement handling, while gusseted configurations capture expanding share in retail grocery distribution due to shelf-standing stability. Biodegradable film laminations represent the fastest-growing material trajectory as European retailers enforce plastic reduction commitments.
India's BIS mandates food-contact safety testing under IS 10146, while the EU Packaging and Packaging Waste Regulation imposes recycled content thresholds that reshape film sourcing strategies for exporters. REACH compliance in Europe restricts certain adhesive chemistries in lamination layers, compelling reformulation investments among Asian manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in target export markets to preempt compliance-driven cost escalations.
Market Dynamics
The laminated woven PP bags market is being restructured by India's BIS certification mandates for food-contact packaging, which are forcing manufacturers to upgrade lamination quality and testing protocols while consolidating production around Gujarat and Maharashtra's petrochemical clusters.
Growth Catalysts
- Agricultural grain handling modernization:Farmers across India's wheat belt are abandoning jute sacks for moisture-resistant laminated PP constructions that protect harvests during monsoon storage.
- BIS IS 10146 compliance infrastructure:India's mandatory food-contact safety testing has created certified supply scarcity that rewards early-adopting manufacturers with procurement lock-ins from Food Corporation of India.
- Biodegradable film laminations:European retailers' plastic reduction commitments are pulling Indian exporters toward starch-based and oxo-biodegradable barrier films.
Market Restraints
- Polypropylene resin price volatility:Feedstock costs tied to naphtha cracking margins in Reliance Industries' Jamnagar complex transmit directly to bag converter margins.
- REACH adhesive restrictions:ECHA's evolving restrictions on solvent-based lamination chemistries force Asian manufacturers into costly water-based adhesive reformulation.
- Jute subsidy persistence:India's Jute Packaging Materials Act mandates food grain packaging in jute, creating a subsidized substitute that caps PP bag penetration in certain procurement channels.
Strategic Opportunities
- Gusseted retail grocery configurations:India's organized retail expansion creates shelf-standing stability demand that flat-woven bags cannot satisfy.
- EU Packaging and Packaging Waste Regulation recycled content thresholds:Exporters who secure post-industrial PP film supply chains gain preferential access to European agricultural bulk buyers.
- Aftermarket custom printing services:Brand owners seeking traceability and anti-counterfeiting features are unbundling printing from base bag manufacturing.
Industry Challenges
- Food-grade certification timeline compression:BIS testing protocols for migration limits and heavy metal content extend new product qualification cycles beyond seasonal procurement windows.
- Extrusion lamination equipment capex intensity:Multi-layer coextrusion lines capable of sub-5 g/m²/day moisture vapor transmission rates require capital deployment that mid-scale weavers cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Woven PP Bags Market |
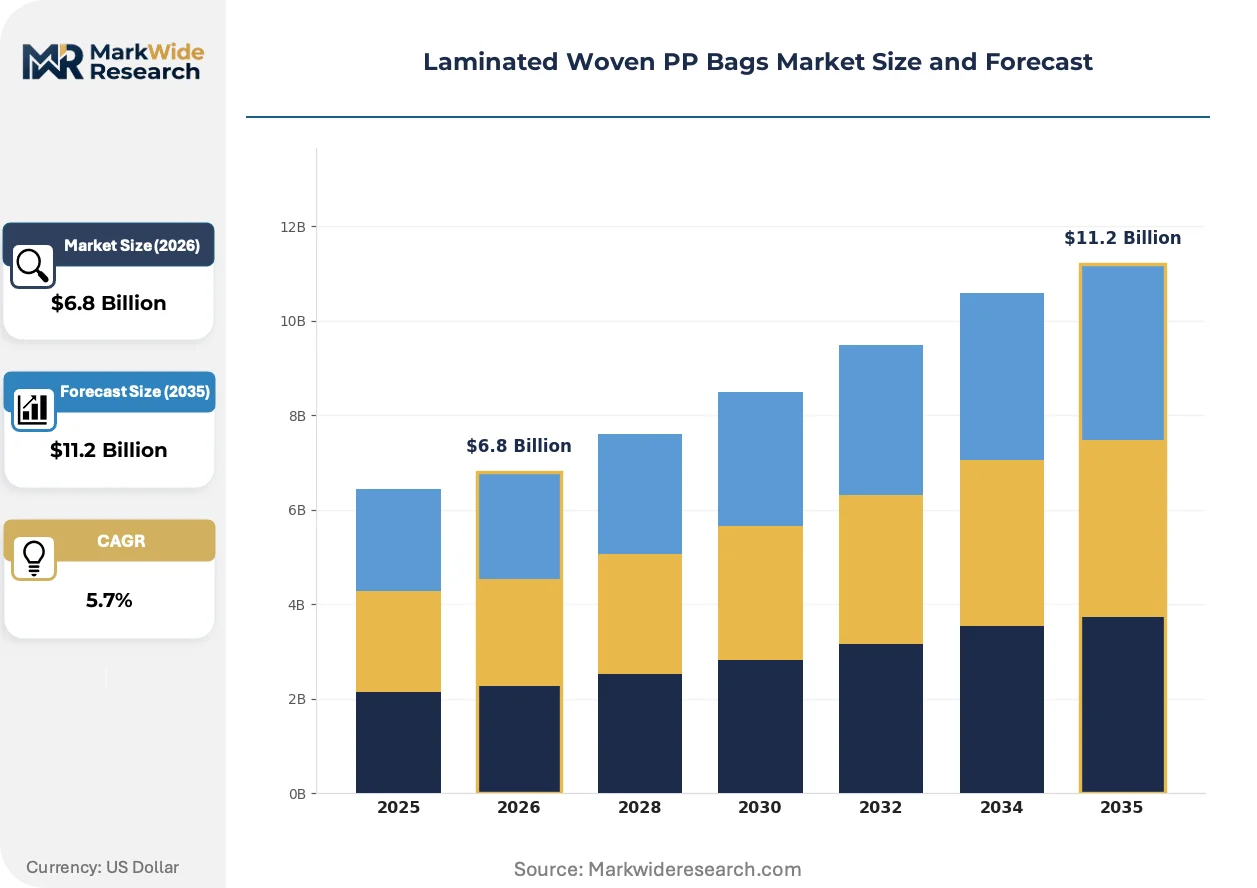
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawstring Bags, Gusseted Bags, Pouches, Heavy-Duty Bags End User: Agriculture, Food Packaging, Industrial Use, Retail Material: Polypropylene, Laminated Non-Woven, Recyclable Films, Biodegradable Films Application: Material Handling, Shipping, Storage, Groceries |
| Companies Covered | LC Packaging International BV, Emmbi Industries Limited, Berry Global Inc., Shrijikrupa Polypack Pvt. Ltd., Al-Tawfiq Company, Mondi Group, Muscat Polymers Pvt. Ltd., Rishi FIBC Solutions Pvt. Ltd., Uflex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Woven PP Bags Market Shifts & Advancements
Digital printing and smart packaging integration are rewriting value capture in laminated woven PP bags, shifting margin from commodity fabrication toward differentiated branding and traceability services.
Digital inkjet printing systems with UV-curable inks are virtualizing the traditional flexographic pre-print model for short-run custom bag orders. Agricultural cooperatives and specialty grain exporters are adopting these systems for lot-specific branding and QR-code traceability. This virtualization collapses minimum order quantities from ten thousand units to five hundred, enabling just-in-time procurement patterns that challenge inventory-heavy conventional converters.
The EU Packaging and Packaging Waste Regulation's recycled content mandates are forcing Indian exporters to reengineer film sourcing strategies. Manufacturers must now document post-industrial PP recovery rates across their lamination supply chains to maintain European market access. Agricultural bulk packaging destined for EU distributors faces the most acute compliance pressure, driving partnerships with European film recyclers.
Brand owners are unbundling anti-counterfeiting features from base bag specifications and contracting them separately through security printing specialists. Pharmaceutical and premium seed companies in Maharashtra's agribusiness corridor now specify holographic strips and microtext as standalone procurement line items. This disaggregation is most visible in western India's organized retail and export-oriented agricultural processing zones.
Laminated Woven PP Bags Market Segmentation
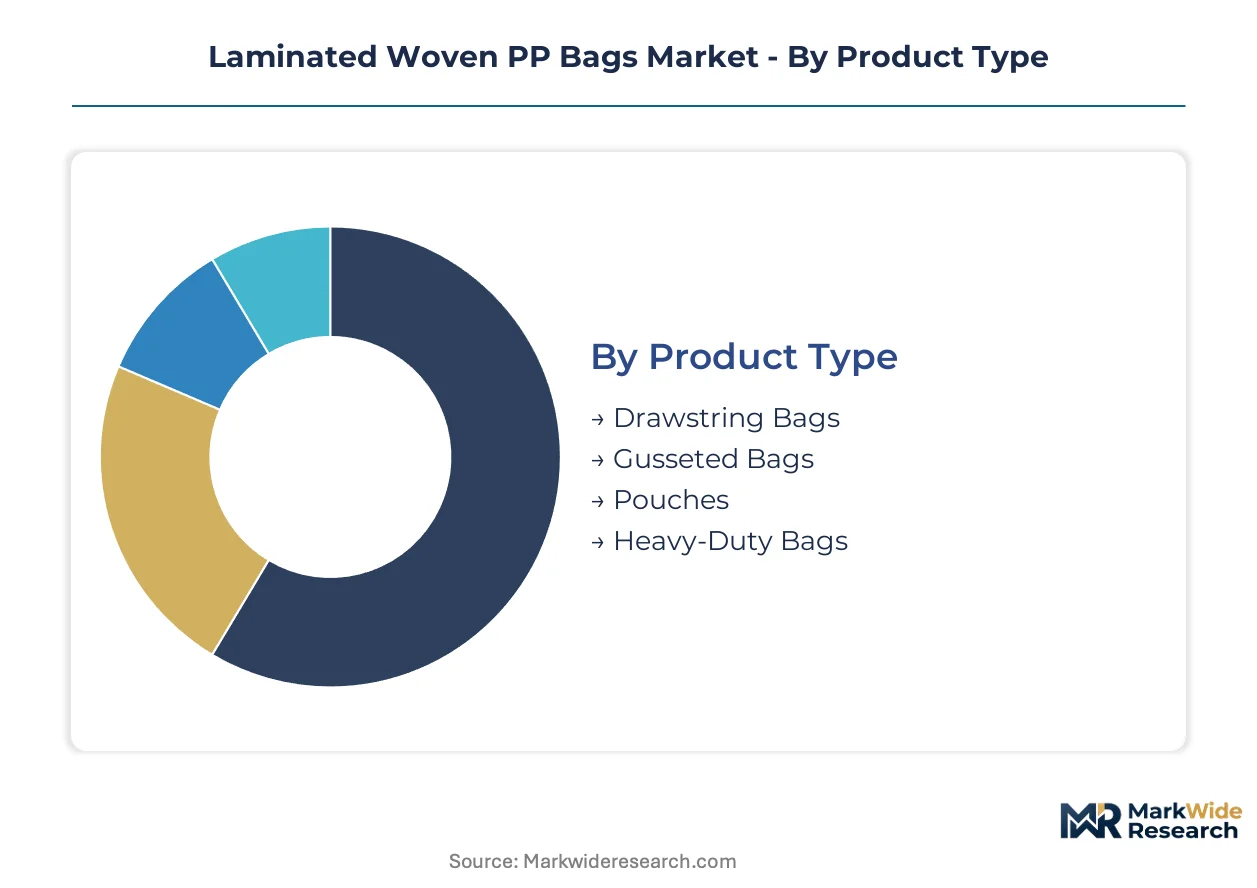
Segmentation in laminated woven PP bags reveals how specification, end-use, and material compliance interact to determine procurement patterns. Buyers select configurations based on load-bearing requirements, regulatory exposure, and shelf-display needs rather than commodity pricing alone.
Product Type:
Product configurations span from lightweight retail formats to industrial bulk containers, with structural design dictating both manufacturing complexity and margin capture.
- Heavy-Duty Bags:Multi-ply woven constructions with reinforced seams handle loads exceeding 50 kg for fertilizer, cement, and agricultural commodity transport. India's Food Corporation of India procurement concentrates demand in Gujarat and Maharashtra where integrated extrusion-lamination lines achieve IS 10146 certification.
- Gusseted Bags:Side-folded panels create rectangular profiles that stand upright on retail shelves, addressing organized grocery requirements in western India's urban corridors. The format commands premium pricing over flat-woven alternatives due to specialized cutting and stitching equipment.
- Drawstring Bags:Integrated closure systems serve small-lot agricultural seed packaging and specialty food ingredients where resealability matters.
- Pouches:Compact formats target retail grocery portion control and promotional sampling applications with lower volume thresholds.
Established volume favors heavy-duty configurations; emerging adoption favors gusseted formats.
End User:
End-use concentration determines certification requirements, with food-contact and agricultural procurement subject to the most stringent compliance protocols.
- Agriculture:Grain handling, fertilizer packaging, and seed distribution dominate tonnage, with moisture resistance during monsoon storage driving laminated construction adoption. BIS IS 10146 migration testing is mandatory for Food Corporation of India suppliers.
- Food Packaging:Processed food and ingredient handling requires certified food-contact laminations with documented heavy metal compliance, creating supply scarcity that rewards early-certified manufacturers.
- Retail:Organized grocery chains in Maharashtra and Gujarat specify gusseted configurations with custom printing for shelf differentiation.
- Industrial Use:Cement, chemicals, and construction materials utilize heavy-duty formats where tensile strength supersedes food-grade certification requirements.
Procurement scale clusters in agricultural channels; margin expansion concentrates in food-certified segments.
Material:
Material selection balances cost, barrier performance, and regulatory positioning across domestic and export markets.
- Polypropylene:Virgin PP tapes woven into tubular or flat fabric provide the substrate for all laminated constructions, with tensile strength and extrusion compatibility determining grade selection.
- Biodegradable Films:Starch-based and oxo-biodegradable barrier laminations respond to EU retailer plastic reduction commitments, representing the steepest expansion trajectory among material options.
- Recyclable Films:Post-industrial PP recovery streams are being documented to satisfy EU Packaging and Packaging Waste Regulation recycled content thresholds for export-bound agricultural bulk packaging.
- Laminated Non-Woven:Spunbond alternatives serve applications requiring softer hand feel and lower rigidity than woven substrates.
Cost efficiency favors conventional polypropylene; regulatory access favors biodegradable and recyclable film investments.
Application:
Application context dictates barrier specifications, with extended storage and maritime exposure requiring the most demanding moisture vapor transmission rates.
- Storage:Extended agricultural warehousing during monsoon seasons demands sub-5 g/m²/day moisture vapor transmission rates through multi-layer coextrusion lamination.
- Shipping:Maritime container transport subjects bags to humidity cycling and condensation exposure, driving adoption of heavy-duty laminated formats with heat-sealed seams.
- Material Handling:Forklift and conveyor compatibility requires specified tensile strength and sling-point reinforcement for fertilizer and cement logistics.
- Groceries:Retail shelf presentation prioritizes gusseted stability and printable surface area for brand communication in organized retail environments.
Performance requirements intensify in storage and shipping; convenience differentiation dominates grocery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys laminated woven PP bags predominantly for agricultural grain procurement, whereas European buyers prioritize biodegradable laminations for retail compliance, creating divergent specification requirements across major consumption zones.
India
Food Corporation of India procurement drives heavy-duty bag consumption across wheat and rice belts. BIS IS 10146 certification mandates reshape supplier qualification timelines. Production clusters concentrate in Gujarat's petrochemical corridor and Maharashtra's Thane-Bhiwandi belt, where integrated extrusion-lamination lines achieve food-grade compliance.
Germany
Retail grocery chains demand gusseted configurations with documented recycled content for shelf-standing stability. ECHA REACH restrictions on solvent-based lamination adhesives accelerate water-based chemistry adoption. The Rhine-Ruhr industrial zone hosts converters serving agricultural bulk exporters targeting EU Packaging and Packaging Waste Regulation thresholds.
United States
Midwestern grain elevators and fertilizer distributors specify heavy-duty laminated formats for moisture protection during extended storage. EPA industrial emissions guidelines influence lamination facility siting decisions. Chicago-Gary and Houston petrochemical corridors anchor domestic PP tape and film supply integration.
Brazil
Soybean and corn export handlers drive adoption of maritime-grade laminated bags with sub-5 g/m²/day moisture barriers. ANVISA food-contact packaging regulations govern domestic grain processor procurement. São Paulo state's industrial belt concentrates converter capacity serving Mercosur agricultural trade routes.
China
Fertilizer and chemical logistics dominate heavy-duty bag consumption alongside emerging retail grocery formats. GB standards for food-contact plastics impose migration testing requirements on domestic manufacturers. The Yangtze River Delta clusters PP resin production with downstream weaving and lamination operations.
Laminated Woven PP Bags Market Competitive Landscape
Capability concentration sits with integrated film extrusion specialists; scale advantage sits with high-volume weavers serving commodity agricultural channels. The market structures around three tiers: petrochemical-integrated converters with captive resin supply, independent laminators purchasing PP tapes and films on spot markets, and regional weavers without lamination capacity. Dominant competitive moves include backward integration into film extrusion and certification-driven customer lock-ins through BIS or EU compliance documentation.
Among the named participants, LC Packaging International BV and Mondi Group occupy positions reflecting European integrated packaging capabilities, while Emmbi Industries Limited exemplifies India-focused food-grade certification specialization. Berry Global Inc. represents North American diversified packaging scale. Shrijikrupa Polypack Pvt. Ltd., Muscat Polymers Pvt. Ltd., and Rishi FIBC Solutions Pvt. Ltd. sit within India's western state production clusters, with Uflex Ltd. spanning flexible packaging laminations across multiple substrate categories. Al-Tawfiq Company anchors Middle Eastern regional supply for agricultural export corridors.
| Leading Market Players |
|---|
| LC Packaging International BV |
| Emmbi Industries Limited |
| Berry Global Inc. |
| Shrijikrupa Polypack Pvt. Ltd. |
| Al-Tawfiq Company |
| Mondi Group |
| Muscat Polymers Pvt. Ltd. |
| Rishi FIBC Solutions Pvt. Ltd. |
| Uflex Ltd. |
| Others |
Supply & Pricing Matrix
Reliance Industries' Jamnagar petrochemical complex anchors polypropylene resin supply for India's western state converters, concentrating margin capture with integrated extrusion-lamination operators while spot-market weavers absorb feedstock volatility.
Pricing Analysis
Long-term offtake contracts with Food Corporation of India lock in volume commitments for BIS-certified manufacturers, while spot-market transactions dominate uncertified industrial bag trade. Price differentiation hinges on IS 10146 migration testing documentation and gusseted format premiums over flat-woven alternatives. Pricing pressure intensifies in standard heavy-duty segments as mid-scale weavers without lamination capacity compete on tape thickness alone. Agricultural cooperatives exhibit highest price sensitivity, whereas pharmaceutical and premium seed buyers prioritize anti-counterfeiting features over unit cost.
Supply Chain Analysis
EU REACH restrictions on solvent-based lamination adhesives limit technology transfer to Asian manufacturers, reshaping equipment sourcing patterns. Raw material flows draw from Saudi Arabian PP resin, South Korean BOPP film, and domestic Indian tape extrusion. Single-source vulnerability concentrates in specialized coextrusion line imports from Germany and Italy. Distribution runs through Gujarat's petrochemical corridor to Maharashtra's Thane-Bhiwandi converter belt, with export-bound agricultural bulk reaching European distributors via Rotterdam and Hamburg gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and application segments creates multiple niche entry points, as BIS compliance timelines and EU recycled content mandates split demand into discrete supplier pools with divergent capability requirements.
For Market Incumbents: Build certification moats through early BIS IS 10146 qualification and documented EU Packaging and Packaging Waste Regulation compliance to preempt customer lock-ins. Expand extrusion-lamination capacity in Gujarat's petrochemical corridor to capture integrated margin. Defend against biodegradable film specialists by securing starch-based lamination partnerships before European retailer mandates harden. For New Entrants and Emerging Players: Uncertified mid-scale weavers in eastern India's rice belt represent the most penetrable entry point for digital printing and smart packaging services unbundled from base bag manufacturing. Target aftermarket custom branding for agricultural cooperatives seeking lot-specific traceability. Establish UV-curable inkjet partnerships to collapse minimum order quantities and enable just-in-time procurement patterns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging converters diversifying from film into woven substrates. Five-to-ten year viability favors operators with captive resin supply and multi-regulatory certification infrastructure. Watch EU biodegradable film mandate acceleration as inflection signal for stranded conventional lamination capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive BOPP supply secures margin against Reliance Industries' naphtha-crack margin volatility. |
| Multi-Regulatory Certification Investment | Simultaneous BIS IS 10146 and EU REACH compliance opens Food Corporation of India and European export channels. |
| Biodegradable Lamination Partnership | Starch-based film alliances preempt European retailer plastic reduction commitment enforcement. |
| Digital Printing Capability Addition | UV-curable inkjet systems capture unbundled branding demand from agricultural cooperatives and seed companies. |
| Post-Industrial PP Recovery Documentation | Verified recycled content streams satisfy EU Packaging and Packaging Waste Regulation thresholds for export-bound agricultural bulk. |
Research Methodology
Desk research of customs trade data, BIS certification registries, and EU Packaging and Packaging Waste Regulation implementation guidance preceded structured interviews with extrusion-lamination plant managers, Food Corporation of India procurement officers, agricultural cooperative supply chain heads, and European retail packaging sustainability directors. Secondary validation drew from SEC filings of listed packaging converters, Reliance Industries' petrochemical segment disclosures, and ECHA REACH restriction updates. Bottom-up capacity modeling triangulated against top-down agricultural procurement volume estimates.
Assumptions held fixed include BIS IS 10146 enforcement timelines and EU recycled content threshold phase-in schedules, while polypropylene resin price trajectories and monsoon season storage demand patterns were varied across sensitivity scenarios. Segmentation dimensions spanned product configuration, end-use certification tier, material compliance pathway, and regional production cluster. CAGRs derived from fitted growth curves applied to verified base-year volumes, with agricultural grain handling modernization and biodegradable film substitution rates as key demand-side inputs.
Practitioners should monitor BIS testing protocol amendments and EU Packaging and Packaging Waste Regulation delegated act releases for early signals of qualification timeline compression. Forecasts reflect these documented assumptions. Material shifts in polypropylene feedstock cost structures or European biodegradable mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Shrink Bags Market