
 Freezing Bags Market | 2026-2036
Freezing Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Freezing Bags Market Analytics
Food-grade polymer certification is unwinding legacy commodity positioning across the freezing bags landscape. Reynolds Consumer Products leverages captive film extrusion capacity to sustain cost leadership in North American retail channels. Sartorius AG anchors the biopharma cold-storage segment with ultra-low-temperature validated bag systems. Thermo Fisher Scientific differentiates through laboratory-grade traceability protocols that extend into clinical logistics.
Freezing bags are multi-layer polymer pouches engineered to withstand temperatures from ambient down to minus eighty degrees Celsius without embrittlement or seal failure, serving food preservation, biomedical specimen transport, and industrial cold-chain applications. Quart-capacity zip-lock configurations dominate household procurement due to freezer-space efficiency, while vacuum-seal formats command premium placement among restaurants and caterers prioritizing shelf-life extension. Biodegradable product types capture regulatory tailwinds though cost structures currently limit penetration beyond institutional food-service contracts.
FDA food-contact substance notifications govern polymer migration limits in US commercial freezing applications, while the EU Single-Use Plastics Directive and REACH chemical compliance reshape material specifications for European suppliers. BIS polymer standards in India and China's GB food-contact national standards add compliance layers for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass through price adjustments to channel partners.
Market Dynamics
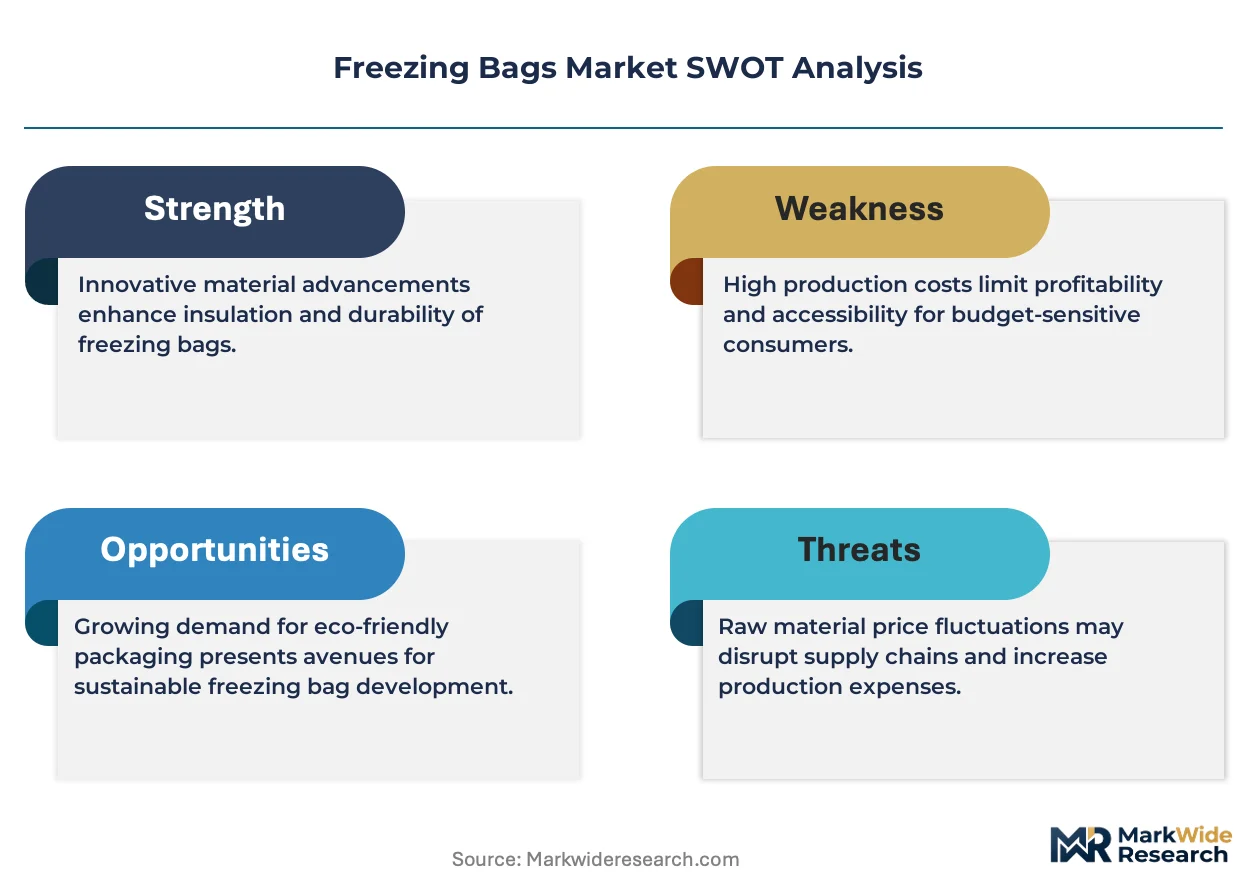
Material substitution pressures from the EU Single-Use Plastics Directive are forcing freezing bag manufacturers to requalify polymer formulations, creating a bifurcation between legacy polyethylene suppliers and biodegradable innovators racing for food-contact certification.
Growth Catalysts
- EU Single-Use Plastics Directive:The mandate accelerates demand for certified biodegradable alternatives in institutional food service across Germany, France, and the Netherlands.
- Biopharma cold-chain expansion:Cell and gene therapy logistics require validated ultra-low-temperature bag systems from ambient to minus eighty degrees Celsius.
- Germany's industrial food processing corridor:Concentrated meat and prepared-meal production sustains bulk procurement of multi-layer vacuum-seal configurations.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings compress margins for conventional polyethylene film extruders serving retail channels.
- Compostable resin supply concentration:PLA and PBAT production clusters in Thailand and China create import dependency for European converters.
- Seal integrity at cryogenic temperatures:Embrittlement failures in minus eighty degrees Celsius storage limit adoption in long-term biobanking applications.
Strategic Opportunities
- India's cold-chain infrastructure buildout:FSSAI-mandated food safety protocols drive first-time adoption of certified freezing bags in dairy and seafood processing.
- Reusable silicone bag formats:Direct-to-consumer subscription models bypass retail margin stacking for household segments.
- Extended producer responsibility frameworks:France's AGEC law and Italy's plastic tax create preferential procurement channels for recyclable-content suppliers.
Industry Challenges
- Food-contact migration testing timelines:FDA notification reviews and EFSA re-evaluations extend new product qualification to eighteen to twenty-four months.
- Multi-layer film recycling infrastructure:Mechanical separation limitations force reliance on chemical recycling partnerships with uncertain capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezing Bags Market |
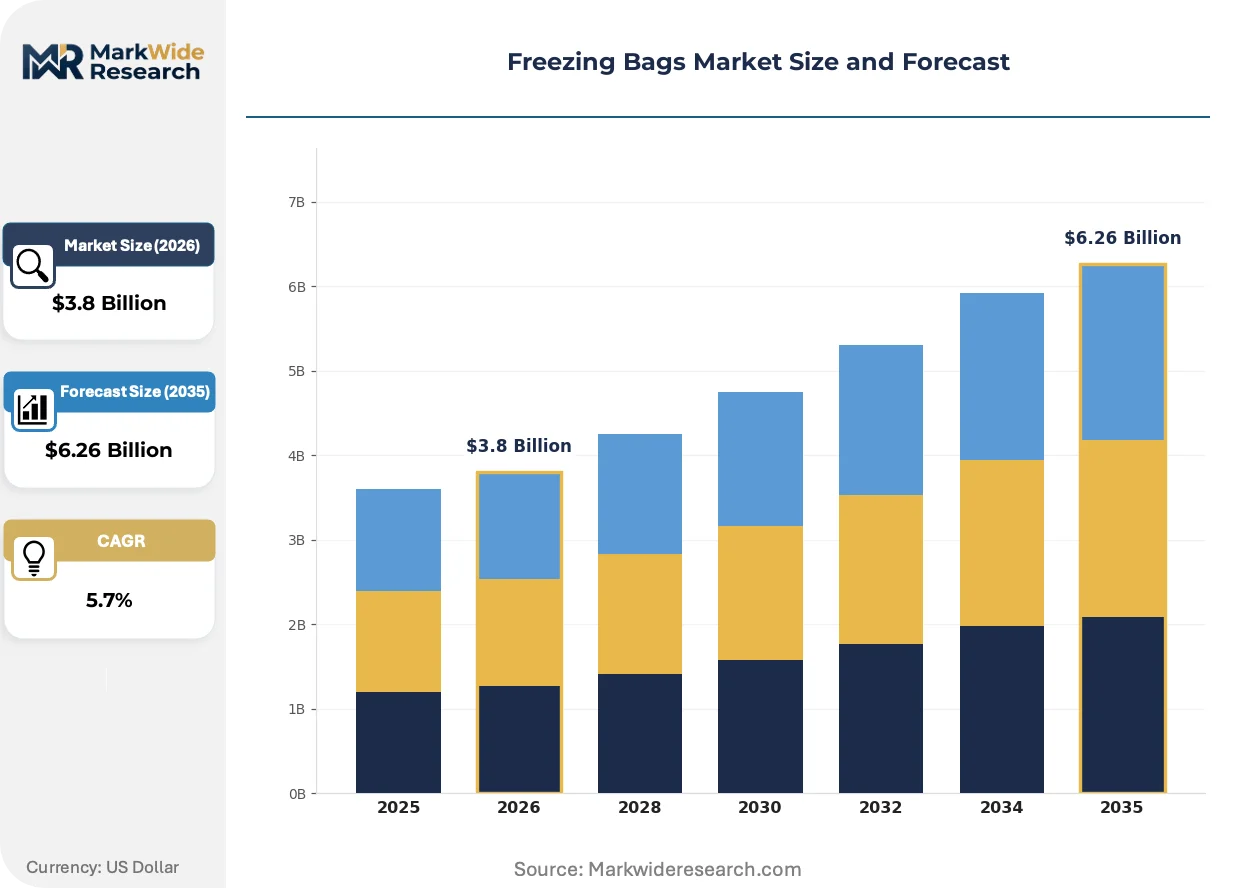
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Reusable, Vacuum Seal, Biodegradable Closure Type: Zip Lock, Twist Tie, Heat Seal, Button Capacity: Quart, Gallon, Pint, Half-Gallon End User: Household, Restaurants, Caterers, Food Manufacturers |
| Companies Covered | SC Johnson & Son, Inc., Reynolds Consumer Products, The Glad Products Company, Thermo Fisher Scientific Inc., Sartorius AG, Merck KGaA, Inteplast Group, Berry Global Group, OriGen Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezing Bags Market Evolving Landscape
Active material science breakthroughs are compressing the performance gap between petroleum-derived films and bio-based alternatives, while regulatory deadlines in Europe force accelerated commercialization timelines.
Mono-material polyethylene structures with enhanced barrier coatings are displacing conventional multi-layer laminates in retail freezing applications. Quick-service restaurants and meal-kit providers are piloting these formats for curbside recycling compatibility. The shift is displacing legacy ethylene-vinyl alcohol coextrusion lines and forcing film converters to retool coating equipment.
REACH chemical compliance expansions are restricting per- and polyfluoroalkyl substance use in grease-resistant bag liners. The restriction forces reformulation of microwave-safe freezing bag SKUs across EU member states. Manufacturers are responding with silicone-based and mineral-filled alternatives, though heat-seal strength trade-offs persist.
Direct sourcing contracts between food processors and film extruders are collapsing traditional distributor tiers in North American institutional channels. Large protein packers now specify polymer grades and seal-strength parameters in master service agreements. The pattern is most pronounced in the US Midwest meatpacking belt and Pacific Northwest seafood processing clusters.
Freezing Bags Market Segmentation
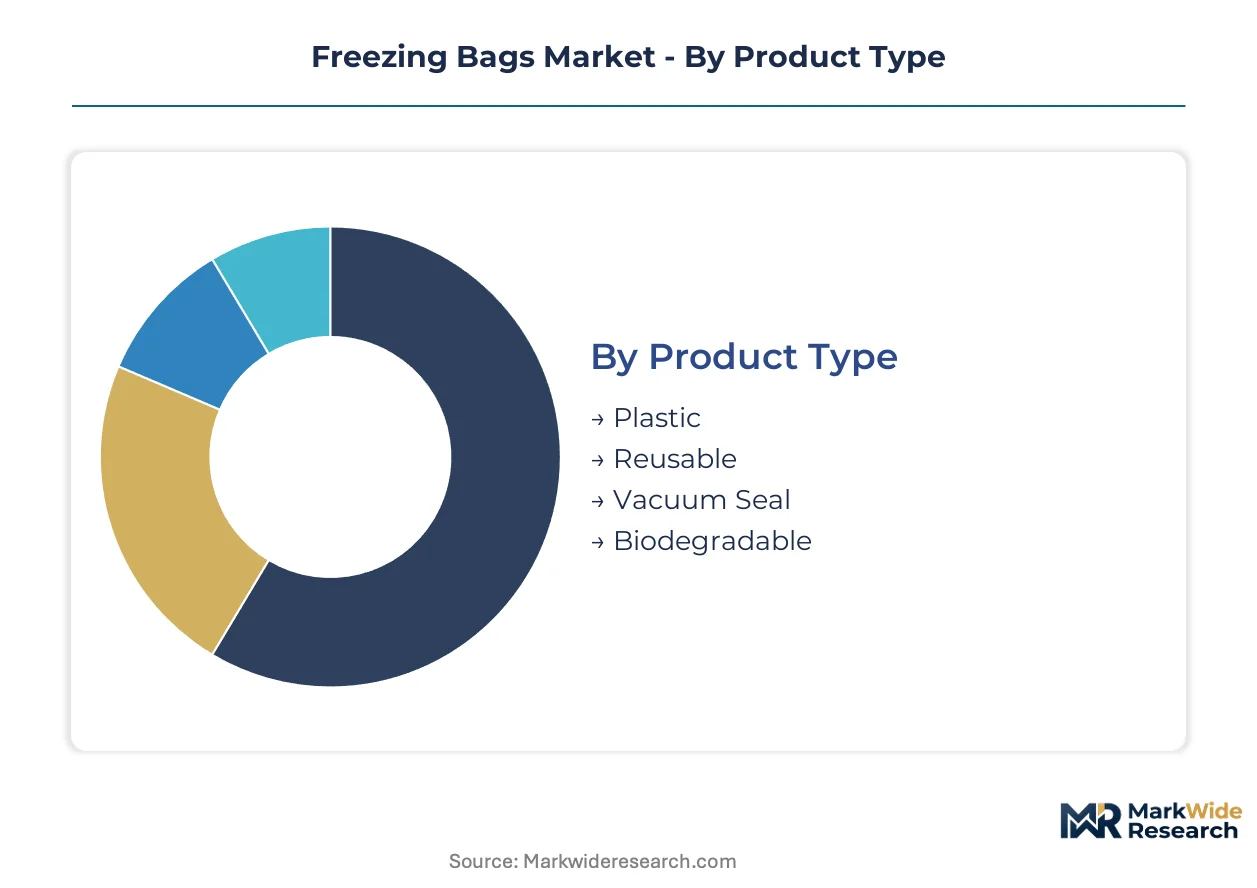
Freezing bag procurement patterns diverge sharply across product formats and user categories. Material certification requirements and cold-chain validation protocols create distinct margin pools that reward specialized positioning over commodity supply.
Product Type:
Margin pools concentrate in validated ultra-low-temperature formats and certified biodegradable alternatives where regulatory compliance creates pricing power.
- Plastic:Multi-layer polyethylene and polypropylene laminates dominate institutional procurement due to cost efficiency at scale. Germany's meat processing corridor sustains bulk orders for vacuum-compatible extrusions with specified seal-strength parameters.
- Biodegradable:PLA and PBAT formulations capture regulatory tailwinds from France's AGEC law and Italy's plastic tax. Compostable resin supply clusters in Thailand and China constrain European converter margins through import dependency.
- Reusable:Silicone-based formats bypass retail margin stacking via direct-to-consumer subscription channels.
- Vacuum Seal:Channel-evacuated pouches extend shelf-life for restaurant and catering segments prioritizing inventory rotation efficiency.
Plastic holds installed capacity. Biodegradable is rotating up the share rankings.
Closure Type:
Application-specific sealing mechanisms determine performance validation tiers and replacement frequency economics.
- Zip Lock:Interlocking polyethylene tracks enable repeated access without seal degradation. Quart-capacity configurations dominate household freezer-space optimization in North American retail channels.
- Heat Seal:Impulse-sealed closures withstand minus eighty degrees Celsius biobanking protocols without embrittlement failure. Sartorius AG and Thermo Fisher Scientific anchor demand in cell and gene therapy logistics.
- Twist Tie:Wire-and-paper fasteners persist in economy retail SKUs with limited reuse cycles.
- Button:Mechanical latch systems appear in reusable silicone formats targeting sustainability-conscious consumers.
Heat Seal commands premium placement in clinical cold-chain. Zip Lock maintains volume leadership across household procurement.
Capacity:
Standardized volume increments align with freezer compartment dimensions and commercial portion-control requirements.
- Quart:Rectangular proportions optimize vertical stacking in residential freezer drawers. Meal-kit providers specify quart dimensions for single-portion protein packaging.
- Gallon:Bulk configurations serve institutional food service and protein packers in the US Midwest meatpacking belt.
- Pint:Compact formats target specialty ingredient preservation and sous-vide preparation segments.
- Half-Gallon:Mid-scale capacity bridges household bulk purchasing and small commercial kitchen requirements.
Gallon holds installed capacity in food manufacturing. Quart is rotating up the share rankings through meal-kit channel expansion.
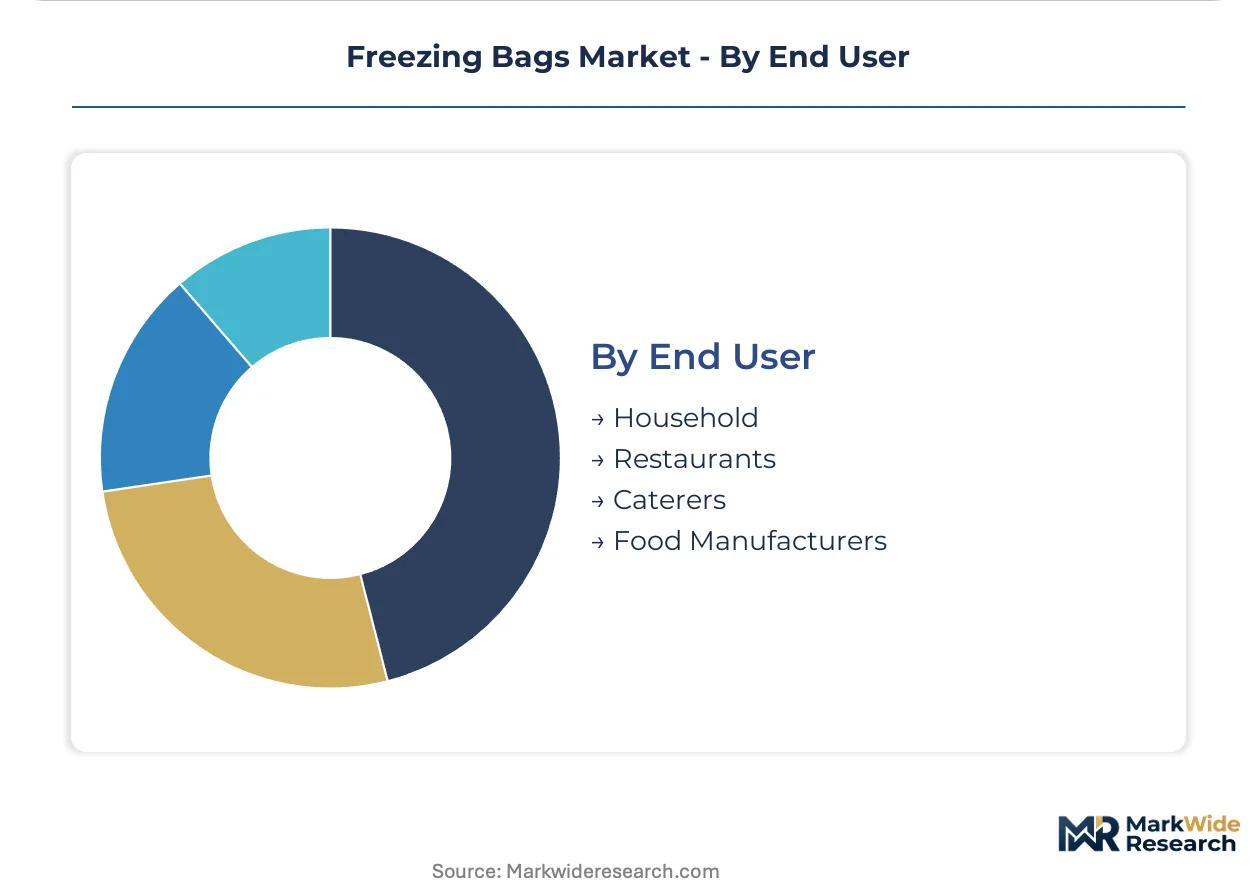
End User:
Procurement sophistication varies from specification-driven master service agreements to price-sensitive retail shelf selection.
- Food Manufacturers:Direct sourcing contracts with film extruders collapse distributor tiers. Large protein packers now specify polymer grades and migration limits in binding agreements.
- Restaurants:Vacuum-seal formats command premium placement for inventory shelf-life extension. Quick-service restaurants pilot mono-material structures for curbside recycling compatibility.
- Household:Zip-lock quart configurations dominate retail procurement driven by freezer-space efficiency and brand recognition.
- Caterers:Event-volume requirements favor bulk gallon formats with reliable seal integrity across transport conditions.
Food Manufacturers hold installed capacity. Restaurants are rotating up the share rankings through sustainability specification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional performance across the freezing bags landscape. Germany and the United States maintain trade surpluses in specialized biopharma-grade formats, while Asian converters dominate commodity polyethylene volumes.
Germany
Industrial meat processing and prepared-meal manufacturing sustain bulk demand for vacuum-seal configurations. The EU Single-Use Plastics Directive accelerates biodegradable material transitions across institutional food service. The Rhine-Ruhr corridor hosts concentrated film extrusion capacity serving pan-European distribution networks.
United States
FDA food-contact substance notifications govern polymer migration limits for commercial freezing applications. Retail channel concentration in zip-lock quart formats persists through brand recognition and freezer-space optimization. The Midwest meatpacking belt anchors direct sourcing contracts between protein packers and film extruders.
China
GB food-contact national standards add compliance layers for exporters targeting domestic manufacturing hubs. Compostable resin production clusters in coastal provinces constrain European converter margins through supply concentration. Yangtze River Delta processing centers export multi-layer laminates to Southeast Asian food manufacturers.
India
FSSAI-mandated food safety protocols drive first-time adoption of certified freezing bags in dairy and seafood processing. BIS polymer standards create technical barriers for imported film products. Gujarat and Maharashtra industrial corridors expand cold-chain infrastructure for agricultural export compliance.
France
The AGEC law creates preferential procurement channels for recyclable-content suppliers across institutional catering. EFSA re-evaluations extend new product qualification timelines for bio-based alternatives. The Île-de-France region concentrates quick-service restaurant headquarters piloting mono-material structures for curbside recycling compatibility.
Freezing Bags Market Competitive Landscape
Listed leaders compete with private specialists across material certification tiers and channel access. The vendor base segments into three layers: multinational conglomerates with captive film extrusion, mid-scale converters serving regional food processors, and niche biopharma validators. Strategic moves concentrate on M&A for polymer compounding capabilities and direct sourcing partnerships with protein packers.
Within the biopharma validation tier, Sartorius AG and Thermo Fisher Scientific occupy positions anchored by ultra-low-temperature protocol certification. Reynolds Consumer Products exemplifies the retail-channel archetype through scale-driven cost positioning in North American household segments. SC Johnson & Son, Inc. sits within the branded consumer goods cluster competing on shelf recognition and distribution density.
| Leading Market Players |
|---|
| SC Johnson & Son, Inc. |
| Reynolds Consumer Products |
| The Glad Products Company |
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Merck KGaA |
| Inteplast Group |
| Berry Global Group |
| OriGen Biomedical |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German meat processors and Rhine-Ruhr film extruders lock in polyethylene resin access and freeze price visibility across eighteen to twenty-four month horizons, insulating volume buyers from ethylene feedstock volatility while compressing margin flexibility for converters serving spot retail channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to FDA-validated biopharma formats and EU-certified biodegradable alternatives where REACH compliance and EFSA re-evaluations create scarcity rent. Standard tiers serve vacuum-seal configurations for institutional food service. Economy tiers cover commodity zip-lock retail SKUs where Reynolds Consumer Products and SC Johnson wage volume-based share contests. Cost compression in standard tiers is intensifying because mono-material polyethylene transitions force coating equipment retooling. Household consumers exhibit highest price sensitivity, while cell and gene therapy logistics buyers accept premium multiples for minus eighty degrees Celsius seal integrity validation.
Supply Chain Analysis
Compostable resin supply concentration in Thailand and China constrains European converter margins through import dependency and single-source vulnerability. PLA fermentation capacity clusters around coastal Chinese provinces. PBAT polymerization plants anchor in Thai petrochemical corridors. Multi-layer film production draws from German extrusion expertise, US Midwest meatpacking belt specifications, and Yangtze River Delta laminate exports. Distribution runs through master service agreements collapsing traditional distributor tiers in North American institutional channels, with direct film extruder relationships now governing procurement in protein packing and seafood processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freezing bags procurement is shifting toward platform-standardized material certification ecosystems where EFSA-validated bio-based formulations achieve interoperability across EU member state institutional catering contracts, creating winner-take-most dynamics for first-movers securing pan-European food-contact substance approvals.
For Market Incumbents: Consolidate polymer compounding capabilities through captive supply of PLA and PBAT resin streams to offset Thai and Chinese import dependency. Secure extended producer responsibility framework pre-qualification under France's AGEC law and Italy's plastic tax before regulatory deadlines harden procurement specifications. Defend against silicone-based reusable formats by accelerating mono-material polyethylene transitions for curbside recycling compatibility in quick-service restaurant channels. For New Entrants and Emerging Players: Anchor in India's FSSAI-mandated cold-chain infrastructure buildout where first-time certified freezing bag adoption in Gujarat and Maharashtra dairy processing creates specification-naive demand. Target direct-to-consumer subscription models for reusable silicone formats bypassing retail margin stacking. Pursue biopharma validation partnerships with Sartorius AG and Thermo Fisher Scientific anchor customers as qualification credential. For Investors and Strategic Acquirers: Film converters with captive bio-resin tolling agreements and EU Single-Use Plastics Directive pre-certification represent the highest-conviction acquisition archetype. Long-term viability hinges on extended producer responsibility framework positioning across five to ten year regulatory enforcement windows. Watch for EFSA re-evaluation acceleration timelines as inflection signal—compressed qualification periods favor pre-validated asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Resin Supply | Thai and Chinese PLA/PBAT concentration creates margin vulnerability for European converters without captive fermentation capacity. |
| Mono-Material Structure Transition | Quick-service restaurant pilots under France's AGEC law reward curbside-recyclable formats with preferential procurement terms. |
| Ultra-Low-Temperature Validation Certification | Cell and gene therapy logistics specifications from Sartorius AG anchor customers command premium placement in clinical cold-chain. |
| Direct Sourcing Contract Expansion | US Midwest meatpacking belt protein packers now specify polymer grades and seal-strength parameters in binding master service agreements. |
| Extended Producer Responsibility Pre-Qualification | Italy's plastic tax and France's AGEC law create regulatory procurement channels favoring recyclable-content suppliers with advance compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with film extrusion plant managers, protein packer procurement leads, quick-service restaurant category buyers, biopharma cold-chain logistics coordinators, and regulatory affairs specialists at EU notified bodies. Secondary validation incorporated FDA food-contact substance notification databases, EFSA scientific opinion archives, EU Single-Use Plastics Directive implementation trackers, BIS polymer standard filings, and customs trade data from German, US, and Chinese export-import flows. Bottom-up volume builds across product type, closure mechanism, capacity tier, and end-user segment were triangulated against top-down macroeconomic anchors.
Across the analysis window, forecasting employed segment-level elasticity modeling calibrated to ethylene feedstock price indices, regulatory compliance cost pass-through assumptions, and cold-chain infrastructure investment flows. Segmentation dimensions spanned material certification grade, closure validation tier, freezer temperature protocol, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, penetration rate trajectories in India's FSSAI-mandated dairy sector, and substitution elasticities between petroleum-derived and bio-based alternatives under EU directive enforcement.
Material uncertainties—ethylene feedstock volatility, EFSA re-evaluation timeline compression, compostable resin supply disruptions, and extended producer responsibility framework adoption rates—sit outside the modeled envelope. Forecasts embed assumptions regarding REACH chemical compliance expansion scope and biopharma cold-chain validation protocol standardization. Revision becomes warranted when EU member state implementation variance of Single-Use Plastics Directive mandates crosses thresholds that alter pan-European procurement interoperability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Block Sack Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Global Household Food Storage Containers Market