
 APAC Flexible Packaging Market | 2026-2036
APAC Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Flexible Packaging Market Outlook
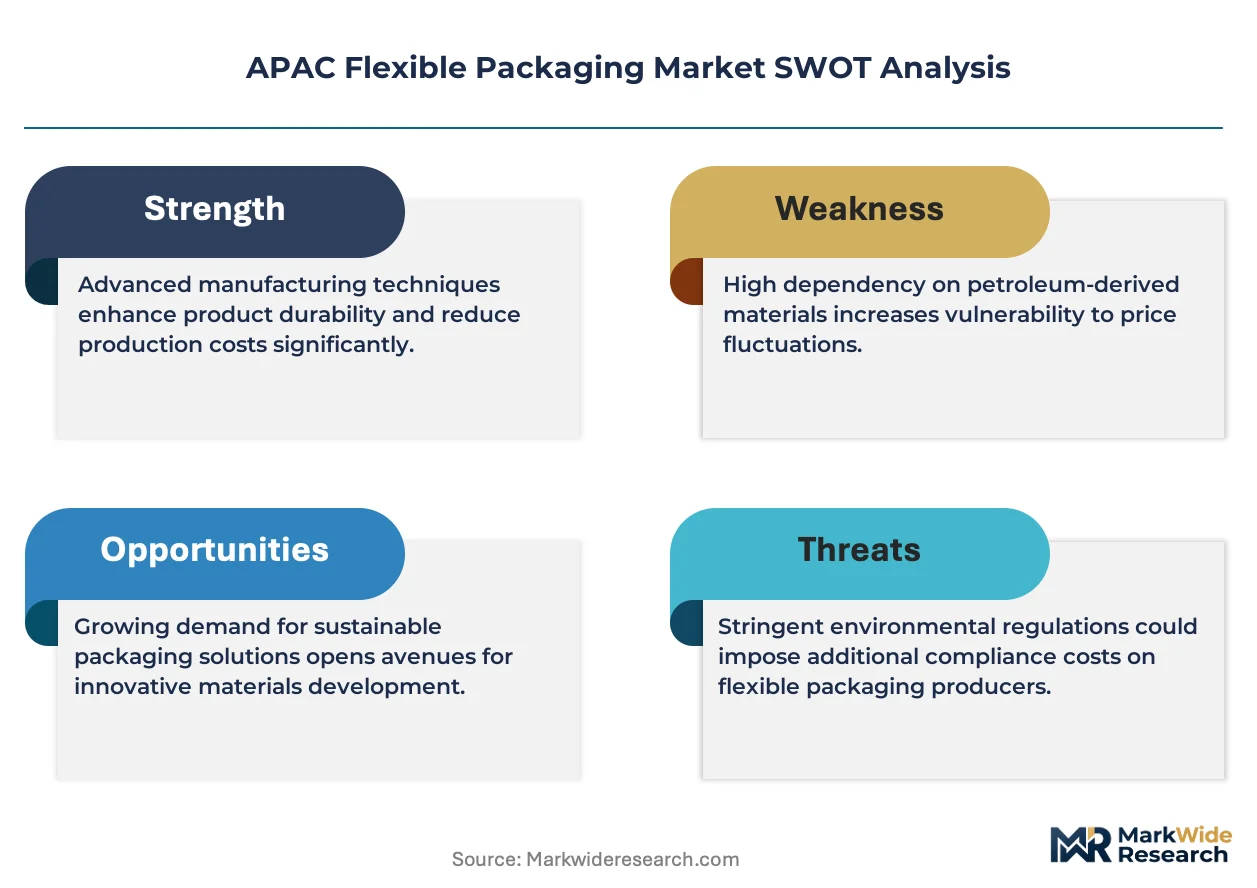
Asset-light leasing models for multilayer coextrusion lines is fragmenting competitive dynamics across the APAC flexible packaging landscape. Amcor Limited leverages its regional film manufacturing network to sustain cost advantages in polyethylene-based formats. Sealed Air Corporation anchors its position through proprietary barrier technologies that extend shelf life for proteins and dairy. Mondi Group competes via integrated kraft paper operations that supply renewable substrate alternatives to plastic-intense applications.
Flexible packaging denotes pliable material structures—typically laminates of polyethylene, polypropylene, paper, or aluminum between 50-250 microns total caliper—engineered to conform to product shape while providing moisture, oxygen, and light barrier protection for perishable and non-perishable goods. Stand-up pouches dominate value pools due to premium shelf presence and material efficiency versus rigid alternatives, while films capture the largest volume base across snack and frozen food applications. Polypropylene formulations are gaining share in retort and hot-fill segments where temperature resistance requirements exceed standard polyethylene capabilities.
China's SAMR enforces GB standards for food-contact material migration limits, while India's BIS mandates mechanical strength and print adhesion benchmarks for domestic distribution. Japan's METI circular economy guidelines are forcing converters to validate recyclability claims or face market access restrictions. Stakeholders must monitor how extended producer responsibility frameworks evolve across these jurisdictions, as compliance investments will separate contract winners from commodity suppliers.
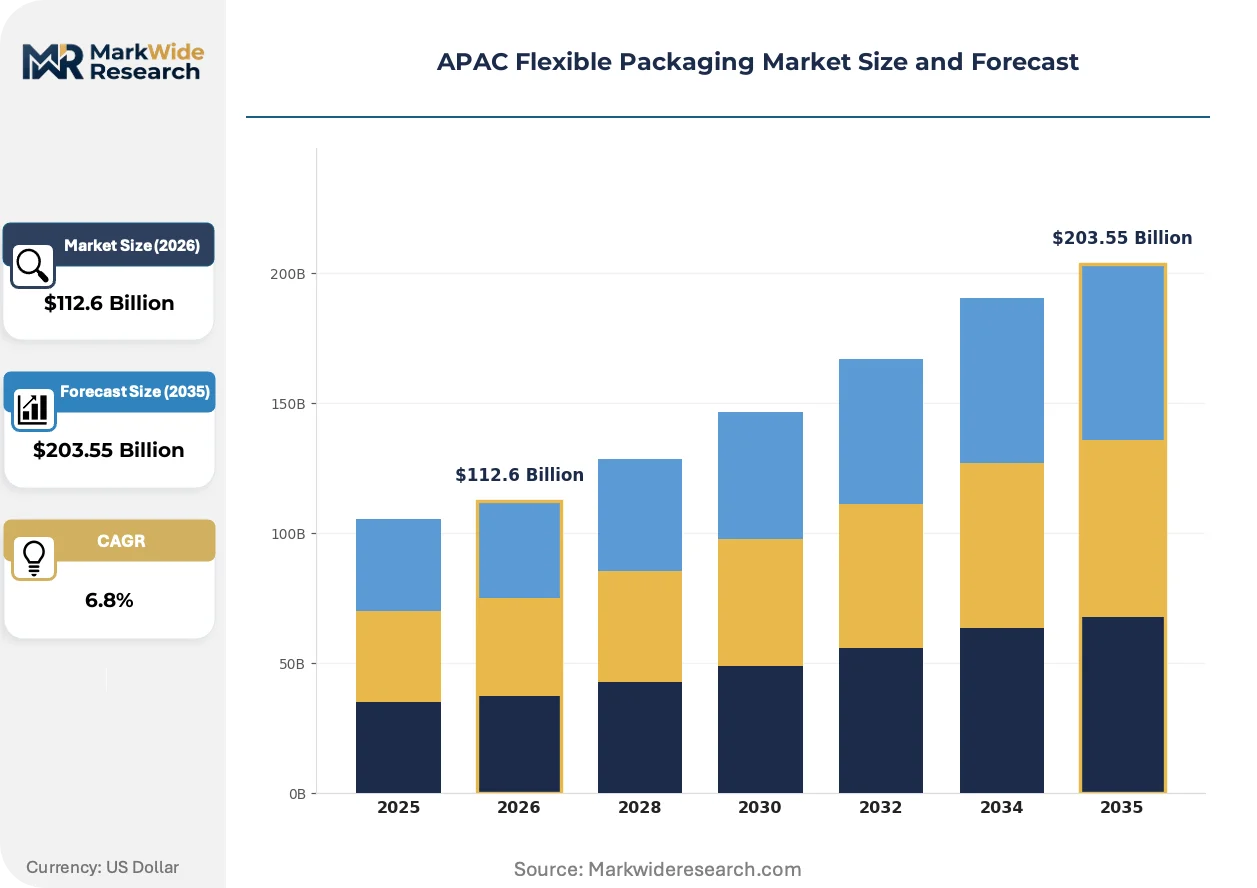
Market Dynamics
Asset-light leasing models for multilayer coextrusion equipment are fragmenting competitive dynamics across the APAC flexible packaging landscape, enabling mid-tier converters to access barrier film capabilities without balance-sheet strain.
Growth Catalysts
- Food-contact migration limits:China's SAMR enforcement of GB standards is forcing domestic converters to upgrade barrier specifications, creating upgrade demand for compliant laminate structures.
- Stand-up pouch conversion:Southeast Asian beverage brands are accelerating rigid-to-flexible transitions, with Thailand and Vietnam processors expanding pouch-filling capacity for ambient juices.
- Retort polypropylene adoption:Hot-fill and shelf-stable protein applications are driving temperature-resistant formulations beyond standard polyethylene capabilities in Japan and South Korea.
Market Restraints
- Aluminum foil supply concentration:Regional dependence on Chinese smelter output creates input cost volatility for high-barrier pharmaceutical and dairy laminates.
- Mechanical strength mandates:India's BIS certification timelines extend 14-18 weeks for domestic distribution, compressing speed-to-market for imported film structures.
- Recyclability validation costs:Japan's METI circular economy guidelines require third-party testing for recyclability claims, adding fixed compliance overhead for export-oriented converters.
Strategic Opportunities
- Western India industrial corridor:Converter clusters between Mumbai and Ahmedabad serve underpenetrated domestic FMCG and export pharmaceutical demand with multimodal logistics access.
- Kraft paper hybrid structures:Renewable substrate alternatives are gaining specification in Australian and New Zealand snack applications where plastic reduction targets tighten.
- Extended producer responsibility frameworks:Emerging EPR legislation across ASEAN jurisdictions creates first-mover advantage for converters with validated mechanical recycling pathways.
Industry Challenges
- Multilayer delamination expertise:Shortage of process engineers capable of optimizing adhesive lamination for seven-layer barrier structures limits yield rates at mid-scale facilities.
- Legacy gravure cylinder inventory:Converters face stranded asset risk as brand owners mandate digital print flexibility for shorter run lengths and versioning requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Flexible Packaging Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Bags, Films, Wraps Material: Polyethylene, Polypropylene, Paper, Aluminum End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zipper, Spout, Heat Seal, Tap |
| Companies Covered | Huhtamaki Oyj, Sealed Air Corporation, Amcor Limited, Berry Global Group, Mondi Group, Husky Injection Molding Systems, Constantia Flexibles, Winpak Limited, Coveris Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Flexible Packaging Market Strategic Shifts
Digital print integration and mono-material redesign are compressing traditional specification cycles, while regulatory pressure on recyclability claims forces validation investments ahead of enforcement deadlines.
High-barrier transparent oxide coatings are migrating from niche pharmaceutical applications to mainstream snack and frozen food segments. Japanese and South Korean processors are adopting plasma-enhanced chemical vapor deposition for oxygen transmission rates below 0.5 cc/m2/day without aluminum foil. This technology is compressing the cost premium versus metallized films to under 15% at commercial scale.
China's GB standards for food-contact material migration limits are tightening testing protocols for aromatic amines and heavy metals. SAMR enforcement actions in 2024 against non-compliant imports have redirected sourcing decisions toward domestic film manufacturers with certified laboratory capabilities. Pharmaceutical and infant nutrition segments are most affected, with brands requiring full supply chain documentation.
Brand owner specification teams are consolidating approved supplier lists around converters with integrated pre-press and digital proofing capabilities. Regional FMCG procurement functions in Indonesia and the Philippines are replacing spot-buying relationships with framework agreements tied to carbon footprint disclosure. This pattern is most visible in personal care and home care verticals where multinational headquarters mandate Scope 3 reporting.
APAC Flexible Packaging Market Segmentation
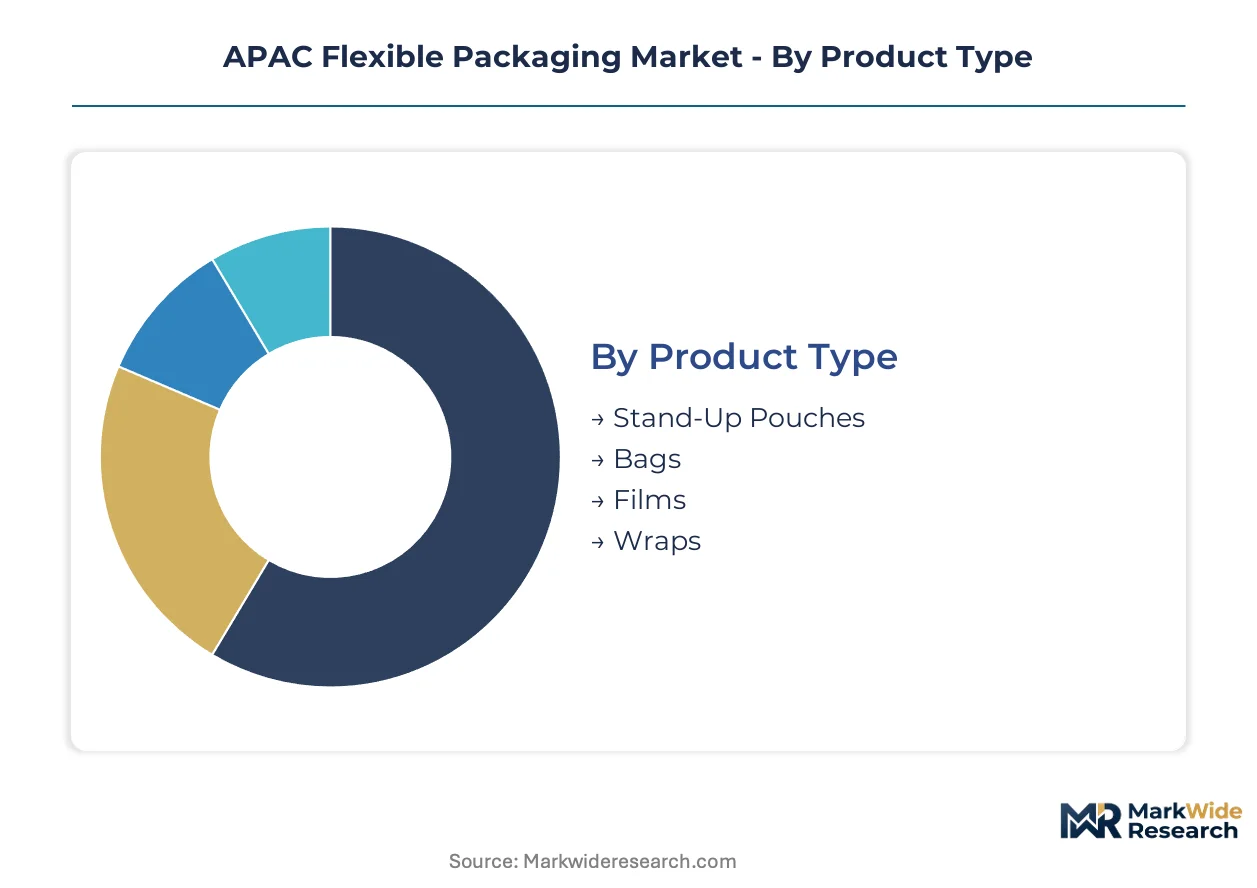
Segmentation in the APAC flexible packaging market reveals how converter capabilities and brand owner specifications diverge across material platforms and closure systems. Understanding these divides exposes where margin pools concentrate and where commoditization pressures intensify.
Product Type:
Application requirements across ambient, chilled, and frozen distribution channels determine format selection and barrier investment levels.
- Stand-Up Pouches:Laminated structures with bottom gusset geometry enable shelf-stable presentation for beverages and sauces. Thai and Vietnamese processors are expanding retort-capable lines for ambient juice applications where premium shelf presence commands price premiums over brick packs.
- Films:Rollstock formats between 50-150 microns serve high-speed form-fill-seal operations for snacks and frozen foods. India's western industrial corridor from Mumbai to Ahmedabad hosts converter clusters supplying both domestic FMCG and export pharmaceutical clients with multilayer coextrusion capabilities.
- Bags:Three-side-seal and pillow configurations dominate commodity snack and bakery applications where cost minimization overrides barrier performance. Standard polyethylene constructions face substitution pressure from mono-material redesign mandates.
- Wraps:Stretch and shrink formats cling to irregular product geometries for fresh produce and pallet unitization. China's domestic film manufacturers with certified laboratory capabilities are capturing sourcing decisions redirected by SAMR enforcement actions.
Films hold installed capacity. Stand-up pouches is rotating up the share rankings.
Material:
Cost tier positioning and recyclability compliance obligations shape procurement patterns across substrate categories.
- Polyethylene:Linear low-density and metallocene grades provide seal integrity and puncture resistance for frozen food and heavy-duty industrial applications. Converters face stranded asset risk on legacy gravure cylinder inventory as brand owners mandate digital print flexibility for shorter run lengths.
- Polypropylene:Oriented and cast formulations deliver temperature resistance exceeding polyethylene capabilities for retort and hot-fill segments. Japanese and South Korean processors are adopting temperature-resistant formulations for shelf-stable protein applications.
- Paper:Kraft and glassine substrates supply renewable alternatives in Australian and New Zealand snack applications where plastic reduction targets tighten. Mondi Group competes via integrated kraft paper operations that supply renewable substrate alternatives to plastic-intense applications.
- Aluminum:Foil laminates provide near-zero oxygen and moisture transmission for pharmaceutical and dairy applications. Regional dependence on Chinese smelter output creates input cost volatility for high-barrier structures.
Polyethylene holds installed capacity. Polypropylene is climbing the fastest among temperature-resistant applications.
End User:
Customer type determines barrier specification stringency, validation documentation requirements, and contract duration structures.
- Food & Beverage:Migration-compliant laminates for infant nutrition and ready-to-eat meals face China's GB standards enforcement. SAMR testing protocols for aromatic amines and heavy metals are redirecting sourcing toward domestic manufacturers with certified laboratory capabilities.
- Pharmaceuticals:Blister foils and sachet stocks demand validated oxygen transmission rates below 0.5 cc/m2/day. Plasma-enhanced chemical vapor deposition technology is compressing the cost premium versus metallized films to under 15% at commercial scale in Japan and South Korea.
- Personal Care:Pouch formats for shampoos and conditioners prioritize shelf presence and dispensing convenience. Indonesian and Philippine procurement functions are replacing spot-buying relationships with framework agreements tied to carbon footprint disclosure.
- Household Products:Chemical-resistant films for detergents and cleaners emphasize seal strength and child-resistance features. Asset-light leasing models for multilayer coextrusion equipment enable mid-tier converters to access barrier capabilities without balance-sheet strain.
Food & Beverage holds installed capacity. Pharmaceuticals is gaining share fastest on barrier premiumization.
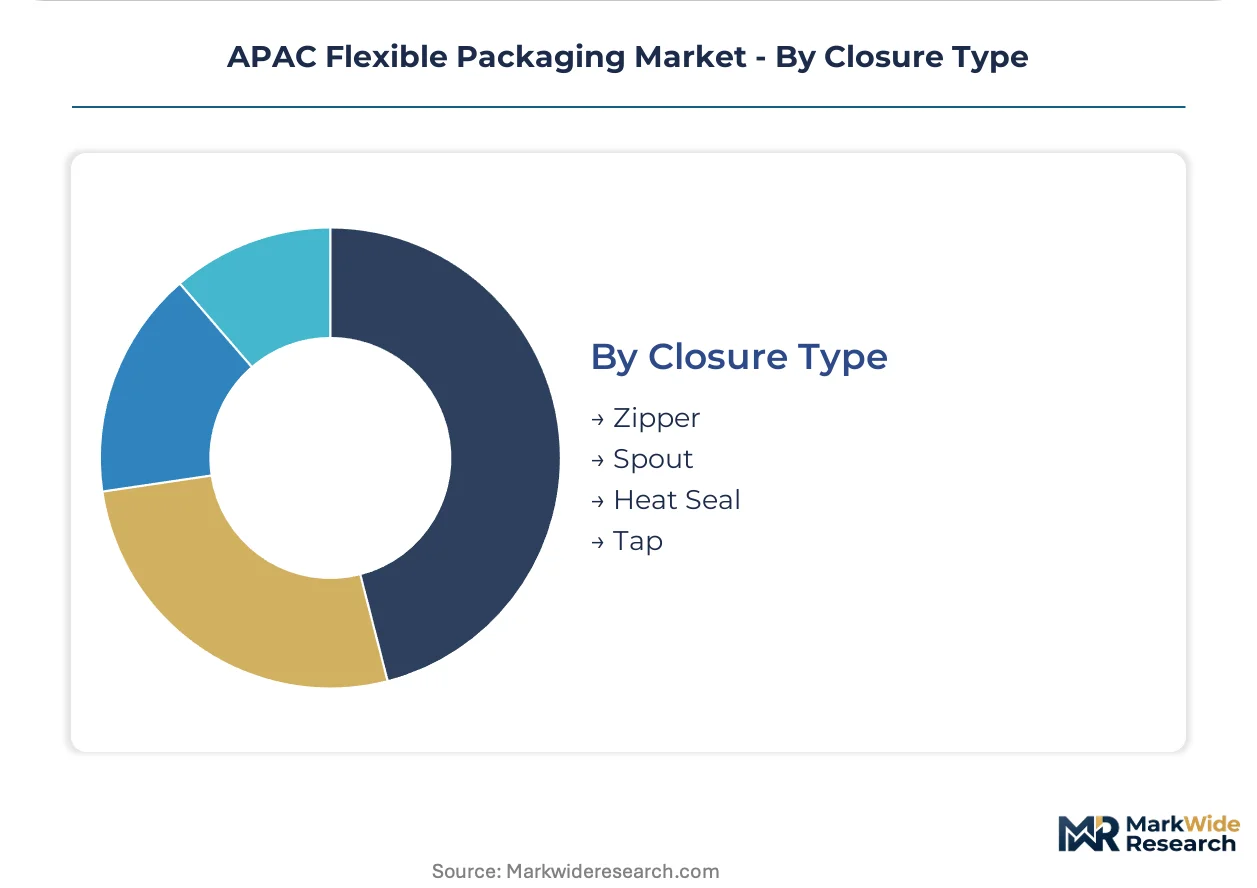
Closure Type:
Volume throughput and reseal functionality requirements segment equipment investment and line speed configurations.
- Heat Seal:Hermetic closure systems dominate ambient shelf-stable applications where oxygen exclusion determines shelf life. India's BIS certification timelines extending 14-18 weeks compress speed-to-market for imported film structures.
- Zipper:Press-to-close profiles enable repeated access for multi-serve snacks and frozen foods. Southeast Asian beverage brands are accelerating rigid-to-flexible transitions with pouch-filling capacity expansion.
- Spout:Fitment integration for pourable liquids commands premium positioning in condiments and beverages. Japan's METI circular economy guidelines require third-party testing for recyclability claims on multi-component structures.
- Tap:Dispensing valves for bag-in-box wine and institutional food service emphasize controlled flow rates. Extended producer responsibility frameworks across ASEAN jurisdictions create first-mover advantage for converters with validated mechanical recycling pathways.
Heat seal holds installed capacity. Spout is rotating up the share rankings on premium beverage adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented converters in Thailand and Vietnam are capturing rigid-to-flexible conversion demand from Southeast Asian beverage brands, while import-dependent markets face compressed margins from aluminum foil cost volatility. China's domestic film manufacturers are redirecting sourcing decisions previously held by foreign suppliers under tighter SAMR enforcement.
China
Domestic manufacturers with certified laboratory capabilities are securing pharmaceutical and infant nutrition contracts after SAMR enforcement actions against non-compliant imports. GB standards for food-contact material migration limits now mandate testing protocols for aromatic amines and heavy metals. Yangtze River Delta converters are expanding plasma-enhanced chemical vapor deposition capacity for transparent oxide coatings.
India
BIS certification timelines extending 14-18 weeks are compressing speed-to-market for imported film structures serving domestic FMCG distribution. The western industrial corridor from Mumbai to Ahmedabad hosts converter clusters supplying both domestic packaged food brands and export pharmaceutical clients. Multilayer coextrusion capabilities concentrate in Gujarat's chemical processing belt.
Japan
METI circular economy guidelines are forcing converters to validate recyclability claims through third-party testing or face market access restrictions. Processors in the Kanto region are adopting temperature-resistant polypropylene formulations for shelf-stable protein applications. High-barrier transparent oxide coatings are migrating from pharmaceutical to mainstream snack segments.
South Korea
Hot-fill and retort applications are driving specification shifts toward polypropylene grades exceeding standard polyethylene temperature resistance. Domestic processors are commercializing oxygen transmission rates below 0.5 cc/m2/day without aluminum foil dependency. Seoul Capital Area converters serve regional dairy and protein brands with validated barrier structures.
Vietnam
Ambient juice brands are accelerating pouch-filling capacity expansion as rigid-to-flexible conversion gains momentum across Southeast Asian beverage markets. Thai and Vietnamese processors are investing in retort-capable stand-up pouch lines. Southern industrial zones around Ho Chi Minh City concentrate foreign-owned converter operations serving export-oriented brand owners.
APAC Flexible Packaging Market Competitive Environment
On the supply side, the industry is fragmenting as asset-light leasing models for multilayer coextrusion equipment enable mid-tier converters to access barrier film capabilities without balance-sheet strain. Three strategic archetypes dominate: integrated film manufacturers with captive resin supply, specialist converters with digital print integration, and paper-based substrate suppliers with renewable positioning. Dominant competitive moves include portfolio diversification into mono-material redesign and geographic expansion through regional converter acquisitions.
Among diversified packaging conglomerates with Asia-Pacific manufacturing footprints, Amcor Limited, Sealed Air Corporation, and Mondi Group exemplify contrasting strategic positions. Amcor represents the integrated film manufacturer archetype leveraging regional polyethylene-based production networks. Sealed Air occupies a position within the barrier technology specialist tier. Mondi anchors the renewable substrate alternative segment through integrated kraft paper operations.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Amcor Limited |
| Berry Global Group |
| Mondi Group |
| Husky Injection Molding Systems |
| Constantia Flexibles |
| Winpak Limited |
| Coveris Holdings |
| Others |
Value Chain & Pricing Dynamics
Chinese smelter concentration for aluminum foil input creates cascading cost volatility that simultaneously widens pricing spreads between commodity and barrier-grade laminates and forces converter networks toward regional coextrusion partnerships. This single-source dependency determines how procurement teams balance spot aluminum exposure against long-term polyethylene resin contracts.
Pricing Analysis
Industrial OEM buyers anchor contract structures around three-tier pricing stratification across premium barrier, standard multilayer, and economy monolayer specifications. Price differentiation rests on GB standard certification tier and volume scale, with pharmaceutical-grade laminates commanding substantial premiums over snack applications. Cost compression in economy polyethylene tiers is intensifying because Indian BIS certification delays compress speed-to-market for imported alternatives. Brand owner procurement functions show highest price sensitivity in commodity snack films, while infant nutrition segment buyers prioritize migration compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta and Pearl River Delta converter clusters, with secondary capacity anchoring in India's western industrial corridor. Raw material flows draw from Chinese petrochemical complexes for polyethylene resin, Thai and Vietnamese film extrusion for regional rollstock, and Australian kraft pulp for renewable substrate alternatives. Single-source vulnerability sits with aluminum foil dependency on Chinese smelter output. Distribution runs through multimodal logistics networks serving FMCG brand owners and pharmaceutical exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible packaging procurement is shifting toward platform-based supplier consolidation, where converters with integrated digital pre-press and carbon disclosure capabilities capture framework agreements previously fragmented across spot-buying relationships.
For Market Incumbents: Insulate barrier technology positions through captive plasma-enhanced chemical vapor deposition capacity additions in Japan and South Korea, while accelerating mono-material redesign R&D to preempt METI recyclability enforcement. Sealed Air Corporation's proprietary oxygen transmission formulations represent the reference architecture for shelf-life extension; replication threats from oxide-coated transparent films demand defensive patent filings. Backward integration into certified laboratory capabilities secures pharmaceutical contract renewals under tightening SAMR migration protocols. For New Entrants and Emerging Players: Build out asset-light leasing models for seven-layer coextrusion equipment targeting mid-tier converters in Vietnam's southern industrial zones, where retort-capable pouch demand outstrips installed capacity. The most penetrable white space sits in Australian and New Zealand kraft paper hybrid structures for snack applications facing plastic reduction mandates. A carbon-footprint-disclosure-first go-to-market angle captures procurement function attention in Indonesian and Philippine personal care verticals. For Investors and Strategic Acquirers: Japan's METI circular economy guidelines reshape the acquisition landscape toward converters with third-party recyclability validation already in place. Long-term viability favors integrated film manufacturers with captive resin supply and digital print infrastructure over commodity gravure-dependent operators. The signal to watch is BIS certification timeline compression in India, which would disadvantage import-reliant converters and advantage domestic Gujarat-based clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Program | Validates recyclability claims under Japan METI guidelines ahead of enforcement deadlines. |
| Plasma-Enhanced CVD Capacity Expansion | Captures pharmaceutical and premium snack share from aluminum-dependent metallized films. |
| Western India Converter Cluster Acquisition | Secures multimodal access to domestic FMCG and export pharmaceutical demand pools. |
| Digital Print Infrastructure Integration | Meets brand owner versioning requirements and short-run flexibility mandates. |
| Kraft Paper Hybrid Structure Development | Positions for Australian and New Zealand plastic reduction specification shifts. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of converter production databases, SAMR enforcement records, and ASEAN trade flow statistics. Interviews with plant managers at multilayer coextrusion facilities, procurement leads at Thai and Vietnamese beverage processors, and regulatory affairs specialists at pharmaceutical packaging divisions informed barrier technology adoption patterns. Secondary validation drew from BIS certification timelines, METI circular economy guideline drafts, and customs records for aluminum foil import dependencies. Bottom-up capacity assessments triangulated against top-down brand owner procurement survey data.
Forecast inputs span material platform migration rates, closure system specification shifts, and end-use vertical penetration curves across the projection horizon. Segmentation dimensions modeled include product type, substrate material, end-use industry, and closure configuration, with regional regulatory cluster as an overlay. CAGRs were derived from installed capacity expansion announcements, brand owner conversion timelines, and resin price elasticity assumptions. Industry-specific inputs incorporated BIS certification queue lengths and SAMR laboratory accreditation thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic film manufacturers with certified laboratory capabilities would shift outcomes toward import substitution. Quarterly review of aluminum foil spot pricing, BIS certification approval velocities, and METI third-party testing queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market