
 Water Soluble Bags Market | 2026-2036
Water Soluble Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Bags Market Outlook
Modular packaging configurations is restructuring procurement decisions across institutional buyers of water soluble bags. Kuraray leverages its PVA polymer expertise to dominate specialty film supply for pharmaceutical and agrochemical applications. Sekisui Chemical anchors Japanese manufacturing scale for hot water soluble formats serving industrial laundries. Mondi Group competes through European production networks that control distribution into regulated healthcare and hospitality channels.
Water soluble bags are engineered containers fabricated from polyvinyl alcohol (PVA) or modified starch polymers that dissolve completely in aqueous environments without toxic residue, manufactured through blown film extrusion with controlled hydrolysis rates for targeted dissolution temperatures. Their primary purpose is eliminating human contact with contaminated contents in healthcare laundry and enabling precise-dose delivery of agrochemicals and detergents. Cold water soluble formats lead unit volume in pharmaceutical and agricultural packaging where energy minimization drives procurement criteria, while biodegradable starch-based materials represent the fastest-expanding segment as European REACH compliance tightens restrictions on persistent synthetic polymers. PVA-based industrial grade products retain the deepest margin pools due to formulation complexity and certification requirements for hazardous material containment.
EPA regulations on hospital waste handling and OSHA bloodborne pathogen standards mandate sealed containment systems that directly expand demand for certified water soluble laundry bags in US healthcare facilities. ECHA REACH restrictions on microplastic release and the EU Green Deal circular economy requirements are redirecting European manufacturing toward compostable starch and PLA alternatives. Stakeholders must monitor evolving polymer certification standards and regional biodegradability test protocols to align R&D investment with shifting compliance thresholds.
Market Dynamics
EU REACH restrictions on microplastic release and the EU Green Deal circular economy mandates are forcing polymer manufacturers to abandon conventional PVA formulations in favor of certified compostable alternatives, restructuring raw material sourcing across the value chain.
Growth Catalysts
- EPA hospital waste regulations:OSHA bloodborne pathogen standards mandate sealed containment systems for contaminated laundry, directly expanding certified water soluble bag procurement across US healthcare networks.
- Agrochemical precision dosing:Farmers adopt unit-dose packaging to reduce chemical exposure and ensure accurate application rates, driving unit volume in agricultural distribution channels.
- Hot water soluble industrial formats:Japanese manufacturing scale for high-temperature dissolution films supports automated laundry systems in hospitality and healthcare facilities seeking infection-control protocols.
Market Restraints
- PVA resin price volatility:Ethylene and vinyl acetate monomer feedstock costs fluctuate with petrochemical markets, compressing margins for film extruders without long-term supply contracts.
- Starch polymer performance limitations:Biodegradable alternatives exhibit inferior tensile strength and moisture barrier properties, restricting adoption in hazardous material containment applications.
- REACH certification timelines:ECHA biodegradability testing protocols require 18-24 month validation cycles, delaying product launches for modified polymer formulations.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization requirements and expanding domestic generic drug manufacturing create demand for cold water soluble unit-dose formats in secondary packaging.
- EU Green Deal procurement mandates:Public healthcare tenders now specify compostable packaging credentials, creating preferential market access for REACH-certified suppliers.
- RFID-PVA film integration:Converging track-and-trace electronics with soluble substrates enables automated inventory management in hospital laundry systems without residue contamination.
Industry Challenges
- Polymer formulation expertise scarcity:Specialized knowledge of controlled hydrolysis rates and dissolution temperature engineering concentrates among veteran R&D chemists, constraining workforce expansion.
- ISO 14855 compostability certification:Multi-phase biodegradation testing under varying temperature and humidity conditions extends product development timelines and capital lockup periods.
- Legacy laundry equipment retrofitting:Existing industrial washing infrastructure requires sensor and dosing system modifications to accommodate soluble bag dissolution monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Bags Market |
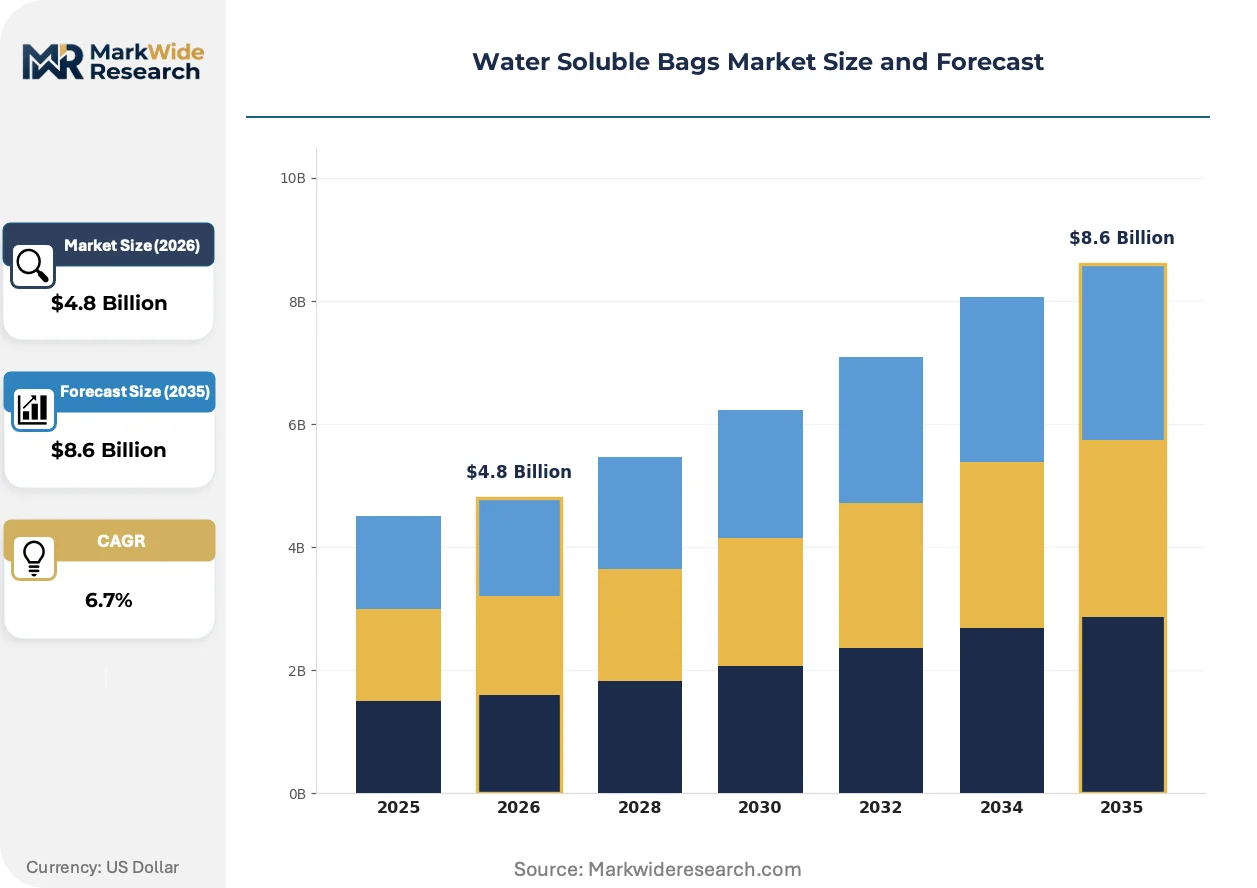
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Water Soluble, Hot Water Soluble, Biodegradable, Industrial Grade Application: Packaging, Agriculture, Laundry, Pharmaceuticals Material: PVA, PLA, Starch-based, Other Polymers End User: Retail, Manufacturing, Hospitality, Healthcare |
| Companies Covered | Kuraray, Sekisui Chemical, Aicello Corporation, Mitsubishi Chemical Corporation, Arrow GreenTech, Cortec Corporation, Mondi Group, Aquapak Polymer, Jiangmen Proudly Water-soluble Plastic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Bags Market Strategic Shifts
Material science advances and regulatory compliance automation are converging to transform how water soluble films are formulated, certified, and deployed across regulated end-use environments.
Blown film extrusion with real-time viscosity monitoring is automating quality control in PVA manufacturing, reducing batch-to-batch dissolution variability. German healthcare laundries and Dutch agrochemical packers are adopting these systems fastest. This automation is compressing defect rates and enabling just-in-time production runs for customized dissolution temperature specifications.
ECHA REACH Annex XVII microplastic restrictions are prohibiting non-biodegradable polymer releases into wastewater streams, forcing reformulation of conventional cold water soluble films. European pharmaceutical packaging converters face the steepest compliance deadlines. Industrial laundries in Germany and France are accelerating procurement of starch-PLA hybrid alternatives ahead of enforcement phases.
Hospital procurement departments now require dissolution certification documentation as a mandatory bid component, displacing price-only evaluation frameworks. Group purchasing organizations aggregate demand across regional healthcare networks, consolidating supplier relationships. This behavioral shift is most pronounced in US metropolitan hospital systems and UK National Health Service trusts.
Water Soluble Bags Market Segmentation
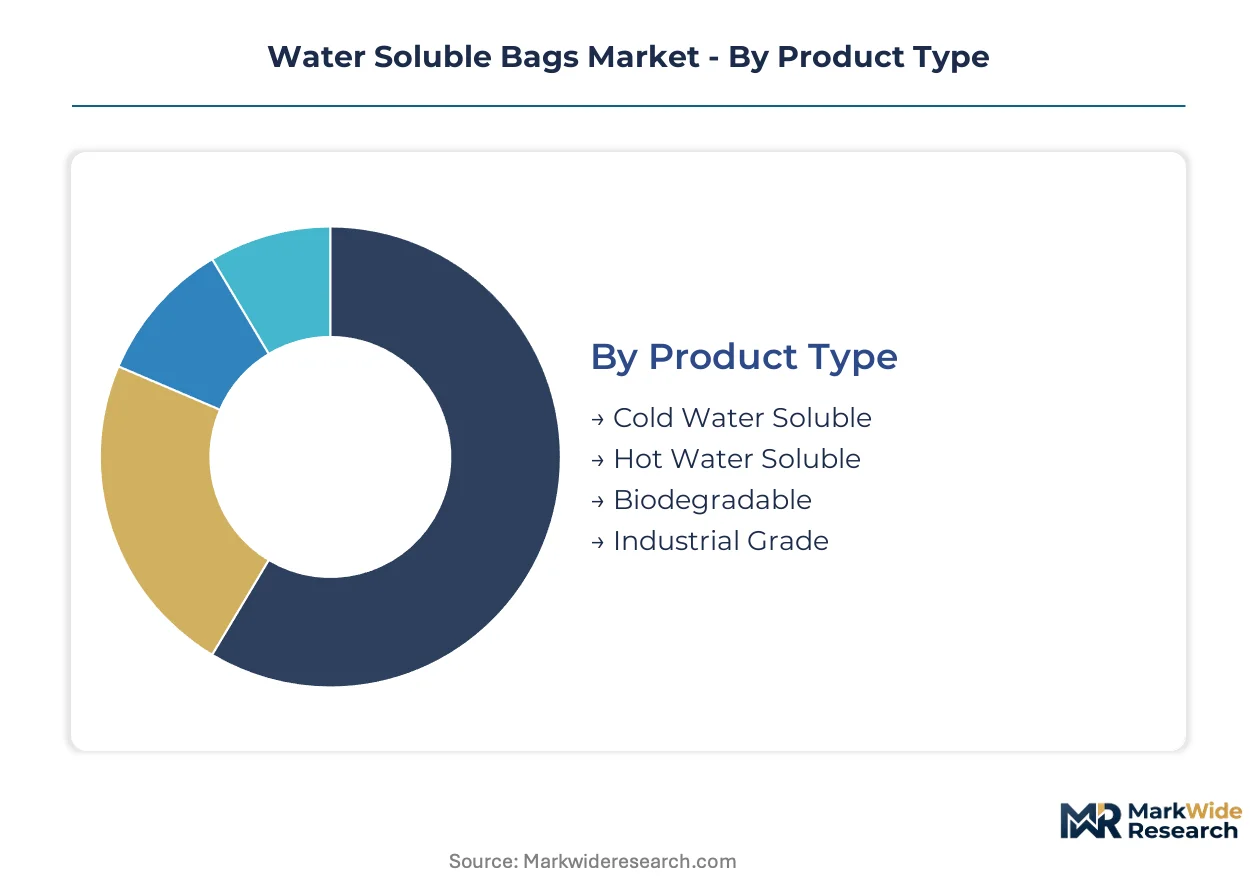
Water soluble bags serve fundamentally different operational roles depending on dissolution temperature, material chemistry, and end-use contamination risk. Procurement patterns diver sharply between standalone consumer formats and embedded industrial systems requiring certified containment protocols.
Product Type:
Cold water formats operate as standalone consumer-facing solutions, while hot water and industrial grades embed into automated processing infrastructure with sensor-integrated dissolution monitoring.
- Cold Water Soluble:Engineered from partially hydrolyzed PVA with dissolution thresholds between 15°C and 25°C, these films prioritize energy minimization in pharmaceutical unit-dose and agrochemical precision packaging. Demand clusters in Indian generic drug manufacturing where CDSCO serialization mandates trackable secondary packaging with minimal processing energy.
- Hot Water Soluble:High-temperature dissolution films formulated for 60°C to 80°C activation anchor automated infection-control laundry systems in Japanese and German healthcare networks. These formats require integration with industrial washing infrastructure and real-time dissolution sensors.
- Biodegradable:Starch-PLA hybrid formulations certified under ISO 14855 compostability protocols serve EU Green Deal procurement mandates in French and Dutch public healthcare tenders.
- Industrial Grade:Reinforced PVA laminates with tensile strength exceeding 30 MPa contain hazardous materials in US chemical manufacturing and EPA-regulated hospital waste streams.
Volume placements concentrate in Cold Water Soluble formats; the faster expansion belongs to Biodegradable alternatives under REACH compliance pressure.
Application:
Cost tiering separates commodity packaging from regulated containment applications where certification premiums justify specialized polymer engineering.
- Packaging:Standard PVA films for detergent pods and consumer goods represent the largest unit volume segment with thin-gauge specifications driving material efficiency.
- Agriculture:Unit-dose agrochemical packaging reduces operator exposure and ensures precise application rates; German and Dutch packers lead adoption of compostable alternatives ahead of ECHA enforcement.
- Laundry:OSHA-mandated sealed containment for contaminated textiles in US metropolitan hospital systems and UK NHS trusts commands the deepest margin pools due to infection-control certification requirements.
- Pharmaceuticals:Cold water soluble secondary packaging with embedded serialization meets CDSCO requirements in Indian generic drug distribution and FDA track-and-trace mandates in US pharmaceutical supply chains.
Margin concentration sits with Laundry applications; Pharmaceuticals exhibits the steepest expansion trajectory as serialization regulations proliferate.
Material:
Supply-side formulation expertise concentrates among veteran polymer chemists capable of engineering controlled hydrolysis rates across dissolution temperature specifications.
- PVA:Polyvinyl alcohol dominates industrial and hot water applications where tensile strength and moisture barrier performance are non-negotiable; Kuraray and Sekisui Chemical anchor global supply through captive resin production.
- PLA:Polylactic acid serves European pharmaceutical and food packaging converters seeking compostable credentials under EU Green Deal circular economy procurement rules.
- Starch-based:Modified starch polymers from agricultural feedstocks represent the fastest-climbing material category as REACH Annex XVII microplastic restrictions force abandonment of persistent synthetic formulations.
- Other Polymers:Experimental polyvinyl acetate and cellulose derivatives occupy niche applications in specialty chemical containment and cosmetic packaging.
Production scale concentrates in PVA; starch-based alternatives gain share fastest under tightening biodegradability mandates.
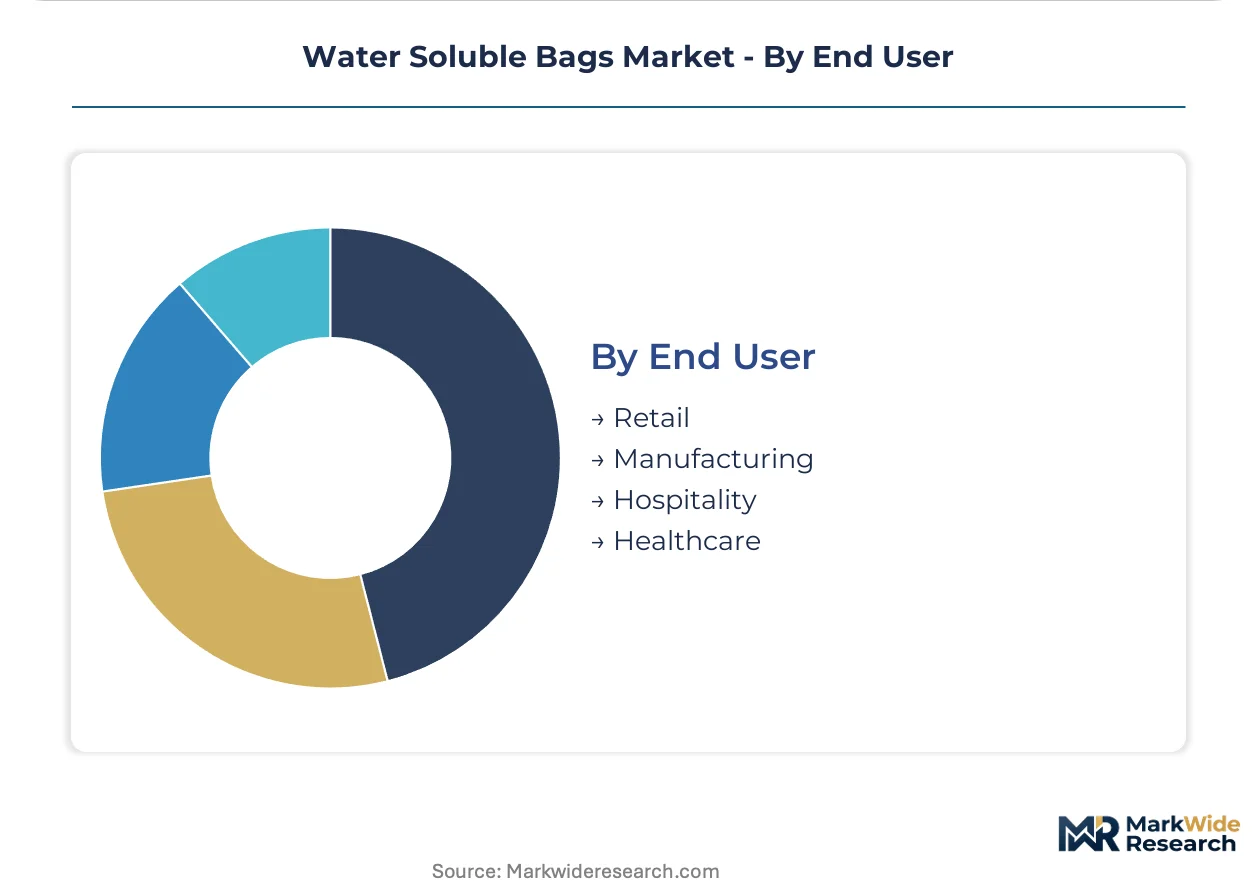
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging group purchasing organization aggregation against fragmented retail demand.
- Retail:Consumer detergent pods and household cleaning products generate high unit volumes with thin-margin economics and price-sensitive private label competition.
- Manufacturing:Industrial chemical and agrochemical producers specify certified containment for hazardous material handling, particularly in German and US chemical processing corridors.
- Hospitality:Hotel and restaurant laundry operations in Japan and Germany adopt hot water soluble formats for automated infection-control protocols in high-throughput washing systems.
- Healthcare:Hospital procurement departments now mandate dissolution certification documentation as a mandatory bid component, consolidating supplier relationships through group purchasing organizations across US metropolitan systems and UK NHS trusts.
Procurement volume concentrates in Retail; Healthcare demonstrates the most rapid behavioral shift toward certified specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian pharmaceutical packaging investment. German industrial clusters anchor European biopolymer R&D. Japanese manufacturing corridors sustain hot water soluble film production scale.
United States
OSHA bloodborne pathogen standards and EPA hospital waste regulations mandate sealed containment systems for contaminated laundry. Group purchasing organizations across metropolitan hospital networks consolidate supplier relationships through mandatory dissolution certification requirements. Texas and California healthcare systems drive procurement volume for certified infection-control formats.
Germany
ECHA REACH Annex XVII microplastic restrictions and EU Green Deal circular economy mandates force polymer reformulation toward compostable alternatives. The country's national chemical regulator enforces 18-24 month biodegradability validation cycles. Industrial laundries in North Rhine-Westphalia and Bavaria accelerate starch-PLA hybrid adoption ahead of enforcement phases.
Japan
METI industrial standards support automated infection-control protocols in hospitality and healthcare facilities. The Ministry of Health, Labour and Welfare maintains stringent dissolution performance benchmarks for medical applications. Manufacturing scale concentrates in Kanto and Kansai corridors for high-temperature dissolution films serving automated laundry infrastructure.
India
CDSCO serialization requirements and expanding domestic generic drug manufacturing create demand for cold water soluble unit-dose formats. The Department of Pharmaceuticals PLI scheme incentivizes specialized packaging investment. Pharmaceutical packaging converters in Gujarat and Maharashtra scale secondary packaging capacity for export-oriented generic drug distribution.
Netherlands
EU Green Deal procurement mandates specify compostable packaging credentials in public healthcare tenders. The national environmental agency enforces wastewater discharge standards affecting polymer selection. Agrochemical packers in Rotterdam and Amsterdam port clusters lead adoption of certified biodegradable alternatives ahead of ECHA enforcement timelines.
Water Soluble Bags Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation complexity tiers. The vendor base organizes around captive resin production, regional distribution control, and certification depth. Three strategic archetypes dominate: integrated polymer producers with backward control over PVA supply, regional packaging converters leveraging proximity to regulated end-users, and specialty film engineers serving pharmaceutical serialization requirements. Competitive moves concentrate on capacity expansion in REACH-compliant geographies and technology licensing for controlled hydrolysis rate engineering.
Within the integrated polymer tier, Kuraray and Sekisui Chemical represent archetypes of captive PVA resin production anchoring specialty film supply. Mondi Group occupies a position exemplifying European distribution network control into regulated healthcare channels. Among Asia-Pacific fabricators, Aicello Corporation and Mitsubishi Chemical Corporation sit within the specialty film engineering segment serving pharmaceutical and agrochemical precision packaging requirements.
| Leading Market Players |
|---|
| Kuraray |
| Sekisui Chemical |
| Aicello Corporation |
| Mitsubishi Chemical Corporation |
| Arrow GreenTech |
| Cortec Corporation |
| Mondi Group |
| Aquapak Polymer |
| Jiangmen Proudly Water-soluble Plastic |
| Others |
Value Chain & Pricing Dynamics
Vinyl acetate monomer spot indices cascade through PVA resin contracts into three-tier pricing structure across premium, standard, and economy levels for water soluble film extruders. ECHA REACH certification premiums compress margins for uncertified converters while starch-PLA hybrid feedstock costs reset procurement baselines across European healthcare tenders.
Pricing Analysis
Margin tightening in standard-grade PVA films reflects ethylene feedstock volatility and compressed contract renewal cycles. Pricing stratifies across premium, standard, and economy tiers with ISO 14855 compostability certification and dissolution temperature precision as primary differentiation drivers. Cost-down pressure on economy-tier commodity formats accelerates because Indian pharmaceutical packers prioritize thin-gauge material efficiency over performance specifications. Retail detergent pod buyers exhibit highest price sensitivity; OSHA-mandated hospital laundry procurement demonstrates lowest sensitivity due to infection-control liability exposure.
Supply Chain Analysis
Dual-sourcing requirements from German healthcare laundries and US metropolitan hospital systems mandate multi-supplier qualification across Japanese, German, and Indian film extruders. PVA resin supply draws from Kuraray and Sekisui Chemical captive production in Japan, modified starch feedstock sources from agricultural processors in the Netherlands and Germany, and PLA polymer hinges on NatureWorks and TotalEnergies Corbion capacity in Thailand and the US. Single-source vulnerability concentrates in high-temperature dissolution film grades where controlled hydrolysis expertise remains scarce. Distribution runs through regional packaging converters with ECHA REACH pre-certification and direct hospital GPO relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH Annex XVII microplastic restrictions erect a cost-of-compliance barrier that entrenches certified incumbents while forcing reformulation investments from challengers. This regulatory moat deepens with each 18-24 month biodegradability validation cycle.
For Market Incumbents: Deepen backward integration into PVA resin production to offset vinyl acetate monomer price volatility and secure margin pools in industrial-grade hazardous containment applications. Anchor capacity expansion in Gujarat and Maharashtra pharmaceutical corridors to capture CDSCO serialization-driven demand. Defend against starch-PLA hybrid substitution by accelerating ISO 14855 certification breadth ahead of EU Green Deal enforcement phases. For New Entrants and Emerging Players: Group purchasing organizations in US metropolitan hospital systems represent the most penetrable channel archetype for REACH-certified specialty film suppliers. Target Indian generic drug packaging converters with cold water soluble unit-dose formats priced below Kuraray and Sekisui Chemical import premiums. Pursue technology licensing partnerships with veteran polymer chemists possessing controlled hydrolysis rate engineering expertise rather than greenfield R&D investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor European packaging converters with dormant REACH certification assets in North Rhine-Westphalia and Bavaria industrial laundry corridors. Long-term viability centers on compostable polymer formulation capabilities aligned with tightening ECHA enforcement timelines. Monitor ECHA biodegradability test protocol revisions as the critical inflection signal for capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Acceleration | Pre-validated compostable formulations secure preferential access to EU Green Deal healthcare tenders in France and the Netherlands. |
| Backward Integration into PVA Resin | Captive vinyl acetate monomer supply insulates margin pools from petrochemical feedstock volatility affecting film extruders. |
| RFID-PVA Film Integration | Embedded track-and-trace electronics enable automated dissolution monitoring in Japanese and German hospital laundry systems. |
| Indian Pharmaceutical Packaging Expansion | CDSCO serialization mandates drive cold water soluble secondary packaging demand in Gujarat and Maharashtra manufacturing clusters. |
| Starch-PLA Hybrid Scale-Up | Compostable alternatives capture share from conventional PVA as ECHA Annex XVII microplastic restrictions tighten enforcement deadlines. |
Study Parameters
Trade flow databases, ECHA REACH registration dossiers, and SEC filings from disclosed polymer producers formed the secondary backbone for supply-side calibration. Primary interviews with film extrusion plant managers, hospital procurement directors at US metropolitan GPOs, pharmaceutical packaging converters in Gujarat, and ECHA compliance consultants validated dissolution temperature specifications and certification timeline assumptions. Bottom-up volume modeling across cold water, hot water, biodegradable, and industrial-grade product categories triangulated against top-down healthcare and agrochemical packaging spend estimates.
Bottom-up unit economics modeled blown film extrusion capacity, resin feedstock costs, and certification overhead across the projection horizon. Segmentation dimensions included dissolution temperature tier, material chemistry, application vertical, and end-user procurement sophistication. CAGRs derived from regression analysis of historical vinyl acetate monomer price elasticity and regulatory-driven substitution patterns in European healthcare procurement. Forecast inputs incorporated ECHA enforcement phase schedules and CDSCO serialization rollout timelines for pharmaceutical secondary packaging.
Caveats apply where ECHA biodegradability protocol revisions or vinyl acetate monomer supply disruptions could materially shift the outlook. Deviation in REACH certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Trash Can Liners Market
Bags and Containers
Portion Bags Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Padding Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Hermetic Storage Bags Market