
 Global Household Food Storage Containers Market | 2026-2036
Global Household Food Storage Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Household Food Storage Containers Market Outlook
Specialized polymer engineering talent is unwinding supply bottlenecks for high-performance container seals across Asian manufacturing hubs. Tupperware Brands Corporation leverages decades of direct-selling infrastructure to sustain brand loyalty in Latin American markets. Sealed Air Corporation anchors its position through advanced barrier film technology that extends shelf life for refrigerated goods. Newell Brands Inc. competes across multiple price tiers through diversified houseware portfolios spanning Rubbermaid and FoodSaver lines.
Household food storage containers are engineered receptacles—typically fabricated from polypropylene, borosilicate glass, or stainless steel—designed to preserve food quality through controlled atmosphere, moisture regulation, and temperature resistance from freezer to microwave. Their primary commercial purpose centers on reducing household food waste while enabling organized inventory management in domestic kitchens. Plastic containers still dominate unit volume due to lightweight durability and cost efficiency, though glass containers command premium positioning as health-conscious consumers reject chemical leaching concerns. Airtight feature sets are capturing the fastest margin expansion as vacuum-seal mechanisms migrate from commercial foodservice into mainstream household adoption.
The US FDA governs direct food contact materials through 21 CFR standards that dictate permissible polymer additives and migration limits, while the EU REACH framework restricts phthalates and bisphenol derivatives in consumer-grade plastics. China's GB standards and SAMR enforcement create parallel compliance obligations for exporters targeting domestic retail channels. Stakeholders must monitor evolving extended producer responsibility schemes in France and Germany, where packaging take-back obligations are poised to reshape cost structures and material selection across the entire supplier base.
Market Dynamics
The migration from single-use disposables toward reusable food storage systems is compressing demand cycles and forcing material science investments across container manufacturers. This structural pivot toward circularity is redrawing competitive boundaries between polymer specialists and glass/ceramic incumbents.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on disposable foodware across member states is channeling household expenditure toward durable polypropylene and borosilicate glass alternatives with extended lifecycle ratings.
- Meal kit logistics:Portion-controlled subscription services require standardized container footprints, creating pull-through demand for modular, stackable designs with uniform sealing mechanisms.
- German municipal composting mandates:Strict organic waste separation rules are accelerating replacement of non-compostable storage with certified biodegradable and reusable options.
Market Restraints
- Specialized silicone supply concentration:Platinum-cured silicone for high-performance seals concentrates among three Asian compounders, exposing container makers to input volatility and allocation rationing.
- REACH compliance burden:The EU's chemical registration framework imposes testing costs that disproportionately burden small-format producers seeking pan-European distribution.
- Stainless steel substitution:Unlined metal containers are capturing freezer-to-oven use cases where thermal shock resistance matters, eroding glass's premium positioning in specific temperature applications.
Strategic Opportunities
- India's FSSAI packaging standards:New food-contact material regulations are creating first-mover advantage for compliant exporters as organized retail expands in tier-2 cities.
- Vacuum-seal convergence:Integration of battery-powered evacuation pumps with container lids is opening premium positioning previously reserved for commercial foodservice equipment.
- Direct-to-consumer refurbishment:Mail-in seal replacement and lid-matching services are emerging as loyalty mechanisms that bypass traditional retail markups.
Industry Challenges
- Polymer additive chemist scarcity:Formulation expertise for high-clarity, BPA-free copolymers is concentrating among aging technical workforces in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous FDA 21 CFR, EU REACH, and China GB standard compliance extends product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Household Food Storage Containers Market |
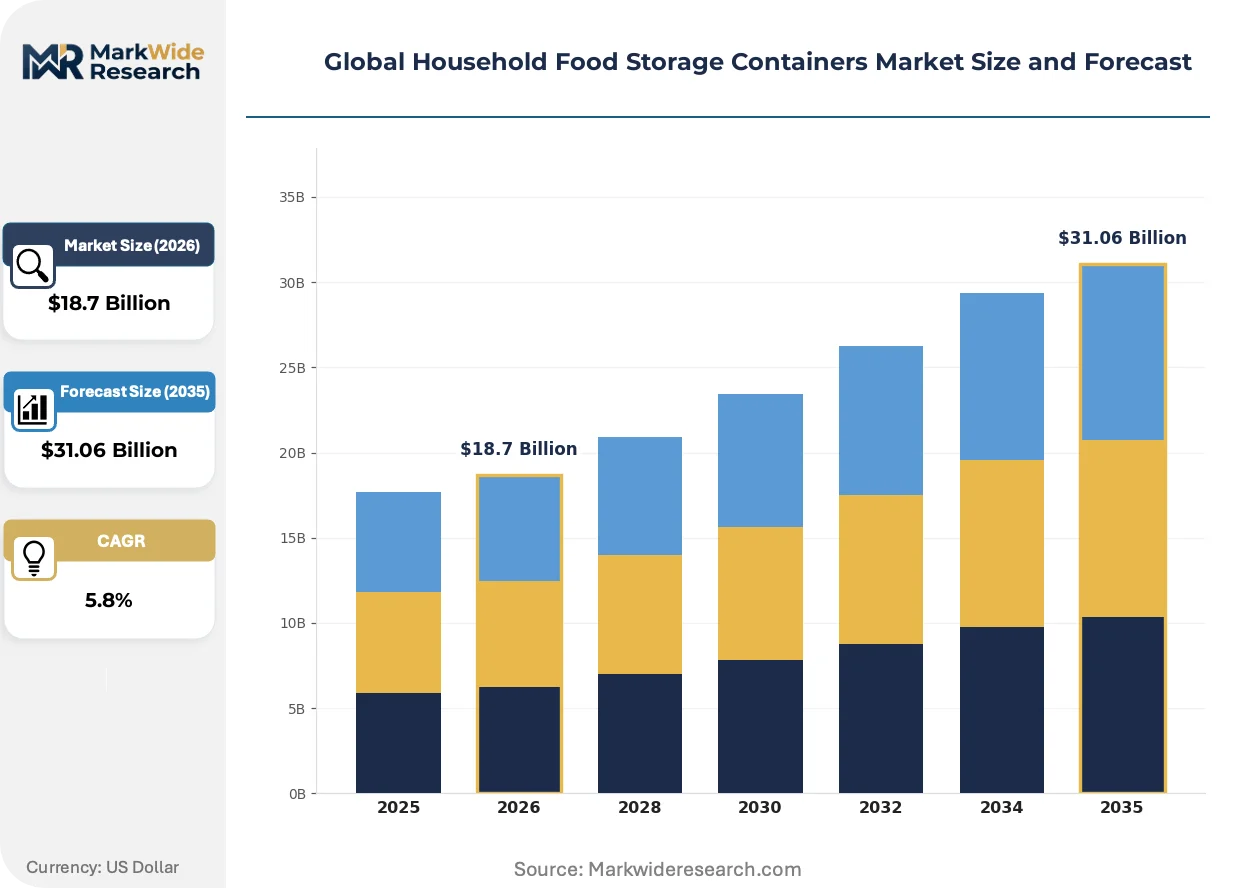
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Glass Containers, Metal Containers, Silicone Bags Size: Small, Medium, Large, Extra Large Feature: Stackable, Airtight, Microwave Safe, Freezer Safe End User: Households, Food Service, Retail Stores, Meal Preppers |
| Companies Covered | Lock & Lock Co., Ltd., SC Johnson & Son, Inc., Tupperware Brands Corporation, Corelle Brands LLC, Huhtamaki Oyj, Sealed Air Corporation, Amcor PLC, Helen of Troy Limited, Newell Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Household Food Storage Containers Market Strategic Shifts
Active intelligence integration and material hybridization are redefining what consumers expect from domestic food preservation. These developments are compressing the gap between commercial foodservice capabilities and household-grade equipment.
Smart container technology is bifurcating the market into connected and passive segments. Bluetooth-enabled lids with spoilage sensors are penetrating premium urban households in South Korea and Japan. This capability split is forcing manufacturers to maintain parallel R&D streams for sensor-integrated and purely mechanical product lines.
REACH Annex XVII restrictions on phthalates and bisphenol derivatives are accelerating bio-based polymer validation. European compounders are scaling polylactic acid and polyhydroxyalkanoate blends for freezer-grade applications. German retailers are demanding third-party migration testing documentation before listing new polymer formulations.
Subscription bundling is restructuring how households acquire container systems. Meal prep services in the United States and United Kingdom are incorporating branded storage into weekly delivery cycles. This channel shift is displacing traditional houseware retail and concentrating procurement decisions among logistics coordinators rather than individual consumers.
Global Household Food Storage Containers Market Segmentation
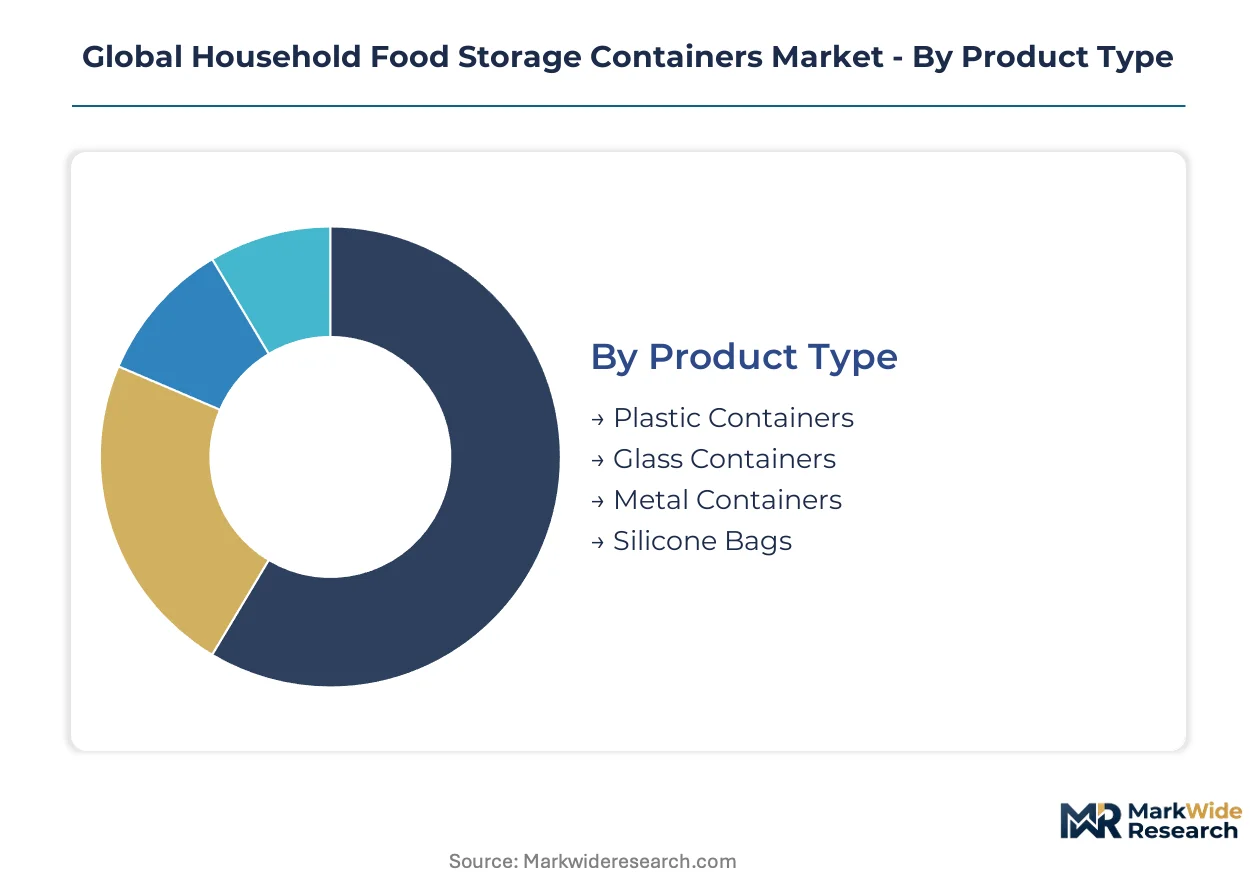
Container manufacturers align R&D budgets and distribution strategies around how households actually organize kitchen inventory. Segment-level margin capture depends on matching material performance claims to specific preservation use cases rather than pursuing undifferentiated volume.
Product Type:
Margin pools concentrate in premium-positioned materials where health-conscious consumers accept price premiums for chemical-free contact surfaces.
- Plastic Containers:Polypropylene and Tritan copolymers deliver lightweight impact resistance across freezer-to-microwave temperature cycles. Unit volume concentrates in North American mass retail channels where cost efficiency dominates procurement criteria for bulk-set purchases.
- Glass Containers:Borosilicate formulations resist thermal shock from oven to freezer transitions without leaching concerns. German and French households are driving replacement demand as EU REACH restrictions on bisphenol derivatives accelerate migration from polymer alternatives.
- Metal Containers:Unlined stainless steel captures specialized use cases requiring durability without breakage risk.
- Silicone Bags:Platinum-cured formulations offer collapsible storage with oven-safe temperature tolerance.
The dominant share belongs to Plastic Containers, while Glass Containers is closing the gap fastest.
Size:
Inventory turnover velocity varies dramatically by capacity tier, with mid-size formats generating the most frequent replacement purchases.
- Small:Under-500ml capacities target sauce portioning and single-serve leftovers. Meal prep subscription services in the United States and United Kingdom are standardizing on these footprints for weekly delivery logistics.
- Medium:500ml-1.5L range captures the bulk of everyday leftover storage and lunch-portion applications. Japanese retailers report the strongest per-household penetration here as compact kitchen dimensions favor stackable efficiency.
- Large:1.5L-3L capacities address family-sized meal preservation and bulk ingredient storage.
- Extra Large:Above-3L formats serve batch cooking and extended-family portions.
Medium sizes command the highest purchase frequency, while Small formats are expanding most quickly through subscription bundling channels.
Feature:
Functional differentiation determines price positioning, with sealing technology commanding the steepest premiums over basic containment.
- Airtight:Silicone-gasketed lids with vacuum-compatible valves extend refrigerated shelf life by limiting oxidative degradation. South Korean and Japanese households are driving adoption of Bluetooth-enabled spoilage sensors integrated into premium lid designs.
- Stackable:Modular footprint standardization enables vertical cabinet density. German municipal composting mandates are accelerating demand for uniform container systems that integrate with organized organic waste separation workflows.
- Microwave Safe:Thermal stability without warping or chemical release defines baseline expectations for reheating applications.
- Freezer Safe:Brittleness resistance at sub-zero temperatures varies significantly by material formulation.
Airtight functionality carries the highest margin premium, while Stackable designs are gaining share fastest through space-constrained urban kitchen renovations.
End User:
Procurement authority is fragmenting as logistics coordinators at meal services displace individual household purchasing decisions.
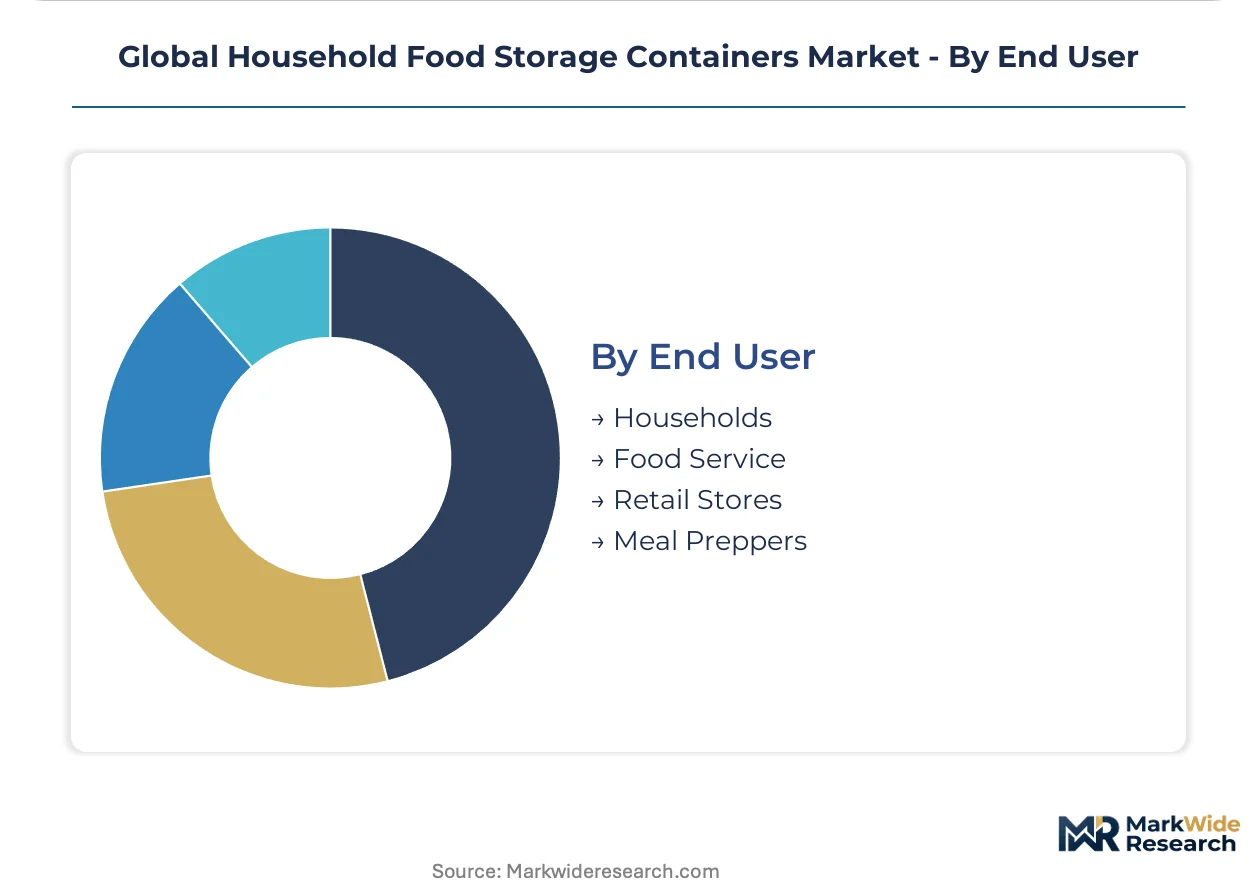
- Households:Individual consumers select containers through retail, e-commerce, and direct-to-consumer channels. Replacement cycles are shortening as EU extended producer responsibility schemes in France and Germany incentivize durable over disposable options.
- Meal Preppers:Dedicated portion-control practitioners demand standardized systems with uniform sealing and modular stacking. This segment shows the steepest expansion trajectory as subscription services incorporate branded storage into weekly delivery cycles.
- Food Service:Commercial kitchens and catering operations require NSF-certified durability for high-cycle washing.
- Retail Stores:Private-label housewares buyers source containers for store-brand merchandising.
Households retain the largest volume base, while Meal Preppers is climbing the fastest through subscription-channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR standards governing direct food contact materials anchor the United States as the regulatory reference point for polymer formulation compliance across export-oriented manufacturing. National frameworks in Germany, Japan, China, and India create parallel certification obligations that extend product development timelines.
United States
Meal kit subscription services in California and New York Metro are standardizing container footprints for weekly logistics, pulling demand for modular polypropylene systems. FDA migration limit testing for BPA-free copolymers adds 6-8 months to new product introductions. Texas-based polymer compounders are expanding Tritan copolymer capacity to serve freezer-to-microwave applications.
Germany
Municipal composting mandates in Bavaria and North Rhine-Westphalia are accelerating replacement of non-compostable storage with certified reusable glass and silicone alternatives. ECHA REACH Annex XVII restrictions on phthalates channel procurement toward borosilicate containers. Berlin-Brandenburg retailers now require third-party migration documentation before listing new polymer formulations.
China
GB standards and SAMR enforcement create dual compliance tracks for exporters targeting domestic versus export channels. Yangtze River Delta manufacturers are scaling platinum-cured silicone seal production for premium airtight lids. Pearl River Delta injection molders are consolidating polypropylene capacity to serve cross-border e-commerce fulfillment.
Japan
Compact kitchen dimensions in Tokyo and Osaka are driving stackable container design specifications with vertical density optimization. METI energy efficiency guidelines are shaping microwave-safe thermal stability requirements. Nagoya-based houseware distributors are integrating Bluetooth-enabled spoilage sensors into premium lid offerings.
India
FSSAI packaging standards for food-contact materials are creating compliance barriers for unorganized sector imports as modern retail expands in Maharashtra and Karnataka. Organized retailers in Delhi-NCR are demanding batch-level certification documentation. Gujarat-based polymer processors are investing in high-clarity copolymer lines to capture tier-2 city demand.
Global Household Food Storage Containers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with direct-selling infrastructure and barrier film technology representing distinct competitive moats. The market structure favors players with captive polymer formulation expertise or established logistics relationships with meal service providers. Three archetypes dominate: heritage direct-selling networks, diversified houseware conglomerates, and advanced materials specialists. Consolidation is proceeding through targeted acquisition of silicone seal compounders and strategic partnerships with subscription meal services.
Within the heritage network tier, Tupperware Brands Corporation exemplifies direct-selling infrastructure deployed across Latin American markets. Newell Brands Inc. and Sealed Air Corporation occupy positions spanning diversified houseware portfolios and advanced barrier technology respectively. These three anchors represent divergent strategic bets on channel control, portfolio breadth, and materials science specialization.
| Leading Market Players |
|---|
| Lock & Lock Co., Ltd. |
| SC Johnson & Son, Inc. |
| Tupperware Brands Corporation |
| Corelle Brands LLC |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Amcor PLC |
| Helen of Troy Limited |
| Newell Brands Inc. |
| Others |
Value Chain & Pricing Dynamics
Polypropylene compounding scale in China's Yangtze River Delta anchors global cost floors for mid-tier container production, compressing margins for smaller format specialists while concentrating price-setting power among integrated molders with captive resin supply.
Pricing Analysis
Price spreads between German borosilicate glass and Southeast Asian polypropylene containers exceed threefold at retail, with EU REACH compliance costs and third-party migration testing documentation driving premium tier separation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance claims. Cost compression in mass-market plastic sets is intensifying as Yangtze River Delta capacity consolidates. Meal prep subscription services show least price sensitivity due to logistics standardization requirements, while individual household bulk-set purchasers in North American mass retail channels exhibit highest elasticity.
Supply Chain Analysis
Container lid inventory cycles stretch 8-12 weeks when platinum-cured silicone seal compounders in South Korea and Japan impose allocation rationing during polymer feedstock volatility. Manufacturing concentrates in China, Germany, and the United States, with molding operations drawing from Saudi Arabian and Qatari polypropylene resin supply. Single-source vulnerability concentrates in platinum-cured silicone gasket production among three Asian compounders. Distribution runs through organized retail chains, direct-selling networks in Latin America, and subscription meal service procurement coordinators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among logistics coordinators at meal kit subscription services, fragmenting traditional retail procurement authority and compressing supplier negotiation leverage for undifferentiated container makers.
For Market Incumbents: Fortify barrier film technology positions through backward integration into copolymer formulation, defending against stainless steel substitution in freezer-to-oven applications. Anchor German market share through preemptive EU REACH Annex XVII compliance documentation investments that smaller rivals cannot replicate. Prioritize captive silicone seal compounding capacity to insulate margin structures from Asian supply rationing. For New Entrants and Emerging Players: FSSAI fast-track certification for food-contact materials unlocks organized retail shelf access in India's tier-2 cities before compliance barriers harden. White-space concentrates in Bluetooth-enabled spoilage sensor integration for South Korean and Japanese premium households, and in direct-to-consumer seal replacement services that bypass retail markups. Go-to-market through meal prep subscription service white-label partnerships accelerates volume scaling without brand build-out costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-selling infrastructure owners with established Latin American distributor networks and subscription bundling relationships. Long-term viability favors compounders with validated bio-based polymer formulations for EU Green Deal alignment. Acquisition targets should demonstrate captive platinum-cured silicone seal production or certified biodegradable material pipelines. Signal to monitor: German retailer mandates for third-party migration testing documentation spreading to other EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copolymer Formulation | Captive BPA-free Tritan supply insulates margin compression from resin price volatility. |
| Subscription Service White-Label Partnerships | Logistics coordinator relationships displace traditional retail procurement concentration. |
| Smart Lid Sensor Integration | Bluetooth spoilage detection opens premium positioning in South Korean urban households. |
| FSSAI Certification Fast-Track Investment | First-mover compliance captures organized retail expansion in Maharashtra and Karnataka. |
| Direct-to-Consumer Refurbishment Launch | Mail-in seal replacement builds loyalty moats bypassing traditional channel markups. |
Study Parameters
A standing panel of polymer formulation chemists, meal kit logistics coordinators, organized retail category buyers, and direct-selling network managers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FDA 21 CFR migration limit databases, EU ECHA REACH registration filings, China SAMR GB standard publications, and FSSAI packaging compliance circulars. Bottom-up container unit shipment estimates from manufacturing clusters triangulated against top-down household expenditure surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including material type, capacity tier, sealing technology grade, and end-user procurement channel. CAGRs derived from logistic adoption curves for smart container features and regulatory phase-in timelines for extended producer responsibility schemes. Industry-specific inputs incorporated German municipal composting mandate enforcement trajectories and platinum-cured silicone supply allocation patterns.
Decision-makers should treat outputs as directional under sustained EU Single-Use Plastics Directive enforcement and stable polymer feedstock pricing; material deviation in regulatory timelines or resin supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Single Lip Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Crates Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Textile Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Wooden Boxes Market