
 Bag & Bag Aerosol Can Market | 2026-2036
Bag & Bag Aerosol Can Market Size, Share, and Industry Trends Forecast 2026-2036
Bag & Bag Aerosol Can Market Analytics
Asset-light leasing arrangements for aerosol filling equipment is fragmenting competitive dynamics among metal packaging suppliers. Crown Holdings Inc. leverages captive aluminum supply to control raw material costs across its aerosol operations. Ball Corporation anchors North American beverage-can scale while extending technical metallurgy into precision aerosol shells. Silgan Holdings Inc. specializes in composite can formats for food-grade barrier applications where oxygen ingress tolerance sits below 0.1 cc per day.
Bag and bag aerosol cans consist of a laminated multi-ply barrier pouch welded inside a rigid outer shell, with the product isolated from propellant through a hermetic seal rated for pressures between 6 and 10 bar at 50°C. This architecture serves pharmaceutical, cosmetic, and food applications requiring zero contact between formulation and hydrocarbon or compressed gas propellant. Metal cans dominate volume in personal care due to established recycling infrastructure and crush resistance, while composite cans represent the fastest-growing category as brands target shelf differentiation and reduced shipping weight for e-commerce channels. Eco-friendly packaging commands margin premiums in European retail where Extended Producer Responsibility fees penalize non-recyclable formats.
The EPA regulates volatile organic compound content in consumer aerosols under 40 CFR 59, constraining propellant chemistry and driving laminate barrier adoption to enable water-based formulations. REACH compliance through ECHA mandates disclosure of monomers and additives in bag laminates, adding testing overhead for suppliers serving EU personal care brands. India's BIS certification for aerosol valves and containers creates separate type-approval pathways for exporters. Stakeholders must track how propellant-phaseout timelines in major jurisdictions reshape laminate specification requirements and qualification cycles for new barrier materials.
Market Dynamics
Europe's F-Gas Regulation is forcing propellant-phaseout timelines that compress laminate qualification cycles and reshape supplier R&D priorities across barrier packaging systems.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure requirements for monomers and additives in bag laminates push personal care brands toward pre-qualified barrier suppliers with established testing protocols.
- Compressed air propellant shift:Germany's precision aerosol manufacturing clusters accelerate nitrogen-based system adoption for pharmaceutical contract packers seeking zero hydrocarbon contact.
- E-commerce shelf differentiation:Composite can formats reduce shipping weight and enable dimensional optimization for direct-to-consumer cosmetic brands.
Market Restraints
- Aluminum supply concentration:Captive smelter arrangements among top metal packaging suppliers limit second-source options for mid-tier aerosol manufacturers.
- Laminate qualification timelines:ECHA additive disclosure requirements extend testing overhead by 12-18 months for new barrier material introductions.
- Mechanical substitute pressure:Pump-action dispensers and airless bottles capture sensitive formulation segments where propellant elimination outweighs spray performance.
Strategic Opportunities
- India BIS certification pathway:Separate type-approval requirements for aerosol valves and containers create first-mover advantage for suppliers establishing local testing partnerships.
- Extended Producer Responsibility tailwinds:European retail fee structures penalizing non-recyclable formats generate margin premiums for metal-can platforms with established recycling infrastructure.
- Food-grade barrier convergence:Oxygen ingress tolerance below 0.1 cc per day enables wine and cooking spray applications previously blocked by flavor-scalping concerns.
Industry Challenges
- Metallurgical talent scarcity:Precision aerosol shell engineering requires specialized thin-wall aluminum forming expertise concentrated in legacy manufacturing regions.
- Multi-jurisdiction compliance synchronization:EPA 40 CFR 59 VOC constraints, ECHA laminate disclosures, and BIS valve approvals create divergent specification matrices for global product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag & Bag Aerosol Can Market |
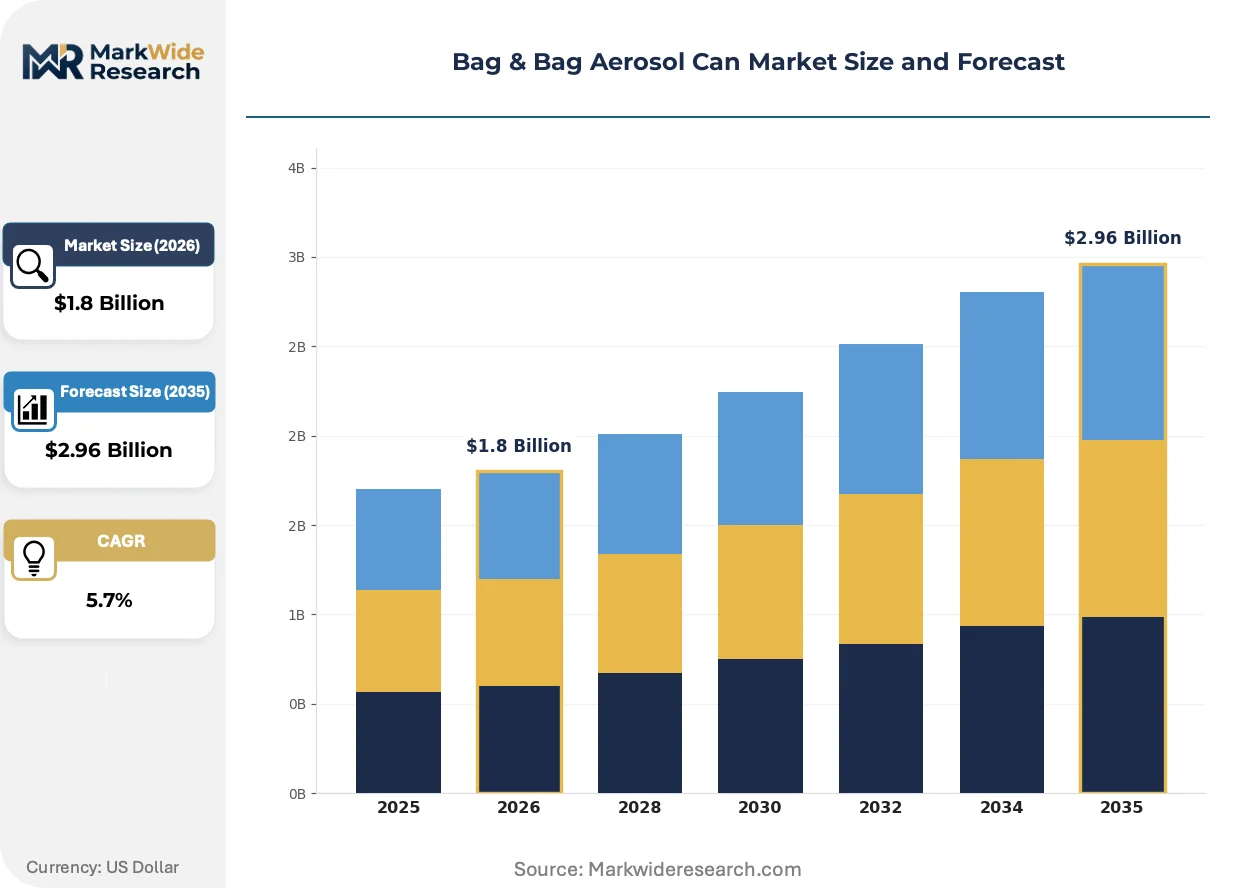
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Metal Cans, Composite Cans, Paper Bags End User: Household, Personal Care, Food & Beverage, Industrial Packaging Type: Flexible Packaging, Rigid Packaging, Eco-friendly Packaging, Standard Packaging Distribution Channel: Retail Stores, E-commerce, Direct Sales, Wholesale |
| Companies Covered | Crown Holdings Inc., Ball Corporation, CCL Container Inc., Ardagh Group S.A., Trivium Packaging, AptarGroup Inc., Silgan Holdings Inc., Mauser Packaging Solutions, Lindal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag & Bag Aerosol Can Market Evolving Landscape
Barrier material science and propellant chemistry are converging to enable water-based formulations previously incompatible with conventional aerosol architectures.
Ethylene vinyl alcohol copolymer laminates are collapsing the performance gap between metal and composite barrier systems. Cosmetic brands in Germany and Switzerland are adopting these structures for preservative-free formulations requiring absolute oxygen exclusion. The technology is collapsing traditional material selection hierarchies that privileged aluminum for high-barrier applications.
Europe's F-Gas Regulation mandates phased reduction in hydrofluorocarbon propellants with complete phaseout timelines accelerating through 2030. This industrial consequence compresses R&D investment into compressed gas compatibility testing and laminate adhesion protocols. Pharmaceutical aerosol manufacturers face the steepest retrofit requirements as sterility validation cycles extend qualification timelines.
Direct procurement from laminate converters is displacing tiered distributor networks for mid-size personal care brands. Cosmetic contract packers in Germany now source multi-ply barrier pouches directly from specialized film laminators, bypassing traditional can-making intermediaries. This channel compression is most visible in precision aerosol clusters where technical specification dialogue requires direct metallurgical and polymer chemistry expertise.
Bag & Bag Aerosol Can Market Segmentation
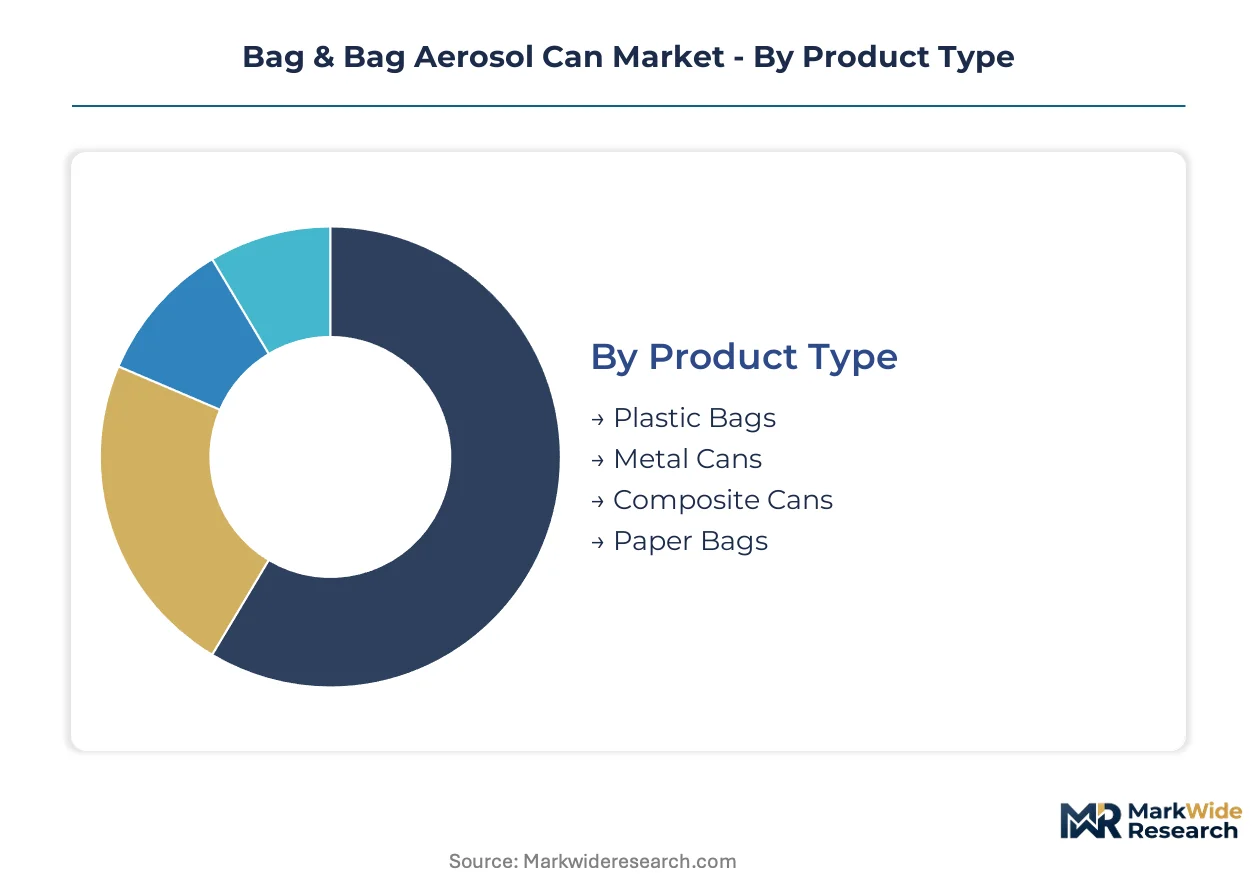
Segmentation in the bag and bag aerosol can market reveals how technical specifications, regulatory compliance, and end-use requirements fragment procurement patterns across buyer categories. Each dimension carries distinct service intensity profiles that reshape supplier relationships and margin structures.
Product Type:
After-sales service intensity varies sharply across material platforms, with metal and composite formats demanding specialized filling equipment calibration support that plastic alternatives rarely require.
- Metal Cans:Aluminum or tinplate shells with hermetic seam welding rated for 6-10 bar pressures. Demand concentrates in Germany's precision aerosol manufacturing clusters serving pharmaceutical contract packers under ECHA REACH compliance mandates.
- Composite Cans:Fiber-wound or plastic-bodied structures with laminated barrier liners. E-commerce cosmetic brands in Switzerland and France drive specification for reduced shipping weight and dimensional optimization.
- Plastic Bags:Multi-ply laminated pouches for low-pressure applications with simplified valve attachment.
- Paper Bags:Kraft-based barrier structures for dry powder aerosol formats with limited moisture sensitivity.
Metal cans hold the largest share; momentum sits with composite cans.
End User:
Application-driven performance requirements create divergent qualification protocols, with pharmaceutical and food segments imposing sterility validation cycles that household products bypass entirely.
- Personal Care:Preservative-free and sensitive formulations requiring absolute oxygen exclusion. Ethylene vinyl alcohol copolymer laminates are displacing aluminum in German and Swiss cosmetic brands seeking shelf differentiation.
- Food & Beverage:Cooking sprays and wine applications with oxygen ingress tolerance below 0.1 cc per day. Europe's F-Gas Regulation accelerates compressed nitrogen propellant adoption for flavor-sensitive products.
- Household:Cleaning and air freshener applications with established hydrocarbon propellant compatibility.
- Industrial:Lubricant and coating aerosols with solvent-heavy formulations and minimal barrier sensitivity.
Personal care commands premium pricing; food and beverage applications are expanding most quickly.
Packaging Type:
Structural rigidity versus flexibility trade-offs determine logistics economics and retail display requirements, with sustainability credentials increasingly filtering procurement decisions.
- Eco-friendly Packaging:Recyclable mono-material or bio-based laminates qualifying for Extended Producer Responsibility fee reductions. European retail chains penalize non-recyclable formats through structured penalty schedules.
- Rigid Packaging:Established aluminum platforms with crush resistance and established recycling infrastructure.
- Flexible Packaging:Reduced material weight for direct-to-consumer shipping channels.
- Standard Packaging:Conventional multi-material laminates without sustainability certification.
Rigid packaging retains volume leadership; eco-friendly formats gain share fastest.
Distribution Channel:
Channel configuration dictates lot size flexibility and technical specification dialogue intensity, with direct procurement compressing traditional distributor networks.
- E-commerce:Direct-to-consumer fulfillment requiring dimensional optimization and damage-resistant composite formats. German cosmetic contract packers now source barrier pouches directly from specialized film laminators.
- Retail Stores:Mass-market personal care with standardized specifications and high-volume replenishment cycles.
- Direct Sales:Pharmaceutical and institutional accounts with custom formulation requirements.
- Wholesale:Industrial and food-service intermediaries with consolidated procurement and extended payment terms.
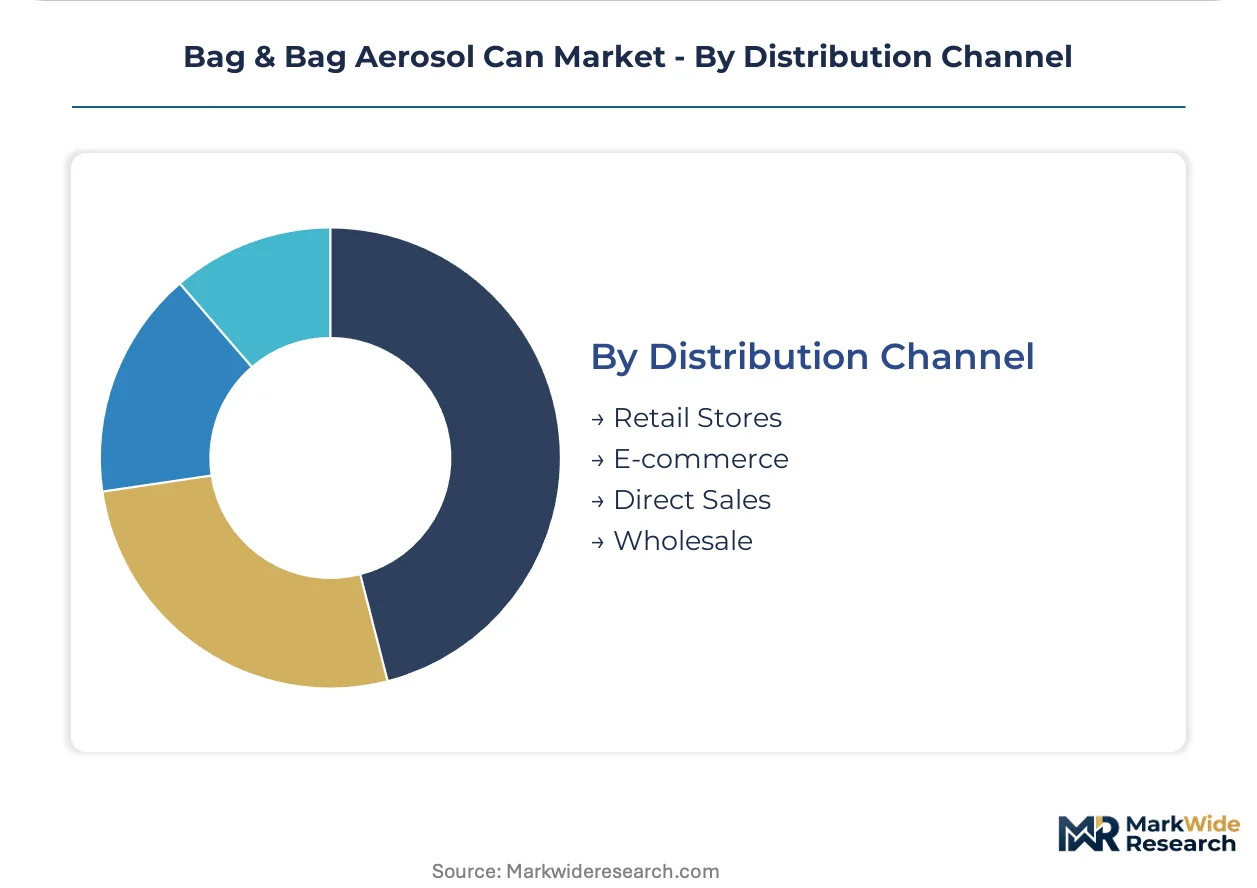
Retail stores dominate transaction volume; e-commerce channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's F-Gas Regulation is compressing propellant-phaseout timelines and redirecting capital toward compressed gas barrier systems. Germany's precision manufacturing clusters anchor continental supply for pharmaceutical contract packers. India's BIS certification pathway creates parallel qualification requirements for exporters seeking access to its domestic personal care market.
Germany
Cosmetic contract packers in Baden-Württemberg and Bavaria drive specification for nitrogen-based bag-on-valve systems serving preservative-free formulations. ECHA REACH mandates on laminate additive disclosure extend qualification cycles for new barrier materials entering the market. The Stuttgart precision aerosol cluster concentrates technical metallurgy expertise for thin-wall aluminum shell forming.
United States
EPA 40 CFR 59 VOC constraints on consumer aerosol propellants push brands toward water-based formulations requiring advanced laminate barriers. The agency's emission thresholds reshape R&D priorities for domestic barrier material suppliers. Chicago-area contract packers serve mass-market personal care brands with established hydrocarbon-compatible filling infrastructure.
India
BIS certification requirements for aerosol valves and containers create separate type-approval pathways that extend market entry timelines for foreign suppliers. The central government's phased manufacturing program incentivizes domestic production of precision metal shells. Maharashtra's industrial corridors near Mumbai concentrate emerging contract packing capacity for regional cosmetic brands.
Switzerland
Swissmedic pharmaceutical regulations impose sterility validation requirements that compress supplier qualification timelines for barrier packaging systems. Swiss cosmetic brands in the Basel-Zurich corridor adopt ethylene vinyl alcohol copolymer laminates for absolute oxygen exclusion applications. The country's precision manufacturing heritage supports high-barrier pharmaceutical aerosol production.
China
NMPA pharmaceutical packaging standards and MIIT industrial guidelines create dual compliance frameworks for barrier material suppliers. The country's dual carbon goals accelerate compressed air propellant adoption in domestic personal care manufacturing. Yangtze River Delta chemical clusters develop localized supply chains for multi-ply laminate films.
Bag & Bag Aerosol Can Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: captive aluminum smelter operators, specialized barrier laminate converters, and integrated can-making specialists. Metal packaging dominates volume through established recycling infrastructure and crush resistance for retail channels. Composite formats represent the fastest-growing category as e-commerce cosmetic brands prioritize shipping weight reduction. Strategic moves center on backward integration into aluminum supply and direct procurement relationships that bypass traditional distributor networks.
Among North American metal packaging specialists, Crown Holdings Inc., Ball Corporation, and Silgan Holdings Inc. occupy positions across the integrated-manufacturer archetype. Crown Holdings exemplifies captive raw material control through aluminum supply chain ownership. Ball Corporation anchors technical metallurgy capabilities extending from beverage can scale into precision aerosol applications. Silgan Holdings represents composite can specialization for food-grade barrier segments where oxygen ingress tolerance requirements sit below 0.1 cc per day.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Ball Corporation |
| CCL Container Inc. |
| Ardagh Group S.A. |
| Trivium Packaging |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Mauser Packaging Solutions |
| Lindal Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta laminate film clusters is compressing margins for mid-tier barrier suppliers while concentrating pricing power among German precision aerosol manufacturers with captive metallurgical capabilities. This utilization asymmetry rewards integrated players with aluminum smelter control and pressures standalone converters to absorb ECHA compliance costs.
Pricing Analysis
Certification level creates the primary spread, separating REACH-compliant laminates with full additive disclosure from standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects sterility validation depth and propellant compatibility testing. Cost compression in composite formats is intensifying because e-commerce brands demand dimensional optimization without barrier performance sacrifice. Pharmaceutical contract packers show least price sensitivity due to sterility validation requirements, while household cleaning brands maximize volume leverage.
Supply Chain Analysis
Export control regimes on ethylene vinyl alcohol copolymer resin technology limit laminate converter expansion outside established chemical clusters. Supply concentrates in Germany, China, and Switzerland, with raw material dependencies spanning aluminum smelter output, multi-ply film substrates, and precision valve assemblies. Single-source vulnerability runs through Germany's thin-wall aluminum forming expertise, where metallurgical talent scarcity constrains capacity expansion. Distribution runs through direct procurement relationships that displace traditional can-making intermediaries for mid-size cosmetic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German cosmetic contract packers consolidating procurement through direct laminate converter relationships, fragmenting traditional supplier tiers. This concentration forces packaging specialists to defend margin through technical specification lock-in rather than volume leverage.
For Market Incumbents: Insulate position by deepening captive aluminum supply control and accelerating nitrogen-based system R&D ahead of F-Gas phaseout deadlines. Ball Corporation and Crown Holdings should extend technical metallurgy partnerships with Stuttgart-area precision formers to secure thin-wall shell capacity. ECHA additive disclosure mandates threaten margin if testing overhead cannot be passed through. For New Entrants and Emerging Players: Pursue white-space opportunities in India's BIS-certified valve and container segments, where domestic manufacturing incentives create first-mover advantage for localized testing partnerships. Maharashtra's industrial corridors near Mumbai offer the most penetrable geography for regional cosmetic brand supply. A direct-to-e-commerce go-to-market angle bypasses established retail channel gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because propellant-phaseout timelines across EPA, ECHA, and BIS jurisdictions create divergent qualification cycles that favor multi-jurisdiction compliance platforms. Acquisition targets should display established testing protocols across at least two regulatory clusters. Watch for F-Gas Regulation acceleration announcements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Crown Holdings leverages captive supply to control raw material costs across aerosol operations. |
| Direct Laminate Converter Procurement | German cosmetic contract packers bypass can-making intermediaries for technical specification dialogue. |
| Nitrogen-Based System R&D Expansion | Pharmaceutical manufacturers face compressed retrofit timelines under Europe's F-Gas Regulation mandates. |
| BIS Certification Partnership Establishment | Foreign suppliers extend market entry timelines without local testing infrastructure in India. |
| Ethylene Vinyl Alcohol Copolymer Adoption | Swiss cosmetic brands deploy these laminates for preservative-free formulations requiring absolute oxygen exclusion. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings from packaging specialists, and ECHA additive disclosure registries preceded structured interviews with aerosol contract packing operations managers, laminate converter technical directors, pharmaceutical packaging procurement leads, and personal care brand supply chain executives. Primary fieldwork combined with secondary validation from aluminum industry association reports and barrier material patent filings. Bottom-up volume estimates triangulated against top-down market sizing from identified production clusters.
Assumptions held F-Gas Regulation phaseout timelines and EPA 40 CFR 59 VOC thresholds fixed across the analysis window, while varying laminate adoption rates by end-use segment and propellant chemistry shifts. The analytical framework modeled product type, end user application, packaging format sustainability credentials, and distribution channel configuration. CAGRs derived from segment-level volume trajectories weighted by regional production capacity shares. Forecast inputs incorporated REACH compliance cost pass-through elasticity and compressed air propellant compatibility testing cycles.
Sensitivities concentrate around ECHA additive disclosure timeline extensions, BIS certification pathway acceleration, and aluminum price volatility from energy cost fluctuations. Forecasts reflect these documented assumptions. Material shifts in F-Gas Regulation enforcement intensity or laminate qualification protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Octabin Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
FIBC Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Inner Bulk Liners Market