
 Bag-In-Box Market | 2026-2036
Bag-In-Box Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Box Market Analysis
The premium wine segment and commodity juice packaging tier is rebalancing as barrier specifications diverge and brand owners demand longer shelf-life performance. Amcor plc leverages its multi-layer film technology to sustain leadership in high-oxygen-barrier applications. Scholle IPN Corp anchors its position through specialized fitment and tap systems that differentiate performance across liquid categories.
Bag-in-box denotes a flexible packaging format comprising a collapsible inner bag sealed within a rigid outer corrugated or paperboard box, typically incorporating ethylene vinyl alcohol or metallized film layers to achieve oxygen transmission rates below one cubic centimeter per square meter per day. The assembly serves to dispense liquids while minimizing oxidation, spillage, and shipping volume loss across food service and retail channels. Wine and juice applications lead volume adoption, with wine commanding higher margin pools due to stringent barrier requirements and brand positioning. Composite material constructions represent the fastest-growing material category as converters blend cost efficiency with regulatory-compliant barrier performance. Food service end users dominate bulk throughput, though retail channel growth accelerates as supermarkets expand private-label bag-in-box offerings.
FDA food contact regulations in the United States and EU REACH restrictions on certain phthalate plasticizers shape film formulation choices and supplier qualification timelines across the supply base. EFSA migration limits and EPA manufacturing emissions standards further constrain material selection and production site certification for suppliers serving North American and European customers. Stakeholders must monitor evolving extended producer responsibility frameworks and barrier technology substitution cycles to preserve formulation flexibility and geographic market access.
Market Dynamics
Barrier film specification divergence between premium wine and commodity juice tiers is compressing converter margins while forcing dual-track R&D investment strategies across the supply base.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant restrictions on fluorinated gases are accelerating metallized film substitution with ethylene vinyl alcohol laminates in high-barrier wine applications.
- Food service channel expansion:Bulk dispensing systems for institutional catering and hospitality operators are displacing rigid alternative formats across France, Germany, and Italy.
- Extended producer responsibility frameworks:EU member state packaging waste directives are mandating recyclability thresholds that favor paperboard-integrated bag-in-box over pure plastic alternatives.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Three Asian petrochemical suppliers control over 70% of specialized EVOH feedstock, exposing converters to input cost volatility and allocation risk.
- Metallized film technical ceiling:Current vacuum deposition processes cannot reliably achieve sub-0.5 cc/m²/day oxygen transmission rates required for ultra-premium wine shelf-life extension.
- REACH compliance friction:ECHA substance of very high concern listings for certain adhesive plasticizers are extending supplier qualification timelines by 12-18 months.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in Maharashtra and Karnataka is creating first-mover advantage for bag-in-box edible oil and dairy packaging formats.
- Biopolymer barrier convergence:Polyhydroxyalkanoate and cellulose nanocrystal co-extrusion technologies are opening certified-compostable pathways for organic wine and juice positioning.
- Direct-to-consumer subscription channels:E-commerce wine clubs in the United States are bypassing traditional three-tier distribution with custom-fitment bag-in-box configurations.
Industry Challenges
- Multi-layer film recycling infrastructure:Current mechanical separation technologies cannot process EVOH-polyethylene-nylon laminates at commercial scale, creating circular economy compliance gaps.
- Fitment-tap system integration complexity:Brand owners demand proprietary dispensing interfaces that require converter co-development cycles extending 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Box Market |
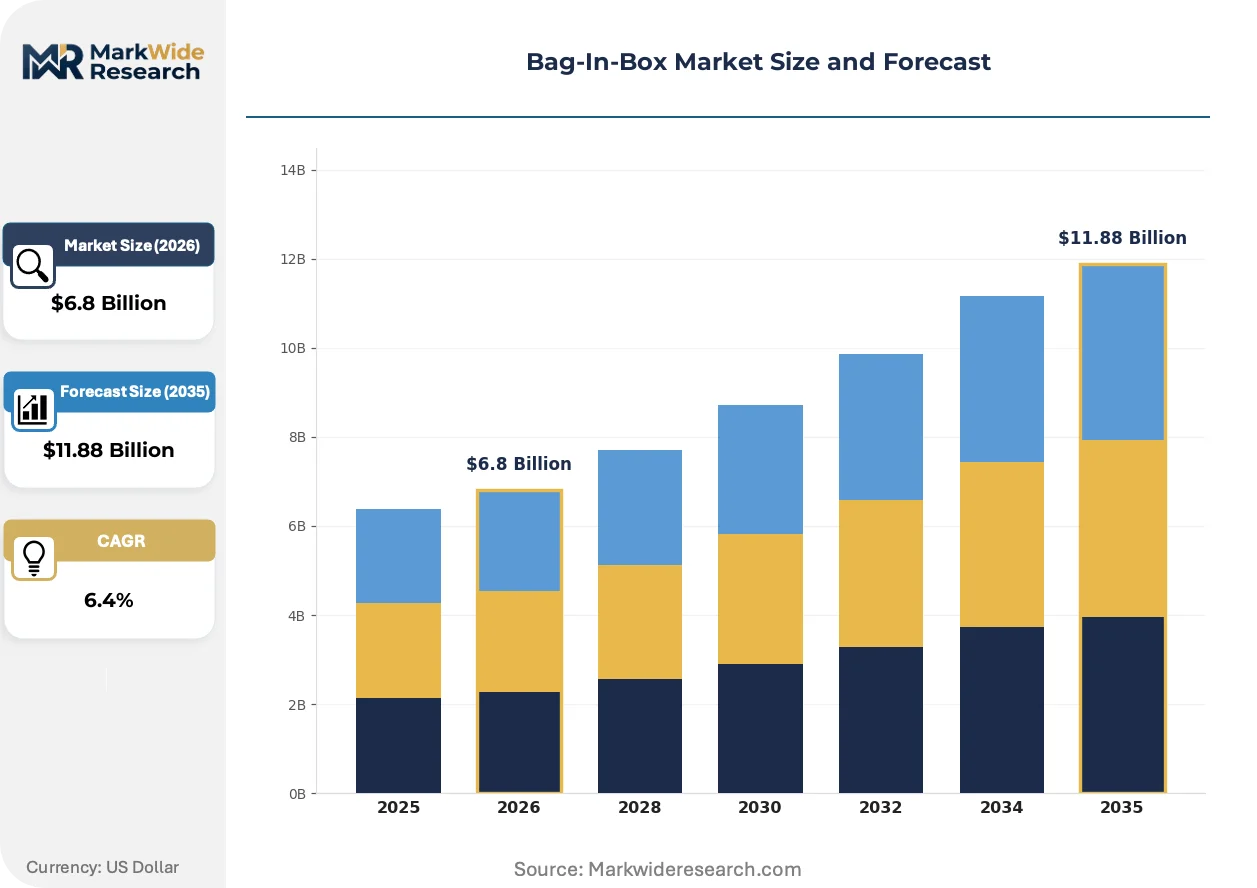
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine, Juice, Soft Drinks, Sauces Material: Plastic, Paperboard, Aluminum, Composite End User: Food Service, Retail, Home Use, Industrial Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Amcor plc, Smurfit Kappa, DS Smith PLC, Scholle IPN Corp, Sealed Air Corporation, Liqui-Box, CDF Corporation, International Paper, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Box Market Emerging Trajectories
Active barrier modification and dispensing interface miniaturization are compressing product development cycles while redefining performance benchmarks across liquid packaging categories.
Inline spectroscopic quality control is automating defect detection in multi-layer film extrusion lines. Wine packaging converters in Bordeaux and Napa Valley are deploying near-infrared systems at 400 meters per minute line speeds. This technology is automating the rejection of pinhole defects and gauge variations that previously required manual sampling protocols.
EU REACH restrictions on per- and polyfluoroalkyl substances are prohibiting fluoropolymer-based grease barriers in paperboard outer structures. Converters serving European retail chains are reformulating with bio-wax and clay coatings. Premium wine applications in France and Italy face the tightest compliance deadlines under the 2025 restriction entry into force.
Private-label supermarket procurement is consolidating supplier panels around integrated film-box-fitment providers. Discounters in Germany and the Netherlands are awarding three-year exclusive contracts to vertically capable converters. Food service distributors in the United States are following with similar bundling requirements, compressing the viable vendor base.
Bag-In-Box Market Segmentation
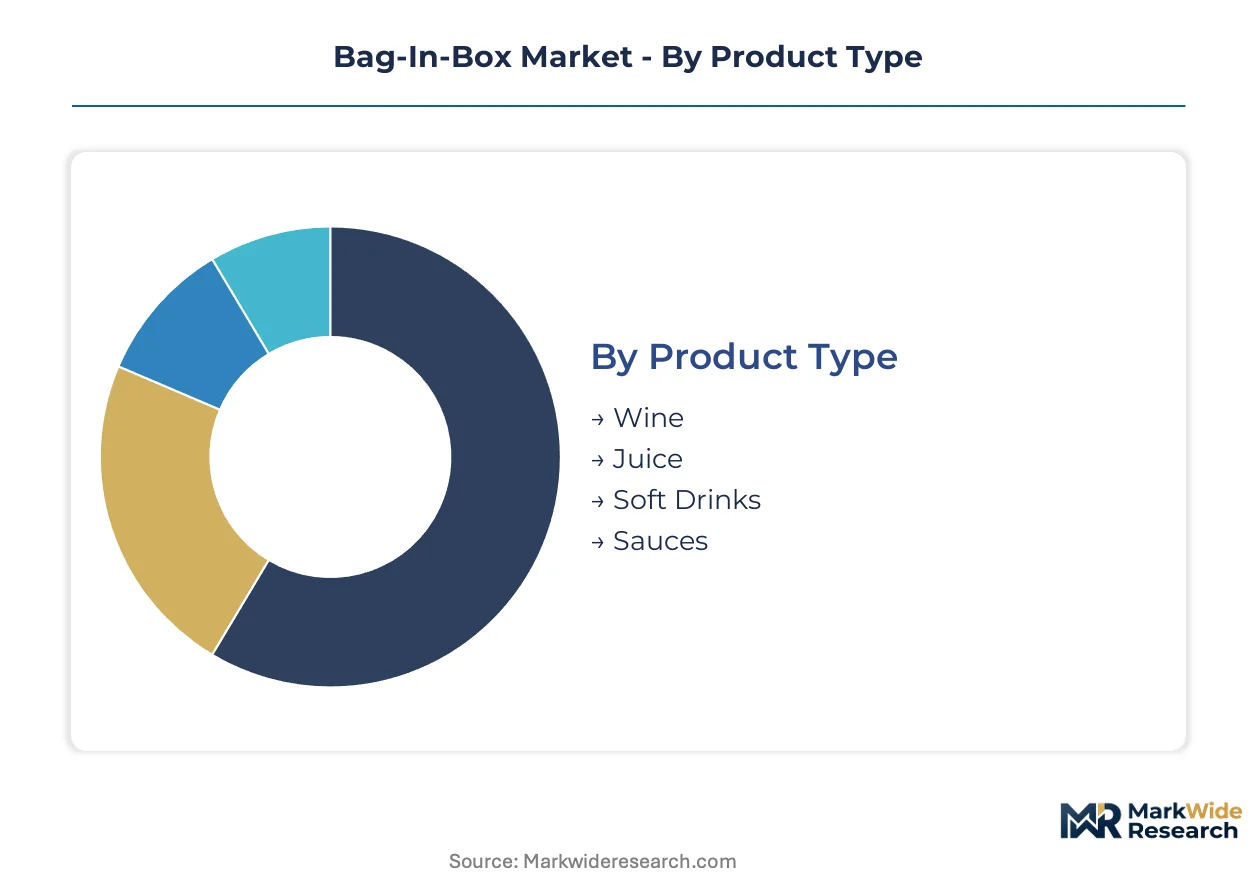
Bag-in-box packaging performance requirements diverge sharply across liquid categories and end-use environments. Material specifications, barrier demands, and dispensing interface complexity create distinct margin pools that shape supplier targeting and converter investment priorities.
Product Type:
Wine buyers prioritize oxygen transmission rates below one cubic centimeter per square meter per day, while juice procurement emphasizes cost-efficient short-shelf-life formats.
- Wine:Multi-layer EVOH or metallized film constructions dominate premium positioning. Demand concentrates in France, Italy, and California where estate bottlers specify custom fitment systems for food service and direct-to-consumer channels. REACH compliance on adhesive plasticizers extends supplier qualification timelines.
- Juice:Standard polyethylene-nylon laminates serve commodity retail tiers. German and Dutch supermarket private-label programs are consolidating supplier panels around vertically integrated converters capable of film-box-fitment bundling.
- Soft Drinks:Carbonation retention requirements favor high-barrier coextrusions with specialized inner layers.
- Sauces:Viscous liquid dispensing demands wider-diameter fitments and reinforced film gauge specifications.
Wine leads on scale; soft drinks lead on momentum.
Material:
Converter margins compress where resin concentration creates allocation risk, favoring backward integration into captive EVOH supply.
- Composite:Blended constructions of polyethylene, nylon, and EVOH balance barrier performance with regulatory compliance. French and Italian wine packaging converters deploy these materials for premium applications requiring sub-0.5 cc/m²/day oxygen transmission specifications.
- Plastic:Pure polyethylene or polypropylene structures serve cost-sensitive juice and soft drink volumes. Three Asian petrochemical suppliers control over 70% of specialized barrier resin feedstock, exposing converters to input volatility.
- Paperboard:Outer box structures face EU REACH restrictions on per- and polyfluoroalkyl substances, driving bio-wax and clay coating substitution.
- Aluminum:Metallized film layers achieve intermediate barrier tiers for mid-market wine positioning.
Plastic dominates volume throughput; composite climbs the fastest.
End User:
Channel-specific dispensing protocols and volume scale determine fitment system complexity and converter co-development cycle length.
- Food Service:Institutional catering and hospitality operators in France, Germany, and Italy drive bulk dispensing system adoption. Extended producer responsibility frameworks favor paperboard-integrated formats over pure plastic alternatives.
- Retail:Supermarket private-label procurement in Germany and the Netherlands awards multi-year exclusive contracts to integrated suppliers.
- Home Use:Smaller-format configurations target convenience-oriented consumers through e-commerce wine clubs.
- Industrial:Bulk ingredient storage for food manufacturing requires specialized aseptic fitment systems.
Food service anchors throughput; retail gains share fastest.
Distribution Channel:
Procurement consolidation around bundled film-box-fitment providers is compressing the viable vendor base across European and North American markets.
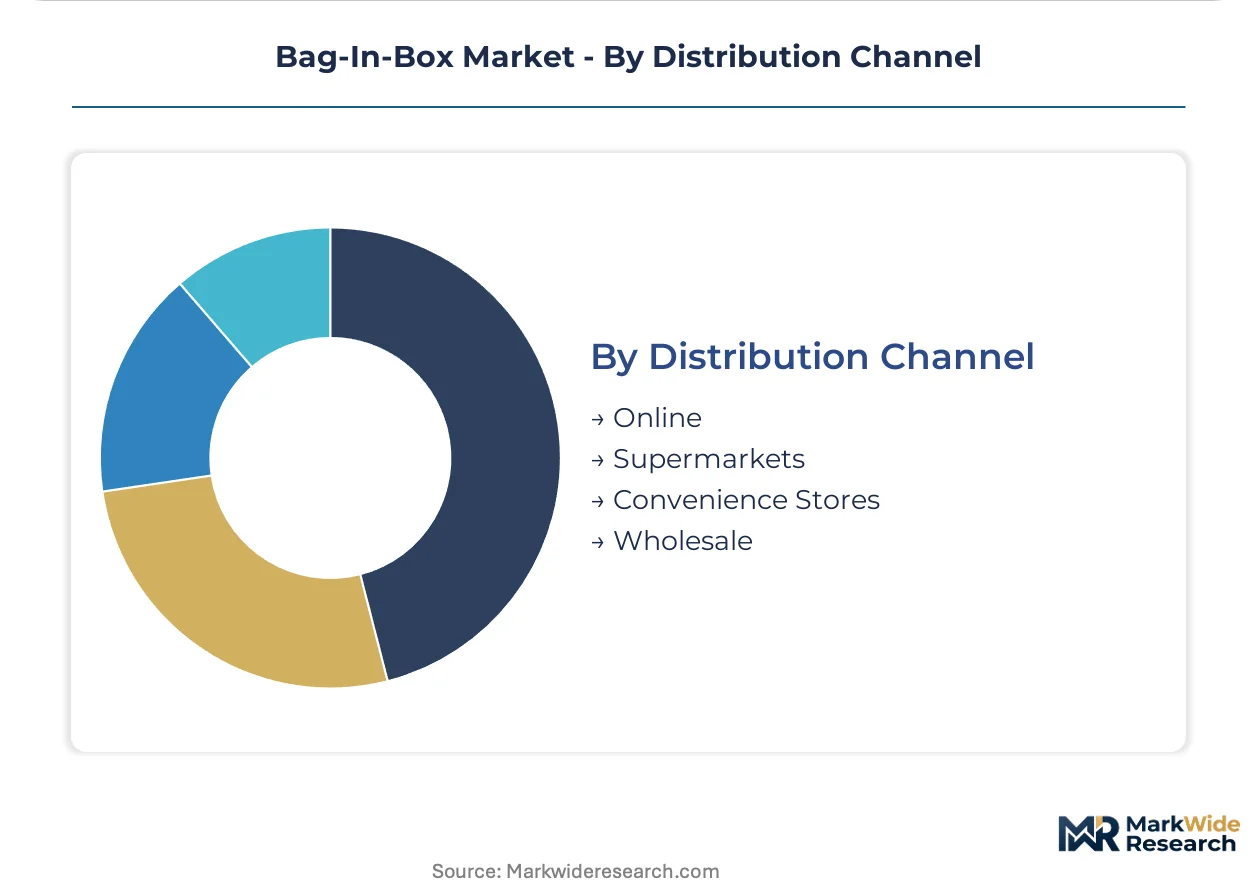
- Supermarkets:Discounter procurement panels in Germany and the Netherlands mandate integrated supplier capabilities spanning extrusion, corrugation, and fitment assembly.
- Wholesale:Food service distributors in the United States follow European bundling requirements, extending qualification timelines for specialized converters.
- Online:Direct-to-consumer wine clubs bypass traditional three-tier distribution with custom-fitment configurations.
- Convenience Stores:Small-format, high-turnover juice and soft drink placements emphasize cost-minimized standard specifications.
Supermarkets command procurement volume; online shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands higher wine packaging conversion rates than the United States, while Germany's supermarket consolidation accelerates supplier panel compression across Central Europe.
France
Bordeaux and Burgundy estate bottlers drive premium bag-in-box adoption for food service and direct-to-consumer channels. ECHA REACH restrictions on adhesive plasticizers extend supplier qualification timelines by 12-18 months. The Nouvelle-Aquitaine cluster concentrates converter investment in multi-layer EVOH film extrusion for sub-0.5 cc/m²/day oxygen barrier specifications.
Germany
Discounter procurement panels mandate integrated film-box-fitment bundling across private-label juice and wine programs. Extended producer responsibility frameworks under EU packaging waste directives favor paperboard-integrated formats. The Baden-Württemberg industrial corridor hosts vertically capable converters serving Aldi and Lidl exclusive contract awards.
United States
E-commerce wine clubs bypass traditional three-tier distribution with custom-fitment configurations. FDA food contact regulations and EPA manufacturing emissions standards constrain material selection and production site certification. California's Napa Valley packaging converters deploy near-infrared spectroscopic quality control systems at 400 meters per minute line speeds.
Italy
Tuscany and Piedmont wine producers specify custom dispensing interfaces requiring 18-24 month co-development cycles. EU F-Gas Regulation phase-down accelerates metallized film substitution with ethylene vinyl alcohol laminates. The Emilia-Romagna converter base specializes in high-barrier constructions for ultra-premium shelf-life extension.
India
Modern trade expansion in Maharashtra and Karnataka creates first-mover advantage for edible oil and dairy bag-in-box formats. FSSAI food safety standards and BIS packaging regulations shape import substitution strategies. The Gujarat industrial belt attracts film extrusion investment targeting organized retail penetration in Western India.
Bag-In-Box Market Vendor Landscape
Top-tier vendors anchor integrated film-box-fitment supply, while mid-scale specialists concentrate on regional dispensing interface customization. The vendor base stratifies around barrier technology leadership, vertical manufacturing depth, and food service channel relationships. Three archetypes dominate: multinational packaging conglomerates with captive resin supply, converter-assemblers focused on fitment-tap system innovation, and corrugated specialists leveraging paperboard integration for EPR compliance. Competitive moves center on backward integration into EVOH resin sourcing and exclusive procurement contracts with German and Dutch supermarket chains.
Among Australia-based packaging conglomerates, Amcor plc occupies a position exemplifying multi-layer film technology leadership for high-oxygen-barrier wine applications. Scholle IPN Corp and Liqui-Box represent the fitment-system specialization archetype, anchoring differentiation through proprietary tap and dispensing interface development. These three companies illustrate the competitive tension between material science depth and liquid handling expertise that defines supplier positioning across European and North American markets.
| Leading Market Players |
|---|
| Amcor plc |
| Smurfit Kappa |
| DS Smith PLC |
| Scholle IPN Corp |
| Sealed Air Corporation |
| Liqui-Box |
| CDF Corporation |
| International Paper |
| WestRock Company |
| Others |
Supply Flow & Price Mechanics
German and Dutch supermarket discounters command procurement leverage through exclusive three-year contract awards, forcing bundled film-box-fitment pricing models that compress unbundled converter margins. This buyer concentration rewards vertically integrated suppliers with captive EVOH supply while squeezing specialists dependent on spot resin markets.
Pricing Analysis
Bundled service contracts dominate German and Dutch retail procurement, while unbundled component sourcing persists in fragmented food service channels. Three-tier pricing structure across premium wine, standard juice, and economy soft drink applications reflects oxygen barrier performance and fitment complexity differentials. Cost compression in commodity juice tiers intensifies because Asian resin suppliers control over seventy percent of specialized EVOH feedstock. Private-label supermarket buyers exhibit highest price sensitivity; estate bottlers in Bordeaux and Napa Valley demonstrate lowest sensitivity due to custom dispensing interface requirements.
Supply Chain Analysis
REACH and FDA food contact certification gating extends supplier qualification timelines by twelve to eighteen months, favoring incumbents with established regulatory dossiers. Manufacturing concentrates in France, Germany, and Italy for premium wine applications; China and India host growing capacity for commodity juice and edible oil formats. Raw material dependencies center on ethylene vinyl alcohol resin, metallized film substrates, and specialized adhesive plasticizers. Single-source vulnerability pervades the EVOH feedstock layer where three Asian petrochemical suppliers anchor global availability. Distribution runs through integrated converter-assemblers capable of extrusion, corrugation, and fitment assembly under single-roof operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU REACH compliance costs and Indian FSSAI certification pathways creates manufacturing relocation incentives, with labor and regulatory cost differentials favoring Gujarat-based film extrusion investment for export-oriented supply.
For Market Incumbents: Deepen backward integration into captive EVOH resin sourcing to defend against Asian petrochemical supplier allocation risk and input cost volatility. Secure exclusive procurement contracts with Aldi and Lidl procurement panels before three-year renewal cycles consolidate supplier bases further. Prioritize co-development investments in biopolymer barrier technologies to preempt REACH restriction expansion on conventional plasticizers. For New Entrants and Emerging Players: Enter via Maharashtra and Karnataka organized retail corridors where modern trade expansion creates first-mover advantage for edible oil and dairy bag-in-box formats. Target India's underpenetrated dairy segment through FSSAI-compliant barrier film configurations adapted from European wine packaging specifications. Deploy direct technical sales teams to bypass established distributor relationships in Western India. For Investors and Strategic Acquirers: Packaging conglomerates with captive resin supply are the most active acquirer in this space, pursuing fitment-system specialists to complete vertical capability stacks. Five-to-ten year viability hinges on circular economy compliance infrastructure for multi-layer film recycling. Monitor EU extended producer responsibility framework implementation timelines as inflection indicator for recyclable-format investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin | Mitigates allocation risk from three Asian petrochemical suppliers controlling seventy percent of feedstock. |
| Biopolymer Barrier Certification | Opens compostable pathways for organic wine positioning under tightening EU REACH restrictions. |
| Exclusive Retail Contract Capture | Locks in three-year procurement awards from German and Dutch supermarket discounters consolidating panels. |
| India Manufacturing Footprint | Exploits FSSAI compliance cost advantages against EU REACH regulatory burden for export supply. |
| Multi-Layer Film Recycling Infrastructure | Addresses circular economy compliance gaps under EU packaging waste directives favoring paperboard integration. |
Methodological Framework
Bottom-up food service and retail channel modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with film extrusion plant managers, supermarket category buyers, estate bottler procurement leads, and food service distribution operators were validated against secondary sources including EU ECHA substance registration databases, FDA food contact substance notifications, SEC filings from packaging conglomerates, and trade flow data from French and Italian packaging industry associations.
Input-output matrices mapped resin feedstock availability through converter assembly to end-use channel demand across the projection horizon. Segmentation dimensions modeled include liquid category, barrier material construction, end-user channel, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating EVOH resin price trajectory assumptions and REACH compliance cost escalation curves for adhesive plasticizer reformulation.
Inputs from ECHA substance registration databases and FDA food contact notifications were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term supply estimates. Forecasts reflect documented assumptions regarding F-Gas Regulation phase-down timelines and extended producer responsibility implementation schedules. A model refresh is warranted upon material change in EU packaging waste directive recyclability thresholds or Asian petrochemical supplier EVOH allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Cross Corner Industrial Bags Market