
 Trash Bags Market | 2026-2036
Trash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Bags Market Intelligence
Expertise in polymer science and sustainable material engineering is rotating toward the development of high-performance recycled and compostable resins. Berry Global Group, Inc. leverages its significant manufacturing scale to offer a wide portfolio of products with recycled content. Reynolds Consumer Products Inc. sustains its market position through strong brand recognition and extensive retail channel control in the United States. Novolex Holdings, LLC specializes in both plastic and paper-based packaging solutions, including certified compostable bags.
Trash bags are flexible containers used to contain and dispose of solid waste. They are typically produced from plastic films like low-density polyethylene (LDPE) and are defined by properties such as tensile strength and puncture resistance. The material landscape shows a shift from traditional LDPE toward biodegradable and recycled plastics, driven by both consumer preference and institutional mandates. Drawstring bags lead the household product category, while flat bags are standard for waste management firms and commercial facilities.
The EU's Single-Use Plastics Directive and guidelines from the US EPA are compelling manufacturers to increase recycled content in their products. Concurrently, national bodies like India's BIS set specific requirements for bag thickness and material composition to curb plastic waste. Future competitiveness depends on strategic investments in either advanced recycling capabilities or the development of non-plastic material alternatives.
Market Dynamics
The trash bag market's central dynamic is the collision between material science and regulatory mandates. A structural shift away from virgin polyethylene is underway, driven by global pressure to incorporate recycled content and develop viable biodegradable alternatives without compromising essential performance characteristics.
Growth Catalysts
- Regulatory Mandates:Policies like the EU's Single-Use Plastics Directive and specific thickness and material standards from India's BIS are compelling manufacturers to integrate recycled plastics and explore alternative materials, stimulating innovation and new product lines.
- Hospitality Sector Expansion:Growth in hospitality providers, from hotels to food service establishments, requires a higher volume of durable and reliable waste containment solutions to manage increased waste streams and maintain hygiene standards.
- Urban Waste Management:Rapid urbanization and the formalization of municipal solid waste management systems, particularly in countries like India, are expanding the consumer base for standardized trash bags for household and commercial use.
Market Restraints
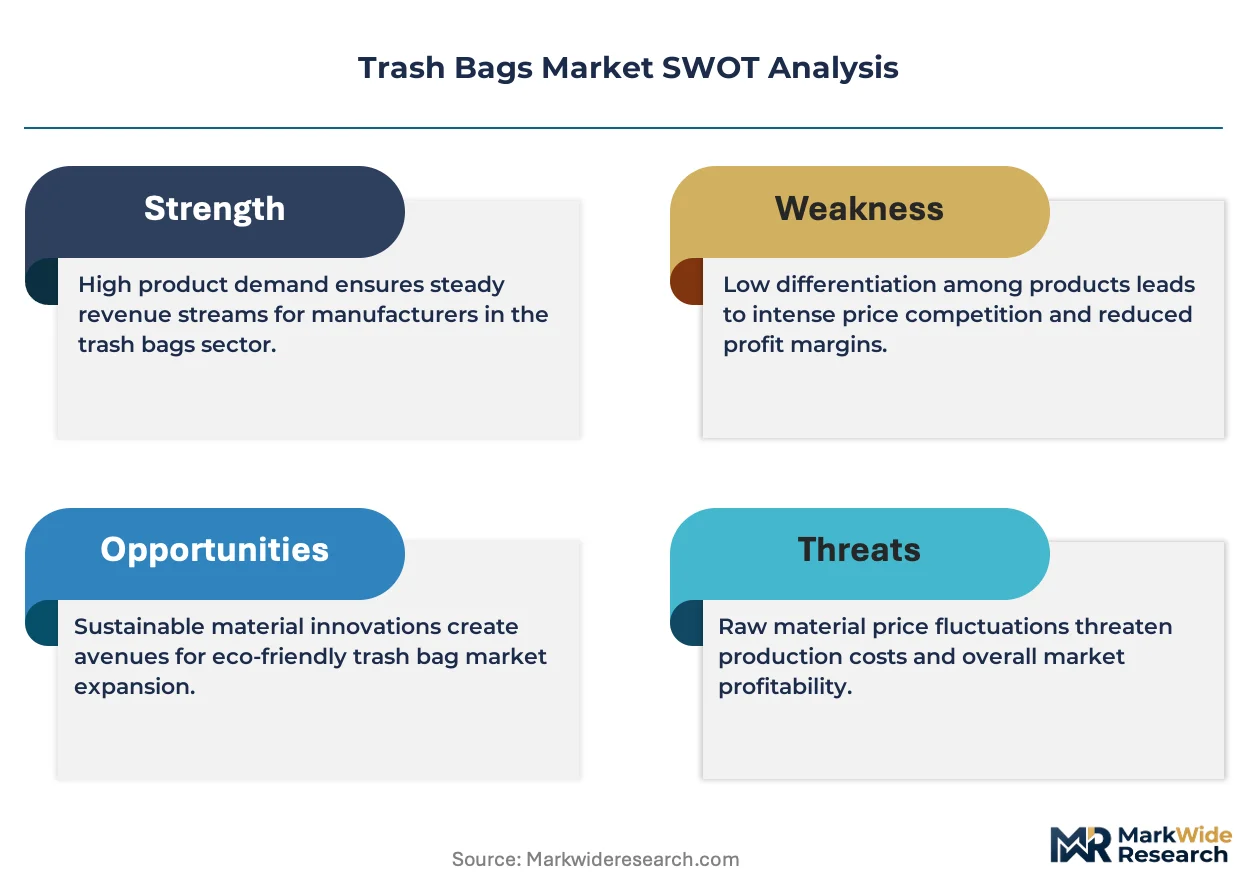
- Input Cost Volatility:The price and availability of high-quality post-consumer recycled (PCR) resins and biodegradable polymers like PLA are often more volatile than those of virgin polyethylene, impacting production costs and margin stability.
- Performance Trade-offs:Products made with high percentages of recycled content or certain biodegradable materials can exhibit lower tensile strength and puncture resistance, creating a performance gap with bags made from virgin resins.
- Substitution Threats:The adoption of bagless waste collection systems in some municipalities and a consumer push towards reusable containers for certain waste streams present a long-term substitution risk for single-use trash bags.
Strategic Opportunities
- High-Performance Compostables:There is significant opportunity in developing and marketing certified compostable bags, particularly from advanced polymers like PHA, that offer superior strength and meet the stringent requirements of industrial composting facilities.
- Geographic Expansion:Market penetration in regions like Southeast Asia and parts of Latin America remains low. Expanding distribution into countries with nascent formal waste management infrastructure represents a major growth vector.
- Channel Innovation:Developing direct-to-consumer subscription models for specialized products, such as compostable bags for organic waste bins, allows brands to capture niche segments and build direct customer relationships.
Industry Challenges
- Fragmented Compliance:Manufacturers face the challenge of navigating a complex web of differing national, state, and municipal regulations on bag thickness, recycled content minimums, and compostability labeling, increasing compliance costs.
- Feedstock Quality Control:Securing a consistent and clean supply of post-consumer recycled plastic is a primary operational hurdle, as contamination in the recycling stream can compromise the quality and performance of the final product.
- Certification Timelines:Obtaining third-party certifications for compostability or recycled content from bodies like BPI or TÜV Austria is a time-consuming and expensive process, creating barriers to entry for new formulations.
Report Scope
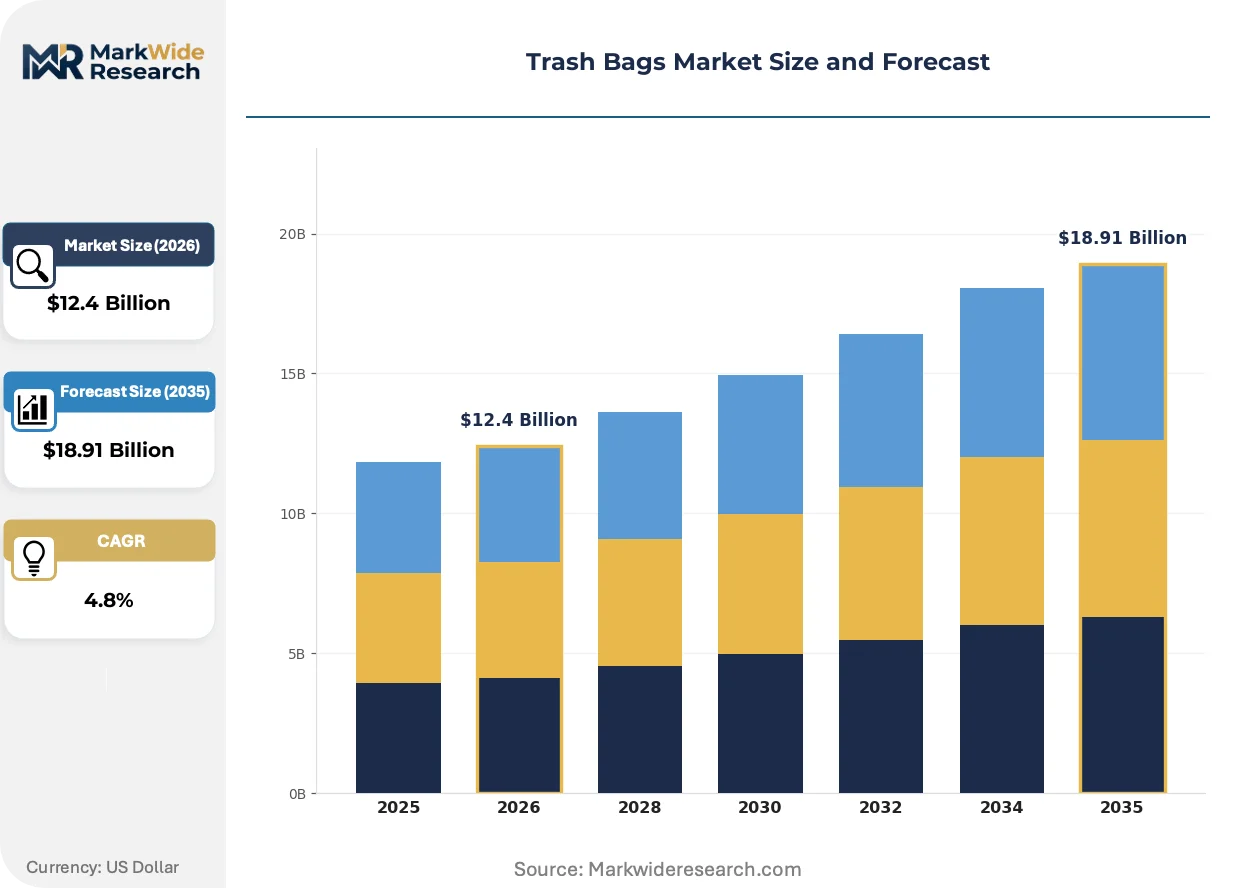
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Bags Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawstring Bags, Flat Bags, Rolled Bags, Flap Tie Bags, Gusseted Bags Material: Low-Density Polyethylene, High-Density Polyethylene, Biodegradable, Compostable, Recycled Plastic End User: Households, Hospitality Providers, Waste Management Firms, Educational Institutions, Commercial Facilities Distribution Channel: Supermarkets, Online Retailers, Wholesale Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Reynolds Consumer Products Inc., Sigma Plastics Group, Inc., Berry Global Group, Inc., Mondi plc, Pactiv Evergreen Inc., Novolex Holdings, LLC, Poly-America, International Plastics Inc., Inteplast Group, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Bags Market Strategic Shifts & Innovations
The industry's evolution is defined by a deliberate pivot toward circularity. This involves re-engineering materials for reduced environmental impact while navigating a complex landscape of international regulations and shifting consumer priorities regarding waste and sustainability.
Advanced Polymer Development
Advanced bioplastics like polyhydroxyalkanoates (PHA) provide an alternative to traditional LDPE and PLA. These materials are engineered for biodegradation in a wider range of environmental conditions, including marine and soil environments. Adoption is gaining traction among environmentally focused institutional buyers and municipalities with advanced organic waste processing capabilities, though consumer uptake is still nascent. This development is bifurcating the market into premium, fully biodegradable solutions and value-oriented, high-recycled-content polyethylene products.
Mandated Recycled Content
Regulations such as the EU's Single-Use Plastics Directive are setting specific, legally binding targets for recycled content in plastic products. This policy directly forces manufacturers to invest in advanced recycling technologies and secure reliable supply chains for post-consumer resin (PCR). The household segment is most impacted, with producers of kitchen and drawstring bags reformulating products to meet these mandates, treating compliance as a prerequisite for continued market access in key European markets.
Certification-Driven Procurement
A significant behavioral shift is occurring in institutional purchasing, where procurement decisions increasingly prioritize products with verified environmental certifications. This trend is disrupting traditional sales models based on cost-per-unit, creating an advantage for suppliers offering bags certified by bodies like the Biodegradable Products Institute (BPI). The shift is most visible in North American and European corporate facilities, healthcare, and food service sectors that have public-facing sustainability commitments.
Trash Bags Market Segmentation
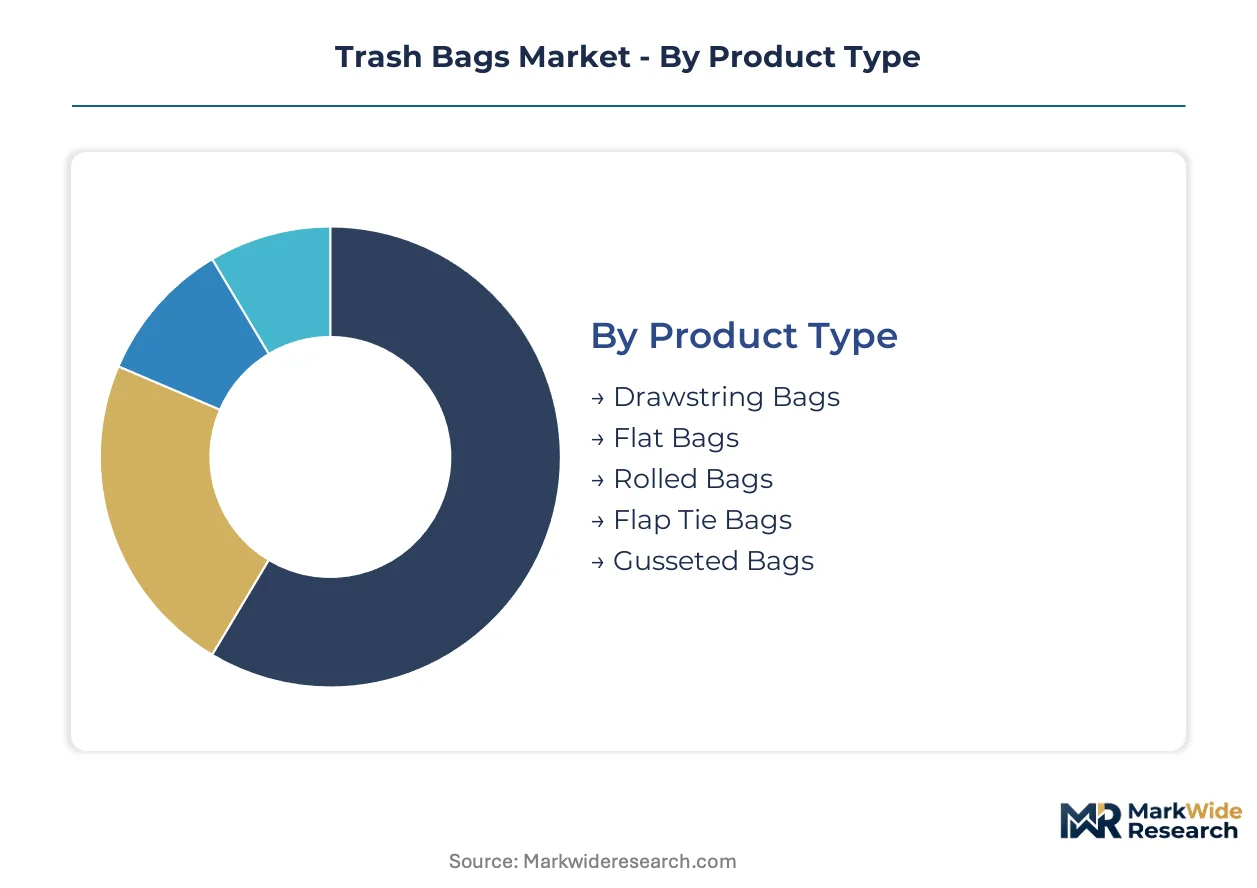
The trash bags market's segmentation reveals diverse needs and procurement strategies across various user groups and product applications. Understanding these distinct segments allows manufacturers to tailor material composition, product design, and distribution approaches effectively.
Product Type:
Trash bag product types dictate their primary distribution channels, influencing consumer access and commercial procurement strategies.
- Drawstring Bags:These bags feature an integrated string for easy closure, often made from LDPE or recycled plastics. Households in North America and Europe drive demand due to convenience.
- Flat Bags:Simple, open-top plastic bags, frequently made from high-density polyethylene for strength. Waste management firms and commercial facilities favor these for bulk collection.
- Rolled Bags:Compactly wound for retail convenience, these are common in supermarkets for household consumers.
- Flap Tie Bags:Incorporate four flaps that tie together, providing a secure closure for domestic waste.
- Gusseted Bags:Feature side folds that expand, increasing capacity for larger waste volumes in industrial settings.
By volume, Flat Bags lead commercial applications. By growth pace, Drawstring Bags are ahead in the household segment.
Material:
Material composition directly impacts a trash bag's performance and suitability for specific waste streams, driving procurement decisions.
- Recycled Plastic:Manufactured from post-consumer recycled (PCR) resins, offering a circular economy solution. Regulations in the EU and US EPA mandates drive adoption.
- Compostable:Certified to break down into organic matter in industrial composting facilities, often made from PLA or PHA. Institutional buyers prioritize these for organic waste collection.
- Low-Density Polyethylene:Flexible plastic offering good puncture resistance, a traditional choice for general waste bags.
- High-Density Polyethylene:Known for strength and thinness, HDPE bags are cost-effective and common in office applications.
- Biodegradable:Designed to decompose over time through natural processes, an alternative to conventional plastics.
The market sees a clear performance-cost trade-off. Sustainability mandates increasingly influence material selection.
End User:
Different end-user segments exhibit distinct volume requirements and performance needs, shaping demand for varied trash bag solutions.
- Households:The largest consumer segment, demanding convenient and durable bags for daily domestic waste. Urbanization in India expands this base significantly.
- Hospitality Providers:Hotels, restaurants, and food service establishments require robust, high-capacity bags. Sector growth directly correlates with higher demand.
- Waste Management Firms:These entities require industrial-grade, large-capacity bags for efficient collection and transport.
- Educational Institutions:Schools and universities use standard bags for general waste, some shifting towards recycled content.
- Commercial Facilities:Offices, retail stores, and other businesses utilize various bag types based on waste volume.
The household sector commands the largest share of consumption. The hospitality sector experiences the fastest expansion in demand.
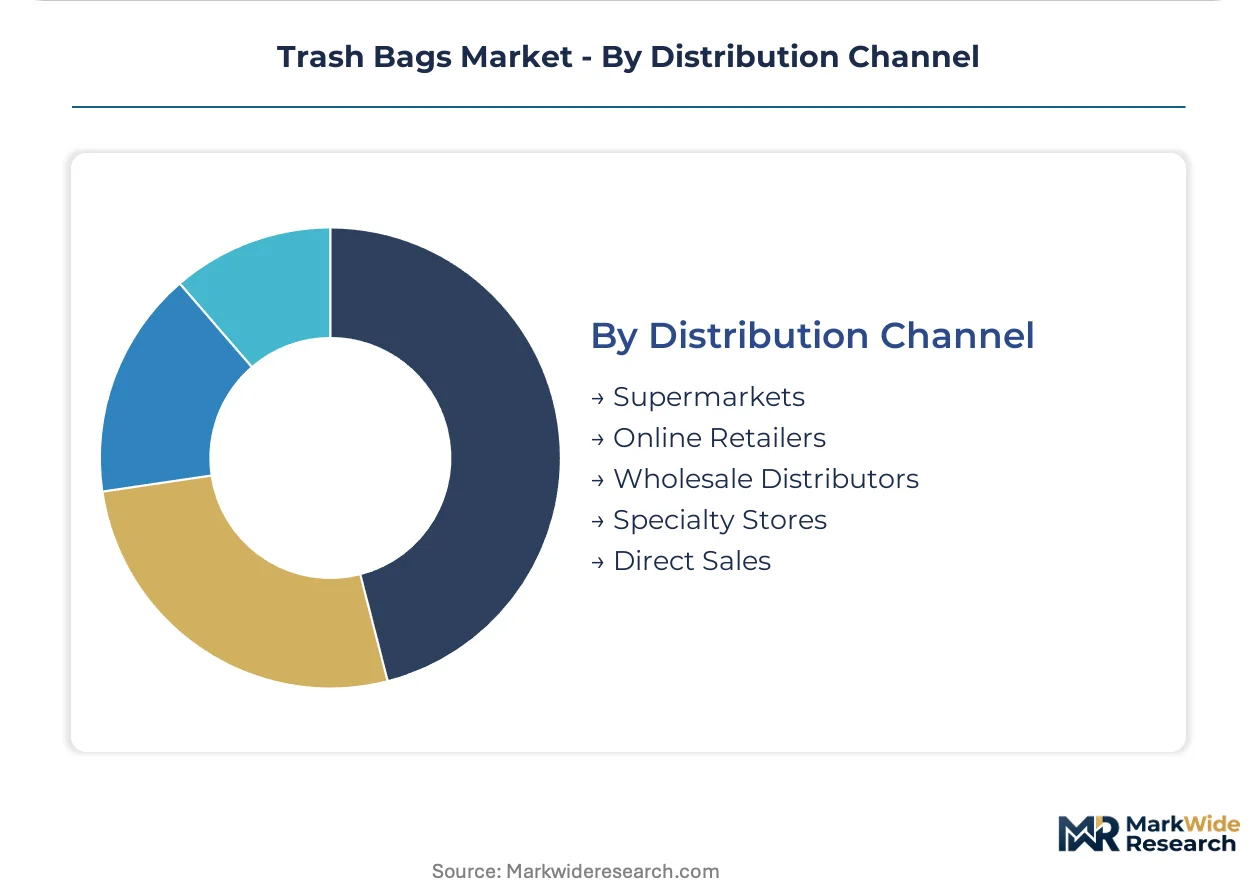
Distribution Channel:
Effective distribution channels determine market penetration and brand visibility for trash bag manufacturers across diverse customer bases.
- Supermarkets:Traditional retail outlets remain a primary channel for household consumers, offering wide product selection. Brand recognition is crucial.
- Online Retailers:E-commerce platforms provide convenience and a broader product range, attracting consumers seeking specialized purchases. This channel is expanding rapidly.
- Wholesale Distributors:These intermediaries supply commercial facilities, hospitality providers, and waste management firms with bulk quantities.
- Specialty Stores:Niche retailers offer premium or eco-friendly trash bag options, targeting conscious consumers.
- Direct Sales:Manufacturers engage in direct sales to large institutional clients, securing long-term contracts.
Supermarkets maintain significant volume leadership. Online retailers demonstrate significant growth in reaching new consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trash bags market exhibits a pricing power asymmetry, with developed economies like the United States often commanding higher-value product segments. Conversely, emerging markets such as India prioritize cost-effectiveness and volume. This dynamic influences material selection and product innovation across different regions.
United States
Household demand for drawstring bags and commercial facility requirements for flat bags drive consumption in the United States. The US EPA guidelines influence manufacturers to increase recycled content in their products. California and New York are seeing increased adoption of compostable solutions for organic waste collection.
India
Rapid urbanization and expanding municipal solid waste management initiatives fuel the demand for standardized trash bags in India. India's BIS sets specific requirements for bag thickness and material composition to curb plastic waste. Major metropolitan areas like Mumbai and Delhi are formalizing waste collection systems, expanding the consumer base.
Germany
Institutional buyers and environmentally conscious consumers drive demand for certified compostable and high-recycled-content bags in Germany. The EU's Single-Use Plastics Directive compels manufacturers to integrate recycled plastics. The Rhine-Ruhr region, with its dense industrial base, focuses on advanced polymer development for sustainable options.
China
Industrial waste management and household convenience products contribute significantly to trash bag consumption in China. National environmental policies, including plastic reduction targets, push for greater recycled content and biodegradable alternatives. Manufacturing hubs in Guangdong and Zhejiang are investing in advanced polymer development for sustainable options.
Brazil
Urban population growth and evolving waste collection services are expanding the market for trash bags in Brazil. Local regulations in states like São Paulo encourage the use of biodegradable bags for organic waste. The southeastern region, including Rio de Janeiro, shows an increased demand for convenient household waste solutions.
Trash Bags Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the trash bags market. The industry exhibits a tiered structure, with large integrated manufacturers competing alongside specialized material innovators. Strategic archetypes include global diversified packaging giants, regional polyethylene film producers, and niche bioplastics developers. Capacity expansion and strategic partnerships are dominant competitive moves among these players.
Within the global diversified packaging segment, Berry Global Group, Inc. and Reynolds Consumer Products Inc. exemplify manufacturers with extensive product portfolios and strong retail presence. Novolex Holdings, LLC, a prominent North American entity, occupies a position across both plastic and paper-based packaging solutions, including certified compostable bags. These companies anchor market share through established supply chains and brand recognition, particularly in the household and commercial sectors. Their strategies often involve leveraging manufacturing scale and distribution networks to meet diverse customer needs.
| Leading Market Players |
|---|
| Reynolds Consumer Products Inc. |
| Sigma Plastics Group, Inc. |
| Berry Global Group, Inc. |
| Mondi plc |
| Pactiv Evergreen Inc. |
| Novolex Holdings, LLC |
| Poly-America |
| International Plastics Inc. |
| Inteplast Group, Ltd. |
Cost & Logistics Intelligence
Large-scale polymer extrusion facilities drive economies of scale in trash bag production, influencing supply concentration and setting competitive price floors. This manufacturing efficiency allows for high-volume output.
Pricing Analysis
Configured-to-order pricing for specialized industrial bags commands a premium over standard, high-volume retail offerings. The dominant pricing model is per-unit transactional, influenced by raw material costs. Price differentiation stems from certification levels, particularly for compostable products, and volume scale for commercial buyers. Pricing softness reflects intense competition in the household segment. Waste management firms are least price-sensitive due to performance requirements, while household consumers exhibit high sensitivity.
Supply Chain Analysis
China and India anchor significant trash bag manufacturing capacity, serving both domestic and export markets. Production relies heavily on virgin polyethylene, recycled plastic resins, and biopolymers like PLA. Commodity price volatility for these polymer feedstocks poses a structural supply chain risk. Distribution runs through a mix of wholesale distributors for commercial clients and supermarkets for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trash bags market is experiencing a high-growth disruption, driven by the rapid development of advanced biodegradable materials. Regulatory mandates for recycled content further accelerate this transformation across product lines.
For Market Incumbents:
Shield core market share against substitution threats from bagless systems by investing in high-performance compostable solutions. Expand advanced recycling capabilities to meet EU's Single-Use Plastics Directive mandates, securing market access. Control distribution channels in North America to counter emerging niche players. Leverage existing manufacturing scale for cost leadership in high-volume segments.
For New Entrants and Emerging Players:
Certification fast-tracks for PHA-based compostable bags offer a clear entry point into institutional procurement. Target the growing hospitality sector in Southeast Asia with premium, certified solutions. Focus on direct-to-consumer subscription models for specialized organic waste bags. This approach bypasses traditional retail barriers and builds direct customer relationships.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized bioplastics developers with proprietary PHA formulations for long-term viability. Focus on companies demonstrating strong intellectual property in marine-degradable polymers. Acquisition targets include niche innovators with established certifications from BPI or TÜV Austria. Widespread municipal adoption of advanced organic waste processing infrastructure is the signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Recycling Capacity | Secures feedstock supply for PCR content mandates and reduces reliance on virgin polymers. |
| Develop PHA-Based Compostable Bags | Addresses demand from institutional buyers and municipalities for fully biodegradable solutions. |
| Expand Direct-to-Consumer Channels | Captures niche segments like organic waste collection and builds brand loyalty. |
| Secure BIS/EU-Compliant Certifications | Ensures market access in India and European Union regions with strict material standards. |
| Form Partnerships with Waste Management Firms | Guarantees bulk procurement contracts and insights into evolving commercial waste streams. |
Research Approach
The analysis maps trash bag product types and end-user segments, each validated through extensive primary interviews with polymer scientists, procurement managers, and waste management executives. Secondary validation leveraged trade association reports, government environmental agency guidelines, and corporate sustainability disclosures. Bottom-up market sizing combined with top-down industry trend analysis ensured data integrity.
Forecast outputs underwent rigorous consistency checks against external industry benchmarks. The analytical framework modeled dimensions including product type, material composition, end-user segment, and regional regulatory impacts. Compound annual growth rates derived from regression analysis of historical data considered urbanization rates and polymer feedstock price forecasts.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory environments; material deviation warrants model refresh. Unforeseen shifts in global trade policies or rapid technological obsolescence pose risk. Outcomes outside this envelope require recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Cassava Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Slider Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Circular Industrial Bags Market