
 UAE Rigid Plastic Packaging Market | 2026-2036
UAE Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Rigid Plastic Packaging Market Analytics
Expatriate polymer engineering talent is bifurcating the competitive landscape, with multinational-trained specialists concentrating in Dubai and Sharjah while smaller emirates face recruitment gaps. Petco Gulf FZE leverages its FZE status to anchor free-zone logistics advantages for re-export volumes across the GCC. Al Amana Plastic Bottles & Containers Manufacturing L.L.C competes through backward integration into preform injection, sustaining margin control amid resin price volatility. Interplast Co. Ltd (Harwal Group) dominates northern emirate manufacturing scale, occupying industrial zones with captive utilities and bulk material handling infrastructure.
UAE rigid plastic packaging comprises thermoformed or injection-molded polymer structures—typically PET, HDPE, or PP—with wall thicknesses exceeding 0.25 millimeters, engineered to protect contents from mechanical damage, moisture ingress, and UV degradation during distribution and retail display. Bottles and containers lead volume throughput, reflecting the emirates' concentration of beverage bottling and edible oil repackaging operations. PET material grades are gaining fastest within pharmaceutical and cosmetics end users, where clarity and barrier specifications displace glass and metal alternatives. Food and beverage end users still absorb the largest share of polypropylene tonnage, though margin pools concentrate in pharmaceutical-grade cleanroom conversion for MOHAP-regulated products.
MOHAP enforces pharmaceutical packaging material traceability through batch-level documentation, while the UAE's technical regulations for food contact plastics align with GCC Standardization Organization (GSO) migration limits and testing protocols. ESMA's UAE System for Conformity Assessment mandates third-party certification for imported rigid containers, shaping supplier qualification timelines and testing costs for new market entrants. Stakeholders must monitor how Abu Dhabi's emerging industrial city clusters and Sharjah's recycling infrastructure investments reshape resin sourcing economics and post-consumer collection obligations.
Market Dynamics
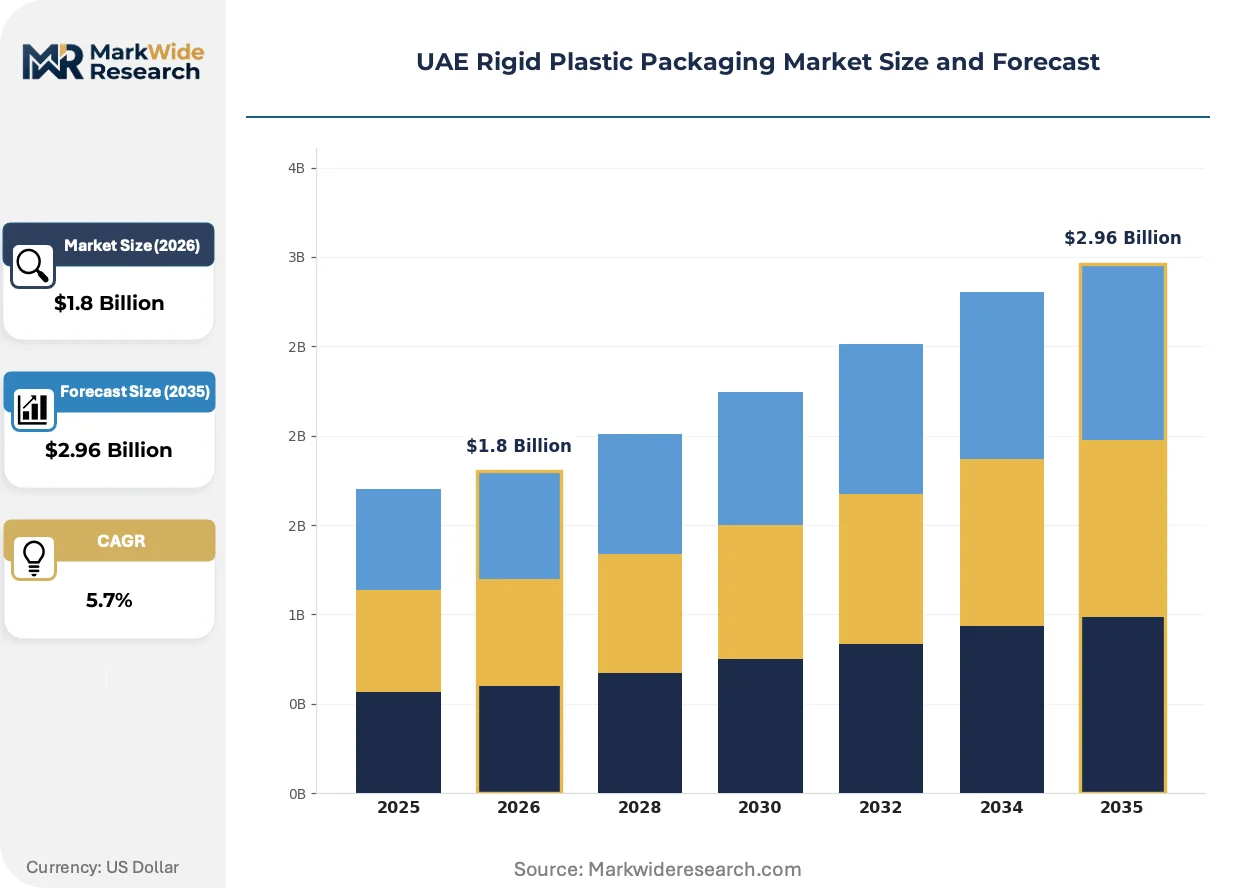
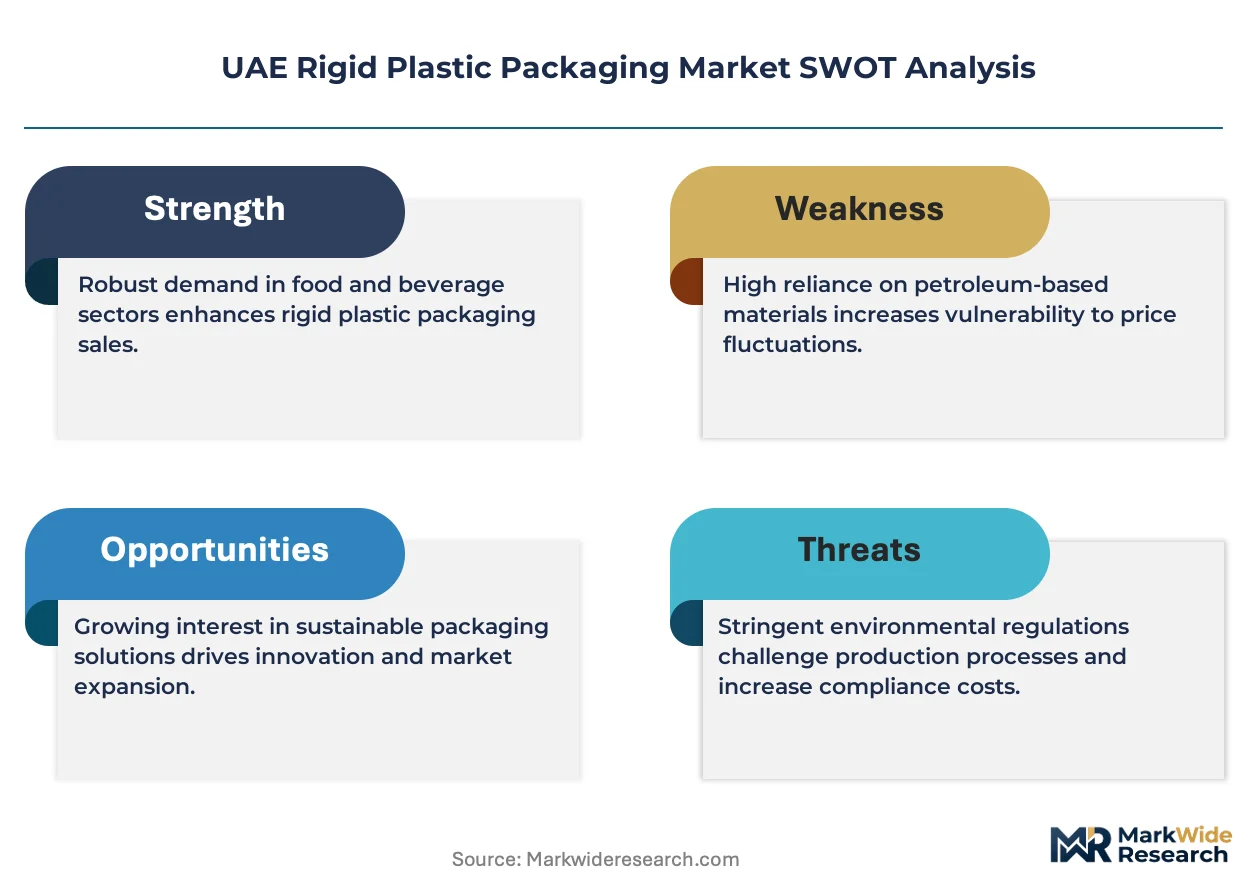
MOHAP's pharmaceutical packaging traceability mandates are compressing supplier qualification timelines while resin price volatility forces converters to renegotiate long-term supply agreements. This regulatory-pressure-plus-input-cost squeeze defines current competitive positioning.
Growth Catalysts
- Food contact compliance alignment:GSO migration limits under ESMA's UAE System for Conformity Assessment are streamlining cross-border trade within GCC states. Standardized testing protocols reduce duplicate certification burdens for exporters.
- Beverage bottling concentration:Dubai's industrial corridor clusters conversion capacity with captive utilities and bulk material handling infrastructure. Proximity to Jebel Ali Port cuts re-export logistics costs for GCC-bound volumes.
- Pharmaceutical-grade PET adoption:Clarity and barrier specifications are displacing glass alternatives in MOHAP-regulated cleanroom conversion. Margins concentrate in batch-documented, traceable supply chains.
Market Restraints
- Resin import dependency:UAE lacks domestic polymer production, exposing converters to freight-rate volatility and Gulf petrochemical supplier pricing power. HDPE and PP grades track naphtha-cracker economics in Saudi Arabia and Qatar.
- Free-zone logistics fragmentation:FZE status advantages concentrate in Dubai and Sharjah, leaving northern emirate manufacturers with higher inland distribution costs. Petco Gulf FZE's re-export hub position is difficult to replicate.
- Mechanical recycling contamination limits:Post-consumer PET flake quality variability constrains food-contact closed-loop applications. ESMA certification requires virgin-equivalent purity that mechanical routes struggle to guarantee.
Strategic Opportunities
- Abu Dhabi industrial city clusters:Emerging conversion zones in KIZAD offer land-cost advantages and proximity to Borouge's polyolefin supply. Resin sourcing economics shift as these facilities reach operational scale.
- Sharjah recycling infrastructure:The emirate's post-consumer collection investments could anchor regional rPET flake supply. Integrated collection-sorting-conversion models align with emerging EPR frameworks.
- Cosmetics barrier packaging convergence:Oxygen-scavenging multilayer PET is displacing glass in premium skincare. Dubai's duty-free retail channel amplifies visibility demands for clarity and decoration.
Industry Challenges
- Polymer engineering talent scarcity:Expatriate specialists concentrate in Dubai and Sharjah, leaving smaller emirates with recruitment gaps. Multinational-trained process engineers command premium compensation packages.
- MOHAP batch-documentation compliance:Pharmaceutical-grade converters face 12-18 month qualification timelines for new resin sources. Material traceability systems require capex in ERP and laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Rigid Plastic Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubs End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, PVC, PET Form: Rigid Containers, Blisters, Trays, Molds |
| Companies Covered | Al Amana Plastic Bottles & Containers Manufacturing L.L.C, Interplast Co. Ltd (Harwal Group), Petco Gulf FZE, Amber Packaging Industries L.L.C., Shubham Plastics FZE, Al Jabri Plastic Factory, Nuplas Industries Ltd., Gulf East Paper and Plastic Industries LLC, Duplas Al Sharq LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Rigid Plastic Packaging Market Evolving Landscape
Lightweighting and barrier enhancement technologies are compressing material intensity per unit while regulatory traceability demands digitize supply chain documentation. These forces reshape converter investment priorities and customer qualification protocols.
Multilayer co-injection PET with oxygen-scavenging additives extends shelf life for sensitive pharmaceuticals and cosmetics. Dubai-based pharmaceutical packagers are adopting these structures fastest, driven by MOHAP stability-testing requirements. Conventional monolayer PET is displacing glass in applications where breakage risk and weight previously blocked conversion.
ESMA's UAE System for Conformity Assessment mandates third-party certification for all imported rigid containers. Testing costs and documentation burdens favor incumbent suppliers with established laboratory relationships. New market entrants face elongated qualification timelines, particularly for food-contact applications requiring migration testing.
Consolidated procurement by multinational beverage bottlers is compressing supplier bases and extending contract durations. Tier-one converters with captive preform injection and in-house mold maintenance are capturing volume from fragmented competitors. This concentration is most visible in Dubai's industrial corridor, where Coca-Cola and Pepsi bottlers have reduced active supplier counts by half over the past five years.
UAE Rigid Plastic Packaging Market Segmentation
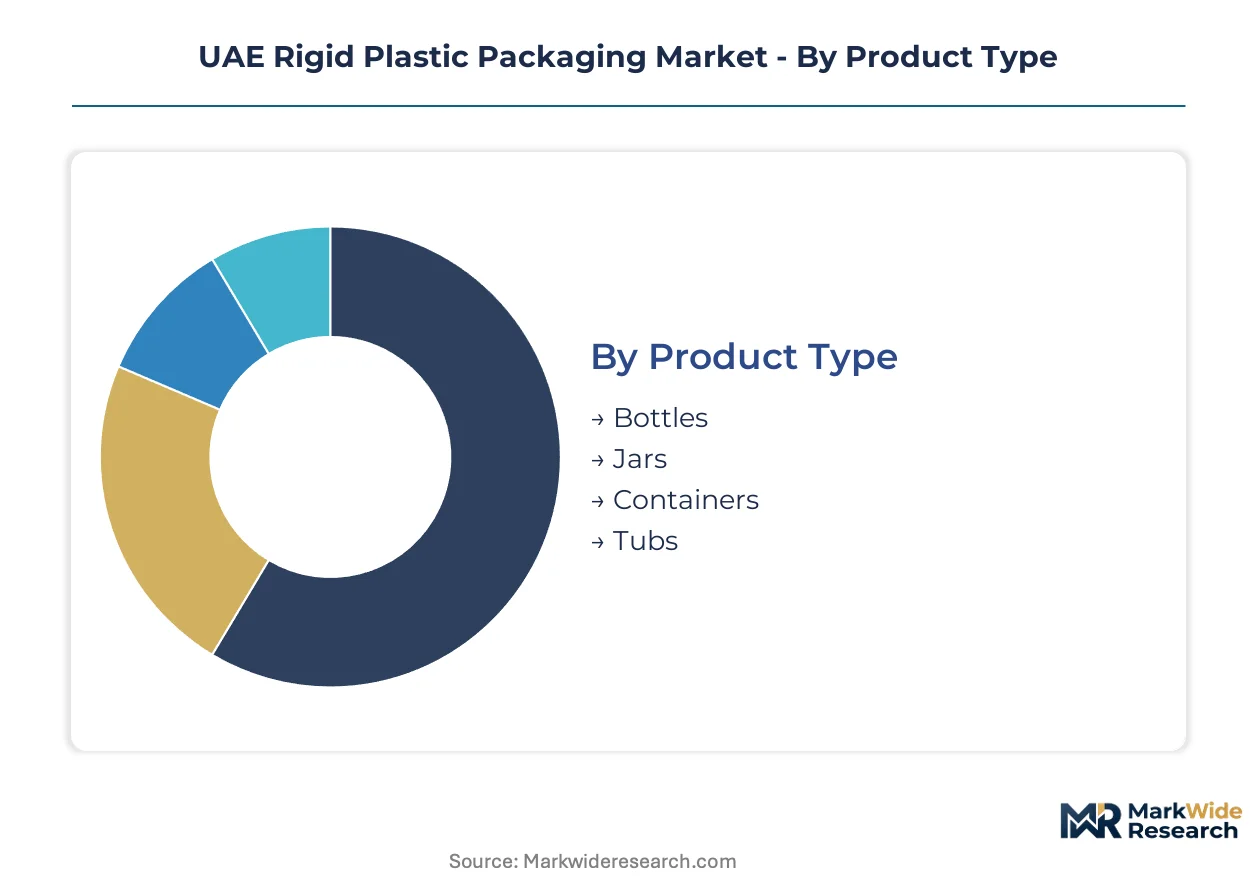
Segmentation in UAE rigid plastic packaging reveals how regulatory pressure and resin economics split margin pools across converter capabilities. Material traceability mandates from MOHAP and ESMA certification requirements create divergent qualification burdens that reshape competitive positioning by product type and end-use.
Product Type:
MOHAP's pharmaceutical packaging standards impose batch-level documentation that favors converters with integrated preform-to-finish capabilities, compressing supplier bases for high-compliance formats.
- Bottles:PET and HDPE blow-molded structures dominate beverage bottling and edible oil repackaging operations clustered in Dubai's industrial corridor. Coca-Cola and Pepsi bottlers have consolidated procurement around tier-one converters with captive preform injection, squeezing fragmented competitors on volume contracts.
- Jars:Wide-mouth PP and PET containers serve spreads, sauces, and cosmetics creams where clarity and decoration visibility matter. Dubai's duty-free retail channel amplifies premium positioning demands for these formats.
- Containers:Injection-molded PP and HDPE boxes and canisters handle dry goods, powders, and household chemicals. Standardized GSO migration testing streamlines cross-border GCC trade for these lower-barrier applications.
- Tubs:Thermoformed PP dairy and foodservice vessels face margin pressure from lightweighting targets and recycled content mandates. Sharjah's emerging recycling infrastructure could anchor regional rPET flake supply for these formats.
Bottles handle the majority of throughput; jars are expanding most quickly on share as cosmetics and premium food brands displace glass.
End User:
Customer procurement concentration splits the market between multinational volume contracts and specialty batch-documented supply chains.
- Food & Beverage:The largest polypropylene absorber, with beverage bottlers and edible oil repackagers driving tonnage through Dubai's industrial corridor. Consolidated procurement has halved active supplier counts over five years.
- Pharmaceuticals:MOHAP-regulated cleanroom conversion commands premium margins through batch-documented, traceable PET supply chains. New resin sources face 12-18 month qualification timelines requiring ERP and laboratory capex.
- Cosmetics:Oxygen-scavenging multilayer PET is displacing glass in premium skincare, with Dubai duty-free visibility demands driving clarity and decoration investment.
- Household Products:HDPE and PP containers for detergents and cleaners compete on resin cost and cycle time, with Borouge's KIZAD proximity shifting sourcing economics for Abu Dhabi-based converters.
Food & Beverage anchors absolute volume; Pharmaceuticals climbs fastest on margin contribution.
Material:
Resin import dependency exposes converters to freight-rate volatility and Gulf petrochemical supplier pricing power, with no domestic polymer production to buffer naphtha-cracker economics.
- PET:Clarity and barrier specifications are displacing glass in pharmaceutical and cosmetics end uses, with multilayer co-injection structures extending shelf life for MOHAP stability requirements. Mechanical recycling contamination limits constrain food-contact closed-loop applications.
- Polypropylene:Dominates food and beverage end uses through injection-molded containers and thermoformed tubs, tracking Saudi and Qatari cracker economics with limited price hedging options.
- Polyethylene:HDPE grades serve household chemicals and beverage closures, with converters renegotiating long-term supply agreements amid resin price volatility.
- PVC:Specialized pharmaceutical blister and medical packaging applications face declining share as PET barrier improvements and regulatory scrutiny reduce adoption.
PET commands the steepest expansion trajectory; Polyethylene maintains the broadest application base across cost-sensitive segments.
Form:
Conversion technology differentiation separates high-volume blow-molding and injection-molding specialists from thermoforming operations serving shorter-run applications.
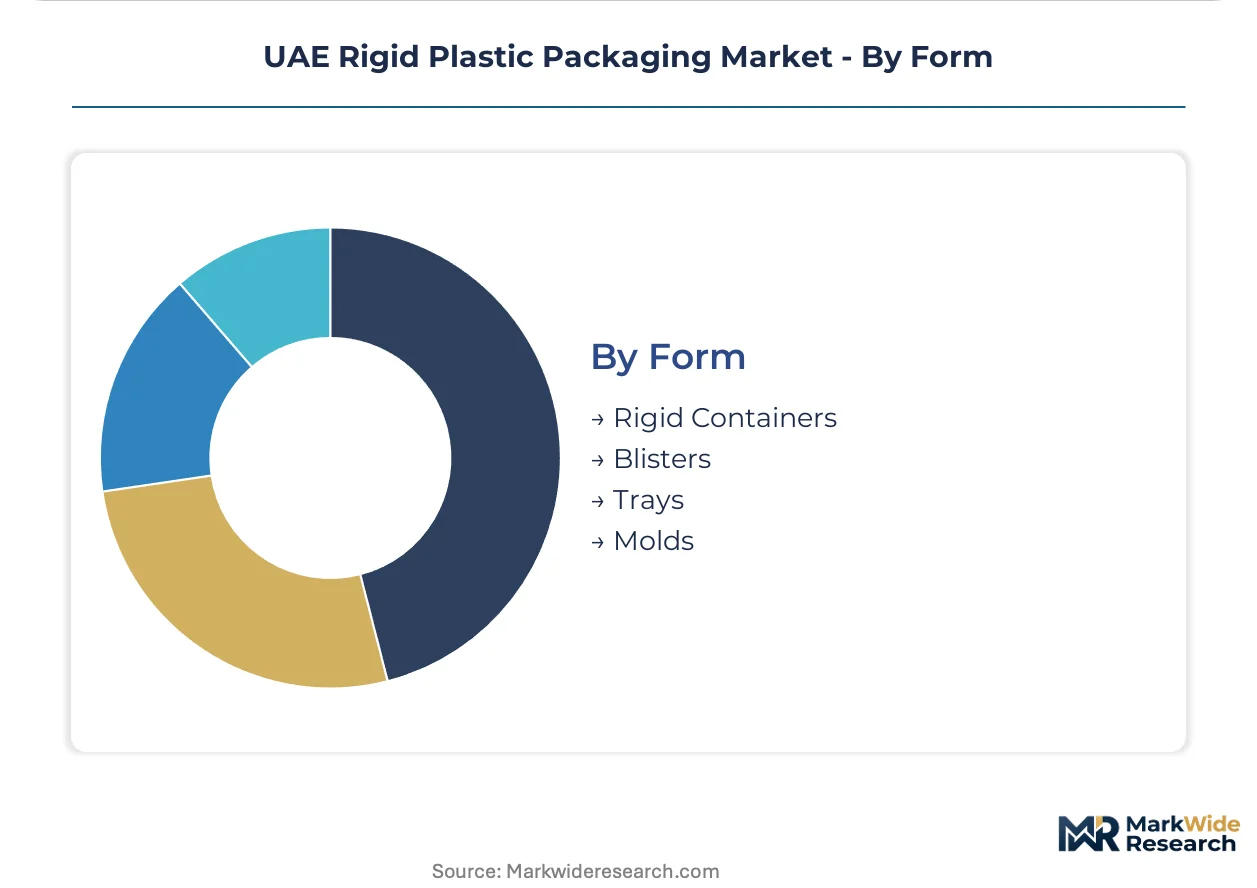
- Rigid Containers:Bottles, jars, and canisters produced through blow-molding, injection-molding, or thermoforming represent the core volume engine, with wall thicknesses exceeding 0.25 millimeters for mechanical protection.
- Blisters:Thermoformed PVC and PET pharmaceutical and consumer goods packaging requires cleanroom conversion for MOHAP-regulated products, concentrating margin in batch-documented supply chains.
- Trays:Foodservice and retail display thermoforms compete on lightweighting and recycled content, with ESMA certification requiring virgin-equivalent purity that mechanical routes struggle to guarantee.
- Molds:Custom injection tooling and blow molds represent captive capabilities for integrated converters, with in-house mold maintenance capturing volume from fragmented competitors.
Rigid Containers processes the dominant share of resin tonnage; Blisters gains fastest on regulatory premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's pharmaceutical packaging standards anchor regulatory gravity in Dubai, where batch-level documentation requirements concentrate compliance-capable converters. Industrial clustering follows logistics infrastructure and free-zone incentives across the emirates.
Dubai
Beverage bottlers and edible oil repackagers drive PET and HDPE throughput through Jebel Ali Port's re-export corridor. ESMA's UAE System for Conformity Assessment mandates third-party certification for imported containers, shaping supplier qualification timelines. Dubai Industrial City clusters conversion capacity with captive utilities, where Coca-Cola and Pepsi bottlers have halved active supplier counts through consolidated procurement.
Abu Dhabi
KIZAD industrial zones offer land-cost advantages and proximity to Borouge's polyolefin supply, shifting resin sourcing economics for emerging converters. The emirate's pharmaceutical manufacturing investments are drawing cleanroom packaging capabilities south from Dubai. Conversion facilities reaching operational scale here will reshape northern emirate competitive positioning.
Sharjah
Post-consumer collection infrastructure investments could anchor regional rPET flake supply for thermoformed foodservice applications. FZE status advantages concentrate free-zone logistics benefits, though re-export hub scale trails Dubai. Integrated collection-sorting-conversion models here align with emerging EPR frameworks.
Northern Emirates
Ajman, Ras Al Khaimah, Fujairah, and Umm Al Quwain face polymer engineering talent scarcity as expatriate specialists concentrate in Dubai and Sharjah. Inland distribution costs run higher without FZE logistics integration. Interplast's Harwal Group operations demonstrate how captive utilities and bulk material handling infrastructure can overcome geographic disadvantage.
UAE Rigid Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into preform injection separating margin-sustainable converters from resin-price-exposed competitors. Market structure reflects procurement consolidation by multinational beverage bottlers and MOHAP's 12-18 month pharmaceutical qualification timelines. Two archetypes dominate: free-zone-anchored re-export specialists and integrated preform-to-finish manufacturers. Competitive moves center on capacity expansion in Abu Dhabi's emerging industrial zones and strategic partnerships for rPET flake supply.
Within the integrated manufacturing tier, Al Amana Plastic Bottles & Containers Manufacturing L.L.C exemplifies backward integration strategies that sustain margin control amid resin volatility. Petco Gulf FZE occupies a position as a free-zone-anchored re-export specialist leveraging FZE logistics advantages. Interplast Co. Ltd represents scale-driven manufacturing anchored in northern emirate industrial zones with captive infrastructure.
| Leading Market Players |
|---|
| Al Amana Plastic Bottles & Containers Manufacturing L.L.C |
| Interplast Co. Ltd (Harwal Group) |
| Petco Gulf FZE |
| Amber Packaging Industries L.L.C. |
| Shubham Plastics FZE |
| Al Jabri Plastic Factory |
| Nuplas Industries Ltd. |
| Gulf East Paper and Plastic Industries LLC |
| Duplas Al Sharq LLC |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month pharmaceutical resin qualification timelines concentrate pricing power with incumbent converters holding active MOHAP batch-documentation systems, while spot-market resin buyers absorb volatility that integrated preform manufacturers buffer through captive supply.
Pricing Analysis
Price spreads between Dubai free-zone converters and northern emirate manufacturers run 8-15% on comparable PET bottle contracts, reflecting FZE logistics subsidies and Jebel Ali Port proximity. Three-tier pricing structure across pharmaceutical-grade certified, food-contact standard, and industrial-economy levels separates margin pools, with MOHAP-regulated cleanroom conversion commanding sustained premiums. Pricing pressure stems from consolidated beverage bottler procurement halving active supplier counts, squeezing mid-tier converters on volume terms. Multinational bottlers show least price sensitivity due to long-term offtake security, while regional edible oil repackagers negotiate hardest on resin pass-through clauses.
Supply Chain Analysis
Strait of Hormuz transit underwrites 90% of UAE resin import volumes, exposing converters to freight-rate spikes and geopolitical disruption risk. Saudi Arabia, Qatar, and Kuwait anchor polyolefin supply through Borouge and SABIC cracker networks, while PET feedstock draws from Asian PTA/MEG producers. Naphtha-cracker economics in Gulf petrochemical complexes tether margin predictability to regional fuel-oil benchmarks. Distribution runs through Dubai's Jebel Ali corridor for GCC re-export, with Sharjah free zones capturing secondary hub scale for northern emirate manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade PET adoption sits at early-cycle penetration against glass incumbents, with MOHAP stability-testing mandates accelerating conversion timelines for oxygen-scavenging multilayer structures.
For Market Incumbents: Compound qualification-capacity advantages by extending batch-documentation systems into cosmetics barrier packaging before specialty chemical multinationals replicate cleanroom infrastructure. Anchor preform injection capacity in Abu Dhabi's KIZAD zones to capture Borouge resin proximity as northern emirate competitors face inland distribution cost handicaps. For New Entrants and Emerging Players: Differentiate on Sharjah-anchored rPET flake integration for thermoformed foodservice applications, where ESMA virgin-equivalent purity requirements currently block mechanical recycling competitors. Target Abu Dhabi pharmaceutical manufacturing investments drawing cleanroom packaging capabilities south from Dubai's saturated corridor, using fast-track MOHAP consulting partnerships as entry credential. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-premium capture play because batch-documented pharmaceutical supply chains concentrate margin in irreplicable qualification timelines rather than commodity conversion scale. Monitor Borouge KIZAD operational ramp as inflection signal for Abu Dhabi-based converters achieving resin cost parity with Dubai free-zone incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Injection | Captive PET supply buffers converters against Saudi-Qatari naphtha-cracker volatility. |
| MOHAP Certification Fast-Track Investment | Twelve-month qualification compression captures pharmaceutical volume from slower competitors. |
| Sharjah rPET Collection-Sorting Integration | Post-consumer flake supply anchors emerging EPR compliance for thermoformed dairy vessels. |
| KIZAD Capacity Expansion | Proximity to Borouge polyolefin shifts sourcing economics for Abu Dhabi-based converters. |
| Oxygen-Scavenging Multilayer Adoption | MOHAP stability requirements displace glass in premium pharmaceutical and cosmetics segments. |
Research Methodology
The analysis maps PET pharmaceutical barrier formats, polypropylene food-contact containers, HDPE household chemical vessels, and thermoformed rPET dairy applications, each validated through converter operations directors, beverage bottler procurement leads, pharmaceutical packaging quality managers, and ESMA certification laboratory heads. Primary fieldwork combined with customs trade data, GCC Standardization Organization technical regulations, MOHAP pharmaceutical packaging guidelines, and Borouge polyolefin supply disclosures enabled bottom-up installation counts and top-down resin consumption triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation by material grade, end-use compliance tier, conversion technology, and emirate-level industrial clustering fed analytical framework construction. CAGRs derived from resin intensity per unit trajectories and end-use demand elasticity modeling, with pharmaceutical PET displacement rates and beverage bottler procurement consolidation pace as key forecast inputs.
Material uncertainties — resin price volatility, MOHAP traceability mandate enforcement intensity, and mechanical recycling contamination limit revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions on qualification timeline stability and GCC cross-border trade friction. Practitioners should keep alternative scenarios live as Abu Dhabi industrial city cluster maturity and Sharjah EPR framework implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market