
 Gusseted Bags Market | 2026-2036
Gusseted Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Gusseted Bags Market Outlook
Food-grade barrier specifications is rotating demand toward higher-performance substrates across the gusseted bags landscape. Sonoco Products Company leverages vertical integration in fiber-based packaging to sustain cost advantages in North American food service channels. ProAmpac anchors its position through specialized high-barrier film technologies for protein and produce applications. Amcor plc dominates flexible packaging R&D intensity with global manufacturing scale that extends across multiple substrate platforms.
Gusseted bags incorporate expandable side or bottom panels that increase volumetric capacity while maintaining stack stability, typically manufactured through blown film extrusion or converted from pre-formed rollstock with heat-sealed seams. The primary commercial purpose centers on maximizing product fill volume per shelf-facing unit in retail and warehouse environments. Polyethylene formulations occupy the largest material share due to cost efficiency and seal integrity, though biodegradable alternatives are gaining fastest traction among European food brands seeking compliance with evolving packaging directives. Stand-up configurations command premium positioning in retail environments where shelf differentiation determines purchase conversion, while wicketed formats sustain volume leadership in automated bakery and produce packing operations.
FDA food contact regulations and EU REACH chemical safety frameworks govern substrate approvals and migration limits across major demand zones, with emerging state-level extended producer responsibility laws in California and New York adding compliance layers for North American suppliers. ISO 22000 food safety management standards increasingly shape qualification requirements for converters serving branded food manufacturers. Stakeholders must monitor material substitution economics as biopolymer scale-up costs converge with regulatory compliance timelines.
Market Dynamics
EU Green Deal packaging waste directives are forcing substrate substitutions across European food packaging supply chains, compressing lead times for biodegradable material qualification while elevating compliance costs for polyethylene-dependent converters.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory recyclability targets and extended producer responsibility schemes in Germany and France are pulling food brands toward certified compostable substrates.
- Automated bakery operations:Wicketed gusseted formats sustain volume leadership in high-speed filling lines across industrial baking facilities in the United States.
- High-barrier film technologies:Modified atmosphere packaging specifications for protein and fresh produce applications are rotating demand toward multi-layer coextruded structures with oxygen scavenging layers.
Market Restraints
- Biopolymer feedstock volatility:PLA and PHA resin prices fluctuate with corn sugar and vegetable oil commodity markets, compressing margin predictability for converters.
- Blown film equipment concentration:German and Italian extrusion machinery suppliers control critical capacity expansion timelines, creating bottlenecks for North American converters seeking scale.
- Migration testing protocols:EU REACH chemical safety frameworks impose multi-month approval cycles for new substrate formulations, delaying product launches.
Strategic Opportunities
- Indian food retail modernization:Organized retail penetration in Maharashtra and Karnataka is creating first-mover advantages for stand-up pouch converters serving branded spice and snack companies.
- California SB 54 implementation:State-level extended producer responsibility mandates are accelerating demand for post-consumer recycled content in flexible packaging ahead of federal timelines.
- Active packaging integration:Convergence of oxygen scavenging films with intelligent freshness indicators opens premium positioning in cold-chain protein distribution.
Industry Challenges
- ISO 22000 auditor scarcity:Qualified food safety management system certifiers concentrate in Western Europe and coastal United States, delaying supplier qualification for emerging market converters.
- Legacy heat-seal line retrofitting:Biodegradable films require modified temperature and pressure profiles, forcing capital expenditure on sealing jaw upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gusseted Bags Market |
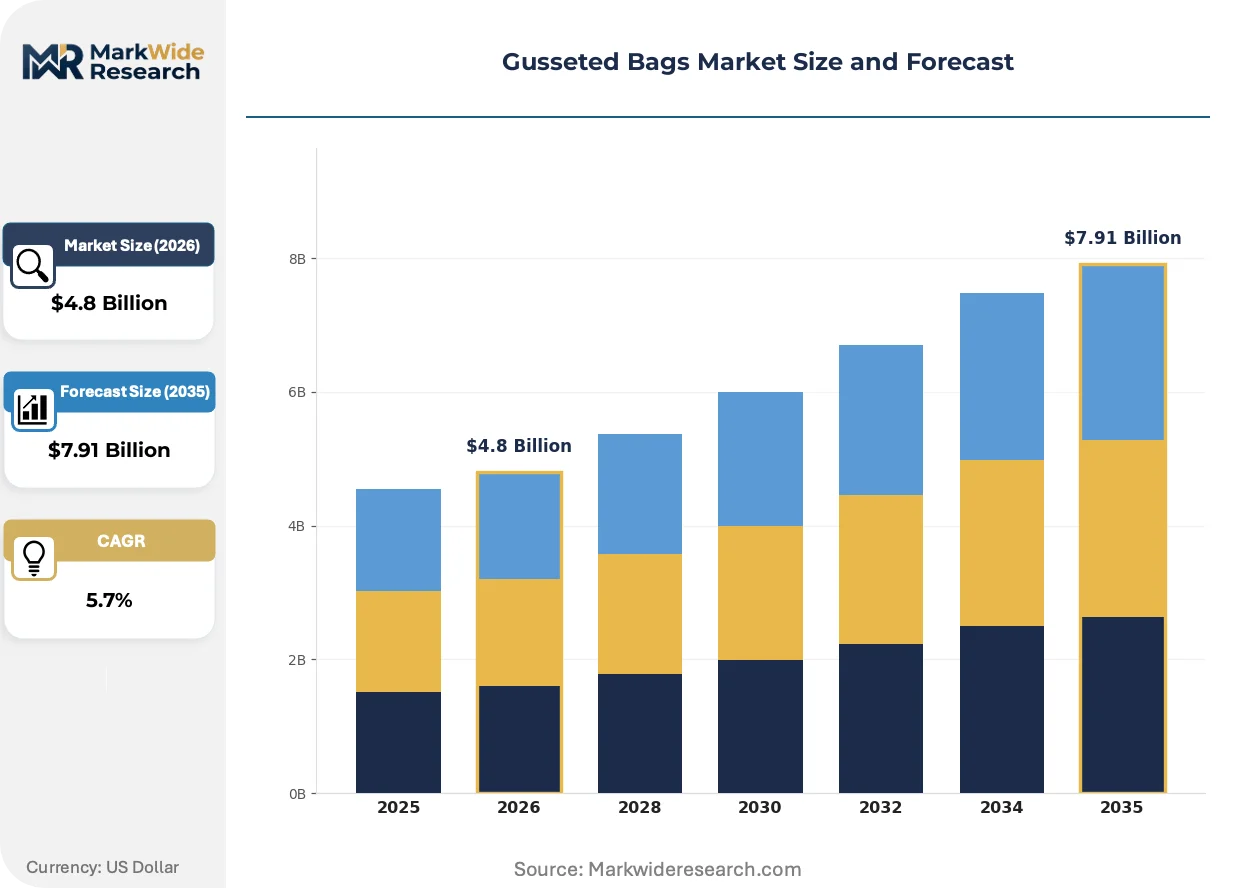
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bag Type: Flat, Wicketed, Stand-Up, Ziplock Material: Polyethylene, Polypropylene, Biodegradable, Paper End User: Food Industry, Retail, Healthcare, E-Commerce Closure Type: Heat Seal, Tape, Zipper, Tie |
| Companies Covered | Sonoco Products Company, ProAmpac, Amcor plc, Huhtamäki Oyj, Sealed Air Corporation, Berry Global Group Inc, Mondi Group plc, Inteplast Group, Novolex Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gusseted Bags Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing development cycles for next-generation barrier substrates while reshaping competitive qualification requirements across food packaging value chains.
Multi-layer coextrusion with nano-clay barrier layers is miniaturizing oxygen transmission rates to below 0.5 cc per square meter per day. Premium meat and cheese packers in the Netherlands and Wisconsin are adopting these structures at replacement cycle pace. The technology is miniaturizing the performance gap between conventional EVOH barriers and emerging bio-based alternatives, accelerating substrate substitution economics.
EU Packaging and Packaging Waste Regulation (PPWR) implementation timelines are mandating recyclability-by-design standards for all flexible packaging placed on the European market by 2030. Industrial converters serving pan-European food brands are restructuring R&D roadmaps to prioritize mono-material PE structures. Protein and dairy applications face the steepest reformulation challenges due to existing high-barrier requirements.
Direct-to-retailer contracting models are displacing traditional distributor-mediated procurement in North American produce packing. Large berry and salad cooperatives in California's Central Valley and Florida's Immokalee region are consolidating volume commitments with specialized converters. This concentration is compressing price negotiation cycles and elevating technical service expectations for traceability and lot control systems.
Gusseted Bags Market Segmentation
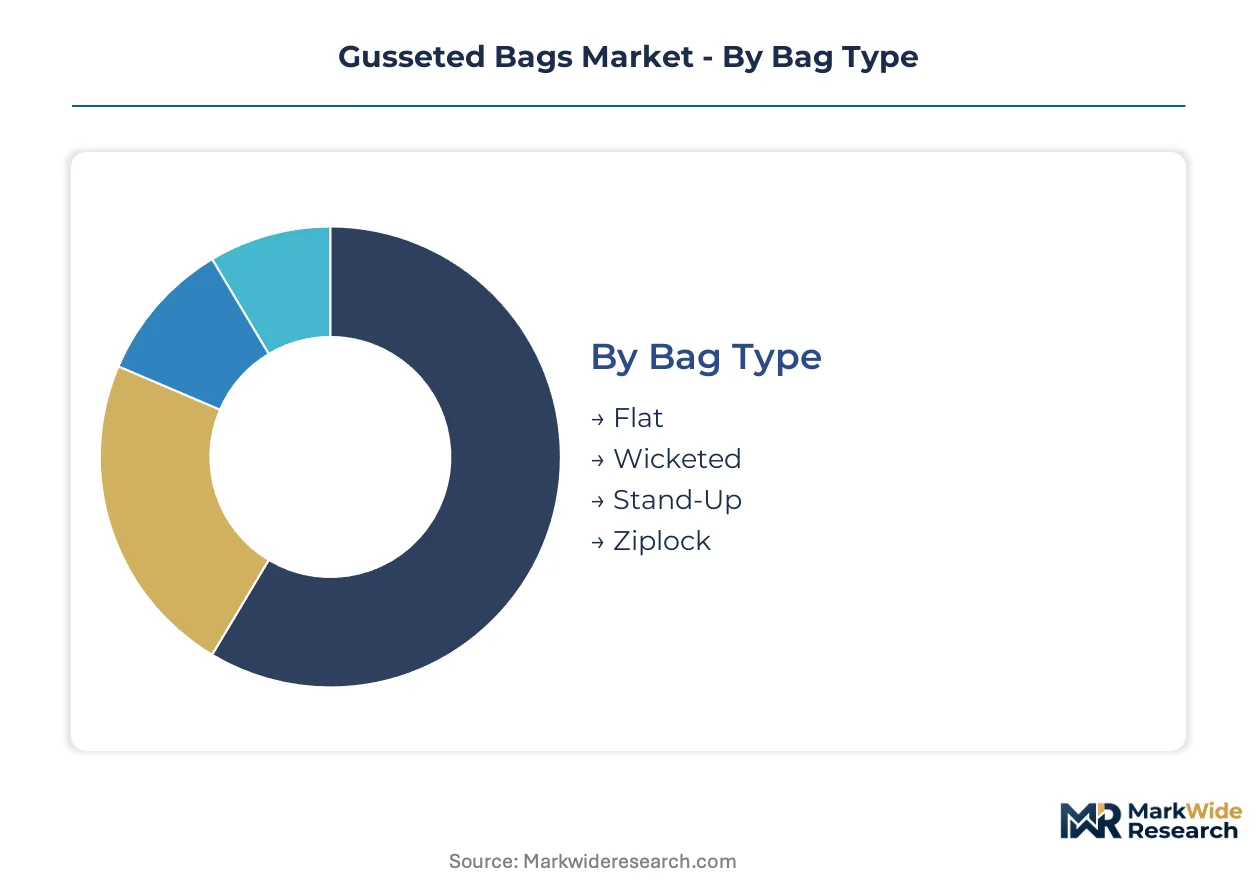
Segmentation in gusseted bags reveals how substrate specifications and closure mechanisms align with distinct regulatory frameworks and operational requirements across food service, retail, and healthcare channels. Material compliance with FDA food contact and EU REACH migration limits creates divergent qualification pathways that reshape converter specialization and customer procurement patterns.
Bag Type:
FDA and EU Green Deal packaging directives impose divergent structural requirements on bag configurations, with recyclability-by-design standards favoring certain formats over others in European versus North American markets.
- Flat:Two-dimensional construction with sealed side gussets maximizes pallet density for bulk ingredient distribution. Industrial bakeries in Wisconsin and frozen food processors in the Netherlands specify flat formats for automated filling lines where speed outweighs shelf presentation requirements.
- Wicketed:Header-punched bundles enable high-speed dispensing on automated bakery and produce packing equipment. California Central Valley berry cooperatives and Florida Immokalee salad processors sustain volume demand through direct-to-retailer contracting that prioritizes throughput over unit differentiation.
- Stand-Up:Bottom gusset geometry creates vertical shelf stability for retail differentiation. Branded spice and snack companies in Maharashtra and Karnataka favor this format as Indian organized retail penetration accelerates.
- Ziplock:Integrated reclosure mechanisms extend product freshness cycles for consumer convenience. Premium cheese and dried fruit packers specify ziplock specifications where repeat purchase loyalty justifies material cost premiums.
Established volume favors Wicketed; emerging adoption favors Stand-Up.
Material:
Cost tier stratification separates commodity resin applications from certified compostable substrates where regulatory compliance timelines compress substitution economics.
- Polyethylene:Blown film extrusion of LDPE and LLDPE formulations delivers cost-efficient seal integrity across high-volume bakery and produce applications. German and French food brands face mounting pressure from EU Green Deal directives to reduce polyethylene dependency despite its dominance in existing equipment footprints.
- Polypropylene:Higher melt strength and clarity specifications serve modified atmosphere packaging for protein and fresh produce where optical properties influence purchase conversion. Dutch meat packers and Wisconsin cheese processors specify cast PP structures for retail-facing applications.
- Biodegradable:PLA and PHA resins derived from corn sugar and vegetable oil feedstocks address compostability mandates. European converters absorb qualification delays from EU REACH migration testing protocols as brands accelerate substitution timelines.
- Paper:Fiber-based substrates with heat-sealable coatings penetrate quick-service and bakery channels seeking plastic reduction credentials. Sonoco Products Company leverages captive pulp supply to sustain cost position in North American food service.
Polyethylene retains volume leadership; biodegradable alternatives are climbing the fastest under regulatory compression.
End User:
Application-specific barrier requirements determine substrate complexity and certification depth across customer segments.
- Food Industry:ISO 22000 food safety management standards govern converter qualification for protein, dairy, bakery, and produce applications where oxygen transmission rates below 0.5 cc per square meter per day preserve shelf life.
- Retail:Shelf differentiation priorities drive stand-up pouch specifications with premium printing and reclosure features. Direct-to-retailer contracting in California and Florida compresses price negotiation cycles and elevates traceability system requirements.
- Healthcare:Sterility and chemical resistance specifications govern medical device and pharmaceutical packaging where FDA validation protocols extend qualification timelines.
- E-Commerce:Dimensional efficiency and damage resistance specifications prioritize puncture-resistant multi-layer structures for direct-to-consumer fulfillment.
Food Industry commands substrate R&D intensity; E-Commerce is gaining share fastest as fulfillment network expansion accelerates format experimentation.
Closure Type:
Customer type segmentation separates industrial automated lines from consumer-facing convenience requirements.
- Heat Seal:Thermal bonding creates hermetic integrity for modified atmosphere packaging in protein and cheese applications where oxygen exclusion determines shelf life. Legacy equipment requires retrofitting for biodegradable film temperature and pressure profiles.
- Tape:Pressure-sensitive adhesive strips balance reclosure convenience with production speed in bakery and snack applications.
- Zipper:Interlocking plastic profiles enable consumer reclosure for multi-use products. Premium positioning in retail environments justifies incremental material cost.
- Tie:Simple twist or clip mechanisms serve bulk produce and industrial ingredient channels where lowest unit cost prevails.
Heat Seal dominates industrial throughput; Zipper commands premium positioning in retail conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export high-barrier film structures to Dutch meat packers and French dairy processors, establishing a trade corridor that channels technical specifications across the Rhine-Ruhr industrial basin into Benelux food manufacturing clusters.
Germany
Industrial bakeries in North Rhine-Westphalia and Bavaria sustain wicketed format demand for automated filling lines. EU Green Deal packaging waste directives mandate recyclability-by-design standards by 2030, pressuring converters in the Rhine-Ruhr region to accelerate mono-material PE qualification timelines.
United States
California Central Valley berry cooperatives and Florida Immokalee salad processors drive wicketed gusseted bag volume through direct-to-retailer contracting. California SB 54 extended producer responsibility mandates accelerate post-consumer recycled content requirements ahead of federal timelines, reshaping converter procurement in the Central Valley.
France
Premium cheese packers in the Auvergne-Rhône-Alpes region specify cast polypropylene structures for retail-facing modified atmosphere applications. ANSM chemical safety frameworks and EU REACH migration testing protocols impose multi-month approval cycles on new substrate formulations, delaying product launches from converters near Lyon.
Netherlands
Dutch meat packers adopt nano-clay barrier layers with oxygen transmission rates below 0.5 cc per square meter per day for protein preservation. ECHA chemical safety oversight and EU Packaging and Packaging Waste Regulation implementation compress lead times for biodegradable material qualification across Rotterdam-area converting facilities.
India
Organized retail penetration in Maharashtra and Karnataka creates first-mover positioning for stand-up pouch converters serving branded spice and snack companies. FSSAI food safety standards and BIS certification requirements govern substrate approvals, while Mumbai and Bangalore industrial zones concentrate technical service capabilities for traceability systems.
Gusseted Bags Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and R&D scale, producing a tiered structure where publicly traded packaging conglomerates anchor global manufacturing footprints alongside regional converters serving single-country demand. Three archetypes dominate: vertically integrated fiber-based specialists, high-barrier film technology developers, and scale-driven flexible packaging conglomerates with multi-substrate platforms. Competitive moves concentrate on backward integration into captive resin supply and geographic expansion through distributor displacement in direct-to-retailer produce channels.
Within the scale-driven tier, Amcor plc and Mondi Group plc exemplify publicly traded conglomerates with global manufacturing reach, while Sonoco Products Company represents North American fiber-based integration. ProAmpac occupies a position among specialized high-barrier film developers serving protein and produce applications. These three anchors illustrate how R&D intensity and substrate diversification separate premium positioning from commodity volume competition.
| Leading Market Players |
|---|
| Sonoco Products Company |
| ProAmpac |
| Amcor plc |
| Huhtamäki Oyj |
| Sealed Air Corporation |
| Berry Global Group Inc |
| Mondi Group plc |
| Inteplast Group |
| Novolex Holdings LLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day resin qualification cycles in European converting facilities compress pricing power for biodegradable substrate adopters while elevating premiums for polyethylene suppliers with legacy equipment compatibility. This lead-time asymmetry between certified compostable and conventional material pathways concentrates margin capture among German and Italian extrusion machinery holders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across wicketed format procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated heat-seal specifications from commodity bakery applications. Cost compression in biodegradable tiers intensifies because PLA and PHA feedstock volatility transfers directly to converter margins. Automated bakery operations in Wisconsin and California exhibit highest price sensitivity; premium cheese packers in the Auvergne-Rhône-Alpes region show least sensitivity due to shelf-life performance requirements.
Supply Chain Analysis
Sixty-day inventory positions for multi-layer coextruded films reflect dependency on German and Italian blown film equipment suppliers controlling critical capacity expansion timelines. Raw material sourcing draws from polyethylene resin producers in the United States and Germany, nano-clay additive suppliers in the Netherlands, and PLA feedstock processors in Thailand. Single-source vulnerability concentrates in extrusion machinery spare parts and specialized heat-seal coating chemistries. Distribution runs through direct-to-retailer contracting models displacing traditional distributor mediation in North American produce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for traceability and lot control systems expand faster than substrate hardware sales as California berry cooperatives and Florida salad processors consolidate volume commitments with specialized converters.
For Market Incumbents: Shield market position by accelerating backward integration into captive resin supply for post-consumer recycled content qualification ahead of California SB 54 implementation timelines. Prioritize ISO 22000 auditor certification capacity in Mumbai and Bangalore industrial zones to capture Indian organized retail penetration. Biopolymer scale-up cost convergence with regulatory compliance timelines threatens polyethylene-dependent converters with stranded equipment assets. For New Entrants and Emerging Players: Anchor in Maharashtra and Karnataka stand-up pouch demand serving branded spice and snack companies where FSSAI food safety standards create qualification barriers for unestablished competitors. Target wicketed format retrofit services for legacy heat-seal lines requiring modified temperature and pressure profiles for biodegradable films. Go-to-market angle: technical service bundling with traceability system integration. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU Green Deal packaging waste directives and state-level extended producer responsibility mandates compress substitution economics toward mono-material and certified compostable substrates. Acquisition target archetype: specialized high-barrier film developers with protein and produce application expertise and existing EU REACH migration testing protocol approvals. Signal to watch: California SB 54 enforcement intensity and post-consumer recycled content verification system deployment pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive post-consumer recycled content secures California SB 54 compliance ahead of competitor qualification timelines. |
| High-Barrier Film Technology Licensing | Nano-clay oxygen transmission specifications below 0.5 cc per square meter per day command premium positioning in Dutch meat packing. |
| Direct-to-Retailer Contracting Expansion | Volume consolidation with Central Valley berry cooperatives compresses price negotiation cycles and elevates technical service requirements. |
| Biodegradable Material Qualification Acceleration | EU REACH migration testing protocol completion opens German and French market access before 2030 recyclability-by-design mandates. |
| ISO 22000 Auditor Capacity Buildout | Certifier presence in Mumbai and Bangalore industrial zones enables faster supplier qualification for Indian food brand customers. |
Study Parameters
Desk research of trade association publications, customs and trade flow databases, and regulatory filing repositories preceded structured interviews with flexible packaging converters, food brand procurement directors, and extrusion machinery suppliers. Primary fieldwork with plant managers at industrial baking facilities and produce packing cooperatives combined with secondary validation from FDA food contact substance notifications and EU ECHA chemical safety dossiers. Bottom-up volume modeling across bag type, material, and end-user segments triangulated against top-down macroeconomic drivers.
Variance decomposition across substrate substitution scenarios, regulatory compliance timeline assumptions, and automated packaging equipment penetration rates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include bag configuration, material compliance tier, closure mechanism, and end-use application intensity. CAGRs derived from regression-based demand elasticity estimates incorporating protein and produce packaging specification evolution. Industry-specific forecast inputs encompass EU Packaging and Packaging Waste Regulation implementation pace and Indian organized retail square footage expansion.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and biopolymer feedstock cost convergence assumptions; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Counter Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Leno Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Bulk Tote Dumpers Market