
 Side Weld Bags Market | 2026-2036
Side Weld Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Side Weld Bags Market Outlook
EU Packaging and Packaging Waste Regulation is restructuring demand toward mono-material polyethylene constructions that simplify recycling streams. WB Packaging Ltd leverages vertical integration across extrusion and conversion to sustain cost discipline in standard bag volumes. Bison Bag Co., Inc anchors its position through specialized heavy-duty formats for industrial end users. CPS Flexible Ltd differentiates via custom print capabilities that serve branded retail channels.
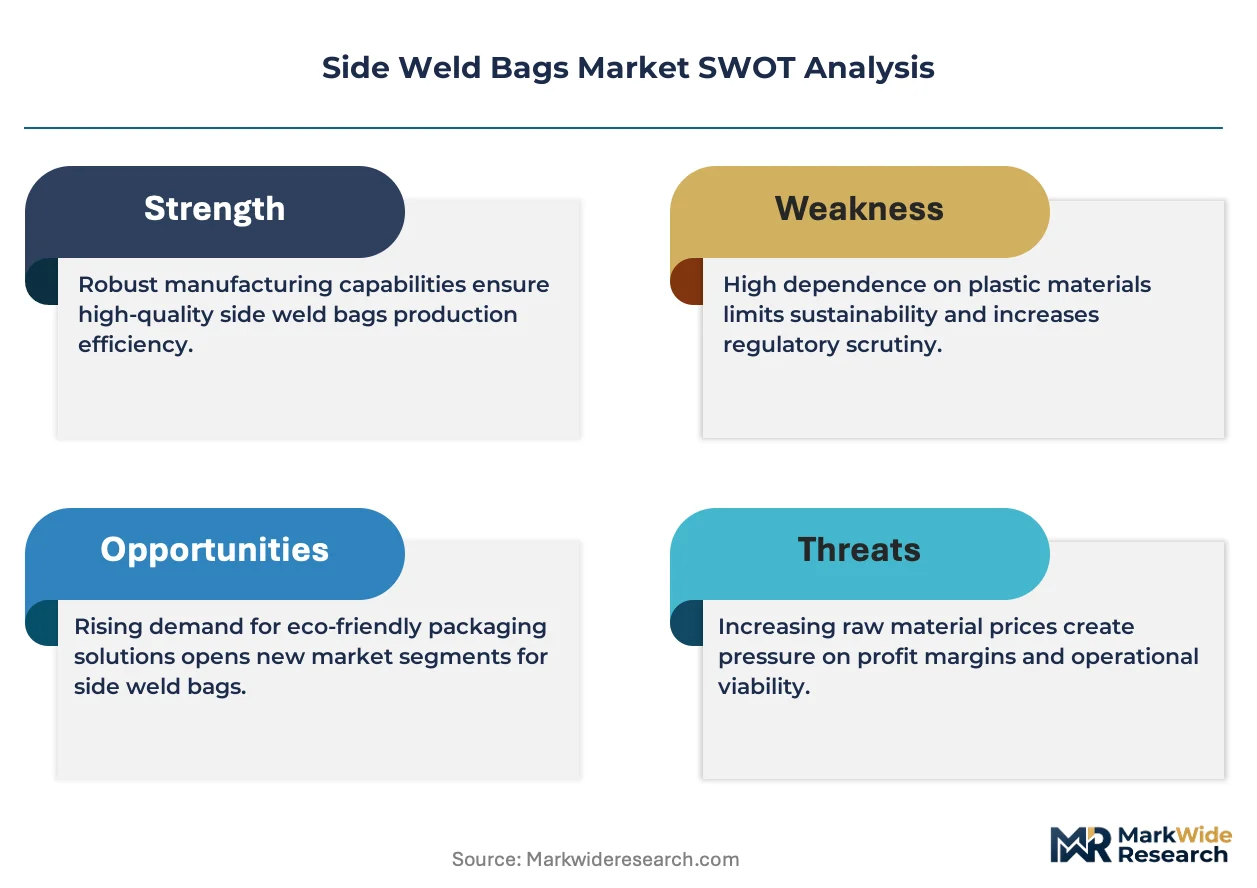
Side weld bags are thermally sealed pouches formed by welding opposite edges of a flat film or sheet, typically produced in thicknesses from 0.5 to 6 mil depending on load-bearing requirements. The process creates clean gusseted or flat profiles used for containment, protection, and display across consumer and industrial applications. Polyethylene dominates material selection for cost-sensitive food service and retail applications, while polypropylene gains traction in pharmaceutical barrier applications where clarity and chemical resistance command premium positioning. Biodegradable bags represent the fastest-expanding product type as converter R&D shifts toward certified compostable resins, though heavy-duty segments retain the deepest margin pools due to specification complexity and lower price elasticity.
FDA food-contact regulations govern polyethylene and polypropylene formulations serving US food service and retail channels, while REACH compliance shapes material declarations for European export-bound production. ECHA restrictions on persistent organic pollutants increasingly filter substrate choices for converters serving multinational brand owners. The EU Green Deal's packaging recyclability targets will tighten compliance burdens before 2030, pressuring mid-tier converters to certify closed-loop compatibility. Stakeholders must monitor emerging state-level extended producer responsibility frameworks in the US and assess whether backward integration into resin compounding or partnerships with certified recyclers offers more durable cost protection.
Market Dynamics
EU Packaging and Packaging Waste Regulation is forcing converters to redesign multi-layer laminates into recyclable mono-material polyethylene structures, compressing margins for mid-tier processors while rewarding extrusion-integrated specialists.
Growth Catalysts
- EU Green Deal recyclability mandates:The EU Green Deal's packaging targets are accelerating demand for certified mono-material polyethylene bags that simplify closed-loop recovery systems across German and French retail channels.
- Food service portion-control conversion:North American quick-service restaurants are adopting pre-sized side weld formats to reduce labor costs and standardize inventory management across franchise networks.
- Industrial heavy-duty specification complexity:German automotive and machinery exporters are specifying custom thickness and seal-strength combinations that lock in multi-year supply contracts with qualified converters.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings transmit directly to polyethylene resin costs, squeezing converter margins on standard food-service volumes where pass-through clauses face buyer resistance.
- Mono-material technical barriers:Current polyethylene formulations struggle to match oxygen and moisture barrier performance of legacy multi-layer structures in pharmaceutical and premium food applications.
- ECHA persistent organic pollutant restrictions:REACH compliance declarations are filtering substrate choices for converters serving multinational brand owners with cross-border distribution requirements.
Strategic Opportunities
- Certified compostable resin certification:TÜV Austria and BPI certification pathways are opening premium positioning for converters that achieve industrial and home compostable validation ahead of 2030 landfill diversion targets.
- Pharmaceutical barrier clarity applications:Polypropylene's chemical resistance and optical properties are creating specification opportunities in unit-dose pharmaceutical packaging where polyethylene clarity falls short.
- Extended producer responsibility frameworks:Emerging state-level EPR legislation in California and New York is creating first-mover advantages for converters with verified post-consumer recycled content integration capabilities.
Industry Challenges
- Extrusion-to-conversion skill gaps:Mono-material blown film optimization requires polymer science expertise that legacy workforce development programs have not addressed, constraining qualified technician supply.
- Certification timeline compression:EU Green Deal packaging recyclability deadlines are forcing simultaneous requalification of resin formulations, seal technologies, and print adhesives within compressed validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side Weld Bags Market |
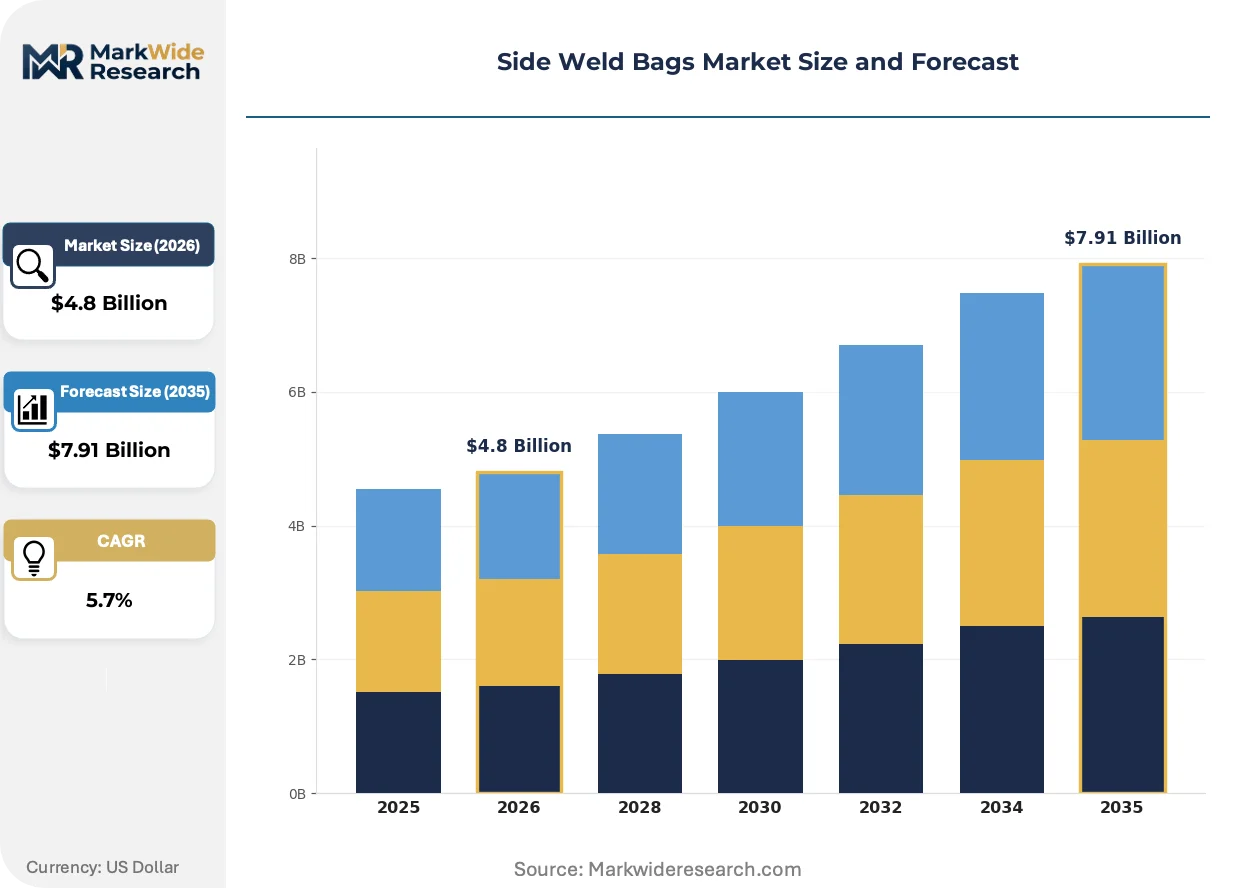
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Custom Bags, Heavy-Duty Bags, Biodegradable Bags Material: Polyethylene, Polypropylene, Paper, Composites End User: Retail, Food Service, Pharmaceuticals, Electronics Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | WB Packaging Ltd, CPS Flexible Ltd, Bison Bag Co., Inc, The Robinette Company, Sideweld Industries Inc, Pebal S.R.O, RJH Plastics, Vitra NV, A-ROO Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side Weld Bags Market Strategic Shifts
Converter R&D investment is concentrating on three vectors: material science breakthroughs that preserve performance in simplified structures, regulatory compliance automation, and buyer procurement model transformation that rewards specification partnerships over transactional sourcing.
High-clarity metallocene polyethylene is integrating advanced catalyst technology to deliver polypropylene-grade optical properties while retaining polyethylene's sealability and cost structure. Pharmaceutical contract packagers in Germany and Switzerland are qualifying these resins for unit-dose applications at accelerated validation timelines. The technology is integrating premium positioning into commodity resin categories, compressing the historical clarity-performance trade-off that segmented material selection.
REACH Article 33 substance disclosure requirements are extending downstream liability to converters serving EU-bound production, forcing systematic supply chain audit protocols. The regulation is restructuring raw material procurement relationships toward certified resin streams with pre-validated compliance documentation. Specialty pharmaceutical and organic food segments are most affected, with buyers now mandating full material passports as contract preconditions.
Brand-owner procurement departments are consolidating specification authority from regional plant managers to centralized sustainability offices, unbundling technical and environmental compliance vetting from price negotiation. Industrial distributors serving mid-market food processors are losing influence to direct converter relationships that offer co-development services and regulatory filing support. The shift is most visible in German and Benelux retail channels where private-label sustainability commitments require supply chain transparency guarantees.
Side Weld Bags Market Segmentation
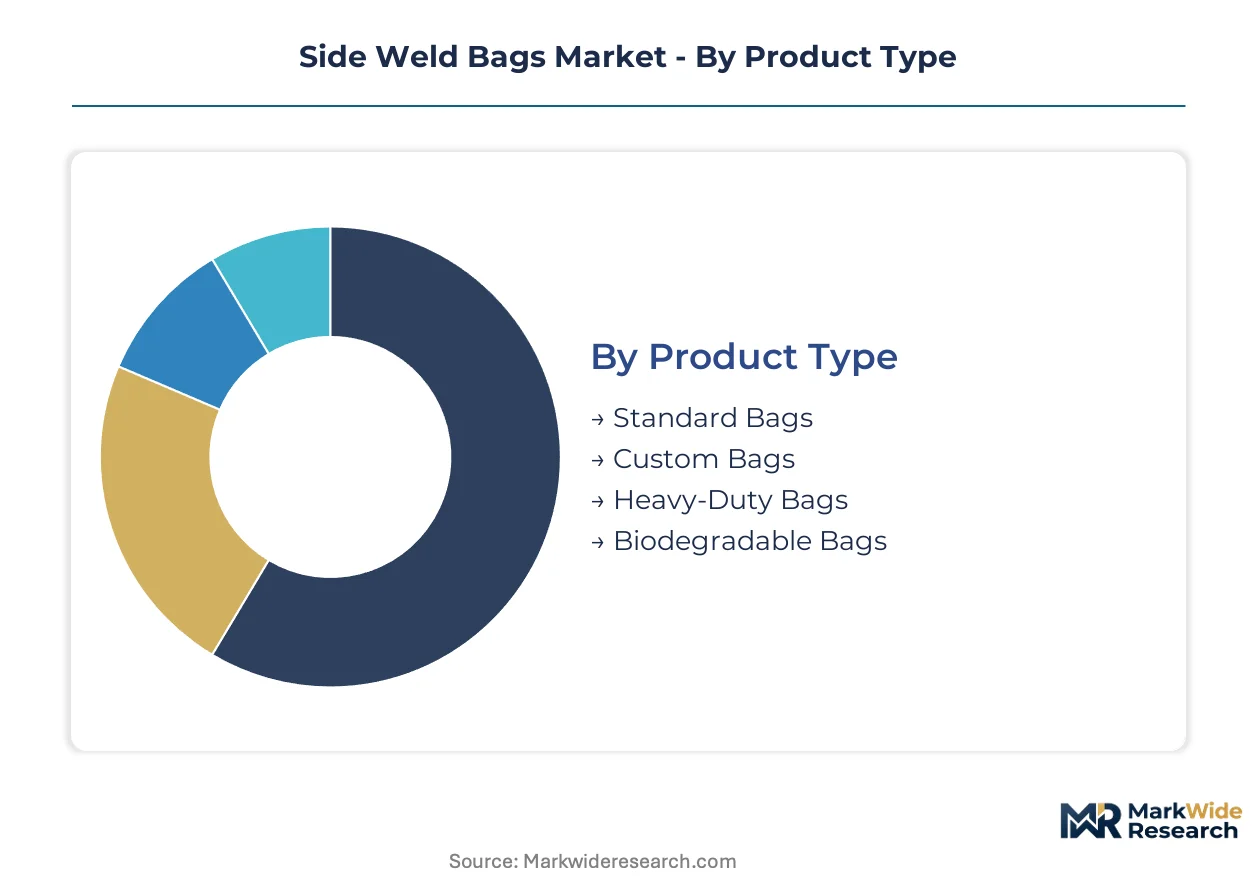
Side weld bag specifications diverge sharply across end-use requirements, with material selection and thickness tolerances determining converter capability positioning. Procurement patterns increasingly segment by sustainability certification tier rather than pure unit economics, restructuring supplier relationships across food service and pharmaceutical channels.
Product Type:
Upgrade cycles in side weld packaging concentrate where regulatory deadlines force material requalification, compressing converter validation timelines and favoring integrated extrusion specialists.
- Standard Bags:These 0.5-2 mil polyethylene formats dominate high-volume food service and retail applications where cost minimization overrides performance differentiation. Quick-service restaurants in the US specify these for portion-control applications, with franchise networks consolidating procurement around approved vendor lists that lock out smaller converters.
- Heavy-Duty Bags:Thickness ranges from 3-6 mil with reinforced seal geometries designed for industrial containment and automotive parts packaging. German machinery exporters specify custom formulations with multi-year qualification requirements, creating sticky supplier relationships that resist price-based displacement.
- Custom Bags:Print-integrated and dimensionally specialized formats serving branded retail channels with shorter run lengths and higher margin structures.
- Biodegradable Bags:Certified compostable resins gaining traction in EU markets where landfill diversion mandates accelerate specification shifts.
Standard bags sit at the top of the volume ranking, with biodegradable bags climbing the fastest.
Material:
Cost tier stratification in resin selection separates commodity polyethylene volumes from premium polypropylene positioning in barrier-sensitive applications.
- Polyethylene:Low-density and linear low-density variants constitute the baseline material for cost-sensitive food service and retail applications, with metallocene catalyst grades now delivering clarity improvements that encroach on polypropylene territory. FDA food-contact compliance requirements govern formulation selection for US-bound production.
- Polypropylene:Superior optical clarity and chemical resistance command premium positioning in pharmaceutical unit-dose packaging where moisture barrier performance is non-negotiable. Swiss and German contract packagers specify these resins for accelerated validation timelines.
- Paper:Fiber-based alternatives serving sustainability-focused retail channels with limited moisture resistance.
- Composites:Multi-material laminates facing regulatory pressure under EU recyclability mandates.
Polyethylene dominates absolute volume, while polypropylene gains share fastest in premium pharmaceutical applications.
End User:
Application-specific performance requirements segment converter capabilities across food contact, barrier, and static-control specifications.
- Food Service:Pre-sized portion-control formats reduce labor costs across North American quick-service franchise networks. Standardized inventory management drives consolidation toward converters with national distribution footprints and regulatory filing support.
- Pharmaceuticals:Unit-dose and bulk API packaging demand validated barrier performance with full material passport documentation. REACH Article 33 disclosure requirements filter supplier qualification toward certified resin streams.
- Retail:Private-label sustainability commitments in German and Benelux channels require supply chain transparency guarantees.
- Electronics:Static-dissipative and moisture-barrier specifications for component protection.
Food service anchors volume demand, with pharmaceuticals expanding most quickly on regulatory compliance premiums.
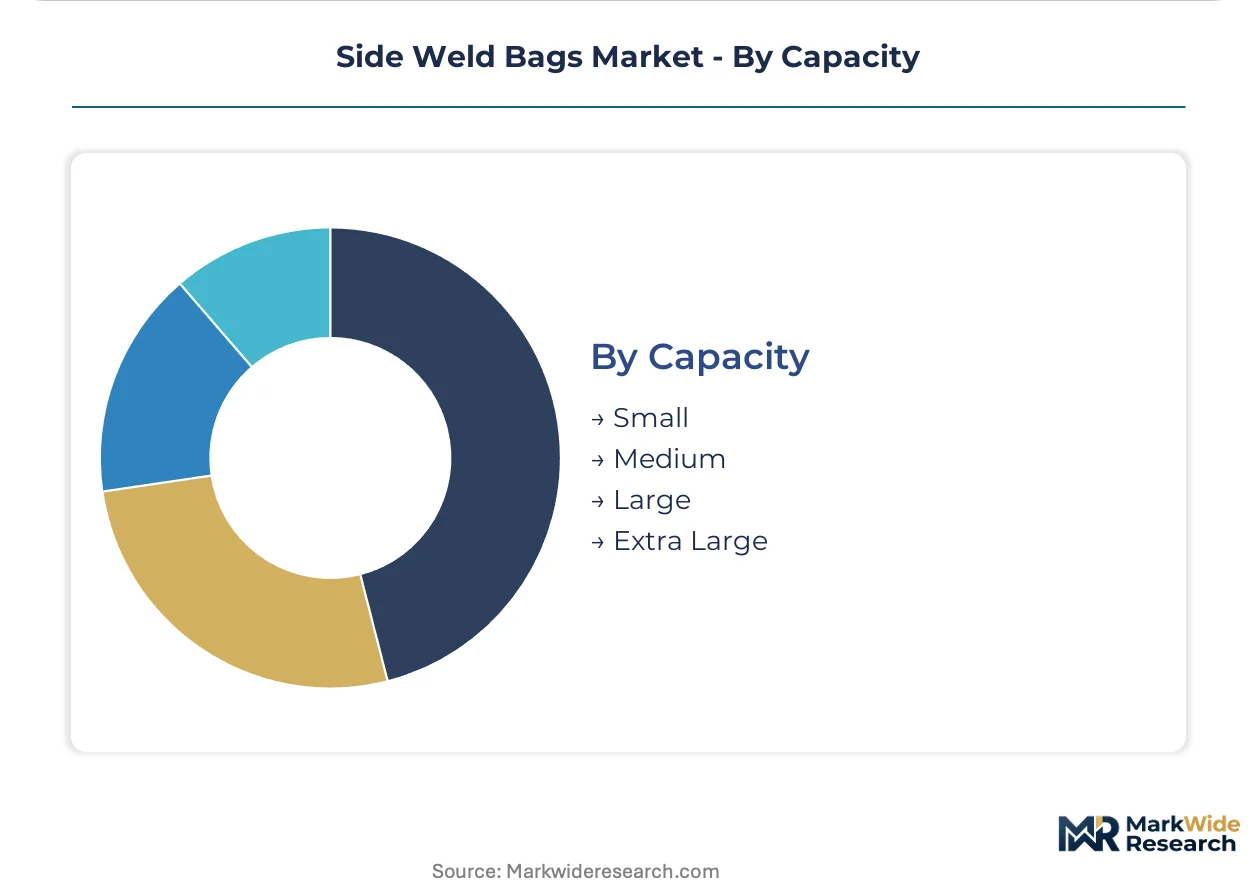
Capacity:
Volume scale differentiation in bag dimensions correlates with end-use automation requirements and handling economics.
- Small:Unit-dose and sample formats for pharmaceutical and cosmetic sampling applications.
- Medium:Standard retail and food service portion sizes with highest SKU proliferation.
- Large:Industrial component and bulk ingredient packaging with thickness scaling.
- Extra Large:Pallet cover and bulk containment applications with specialized seal-strength requirements.
Medium capacity formats command the deepest SKU portfolios, with extra large specifications gaining traction in automated fulfillment centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Side weld bag manufacturing originated in post-war Germany's industrial packaging corridor, where automotive and machinery exporters demanded standardized containment formats. The technology diffused through Western European converter networks before establishing production footholds in North American food service markets and Asian export manufacturing zones.
United States
Quick-service restaurant chains drive specification volume for pre-sized portion-control formats across franchise networks. FDA food-contact regulations govern polyethylene formulation compliance for domestic food service channels. Chicago and Dallas-Fort Worth host converter clusters serving national distribution requirements with integrated extrusion capabilities.
Germany
Automotive and machinery exporters specify custom heavy-duty formats with multi-year qualification protocols that resist supplier displacement. EU Green Deal packaging recyclability mandates accelerate mono-material polyethylene redesign across converter operations. The industrial packaging corridor stretching from Stuttgart to Munich concentrates specification development for export-bound production.
China
Export manufacturing zones generate demand for cost-optimized standard bags serving international brand-owner supply chains. GB standards and evolving dual carbon goals shape material selection for converters targeting European and North American export markets. The Yangtze River Delta converter cluster scales volume production for global retail and food service procurement.
India
Domestic food processing and organized retail expansion create demand for standardized packaging formats with regulatory compliance documentation. FSSAI food safety regulations govern material contact approvals for polyethylene and polypropylene constructions. Maharashtra and Gujarat host emerging converter capacity serving both domestic consumption and Middle East export markets.
France
Private-label sustainability commitments in retail channels drive certified compostable bag specification. REACH Article 33 substance disclosure requirements filter supplier qualification toward certified resin streams with full material passports. The Île-de-France region concentrates procurement decision-making for national retail chains with cross-border distribution requirements.
Side Weld Bags Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and extrusion integration depth, with the vendor base fragmenting across regional food service supply chains while consolidating around integrated specialists serving multinational brand owners. Three archetypes dominate: extrusion-integrated converters capturing margin through resin optimization, custom print specialists serving branded retail channels, and heavy-duty specification houses locking in industrial contracts through qualification complexity. Competitive moves concentrate on backward integration into resin compounding and accelerated certification timelines for compostable formats.
Among UK-based converters, WB Packaging Ltd and CPS Flexible Ltd occupy positions across the integration spectrum, with the former exemplifying captive extrusion capabilities and the latter representing custom print specialization for retail channels. Bison Bag Co., Inc anchors the North American heavy-duty industrial tier. These three entities collectively illustrate how geographic origin and structural positioning map to margin tier and customer relationship durability in a market restructuring around regulatory compliance premiums.
| Leading Market Players |
|---|
| WB Packaging Ltd |
| CPS Flexible Ltd |
| Bison Bag Co., Inc |
| The Robinette Company |
| Sideweld Industries Inc |
| Pebal S.R.O |
| RJH Plastics |
| Vitra NV |
| A-ROO Company LLC |
| Others |
Value Chain & Pricing Dynamics
Polymer science expertise concentrated in Germany's industrial packaging corridor widens pricing-tier spreads between integrated extrusion specialists and conversion-only operators, as labor-cost differentials compound raw material volatility across standard and premium bag specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heavy-duty industrial contracts from commodity food-service volumes, with certification grade and volume scale as primary price differentiation drivers. Cost compression in standard polyethylene formats is intensifying because ethylene feedstock volatility transmits directly to converter margins where pass-through clauses face buyer resistance. Quick-service restaurant procurement teams exhibit highest price sensitivity, while pharmaceutical contract packagers demonstrate lowest sensitivity due to barrier-performance non-negotiability.
Supply Chain Analysis
Single-source vulnerability sits with ethylene feedstock streams drawn from Gulf Coast petrochemical complexes and Middle Eastern production hubs. Raw material dependencies rest on polyethylene resin grades, metallocene catalyst systems, and certified compostable resin formulations. Supply chain risk centers on regulatory restriction as ECHA persistent organic pollutant filtering reshapes substrate qualification timelines. Distribution runs through industrial distributors losing influence to direct converter relationships in German and Benelux retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU Green Deal recyclability mandates shift procurement authority toward converters with certified mono-material capabilities and full material passport documentation.
For Market Incumbents: Anticipate margin compression from extrusion-integrated specialists by securing multi-year qualification protocols with German automotive exporters and accelerating TÜV Austria certification timelines for compostable formats ahead of landfill diversion deadlines. Channel control through direct retail relationships offers defensive positioning against distributor disintermediation.
For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation in Europe opens a window for certified mono-material polyethylene specialists to capture share from legacy multi-layer laminate converters struggling with redesign timelines. White-space targets include pharmaceutical barrier clarity applications where metallocene polyethylene encroaches on polypropylene positioning, and California state-level extended producer responsibility frameworks where post-consumer recycled content capabilities create first-mover positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier conversion-only operators facing simultaneous resin requalification and workforce skill-gap constraints. Long-term viability favors extrusion-integrated specialists with captive supply chain control and established certification pathways. The signal to watch is accelerated private-label sustainability commitment timelines from German and Benelux retail chains as inflection indicator for premium-tier demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene formulation control insulates margins from ethylene feedstock volatility in standard bag volumes. |
| Certified Compostable Resin Certification | TÜV Austria and BPI validation opens premium positioning ahead of EU landfill diversion mandates. |
| Direct Retail Channel Development | Bypassing industrial distributors captures specification authority shifting to centralized sustainability offices. |
| Pharmaceutical Barrier Qualification | Metallocene polyethylene clarity validation encroaches on polypropylene unit-dose packaging in German contract packager networks. |
| Post-Consumer Recycled Content Integration | Verified PCR capabilities create first-mover advantage under emerging California and New York extended producer responsibility frameworks. |
Study Parameters
Direct dialogue with converter operations managers, resin procurement leads at multinational brand owners, pharmaceutical contract packager quality directors, and EU regulatory affairs specialists grounded qualitative findings, cross-referenced with customs trade data, FDA food-contact filing databases, ECHA substance restriction announcements, and SEC 10-K disclosures from packaging sector participants. Bottom-up capacity assessments and top-down demand modeling provided triangulation across analysis perspectives.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by product type, material substrate, end-use application, capacity tier, and regional regulatory cluster. CAGRs were derived from historical elasticity patterns applied to forecast resin cost pass-through rates and certification-driven specification shifts. Industry-specific inputs included EU Green Deal packaging recyclability deadline acceleration scenarios and North American quick-service restaurant franchise procurement consolidation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene feedstock price spike conditions or accelerated ECHA restriction expansions. Forecasts reflect documented assumptions about regulatory implementation timelines and brand-owner sustainability commitment credibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conductive Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Liner Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Bag in Drum Market