
 Grip Seal Bags Market | 2026-2036
Grip Seal Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Grip Seal Bags Market Foresight
Market Context
The divergence between premium and commodity tiers is hardening as food-grade certification requirements and custom printing capabilities separate value-added producers from generic converters. CFN Packaging Group Limited leverages integrated extrusion and printing lines to sustain margin capture in the medical supplies channel. Mondi anchors European supply through its kraft paper-laminated portfolio, while Zip-Pak competes on reseal technology leadership across North American retail packing accounts.
Technical Definition and Structural Segments
Grip seal bags are flexible packaging enclosures featuring an interlocking polyethylene or polypropylene track that permits repeated opening and closure without adhesive, typically manufactured via blown film extrusion followed by zipper profile insertion and side-sealing. Standard bags occupy the mature volume base in household and basic retail applications, while biodegradable plastic formulations represent the fastest-expanding material category as regulatory deadlines on conventional polymers tighten across multiple jurisdictions. Heavy duty bags concentrate margin pools in industrial catering and medical supplies where puncture resistance and compliance documentation command price premiums over commodity equivalents.
Regulatory Frame and Outlook
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation indirectly shape material substitution timelines for PVC-containing variants, while FDA food contact substance notifications govern polyethylene and polypropylene grades entering U.S. food storage channels. BIS certification requirements for plastic packaging in India are raising entry barriers for unqualified exporters. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate which material platforms will retain market access across their priority geographies.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand timelines for conventional polyethylene variants while simultaneously redirecting capital flows toward biodegradable material platforms and kraft-paper laminated alternatives.
Growth Catalysts
- E-commerce fulfillment automation:Heavy-duty grip seal specifications are becoming standard in automated picking environments where puncture resistance reduces line stoppages. German logistics hubs are driving volume specifications.
- REACH phthalate restrictions:PVC-containing variants face substitution pressure, accelerating polypropylene and biodegradable formulation adoption across medical supplies channels requiring compliance documentation.
- Biodegradable polymer R&D:PLA and PBAT blends are achieving cost parity with conventional films in pilot extrusion lines, opening food-grade certification pathways previously blocked by performance gaps.
Market Restraints
- Ethylene feedstock volatility:Crude-linked polyethylene resin costs swing quarterly, squeezing converter margins and preventing long-term contract pricing in commodity segments.
- Extrusion equipment concentration:Blown film lines with integrated zipper insertion capability cluster in Chinese manufacturing zones, creating single-source dependencies for European converters.
- Mechanical recycling contamination:Multi-layer kraft-paper laminates resist standard polyethylene recycling streams, exposing brands to extended producer responsibility penalties under evolving frameworks.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-stable grip seal formats for vaccine distribution remain underpenetrated as CDSCO strengthens packaging integrity requirements.
- Closed-loop retail refill systems:Durable reusable grip seal containers are displacing single-use formats in European bulk grocery channels supported by EU Green Deal implementation funding.
- Smart packaging convergence:RFID-embedded zipper tracks enable inventory tracking without secondary labels, attracting industrial catering operators managing high-SKU environments.
Industry Challenges
- Food-grade certification timelines:FDA food contact substance notifications for novel biodegradable polymers stretch 18-24 months, delaying product launches and freezing R&D pipelines.
- Legacy printing system incompatibility:Water-based inks required for compostable substrates demand press retrofits that mid-tier converters cannot finance without consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grip Seal Bags Market |
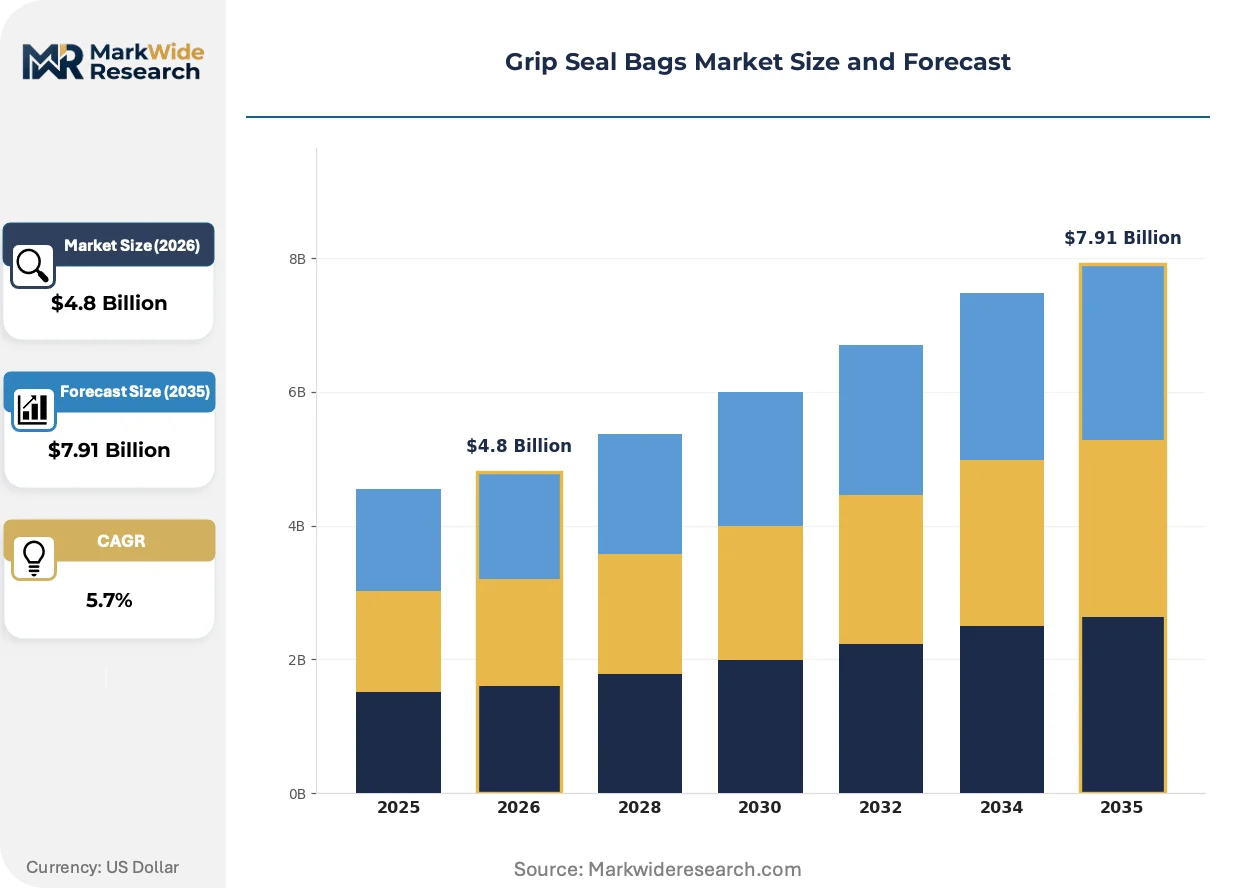
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Heavy Duty Bags, Reclosable Bags, Gusseted Bags Material: Polyethylene, Polypropylene, Biodegradable Plastic, PVC Application: Catering, Retail Packing, Food Storage, Medical Supplies End User: Households, Food Industry, E-Commerce, Healthcare Facilities |
| Companies Covered | CFN Packaging Group Limited, Grays Packaging Ltd., DUO Packaging, Flexopack, Century Art, 3A Manufacturing, Elliott Packaging, Zip-Pak, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grip Seal Bags Market Shifts & Advancements
Material science breakthroughs and regulatory compression are converging to redefine performance specifications across food contact, medical, and industrial segments simultaneously.
Biodegradable blown film formulations incorporating PBAT-PLA copolymers are electrifying technical capabilities in reseal durability and thermal stability. Medical sterilization pouch manufacturers in Germany and the Netherlands are adopting these materials fastest, bypassing conventional polyethylene supply chains entirely. The shift is compressing incumbent converters' access to premium margin pools as certification barriers fall.
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation are eliminating PVC-containing grip seal variants from pharmaceutical and industrial channels. Manufacturers are responding by accelerating polypropylene and kraft-paper laminate line conversions ahead of enforcement deadlines. Medical supplies segments face the steepest compliance ramps, with documentation requirements now extending through sub-tier suppliers.
Direct procurement relationships between e-commerce fulfillment operators and extrusion houses are fragmenting traditional distributor channels. Amazon and regional logistics networks in the US and Germany are specifying custom heavy-duty formats with printed barcodes, bypassing converters entirely. This pattern concentrates volume with vertically integrated producers capable of in-house printing and profile insertion.
Grip Seal Bags Market Segmentation
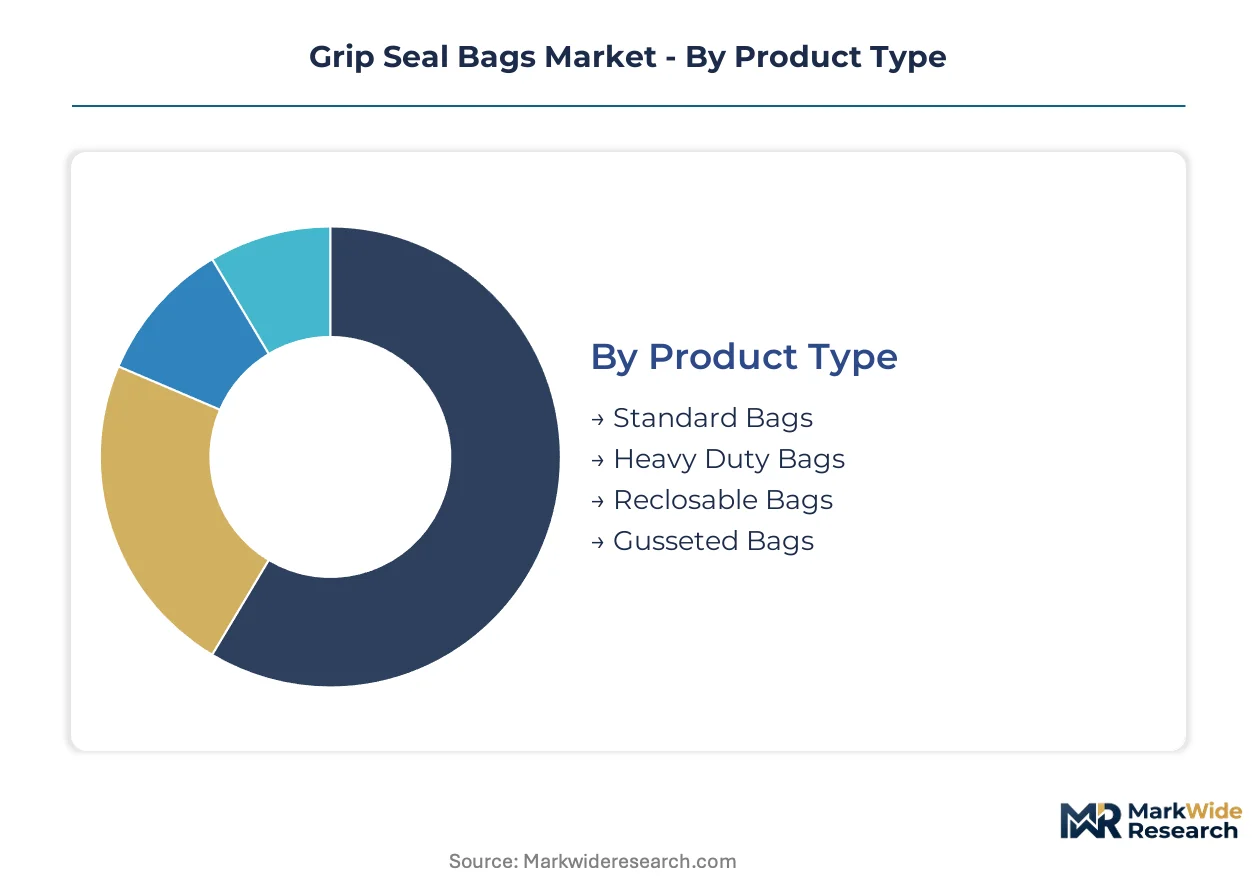
Segmentation in the grip seal bags market reveals distinct margin pools and compliance pathways. Material choices now determine market access more than performance alone, while end-user specifications fragment procurement channels across automated fulfillment and regulated medical channels.
Product Type:
Standard bags operate as standalone commodity purchases for basic household and retail applications, while heavy-duty and specialized formats embed into automated systems and regulated supply chains requiring certification documentation.
- Standard Bags:Blown polyethylene film with basic interlocking zipper profiles serves household storage and basic retail shelf applications. German discount retail chains and North American dollar-store networks concentrate procurement volumes here, though margin compression from resin cost volatility limits converter profitability.
- Heavy Duty Bags:Multi-layer coextruded constructions with reinforced zipper tracks withstand automated picking stresses in e-commerce fulfillment centers. Amazon's European logistics hubs and German third-party fulfillment operators are standardizing these specifications to reduce line stoppages from puncture failures.
- Reclosable Bags:Precision-molded zipper profiles enable hundreds of open-close cycles for food service and industrial applications. Bakery chains and institutional catering operators in France and the Netherlands specify these for ingredient portioning workflows.
- Gusseted Bags:Side-folded constructions expand volume capacity for bulky items without footprint increase. Hardware retailers and textile distributors in the United Kingdom favor these for irregular-shaped merchandise presentation.
Standard bags lead volumes today; heavy-duty variants are gaining share fastest.
Material:
Cost tiers separate incumbent petrochemical platforms from emerging biodegradable alternatives, with regulatory deadlines forcing substitution timelines that vary by application sensitivity.
- Polyethylene:Linear low-density and high-density grades dominate commodity production through established blown film infrastructure. E-commerce fulfillment channels in the United States and Germany absorb the largest volumes, though REACH phthalate restrictions are narrowing pharmaceutical applications.
- Biodegradable Plastic:PBAT-PLA copolymer formulations achieve reseal durability and thermal stability thresholds for food contact certification. Medical sterilization pouch manufacturers in Germany and the Netherlands are converting lines fastest to bypass conventional polyethylene supply chains entirely.
- Polypropylene:Higher melting point and chemical resistance suit autoclave sterilization and industrial chemical containment. Healthcare facilities in Switzerland and Austria specify polypropylene for surgical kit packaging requiring steam sterilization compatibility.
- PVC:Phthalate-plasticized formulations face elimination from EU pharmaceutical and food channels under REACH restrictions. Remaining demand concentrates in industrial containment applications with lower regulatory scrutiny.
Polyethylene retains volume leadership; biodegradable plastic is climbing the fastest.
Application:
Application segmentation tracks customer maturity and documentation requirements, with medical and food storage commanding premium pricing over commodity retail and catering segments.
- Food Storage:FDA food contact substance notifications and EU food contact framework compliance govern material selection for direct food contact. Retail grocery chains in the United States and supermarket cooperatives in Germany drive specifications for freezer-grade clarity and reseal performance.
- Medical Supplies:Sterilization validation and traceability documentation requirements create steep entry barriers. Hospital procurement consortia in France and pharmaceutical distributors in Switzerland concentrate demand for ISO 11607-compliant sterile barrier systems.
- Catering:High-volume disposable formats prioritize cost minimization over durability for single-use event and institutional service. Contract food service operators in the United Kingdom and banquet facilities in Spain represent core demand.
- Retail Packing:Custom printing and barcode integration specifications fragment procurement between distributor and direct extrusion channels. Apparel retailers in Italy and consumer electronics distributors in the Netherlands specify printed grip seal formats for inventory visibility.
Food storage leads volumes today; medical supplies shows the steepest expansion trajectory.
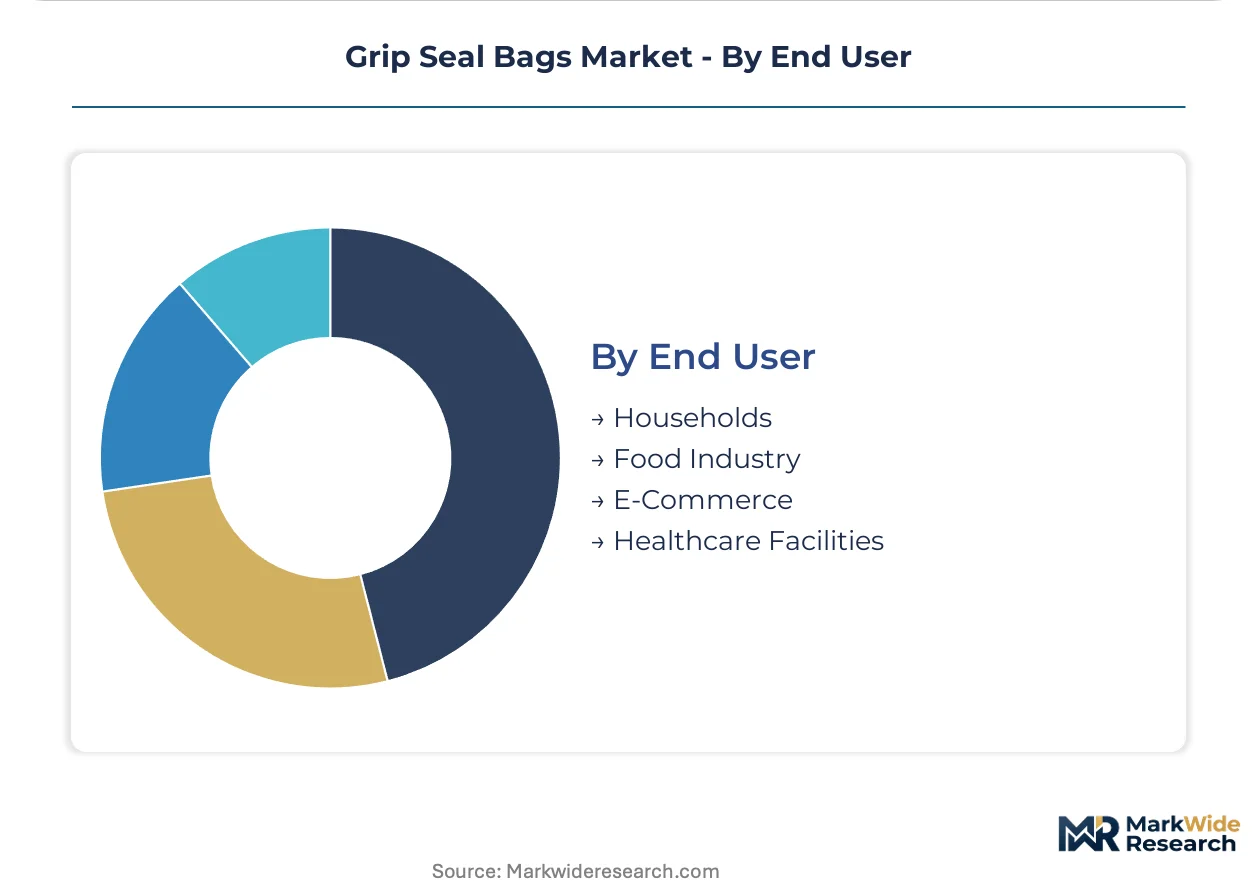
End User:
Customer type segmentation reveals diverging procurement patterns, with institutional buyers consolidating specifications while household demand fragments across price points.
- E-Commerce:Automated fulfillment operators specify custom heavy-duty formats with integrated barcodes, bypassing traditional converter channels. Amazon and German logistics networks concentrate volume with vertically integrated producers capable of in-house printing and profile insertion.
- Healthcare Facilities:Centralized procurement departments enforce material compliance documentation through approved vendor lists. Hospital groups in Switzerland and pharmaceutical manufacturers in Germany validate suppliers through multi-year qualification protocols.
- Food Industry:Processors and packers demand food-grade certification with batch traceability for ingredient and finished goods protection. Bakery cooperatives in France and meat processors in Spain specify temperature-stable formats for cold chain integrity.
- Households:Price-sensitive demand channels through retail discounters and online marketplaces with minimal specification requirements. German discount retail chains and North American mass merchants dominate volume distribution.
Households lead volumes today; e-commerce is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium specification volumes for medical-grade formats, while the United States drives heavy-duty e-commerce procurement at scale. India and China concentrate manufacturing capacity for export markets. Switzerland and the Netherlands anchor specialized sterilization pouch demand.
United States
Amazon's fulfillment network and third-party logistics operators specify custom heavy-duty grip seal formats with integrated barcodes for automated picking lines. FDA food contact substance notifications govern polyethylene grades entering retail grocery channels. The Pacific Northwest and Texas logistics corridors concentrate procurement volume with vertically integrated extrusion houses.
Germany
Hospital procurement consortia and pharmaceutical distributors demand ISO 11607-compliant sterile barrier systems with full traceability documentation. REACH phthalate restrictions on PVC-containing variants accelerate polypropylene and biodegradable formulation adoption. The Rhine-Ruhr manufacturing belt hosts medical sterilization pouch converters converting lines to PBAT-PLA copolymers.
China
Blown film extrusion lines with integrated zipper insertion capability cluster in coastal manufacturing zones serving export markets. The country's national standards regulator enforces plastic packaging quality certifications that raise barriers for unqualified exporters. Zhejiang and Guangdong provinces concentrate commodity-grade production for North American and European distributors.
Switzerland
Healthcare facilities specify polypropylene formats for surgical kit packaging requiring steam sterilization compatibility and autoclave durability. Swissmedic validates packaging suppliers through multi-year qualification protocols with extensive documentation requirements. The Basel pharmaceutical cluster drives demand for temperature-stable cold chain formats.
India
CDSCO strengthens packaging integrity requirements for pharmaceutical cold chain distribution, creating specification gaps for temperature-stable grip seal formats. BIS certification requirements for plastic packaging raise entry barriers for unqualified exporters. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate demand for compliant sterile barrier systems.
Grip Seal Bags Market Competitive Landscape
Top-tier vendors anchor premium medical and food-grade certification channels, while mid-tier converters compete on volume throughput in commodity household segments. The vendor base stratifies across integrated extrusion-printing operations, specialized medical sterilization pouch fabricators, and regional distributors serving retail discounters. Three archetypes dominate: vertically integrated multinationals with captive resin supply, mid-cap specialists with certified cleanroom capacity, and price-driven converters sourcing film from merchant extruders. Consolidation pressures intensify as FDA notification timelines and REACH compliance costs squeeze undifferentiated players, while strategic partnerships between e-commerce operators and extrusion houses bypass traditional distribution layers.
Among European-based packaging groups, Mondi anchors kraft paper-laminated portfolio positions, while Zip-Pak occupies reseal technology leadership across North American retail accounts. CFN Packaging Group Limited represents the integrated extrusion-printing archetype with in-house profile insertion capability.
| Leading Market Players |
|---|
| CFN Packaging Group Limited |
| Grays Packaging Ltd. |
| DUO Packaging |
| Flexopack |
| Century Art |
| 3A Manufacturing |
| Elliott Packaging |
| Zip-Pak |
| Mondi |
| Others |
Supply & Pricing Matrix
Captive extrusion capacity in Germany anchors premium medical-grade pricing power, while outsourced film sourcing from Chinese merchant extruders locks commodity converters into volatile resin pass-through structures that erode margin control.
Pricing Analysis
Capacity additions in Zhejiang and Guangdong are reshaping price floors for standard polyethylene formats, compressing margins for European converters without backward integration into resin production. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-certified medical sterilization pouches from basic household storage bags. Cost compression in commodity tiers is intensifying because ethylene feedstock volatility prevents long-term contract pricing. E-commerce fulfillment operators show least price sensitivity due to line-stoppage cost exposure, while household retail channels concentrate procurement volume with highest sensitivity.
Supply Chain Analysis
FDA food contact substance notifications and EU REACH compliance documentation gate access to premium margin pools, forcing mid-tier converters toward consolidation or exit. Manufacturing gravity centers on China for commodity blown film, Germany for medical-grade sterilization pouches, and the United States for heavy-duty e-commerce specifications. Raw material flows draw from linear low-density polyethylene resin, PBAT-PLA copolymer feedstocks, and kraft paper laminates. Single-source vulnerability concentrates in integrated zipper insertion equipment clustered in coastal Chinese zones. Distribution runs through direct procurement relationships between Amazon and extrusion houses, fragmenting traditional converter-distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German medical-grade certification costs create arbitrage opportunity for converters locating extrusion capacity in India, where BIS compliance expenses run substantially lower while CDSCO pharmaceutical packaging requirements tighten demand specifications.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate PBAT-PLA copolymer line conversions ahead of EU Single-Use Plastics Directive enforcement deadlines to capture sterilization pouch demand fleeing conventional polyethylene. Deepen backward integration into blown film extrusion to bypass Chinese equipment dependencies and secure margin control against resin volatility. For New Entrants and Emerging Players: Specialized medical sterilization pouch fabricators represent the most penetrable channel gap, as FDA notification timelines freeze incumbent R&D pipelines. Target Indian pharmaceutical cold chain specifications where temperature-stable formats remain underdeveloped. Pursue white-label partnerships with German hospital procurement consortia seeking secondary supplier diversification. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and extended producer responsibility frameworks squeeze undifferentiated mid-tier converters without cleanroom certification. Long-term viability favors vertically integrated extrusion-printing operations with captive medical-grade channels. Watch for CDSCO packaging integrity rule finalization as inflection signal triggering Indian pharmaceutical demand surge.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Line Conversion | PBAT-PLA copolymer adoption bypasses EU Single-Use Plastics Directive restrictions on conventional polyethylene. |
| Backward Integration into Extrusion | In-house blown film production reduces dependency on Chinese zipper insertion equipment clusters. |
| Medical Sterilization Pouch Certification | ISO 11607 compliance unlocks hospital procurement consortia in Germany and Switzerland. |
| Direct E-Commerce Fulfillment Partnership | Amazon and German logistics hubs concentrate volume with vertically integrated printing-extrusion operations. |
| Indian Pharmaceutical Cold Chain Entry | CDSCO packaging integrity requirements create specification gaps for temperature-stable formats. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Switzerland, with primary inputs from each market cluster combining extrusion plant managers, hospital procurement directors, pharmaceutical packaging engineers, and e-commerce logistics operators with secondary validation from FDA food contact substance notifications, ECHA REACH restriction updates, CDSCO pharmaceutical packaging circulars, and customs trade flow databases. Bottom-up volume modeling triangulates against top-down resin consumption estimates.
Granularity-level framing applies country-specific material substitution timelines, with segmentation modeled across product type, material platform, application sensitivity, and end-user procurement maturity. CAGRs derive from ethylene feedstock price trajectory assumptions, regulatory enforcement schedule phasing, and e-commerce fulfillment automation penetration curves. Medical sterilization pouch demand and biodegradable polymer cost parity achievement serve as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU extended producer responsibility framework finalization and PBAT-PLA blend performance validation in autoclave sterilization cycles. Forecasts reflect documented assumptions on resin price volatility bands and regulatory enforcement rigor. A model refresh is warranted upon material change in FDA food contact substance notification timelines for novel biodegradable polymers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Compression Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market