
 US Healthcare Discount Plan Market | 2026-2036
US Healthcare Discount Plan Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Discount Plan Market Intelligence
Capital-intensity divergence between technology-enabled platform operators and legacy broker-dependent networks is redrawing competitive boundaries in the US healthcare discount plan sector. AmeriPlan leverages its extensive independent contractor sales force to sustain penetration in underserved metropolitan corridors. DentalPlans.com, Inc. anchors its position through direct-to-consumer digital enrollment infrastructure that controls acquisition costs across all fifty states.
A healthcare discount plan constitutes a membership-based program that negotiates reduced rates with medical, dental, vision, and pharmaceutical providers in exchange for periodic subscription fees, typically functioning outside traditional insurance risk-pooling mechanisms. These arrangements deliver immediate point-of-service price reductions rather than claims-based reimbursement, serving primarily the uninsured, underinsured, and individuals facing high-deductible health plan gaps. Corporate plan types command the deepest employer subsidy pools as businesses seek to supplement narrow-network primary coverage with broader specialist access. Regional provider networks capture disproportionate margin concentration through exclusive contracting arrangements with dominant health systems in non-urban markets.
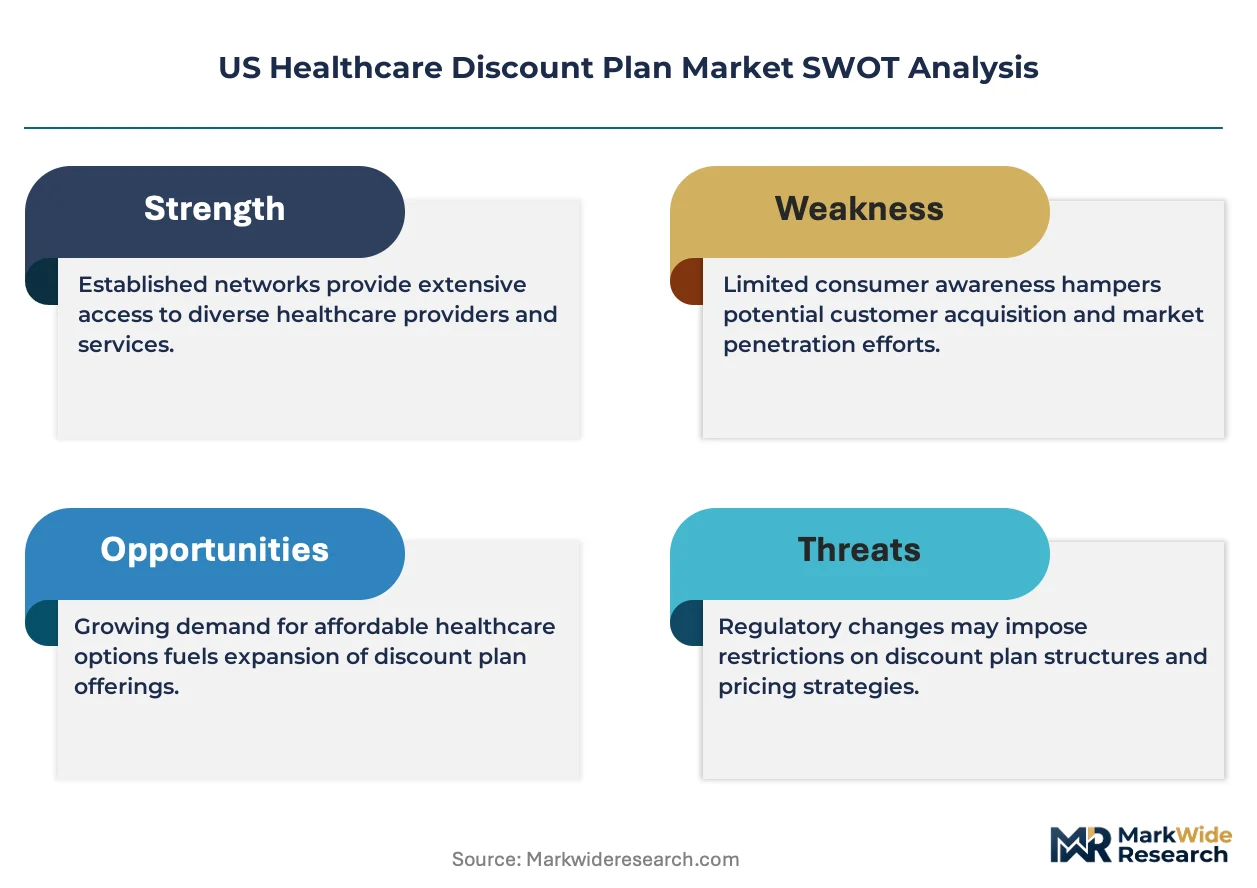
FDA oversight of associated telehealth integrations and state-level insurance commissioner licensing requirements under the National Association of Insurance Commissioners model laws shape product architecture and market access protocols for discount plan administrators. The Federal Trade Commission monitors marketing claims to prevent conflation of discount plans with comprehensive insurance products, constraining subscriber acquisition messaging. Stakeholders must monitor state-by-state legislative movements toward mandatory benefit disclosures and network adequacy standards that could reshape operational compliance burdens.
Market Dynamics
Employer mandate threshold creep under the Affordable Care Act is pushing mid-sized businesses toward supplemental healthcare arrangements that bypass traditional insurance risk pools entirely.
Growth Catalysts
- Medicaid Expansion Gaps:Southeastern states with limited Medicaid coverage create concentrated demand pools seeking alternative cost-reduction mechanisms for outpatient services and prescription access.
- High-Deductible Health Plan Proliferation:Employer-sponsored HDHP adoption exposes workers to substantial point-of-service costs, driving ancillary discount plan enrollment as a financial buffer.
- Telehealth Platform Integration:FDA oversight frameworks for remote care technologies enable discount plan administrators to bundle virtual consultations with negotiated provider rates.
Market Restraints
- Network Adequacy Variability:Rural provider density constraints limit specialist access in non-urban markets, degrading membership value propositions outside metropolitan corridors.
- Regulatory Fragmentation:State-by-state licensing requirements under National Association of Insurance Commissioners model laws impose compliance overhead that scales disproportionately with geographic expansion.
- Insurance Product Confusion:Federal Trade Commission enforcement against misleading marketing claims restricts subscriber acquisition messaging and elevates legal review costs.
Strategic Opportunities
- Corporate Benefit Integration:Mid-sized employers in Texas and Florida seek turnkey ancillary packages that supplement narrow-network primary coverage with broader specialist access.
- Pharmaceutical Discount Layering:Integration with prescription savings programs at point-of-sale creates stickier membership retention through tangible transaction-level savings.
- State Disclosure Mandates:Legislative movements toward standardized benefit transparency requirements favor established operators with compliant infrastructure over opportunistic entrants.
Industry Challenges
- Provider Contracting Velocity:Exclusive arrangements with dominant health systems require extended negotiation cycles that delay network expansion in priority markets.
- Digital Infrastructure Capex:Real-time eligibility verification and claims-adjacent transaction processing demand sustained technology investment to match consumer expectations set by traditional insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Discount Plan Market |
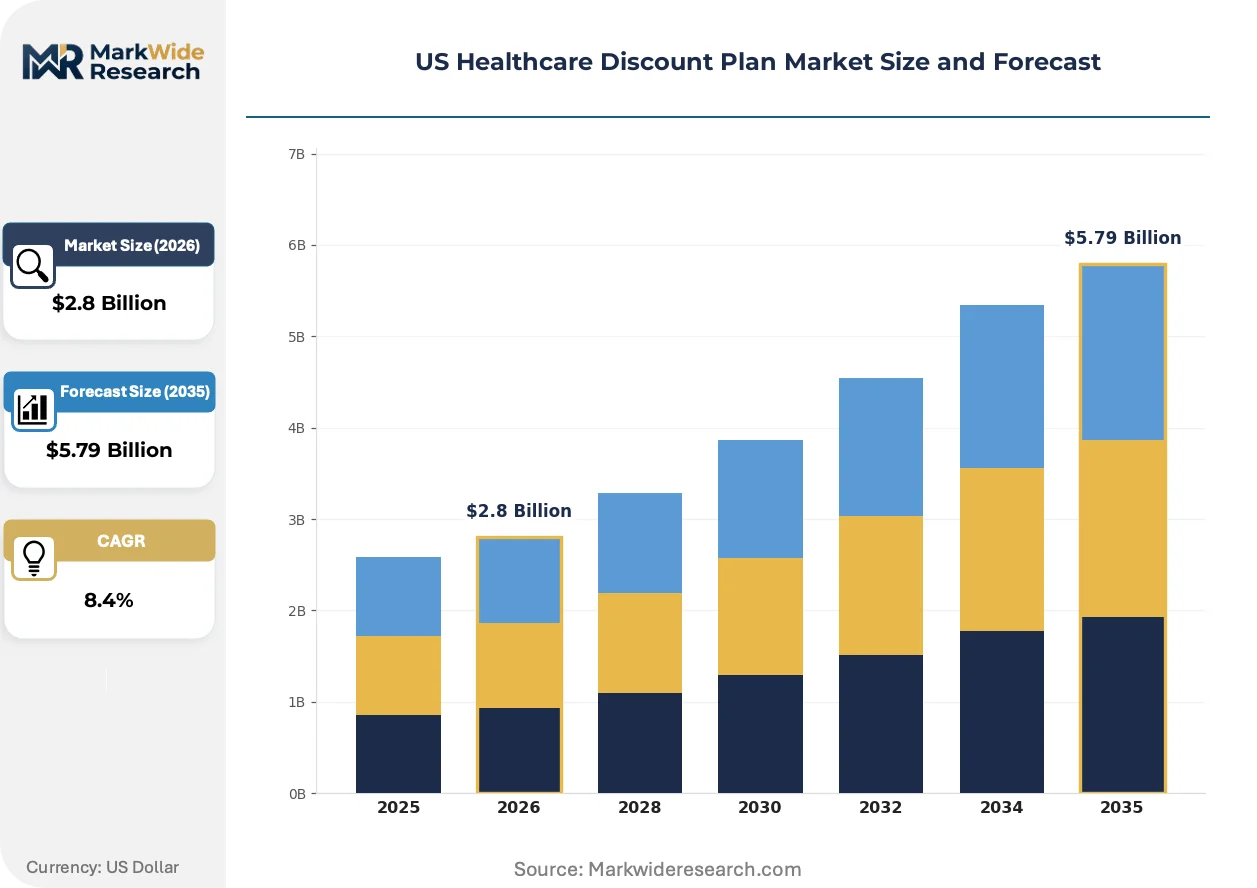
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plan Type: Individual, Family, Corporate, Association Provider Network: National, Regional, Local, Specialty Discount Type: Percentage-Based, Flat Fee, Membership Fee, Co-Pay End User: Employees, Employers, Insurers, Consumers |
| Companies Covered | True Dental Discounts, Best Care Medical Plan, Inc., New Benefits, Ltd., Access One Consumer Health, Inc., Florida Health Solution Corp., AmeriPlan, Avia Dental Plan, Inc., DentalPlans.com, Inc., CARRINGTON International Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Discount Plan Market Strategic Shifts & Innovations
Platform-based enrollment infrastructure is compressing customer acquisition costs while telehealth bundling reshapes the core value proposition beyond simple rate negotiation.
Mobile-first membership management systems are replacing call-center-dependent onboarding workflows. Direct-to-consumer operators deploy these interfaces to reduce per-subscriber enrollment friction. The technology is miniaturizing operational overhead for regional plan administrators competing against national broker networks.
State insurance commissioners are tightening marketing disclosure requirements under NAIC model law amendments. This regulatory pressure elevates compliance documentation burdens for multi-state operators. Administrators with captive legal infrastructure are absorbing these costs more efficiently than franchise-dependent competitors.
Employer procurement of discount plans is consolidating through benefits administration platforms rather than standalone broker relationships. Third-party administrators are embedding these products within broader ancillary benefit suites. This channel shift is most pronounced in the southeastern United States where mid-sized employers lack dedicated benefits staff.
US Healthcare Discount Plan Market Segmentation
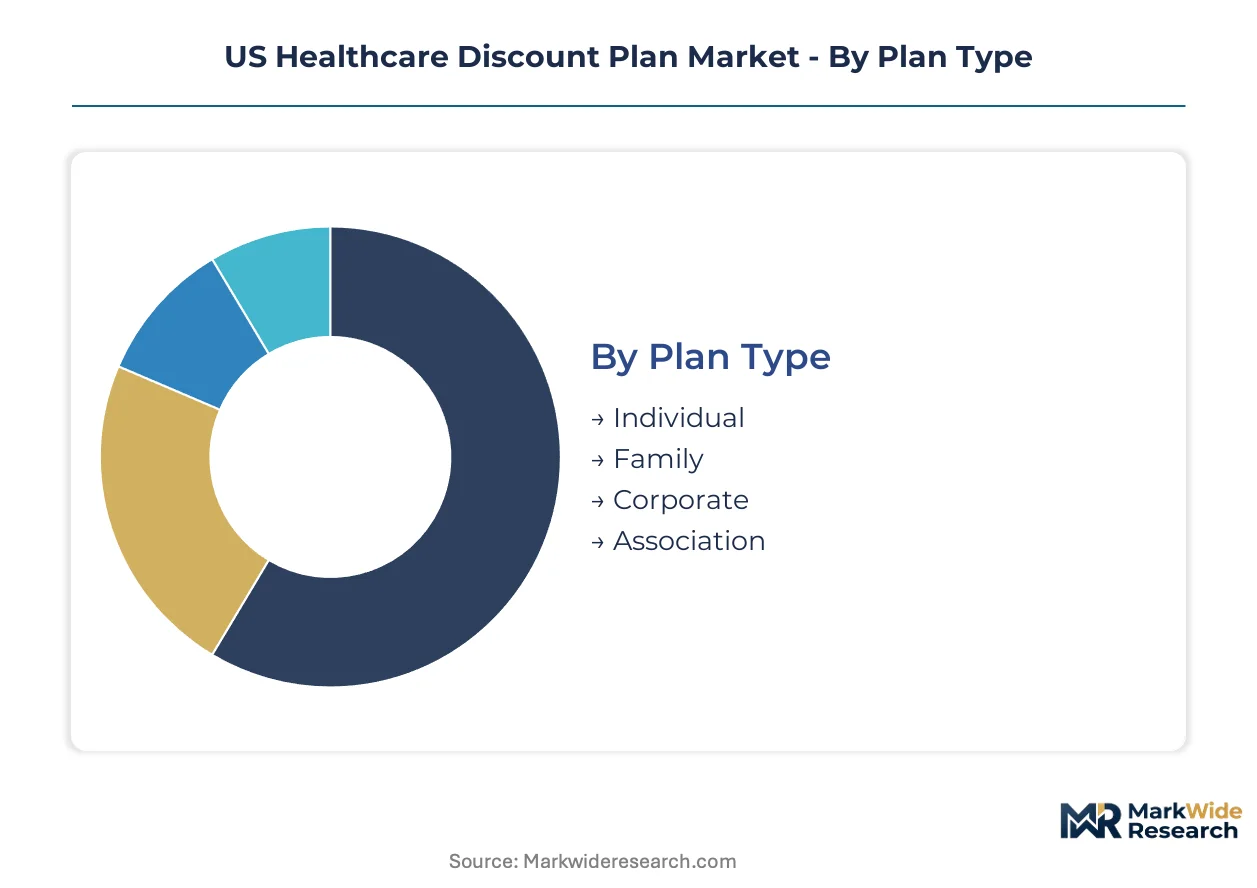
Segmentation in the US healthcare discount plan market reveals distinct margin architectures across plan structures, network configurations, and pricing mechanisms. Each dimension carries unique regulatory exposure and customer acquisition economics that shape operator strategy.
Plan Type:
Margin pools concentrate in corporate arrangements where employer subsidies reduce price sensitivity and improve retention metrics.
- Individual:Single-subscriber plans targeting uninsured consumers through direct-to-consumer channels. Demand clusters in Florida and Texas metropolitan corridors where Medicaid expansion gaps leave working-age adults without coverage alternatives.
- Family:Multi-member household plans bundling dental, vision, and pharmaceutical discounts. Mid-sized employers in Georgia and North Carolina source these as supplemental offerings for employees who decline high-deductible primary coverage.
- Corporate:Turnkey ancillary packages sold through benefits administration platforms. These command the deepest subsidy pools as businesses seek to supplement narrow-network primary coverage with broader specialist access.
- Association:Group-negotiated rates for trade organizations and professional collectives. Member-driven enrollment reduces per-acquisition costs compared to individual marketing campaigns.
The dominant share belongs to Corporate, while Family is closing the gap fastest.
Provider Network:
Network scale determines compliance burden and contracting velocity, with regional configurations capturing disproportionate margin concentration through exclusive health system arrangements.
- National:Coast-to-coast provider directories maintained by technology-enabled platform operators. These networks require sustained investment in real-time eligibility verification systems to match consumer expectations set by traditional insurers.
- Regional:Exclusive contracting arrangements with dominant health systems in non-urban markets. Rural provider density constraints in Appalachian corridors limit specialist access, degrading membership value propositions outside metropolitan areas.
- Local:Metropolitan-area provider clusters serving dense urban populations. These configurations minimize administrative overhead but restrict member mobility and cross-market utility.
- Specialty:Concentrated networks for dental, vision, or pharmaceutical verticals. FDA oversight frameworks for associated telehealth integrations shape product architecture and market access protocols for administrators bundling virtual consultations.
National networks hold the largest footprint, though Regional configurations are expanding most quickly through exclusive health system partnerships.
Discount Type:
Pricing mechanism selection directly influences subscriber perception of value transparency and point-of-service friction.
- Percentage-Based:Proportional reductions off provider chargemaster rates. These arrangements dominate individual and family segments where members compare savings against uninsured retail pricing.
- Flat Fee:Fixed-dollar discounts for specific procedures or service categories. Corporate procurement teams favor this structure for predictable budget forecasting across employee populations.
- Membership Fee:Periodic subscription charges enabling access to negotiated rate schedules. This model concentrates regulatory scrutiny under FTC marketing claim enforcement.
- Co-Pay:Fixed per-visit charges resembling traditional insurance cost-sharing. These hybrid structures risk product confusion and elevate legal review costs for multi-state operators.
Percentage-Based structures command the dominant position, while Co-Pay mechanisms are gaining share fastest among employers seeking insurance-like member experiences.
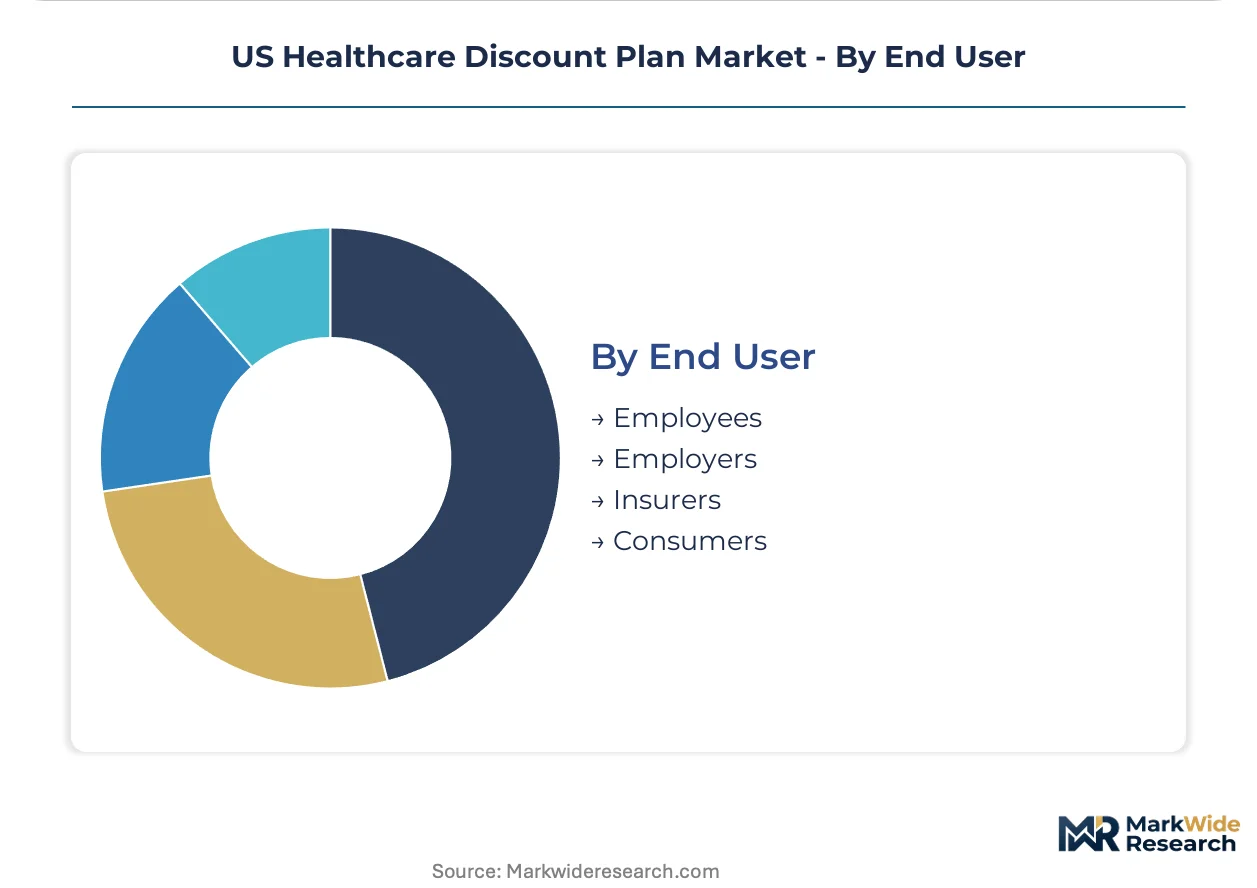
End User:
Customer type segmentation maps directly to distribution channel economics and sales cycle duration.
- Employees:Individual workers accessing discount plans through employer-sponsored arrangements. High-deductible health plan proliferation exposes these subscribers to substantial point-of-service costs, driving ancillary enrollment as a financial buffer.
- Employers:Business entities procuring turnkey ancillary packages. Third-party administrators in the southeastern United States embed these products within broader benefit suites for mid-sized companies lacking dedicated HR staff.
- Insurers:Carriers layering discount plans atop limited-benefit products. These partnerships require navigation of state insurance commissioner licensing requirements under NAIC model laws.
- Consumers:Direct purchasers through digital enrollment infrastructure. Mobile-first membership management systems reduce per-subscriber friction for this segment.
Employers represent the largest addressable base, with Consumers climbing the fastest through direct-to-consumer platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Florida metropolitan corridors where Medicaid expansion gaps sustain premium membership rates, while Appalachian sub-markets face margin compression from rural provider scarcity and elevated acquisition costs.
Southeast
Florida and Georgia dominate volume generation through employer-sponsored corporate plans targeting uninsured service workers. State insurance commissioners enforce NAIC model law disclosure requirements that elevate compliance costs for multi-state operators. Atlanta anchors regional network expansion as dominant health systems negotiate exclusive contracting arrangements with discount plan administrators.
Southwest
Texas metropolitan corridors generate concentrated demand from mid-sized employers seeking HDHP supplements for narrow-network primary coverage. The Affordable Care Act's employer mandate thresholds push businesses toward ancillary arrangements bypassing traditional risk pools. Dallas-Fort Worth hosts the densest provider network configurations, enabling real-time eligibility verification infrastructure deployment.
Mid-Atlantic
Virginia and North Carolina exhibit accelerating family plan adoption through benefits administration platform consolidation. State-level licensing requirements under NAIC frameworks impose geographic expansion friction for emerging operators. Raleigh-Durham's technology corridor attracts platform-based enrollment providers seeking to compress customer acquisition costs through mobile-first interfaces.
Great Lakes
Ohio and Michigan present mixed opportunity profiles with established employer benefit cultures offset by Medicaid expansion coverage reducing uninsured pools. FTC marketing claim enforcement constrains subscriber acquisition messaging across state lines. Detroit's automotive sector employers drive corporate plan procurement as supplementary offerings for hourly production workers.
West Coast
California and Washington demonstrate lower penetration rates due to robust Medicaid expansion and Covered California marketplace competition. FDA oversight of telehealth integrations shapes product architecture for administrators bundling virtual consultations. Los Angeles retains niche demand concentration among gig economy workers ineligible for employer-sponsored coverage.
US Healthcare Discount Plan Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with platform-enabled direct-to-consumer operators commanding acquisition efficiency while broker-dependent networks sustain penetration in underserved corridors. The market exhibits moderate consolidation around national enrollment infrastructure providers and regional health system affiliates. Three archetypes dominate: technology-enabled platforms with captive digital enrollment systems, legacy broker networks leveraging independent contractor sales forces, and health system-captive administrators with exclusive provider contracting. Competitive dynamics center on M&A activity consolidating regional provider networks and strategic partnerships embedding discount products within third-party benefits administration platforms.
Among established platform operators, DentalPlans.com, Inc. and AmeriPlan occupy positions at opposite ends of the channel spectrum, with the former exemplifying direct-to-consumer digital infrastructure and the latter representing broker-dependent network penetration. CARRINGTON International Corporation anchors the health system-affiliated tier through exclusive contracting arrangements. These three players collectively illustrate the market's structural segmentation between acquisition efficiency, sales force scale, and provider network control.
| Leading Market Players |
|---|
| True Dental Discounts |
| Best Care Medical Plan, Inc. |
| New Benefits, Ltd. |
| Access One Consumer Health, Inc. |
| Florida Health Solution Corp. |
| AmeriPlan |
| Avia Dental Plan, Inc. |
| DentalPlans.com, Inc. |
| CARRINGTON International Corporation |
| Others |
Cost & Logistics Intelligence
Membership fee structures lock in subscriber retention while anchoring price visibility against point-of-service alternatives. This contract pattern concentrates margin pools in corporate arrangements where employer subsidies reduce price sensitivity and improve renewal predictability across southeastern US markets.
Pricing Analysis
The customization-premium spread separates turnkey corporate packages from individual direct-to-consumer enrollment. Percentage-based discounts off provider chargemaster rates dominate individual and family segments, while flat-fee structures command corporate procurement for predictable budget forecasting. Price differentiation hinges on network scale and telehealth bundling intensity. Cost compression in individual tiers is intensifying because platform operators compress acquisition overhead through mobile-first infrastructure. Employers exhibit the lowest price sensitivity due to subsidy pools, whereas uninsured consumers in Medicaid expansion gaps face acute cost consciousness.
Supply Chain Analysis
Provider network density in metropolitan corridors anchors supply access for discount plan administrators. The supply chain draws from dominant health systems in Texas, Florida, and Georgia, plus technology vendors enabling real-time eligibility verification. Raw material dependencies include telehealth platform licenses, broker network commissions, and compliance documentation systems. Single-source vulnerability concentrates in exclusive health system contracting arrangements that delay network expansion. Distribution runs through benefits administration platforms embedding discount products within broader ancillary suites for mid-sized employers lacking dedicated HR staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against Medicaid expansion and narrow-network insurance products that capture demand in states adopting broader coverage. Incumbents must navigate employer migration toward integrated benefit platforms.
For Market Incumbents: Shield corporate market share by deepening exclusive health system partnerships in Texas and Florida metropolitan corridors. Accelerate telehealth platform integration to differentiate against narrow-network primary coverage substitutes. Control compliance documentation costs through captive legal infrastructure that absorbs NAIC model law disclosure burdens more efficiently than franchise-dependent competitors. For New Entrants and Emerging Players: NAIC licensing fast-tracks enable geographic entry through states with standardized disclosure requirements rather than fragmented regulatory regimes. White-space concentrates in Appalachian sub-markets where rural provider scarcity degrades incumbent value propositions. Target association plan structures for trade organizations in Georgia and North Carolina to reduce per-acquisition costs versus individual marketing campaigns. For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled platform operators with captive digital enrollment infrastructure and compressed customer acquisition economics. Long-term viability favors administrators controlling real-time eligibility verification systems that match consumer expectations set by traditional insurers. Monitor state legislative movements toward mandatory network adequacy standards as inflection indicators favoring established compliant operators over opportunistic entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | FDA oversight frameworks enable bundled virtual consultations that differentiate against standalone rate negotiation products. |
| Exclusive Health System Partnership | Contracting arrangements with dominant systems in Texas and Florida anchor network density and pricing power. |
| Benefits Administration Platform Embedding | Third-party administrator consolidation in the southeastern US channels corporate procurement toward turnkey ancillary suites. |
| Mobile-First Enrollment Infrastructure | Direct-to-consumer interfaces reduce per-subscriber friction and compress acquisition costs across fifty-state operations. |
| NAIC Compliance Certification | Standardized disclosure documentation absorbs regulatory overhead that disproportionately burdens multi-state geographic expansion. |
Research Approach
Desk research of state insurance commissioner filings, FTC enforcement records, and hospital procurement databases preceded structured interviews with discount plan administrators, benefits platform executives, and health system contracting officers. Primary fieldwork captured network expansion velocity, employer procurement criteria, and telehealth integration economics. Secondary validation drew from NAIC model law amendments, CMS Medicare data, and GPO contract repositories. Bottom-up subscriber volume estimates triangulated against top-down employer benefit spending assessments.
Variance decomposition across the analysis window isolates plan type, provider network configuration, and end-user segment contributions to value trajectories. Segmentation dimensions modeled include corporate versus individual plan structures, national versus regional network scales, and employer versus consumer distribution channels. CAGRs were derived from enrollment flow projections and per-subscriber revenue retention patterns. Forecast inputs incorporate Medicaid expansion gap persistence and HDHP adoption curves.
Underlying assumptions cover employer mandate threshold stability and NAIC model law harmonization, with deviation risk concentrated in state-level disclosure mandate fragmentation and rural provider network adequacy enforcement. Forecasts reflect these assumptions with sensitivity to regulatory acceleration or telehealth reimbursement policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
Germany Health Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
United States Health and Medical Insurance Market
Health Insurance
Healthcare Payer Services Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market