
 Blood Urea Nitrogen Testing Market | 2026-2036
Blood Urea Nitrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Urea Nitrogen Testing Market Outlook
CLIA-waived assay certification is redrawing competitive boundaries in decentralized testing. Siemens Healthineers leverages its installed base of chemistry analyzers to sustain reagent pull-through in hospital core labs. Beckman Coulter anchors its position through backward integration into enzyme production for colorimetric BUN assays. Abbott Laboratories differentiates via cartridge-based platforms that occupy outpatient clinic workflows with minimal operator training.
Blood urea nitrogen testing quantifies nitrogenous waste in serum or plasma, typically measured in mg/dL through enzymatic or colorimetric reactions using urease and glutamate dehydrogenase; the assay serves as a standard renal function screen in clinical chemistry panels. Testing kits dominate volume flows through high-frequency reorder cycles in hospital laboratories, while enzymatic technology leads precision tiers due to superior specificity against ammonia interference. Diagnostic labs represent the fastest-growing end-user channel as regional reference networks consolidate specimen processing.
FDA 510(k) clearance pathways and CLIA complexity categorization shape product design priorities for US manufacturers, while the EU In Vitro Diagnostic Regulation enforces post-market surveillance and performance documentation for CE-marked BUN assays entering European diagnostic labs. Stakeholders must monitor evolving IVD reimbursement codes and point-of-care connectivity standards that will determine which platform architectures capture the next wave of decentralized renal monitoring contracts.
Market Dynamics
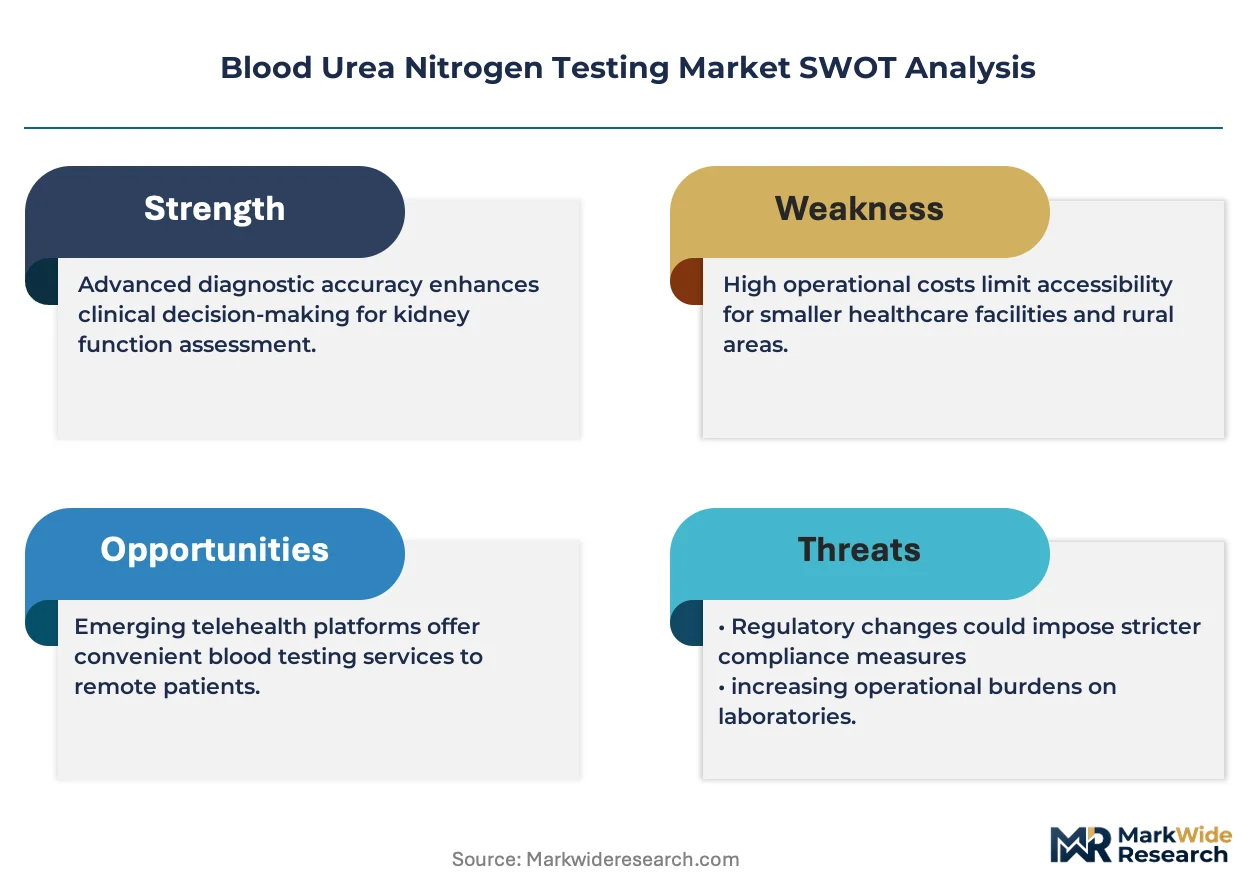
CLIA-waived certification requirements are compressing assay development timelines and forcing manufacturers to strip operational complexity from point-of-care BUN platforms, fundamentally restructuring how renal function testing penetrates outpatient settings.
Growth Catalysts
- Chronic kidney disease protocols:German outpatient nephrology clinics now mandate rapid BUN panels for disease staging, creating standardized demand pull for cartridge-based systems.
- CLIA-waived pathway:The United States complexity categorization framework rewards simplified assay designs with broader operator eligibility, expanding addressable testing sites.
- Enzymatic specificity:Urease-glutamate dehydrogenase chemistry delivers superior ammonia interference resistance, driving replacement of older Berthelot methods in reference laboratories.
Market Restraints
- Reagent supply concentration:Backward integration into urease production limits viable suppliers to enzyme manufacturers with captive fermentation capacity, squeezing mid-tier assay vendors.
- Reference range heterogeneity:Variability in BUN normalization standards across clinical chemistry societies complicates multi-site diagnostic network harmonization.
- Creatinine-based substitution:Estimated glomerular filtration rate calculations using creatinine and cystatin C are displacing standalone BUN ordering in health system protocols.
Strategic Opportunities
- Home-based monitoring:Fingerstick-capable BUN microfluidics open direct-to-patient channels for dialysis patient self-management in markets with remote reimbursement codes.
- Connectivity mandates:FDA guidance on point-of-care data interoperability creates first-mover advantage for platforms with native LIS integration and cloud architecture.
- Veterinary crossover:Adaptation of human enzymatic assays for companion animal renal panels accesses underpenetrated specialty clinic segments with minimal R&D retooling.
Industry Challenges
- CLIA-waived validation timelines:FDA 510(k) clearance for waived complexity demands extensive operator error studies, extending product development cycles by 12-18 months.
- Analyzer-reagent lock-in:Closed cartridge systems require manufacturers to maintain dual competency in consumables and hardware, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Urea Nitrogen Testing Market |
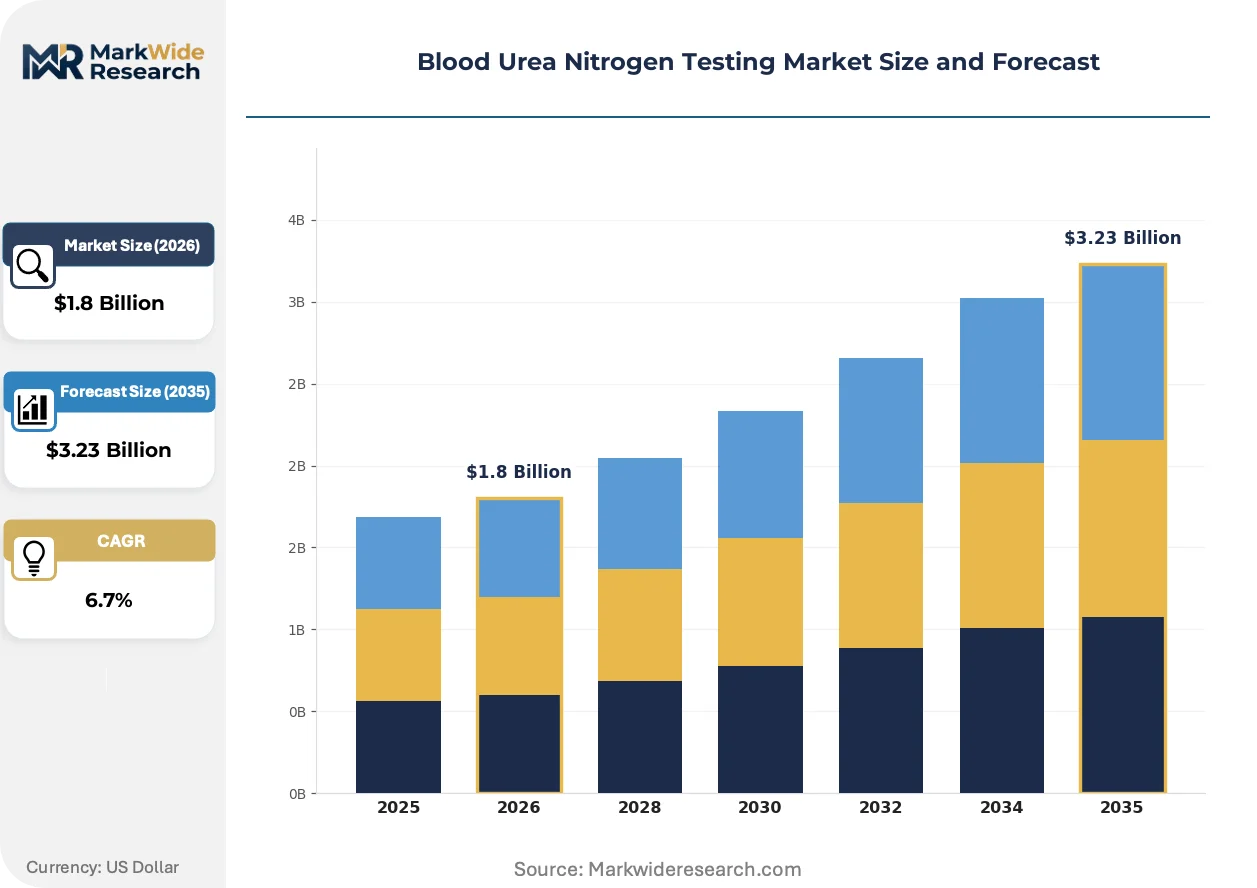
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Testing Kits, Consumables Technology: Colorimetric, Electrochemical, Spectrophotometric, Enzymatic End User: Hospitals, Diagnostic Labs, Home Care Settings, Outpatient Clinics Application: Renal Function Assessment, Diabetic Monitoring, Critical Care, Routine Screening |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Beckman Coulter, Abbott Laboratories, Thermo Fisher Scientific, Sysmex Corporation, Bio-Rad Laboratories, Danaher Corporation, Randox Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Urea Nitrogen Testing Market Strategic Shifts
Decentralization of renal function assessment is collapsing the traditional specimen-to-laboratory workflow, with enzymatic precision now migrating to settings previously served by central lab batch processing alone.
Cartridge-based microfluidic platforms are supplanting conventional wet chemistry analyzers in urgent care and nephrology clinic settings. Outpatient networks in Germany and the United States are adopting these systems at accelerating replacement cycles. The shift is compressing installed base loyalty for core lab analyzer vendors while opening reagent revenue pools to point-of-care specialists.
The EU In Vitro Diagnostic Regulation now enforces post-market surveillance and performance documentation for CE-marked BUN assays entering European diagnostic labs. Manufacturers must maintain clinical evidence packages and vigilance reporting systems that central lab incumbents possess but point-of-care entrants lack. German reference networks are responding by consolidating preferred vendor lists around MDR-compliant suppliers.
Hospital laboratories are unbundling renal panels to match reimbursement coding granularity, with BUN ordered as standalone assays rather than bundled chemistry panels. Reference laboratories in the United States are capturing this volume through direct-to-physician result portals that bypass hospital outreach services. The behavior is most visible in Medicare Advantage networks where risk-adjusted coding drives test specificity requirements.
Blood Urea Nitrogen Testing Market Segmentation
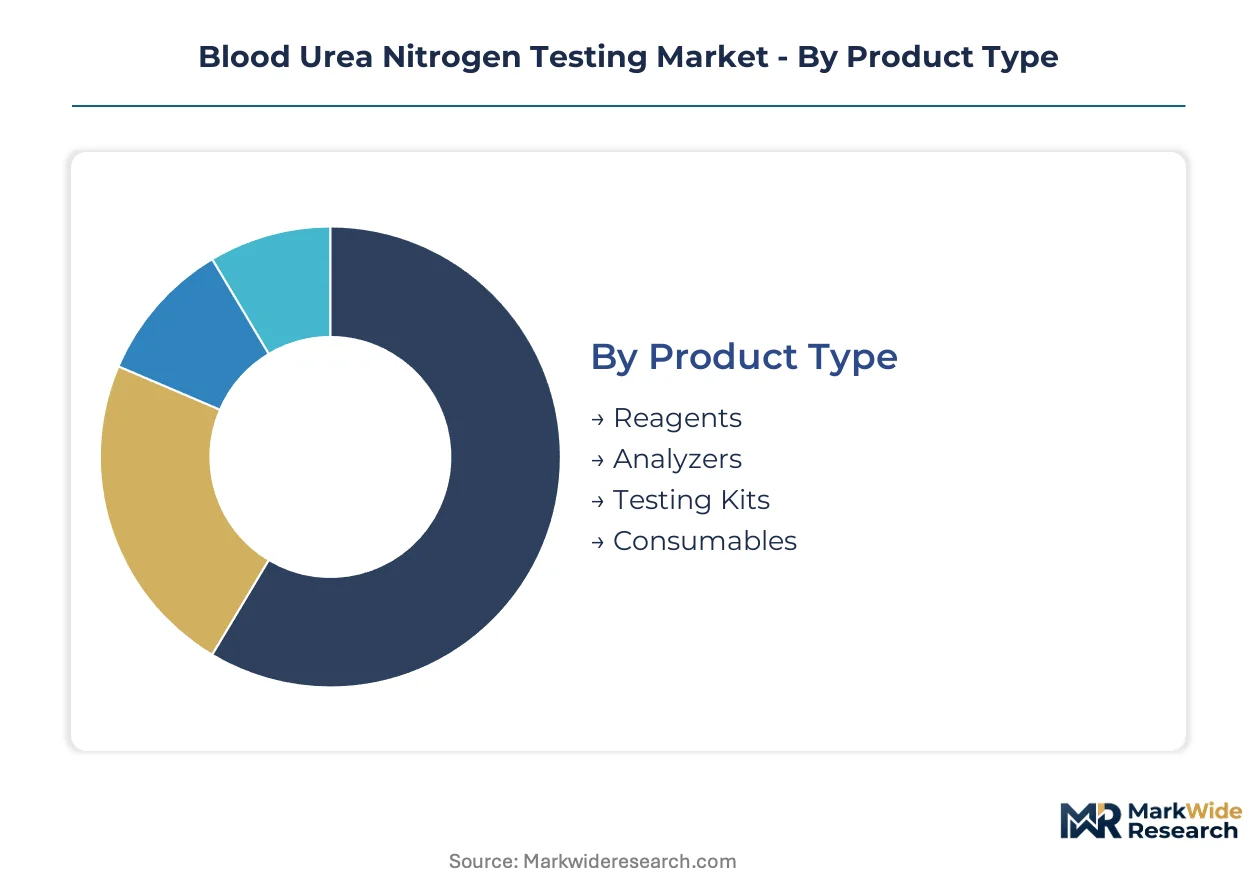
Segmentation in BUN testing reveals how assay formats and platform architectures map to distinct procurement channels and reimbursement pathways. Understanding these splits exposes where manufacturers must build channel-specific capabilities versus where standardization prevails.
Product Type:
Reagent and consumable flows concentrate through high-velocity distribution channels serving hospital core labs, while analyzer placements follow capital equipment sales cycles with extended tender processes.
- Reagents:Liquid-stable enzyme formulations ship in bulk to high-throughput hospital laboratories. German diagnostic networks now mandate lot-to-lot consistency documentation, favoring suppliers with captive fermentation capacity.
- Analyzers:Benchtop and floor-standing chemistry systems anchor core lab workflows. Siemens Healthineers leverages its installed base to sustain reagent pull-through in US hospital systems.
- Testing Kits:CLIA-waived cartridge formats penetrate outpatient clinics with minimal operator training. Abbott Laboratories occupies urgent care workflows through cartridge-based platforms.
- Consumables:Pipette tips, cuvettes, and quality control materials complete assay workflows. Beckman Coulter bundles these into long-term service contracts.
Reagents dominate installed base. Testing kits are where expansion concentrates.
Technology:
Technology selection splits between precision requirements in reference laboratories and operational simplicity in decentralized settings, with enzymatic methods commanding premium positioning.
- Enzymatic:Urease-glutamate dehydrogenase chemistry delivers superior specificity against ammonia interference. US reference laboratories drive replacement of older methods.
- Colorimetric:Berthelot-based assays retain cost-sensitive volume in emerging markets and veterinary applications. The method suffers cross-reactivity with ammonia-containing samples.
- Electrochemical:Ion-selective electrodes enable point-of-care BUN measurement with fingerstick sample volumes. Home dialysis monitoring represents the emerging demand channel.
- Spectrophotometric:UV absorbance methods serve specialized research and pharmaceutical quality control applications. Academic medical centers maintain these for method comparison studies.
Enzymatic platforms anchor precision tiers. Electrochemical formats are climbing the fastest.
End User:
End-user segmentation tracks the decentralization of renal function assessment from centralized hospital laboratories toward outpatient and home-based channels.
- Hospitals:Core laboratories process BUN as part of comprehensive metabolic panels. CLIA-waived certification requirements are compressing point-of-care expansion within these walls.
- Diagnostic Labs:Regional reference networks consolidate specimen processing from multiple health systems. German outpatient nephrology clinics now mandate rapid BUN panels.
- Home Care Settings:Fingerstick-capable microfluidics open direct-to-patient channels for dialysis self-management. FDA guidance on point-of-care data interoperability shapes platform selection.
- Outpatient Clinics:Urgent care and nephrology practices adopt cartridge-based systems for same-day results. The EU In Vitro Diagnostic Regulation enforces post-market surveillance for CE-marked assays.
Hospitals retain volume concentration. Diagnostic labs are gaining share fastest.
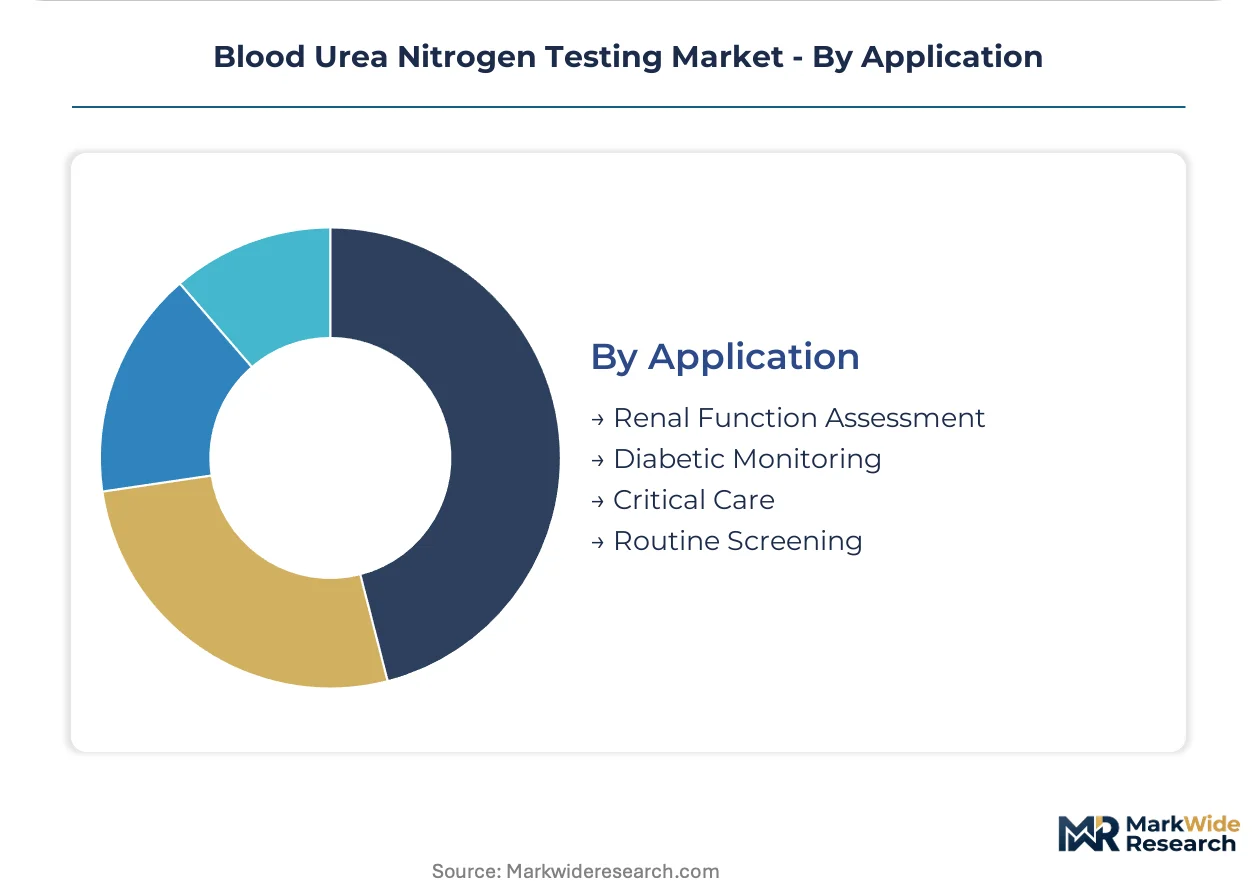
Application:
Application demand reflects how clinical protocols unbundle renal panels and prioritize specific biomarkers for distinct patient management pathways.
- Renal Function Assessment:BUN-to-creatinine ratios guide acute kidney injury staging and chronic kidney disease progression. German protocols now standardize rapid panel integration.
- Diabetic Monitoring:Urea clearance metrics supplement glucose control assessment in nephropathy screening. Medicare Advantage networks drive specificity requirements.
- Critical Care:Rapid turnaround BUN guides fluid resuscitation and dialysis timing in ICU settings. Point-of-care platforms with native LIS integration capture this demand.
- Routine Screening:Annual physical examinations and pre-operative assessments generate high-frequency reorder cycles. Health system protocols increasingly displace standalone BUN with eGFR calculations.
Renal function assessment anchors clinical utility. Critical care represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme fermentation capacity and CLIA-waived assay manufacturing cluster in Germany, the United States, and Japan, with secondary production nodes emerging in South Korea and Switzerland for point-of-care consumables.
United States
Hospital laboratories drive reagent volume through high-frequency metabolic panel reorder cycles. FDA 510(k) clearance pathways and CLIA complexity categorization shape product design priorities for domestic manufacturers. The Boston-Cambridge corridor anchors point-of-care platform development, with cartridge-based systems penetrating urgent care networks.
Germany
Outpatient nephrology clinics mandate rapid BUN panels for chronic kidney disease staging protocols. The EU In Vitro Diagnostic Regulation enforces post-market surveillance and performance documentation for CE-marked assays entering diagnostic labs. The Rhine-Main cluster around Frankfurt consolidates reference laboratory networks preferring MDR-compliant suppliers.
Japan
MetI guidelines on point-of-care connectivity standards determine platform selection for decentralized renal monitoring. PMDA regulatory frameworks prioritize enzymatic specificity in reimbursement coding. The Kansai region around Osaka maintains precision-tier chemistry analyzer manufacturing for domestic hospital systems.
Switzerland
Swissmedic oversight of IVD quality management systems attracts CE-marking operations for cartridge-based assays targeting EU markets. The Basel-Zurich corridor concentrates diagnostic reagent formulation expertise. Cantonal hospital procurement networks standardize around enzymatic methods with documented ammonia interference resistance.
South Korea
MFDS fast-track approval pathways for CLIA-equivalent waived complexity assays accelerate point-of-care platform launches. The Seoul Capital Area integrates rapid BUN testing into dialysis center self-management protocols. Pangyo Techno Valley hosts microfluidic cartridge development for fingerstick-capable home monitoring systems.
Blood Urea Nitrogen Testing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with enzymatic precision commanding premium positioning while colorimetric methods retain emerging market volume. The vendor base splits between consolidated hospital core lab incumbents and specialized point-of-care entrants. Three archetypes dominate: analyzer-reagent integrated systems, cartridge-based platform specialists, and enzyme production backward-integrated suppliers. Competitive moves concentrate on M&A for fermentation capacity and strategic partnerships for connectivity-enabled platform architectures.
Among diversified diagnostics conglomerates, Roche Diagnostics and Siemens Healthineers exemplify the analyzer-reagent integrated archetype, leveraging installed base scale for reagent pull-through. Danaher Corporation occupies a position within the precision-tier supply chain through enzyme and consumable backward integration. Abbott Laboratories represents the cartridge-based platform specialist model, with minimal-training workflows penetrating outpatient clinic channels.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Beckman Coulter |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Randox Laboratories |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and CLIA complexity categorization simultaneously gate supplier qualification and stratify price tiers across hospital core labs, urgent care networks, and home monitoring channels. This regulatory architecture compresses margins for non-compliant vendors while rewarding enzyme manufacturers with backward-integrated fermentation capacity.
Pricing Analysis
CLIA complexity categorization dictates the pricing tier structure across the BUN testing landscape. Three-tier pricing separates FDA-cleared enzymatic platforms from CLIA-waived cartridge systems and cost-sensitive colorimetric assays. Price differentiation centers on certification grade and captive enzyme production, with ammonia interference resistance commanding premium positioning. Pricing pressure stems from reference laboratory consolidation and eGFR substitution protocols displacing standalone BUN orders. Diagnostic labs exhibit highest price sensitivity due to reimbursement compression, while critical care settings prioritize turnaround speed over unit cost.
Supply Chain Analysis
Germany, the United States, and Japan anchor enzyme fermentation capacity for urease and glutamate dehydrogenase production. Supply draws from specialized fermentation facilities with lot-to-lot consistency documentation mandated by German reference networks and EU MDR post-market surveillance requirements. Raw material dependencies include microbial fermentation substrates, chromatography resins, and stabilizer chemistries. Single-source vulnerability concentrates in urease-producing strains held by backward-integrated diagnostics conglomerates. Distribution runs through regional reference laboratory networks, GPO contracts, and direct-to-clinic cartridge replenishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as LIS interoperability and cloud-native architectures determine which assay formats capture decentralized renal monitoring contracts. Cartridge-based systems with native connectivity integration are displacing wet chemistry batch processing across outpatient networks.
For Market Incumbents: Shield core lab reagent pull-through by deepening captive enzyme fermentation capacity and securing long-term GPO contracts with hospital systems. Siemens Healthineers and Roche Diagnostics must accelerate CLIA-waived cartridge development to counter Abbott Laboratories' urgent care penetration. Analyzer-reagent lock-in represents the priority defensive lever against point-of-care platform specialists. For New Entrants and Emerging Players: Home dialysis self-management protocols present the most penetrable white-space target, with fingerstick-capable microfluidics enabling direct-to-patient channels where remote reimbursement codes exist. South Korean and Swiss microfluidic specialists should pursue MFDS fast-track and Swissmedic CE-marking pathways simultaneously. Go-to-market execution requires partnerships with dialysis center networks and nephrology clinic chains rather than hospital system incumbency battles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cartridge platform developers possessing CLIA-waived FDA clearances but lacking global distribution infrastructure. Long-term viability over a five-to-ten year horizon hinges on connectivity-enabled LIS integration and MDR compliance documentation for EU market access. The signal to monitor is CMS reimbursement code expansion for home-based renal monitoring, which would trigger accelerated consolidation of point-of-care platform specialists.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Assay Development | FDA 510(k) clearance for waived complexity expands addressable testing sites beyond hospital core labs. |
| Backward Integration into Enzyme Production | Captive urease fermentation capacity secures supply continuity and lot-to-lot consistency documentation for German reference networks. |
| Cloud-Native LIS Integration | FDA guidance on point-of-care data interoperability creates first-mover advantage for platforms with native hospital system connectivity. |
| MDR Compliance Investment | EU In Vitro Diagnostic Regulation enforcement consolidates preferred vendor lists around post-market surveillance-capable suppliers. |
| Veterinary Assay Adaptation | Companion animal renal panel crossover accesses underpenetrated specialty clinic segments with minimal R&D retooling. |
Study Parameters
The analysis maps enzymatic, colorimetric, electrochemical, and spectrophotometric assay technologies, each validated through hospital laboratory directors, nephrology clinic administrators, diagnostic network procurement managers, and IVD regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR vigilance reporting systems, CMS reimbursement code filings, and GPO contract disclosure records. Bottom-up segment sizing triangulated with top-down market consolidation assessments.
Consistency checks validated volume and value outputs against installed base estimates from chemistry analyzer manufacturers and reagent shipment data from regional distribution networks. The analytical framework modeled technology, end-user channel, application, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure trends and chronic kidney disease prevalence trajectories. Forecast inputs incorporated CLIA-waived test volume expansion, reference laboratory network consolidation patterns, and point-of-care connectivity adoption curves.
Forecasts assume regulatory continuity in FDA 510(k) pathways, CLIA complexity frameworks, and EU MDR enforcement; material policy shifts in reimbursement coding or IVD classification would require re-modeling. Recalibration cycles align with material shifts in connectivity standards, enzyme supply disruptions, or eGFR protocol substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market