
 H. Pylori (Helicobacter Pylori) Test Market | 2026-2036
H. Pylori (Helicobacter Pylori) Test Market Size, Share, and Industry Trends Forecast 2026-2036
H. Pylori (Helicobacter Pylori) Test Market Foresight
Subscription-based reagent rental programs for molecular diagnostic platforms is consolidating purchasing power among high-volume laboratories. Abbott Laboratories leverages its installed base of automated immunoassay systems to sustain recurring revenue streams across hospital networks. Thermo Fisher Scientific competes through integrated PCR workflow bundles that anchor laboratory loyalty and reduce per-test operational variability.
H. pylori testing encompasses serological, breath-based, stool antigen, and endoscopic histopathological methods designed to detect active infection, confirm eradication, or support epidemiological surveillance. Polymerase chain reaction and enzyme-linked immunosorbent assay technologies dominate the technology landscape, with PCR-based methods commanding premium positioning due to superior specificity and antimicrobial resistance profiling capabilities. Diagnostic laboratories represent the most concentrated end-user segment, while home care stool antigen collection kits represent the fastest-growing channel as patients seek alternatives to clinic-based urea breath testing.
The FDA governs in vitro diagnostic premarket pathways and clinical laboratory improvement amendments that determine test complexity classifications and point-of-care eligibility. The Centers for Medicare and Medicaid Services reimbursement schedules directly shape laboratory willingness to adopt newer molecular platforms over established immunoassay menus. Stakeholders must monitor evolving antimicrobial stewardship guidelines from professional gastroenterology societies, as these protocols increasingly mandate susceptibility testing before first-line triple therapy initiation.
Market Dynamics
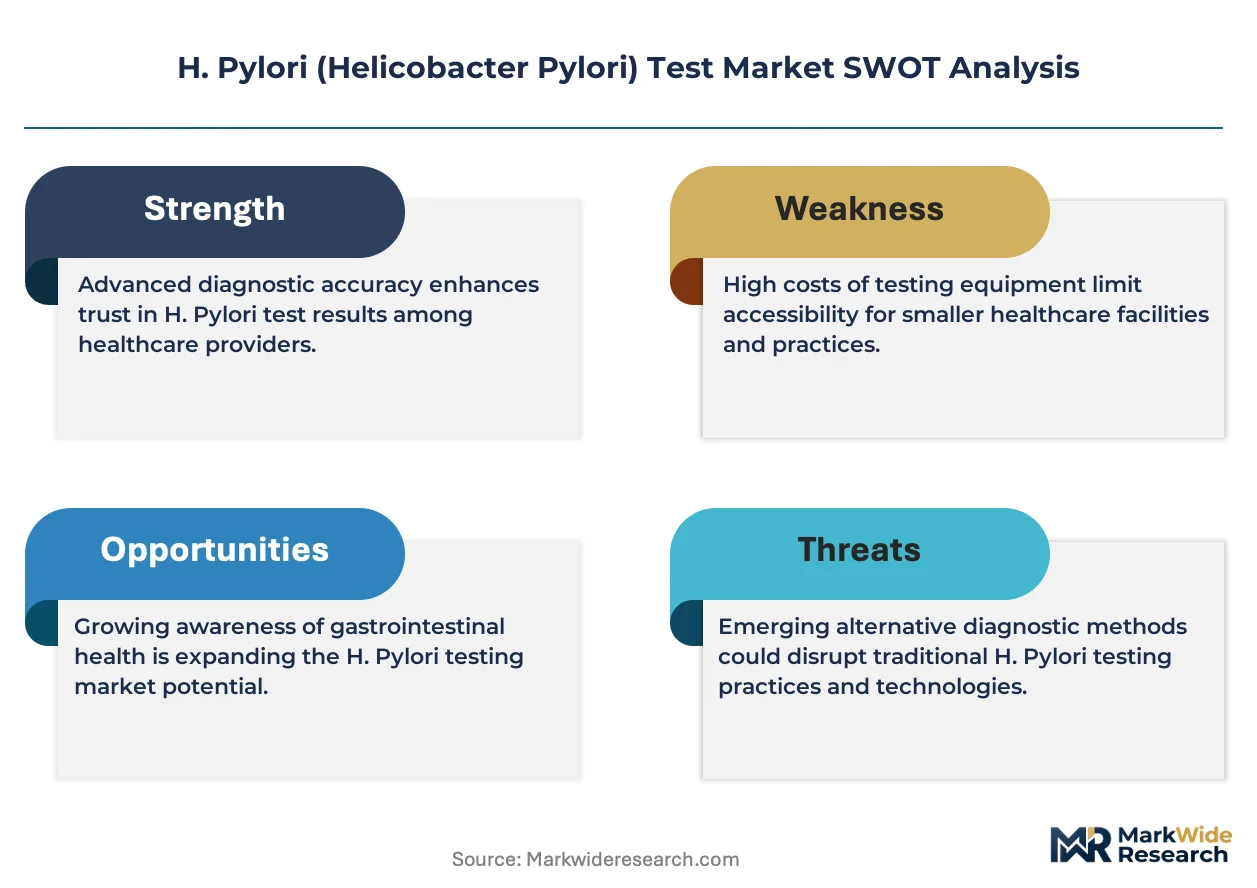
Non-invasive stool antigen and urea breath methods are systematically displacing endoscopy for initial H. pylori detection, restructuring laboratory workflows and capital allocation across diagnostic networks.
Growth Catalysts
- CLIA Complexity Reclassification:The FDA's updated in vitro diagnostic guidance lowers barriers for moderate-complexity molecular platforms, accelerating PCR adoption in hospital laboratories.
- Antimicrobial Stewardship Mandates:Professional gastroenterology societies now require susceptibility testing before triple therapy, driving demand for resistance-profiling capabilities.
- Aging Demographics:Elevated gastric cancer screening protocols among patients over 50 sustain per-capita testing volumes in high-income healthcare systems.
Market Restraints
- Reimbursement Compression:CMS schedule stagnation limits laboratory willingness to retire legacy immunoassay menus for premium molecular alternatives.
- Serological Test Obsolescence Risk:Antibody-based methods cannot distinguish active from past infection, creating stranded inventory across smaller clinical sites.
- Supply Concentration in Reagent Manufacturing:PCR master mix production clusters in Germany and the United States, exposing networks to single-source dependency.
Strategic Opportunities
- Home Collection Channel Expansion:Self-administered stool antigen kits bypass clinic-based urea breath logistics, capturing patient preference for privacy and convenience.
- Resistance Surveillance Integration:Combining PCR detection with metronidazole and clarithromycin susceptibility panels aligns with WHO antimicrobial stewardship frameworks.
- Subscription Reagent Rental Models:High-volume laboratories consolidate purchasing power through instrument placement contracts with per-test consumable commitments.
Industry Challenges
- Cross-Platform Standardization Delays:Absence of harmonized cut-off values between stool antigen ELISA and lateral flow formats complicates multi-site clinical trials.
- Molecular Technologist Shortage:PCR workflow expertise concentrates in academic medical centers, constraining community laboratory expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H. Pylori (Helicobacter Pylori) Test Market |
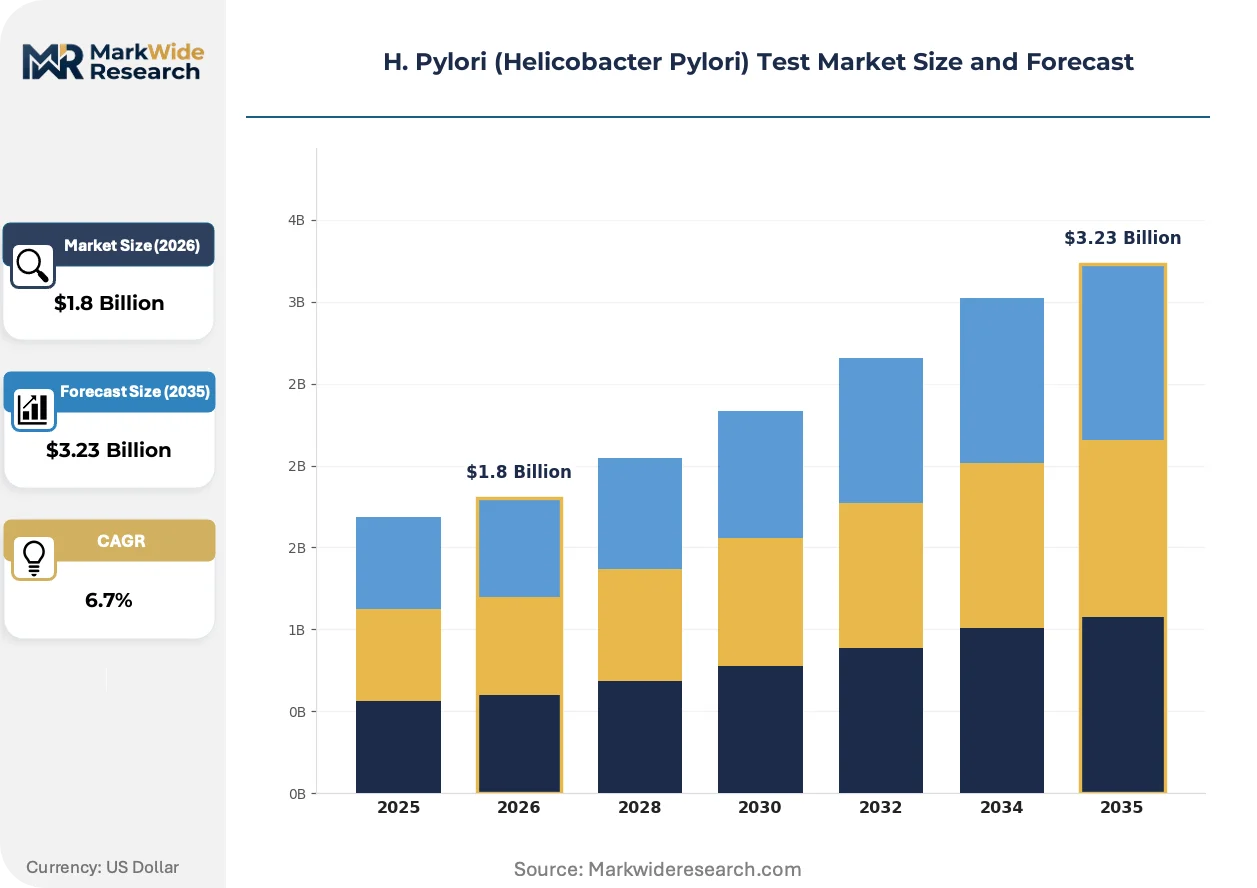
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serology Tests, Urea Breath Tests, Stool Antigen Tests, Endoscopy Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Rapid Antigen Detection, Culture Method End User: Hospitals, Diagnostic Laboratories, Home Care, Specialty Clinics Application: Diagnosis, Treatment Monitoring, Research, Epidemiological Studies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Thermo Fisher Scientific Inc., bioMérieux SA, Bio-Rad Laboratories, Inc., Siemens Healthineers AG, Meridian Bioscience, Quest Diagnostics Incorporated, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H. Pylori (Helicobacter Pylori) Test Market Shifts & Advancements
Digital connectivity and automated sample-to-answer systems are compressing turnaround times while regulatory pressure on antimicrobial resistance reporting reshapes test menu priorities.
Next-generation sequencing is rewriting H. pylori genotyping economics. Reference laboratories in the United States and Japan adopt targeted amplicon panels for virulence factor profiling. This capability is compressing the timeline from detection to tailored eradication regimens.
REACH restrictions on laboratory chemical reagents are forcing reformulation of histopathological staining protocols across European diagnostic networks. Manufacturers accelerate lyophilized reagent development to maintain CE marking compliance. Histology laboratories in Germany and France face the steepest transition costs.
Patient-directed test ordering is fragmenting traditional referral pathways. Direct-to-consumer stool antigen platforms bypass primary care gatekeepers in urban United States markets. Gastroenterology practices respond by unbundling consultation from diagnostic interpretation services.
H. Pylori (Helicobacter Pylori) Test Market Segmentation
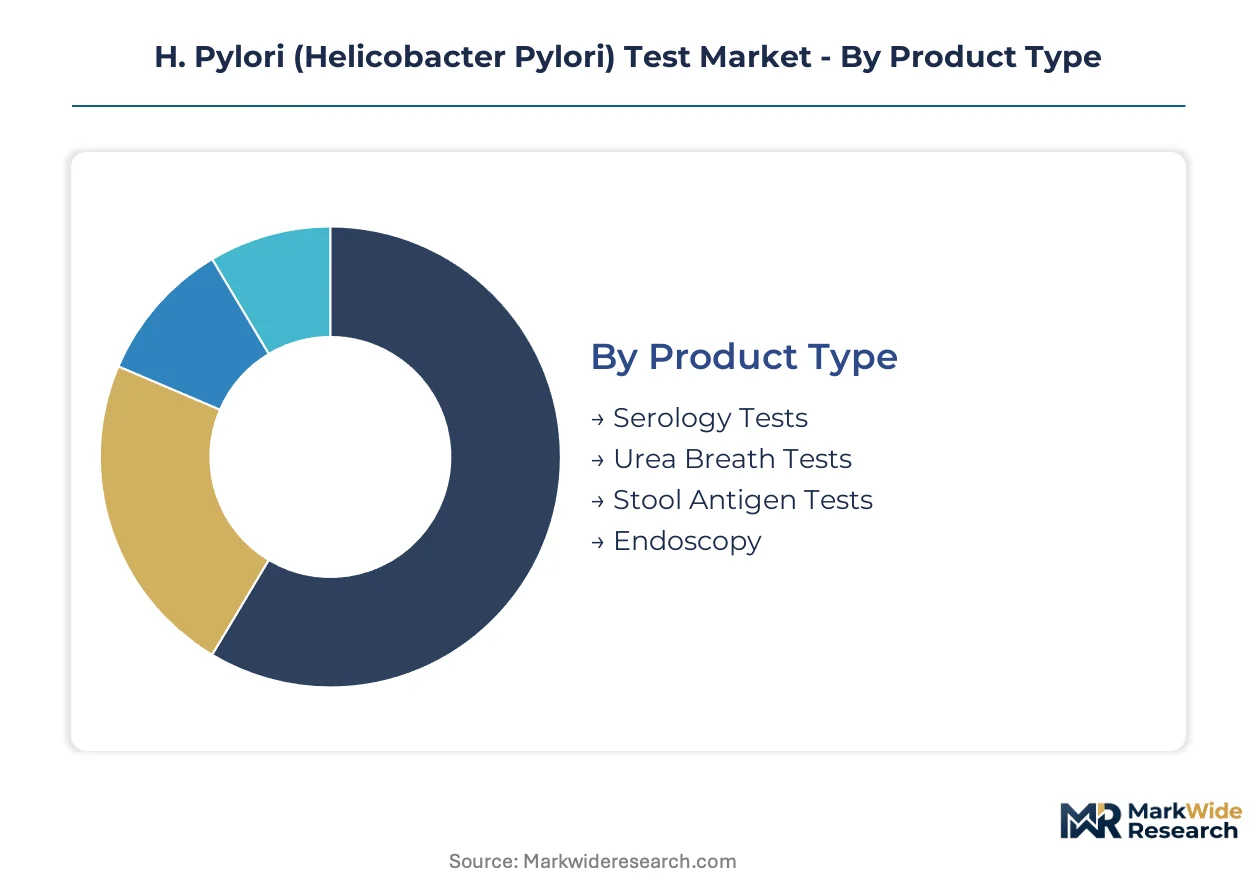
Test format selection in H. pylori diagnostics hinges on regulatory classification complexity, reimbursement eligibility, and laboratory infrastructure capabilities. Segmentation reveals how FDA CLIA tiers and CMS coding decisions channel purchasing toward specific technology-platform combinations across care settings.
Product Type:
FDA 510(k) pathways and CLIA complexity ratings determine which formats reach moderate-complexity hospital laboratories versus waived point-of-care environments.
- Stool Antigen Tests:Enzyme immunoassay and lateral flow formats detect H. pylori antigens in fecal specimens with high specificity for active infection. Diagnostic laboratories in the United States favor these for initial screening due to specimen stability and lower per-test operational burden compared to breath-based alternatives.
- Urea Breath Tests:Carbon-13 or carbon-14 labeled urea assays measure bacterial urease activity through breath sample analysis, offering non-invasive detection with same-day turnaround. Hospital outpatient departments concentrate demand where on-site mass spectrometry or infrared spectroscopy infrastructure supports rapid patient throughput.
- Serology Tests:Antibody detection via serum or whole blood cannot distinguish active from past infection, limiting utility to epidemiological screening.
- Endoscopy:Histopathological examination of gastric biopsies remains the reference standard for complicated cases requiring mucosal assessment.
Stool antigen tests sit at the top of the volume ranking, with urea breath methods climbing the fastest as hospital networks invest in point-of-care metabolic analyzers.
Technology:
Capital intensity and reagent cost structures stratify adoption across academic medical centers, community hospitals, and reference laboratories.
- Polymerase Chain Reaction:Nucleic acid amplification enables detection with simultaneous clarithromycin and fluoroquinolone resistance mutation profiling. Academic medical centers in the United States and Japan anchor demand where antimicrobial stewardship protocols mandate susceptibility-guided therapy selection.
- Enzyme-Linked Immunosorbent Assay:Colorimetric or chemiluminescent signal detection dominates high-throughput stool antigen and serology workflows. Community hospital laboratories standardize on automated ELISA platforms to minimize technologist hands-on time and reduce batch-to-batch variability.
- Rapid Antigen Detection:Immunochromatographic lateral flow devices deliver qualitative results without instrumentation.
- Culture Method:Antimicrobial susceptibility testing via agar dilution or E-test remains confined to reference laboratories.
ELISA platforms command the highest installed base, while PCR methods gain share fastest through resistance-panel bundling.
End User:
Procurement authority and reimbursement capture determine which channels sustain premium pricing versus commodity test economics.
- Diagnostic Laboratories:High-volume centralized processing of stool antigen and PCR panels generates recurring reagent revenue through long-term analyzer placement contracts. National reference networks in the United States leverage scale to negotiate favorable CMS reimbursement rates for molecular complexity tiers.
- Home Care:Self-collection stool antigen kits bypass clinic logistics and capture patient preference for privacy. Direct-to-consumer channels in urban United States markets expand fastest as telehealth platforms integrate test ordering with remote consultation.
- Hospitals:Integrated delivery networks balance inpatient rapid testing against outpatient laboratory send-out economics.
- Specialty Clinics:Gastroenterology practices concentrate urea breath testing for immediate result delivery during consultation.
Diagnostic laboratories generate the highest absolute test volumes, with home care channels expanding most quickly through e-commerce distribution partnerships.
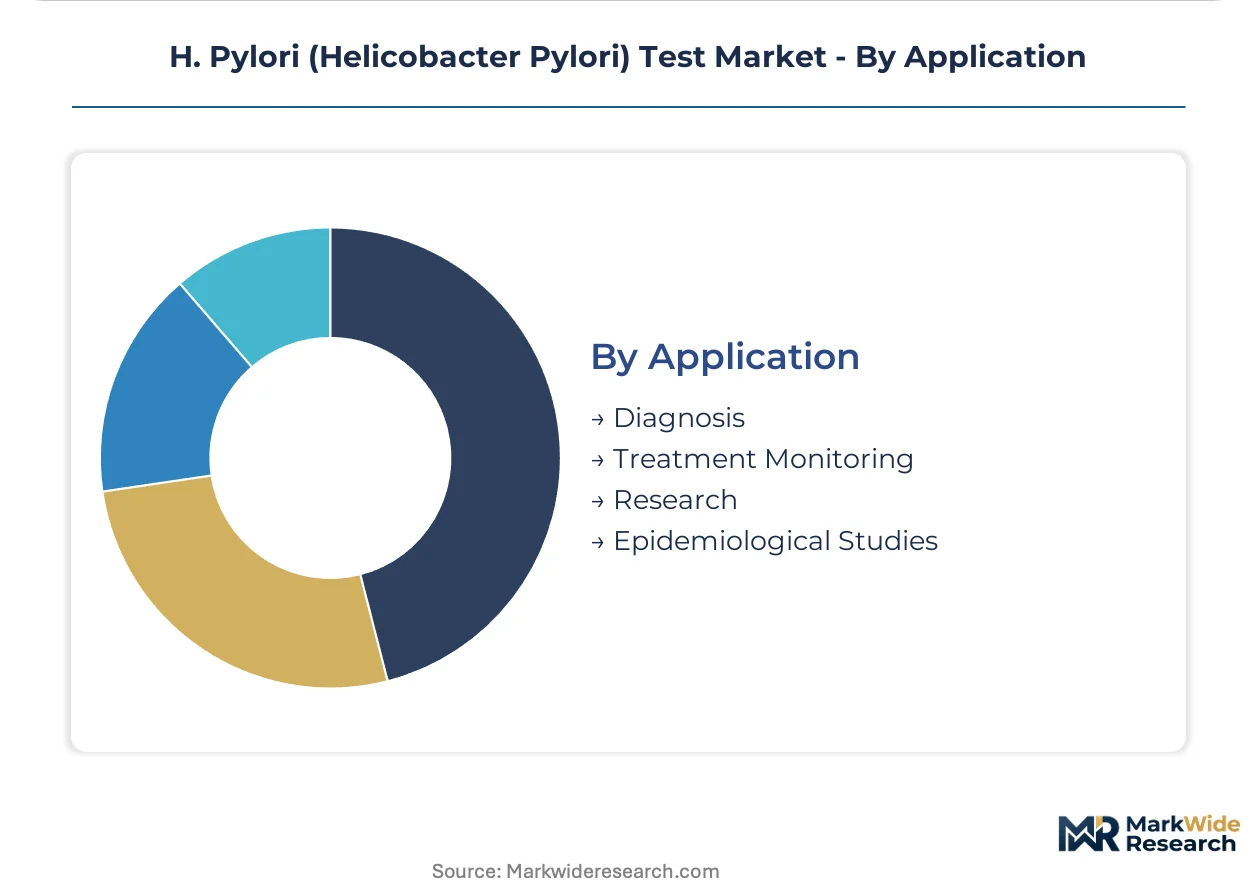
Application:
Clinical utility and regulatory evidence requirements differentiate reimbursable diagnostic use from research and surveillance funding streams.
- Diagnosis:Initial infection detection drives the majority of stool antigen and urea breath test consumption. Primary care protocols in the United States mandate non-invasive confirmation before referral for eradication therapy.
- Treatment Monitoring:Test-of-cure requirements four weeks post-therapy sustain repeat testing demand. Gastroenterology societies mandate urea breath or stool antigen methods over serology to confirm bacterial clearance.
- Research:Academic investigations into virulence factors and vaccine development utilize specialized PCR genotyping.
- Epidemiological Studies:Population-level prevalence surveillance relies on cost-minimized serological screening.
Diagnosis accounts for the dominant share of procedure volume, with treatment monitoring applications gaining momentum fastest through guideline-mandated confirmation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping H. pylori test manufacturing footprints as REACH compliance costs in Europe push reagent production toward jurisdictions with lower chemical-handling burdens. Laboratories in high-compliance regions now import finished diagnostic kits while maintaining local validation and distribution infrastructure.
United States
Aging demographics and gastric cancer screening protocols among patients over 50 sustain elevated per-capita testing volumes. FDA CLIA complexity reclassifications accelerate PCR platform adoption in hospital laboratories seeking moderate-complexity molecular workflows. Reference networks in Boston and San Diego concentrate antimicrobial resistance profiling capacity for stewardship-guided therapy selection.
Germany
ECHA REACH restrictions on laboratory chemical reagents force histopathological staining protocol reformulations across diagnostic networks. Manufacturers accelerate lyophilized reagent development to maintain CE marking compliance. Histology laboratories in Munich and Frankfurt face the steepest transition costs as they migrate from wet chemistry to stabilized formats.
Japan
PMDA streamlined approval pathways for in vitro diagnostics compress time-to-market for PCR-based resistance panels. METI antimicrobial stewardship frameworks mandate susceptibility testing before first-line triple therapy initiation. Academic medical centers in Tokyo and Osaka anchor next-generation sequencing adoption for virulence factor profiling.
China
NMPA medical device classification reforms expand point-of-care eligibility for stool antigen lateral flow devices. Domestic manufacturers in Shanghai and Shenzhen scale automated immunoassay production to capture hospital laboratory consolidation trends. GB standard harmonization with ISO 13485 simplifies export qualification for regional producers.
India
CDSCO medical device rules create compliance tiering that favors imported molecular platforms over domestic kit assembly. BIS quality certification requirements strain smaller diagnostic distributors in Delhi and Mumbai. Telehealth platforms in Bangalore integrate direct-to-consumer stool antigen ordering with remote gastroenterology consultation.
H. Pylori (Helicobacter Pylori) Test Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostic conglomerates commanding hospital laboratory accounts while regional kit assemblers capture price-sensitive clinic volumes. The vendor base organizes into three tiers: multinational platform holders with recurring reagent revenue, mid-scale regional distributors with flexible sourcing, and emerging direct-to-consumer entrants. Consolidation pressures favor instrument placement contracts with per-test consumable commitments over capital sales. Technology licensing and geographic distribution partnerships represent the dominant competitive moves as firms seek CLIA-waived format approvals.
Among Swiss and American platform holders, F. Hoffmann-La Roche Ltd and Abbott Laboratories exemplify the integrated diagnostics archetype through automated immunoassay system penetration. Thermo Fisher Scientific Inc. occupies a position within the molecular workflow bundling segment, anchoring laboratory loyalty through PCR reagent rental programs. These three entities represent contrasting strategic postures: Roche's centralized reference laboratory focus, Abbott's hospital network installed base leverage, and Thermo Fisher's academic medical center resistance-profiling specialization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Bio-Rad Laboratories, Inc. |
| Siemens Healthineers AG |
| Meridian Bioscience |
| Quest Diagnostics Incorporated |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
ECHA REACH restrictions on laboratory chemical reagents gate qualified supply for European diagnostic networks and enforce premium-tier pricing access for manufacturers with lyophilized reagent capabilities. Buyers in Germany and France face elevated procurement costs as wet chemistry formulations lose CE marking eligibility, compressing margins for distributors without reformulation partnerships.
Pricing Analysis
Capacity additions in China are reshaping price floors for automated immunoassay platforms as domestic manufacturers in Shanghai and Shenzhen scale production. Three-tier pricing structure across premium PCR resistance panels, standard ELISA stool antigen kits, and economy lateral flow devices stratifies the market. Cost compression in the economy tier is intensifying because of import tariff exposure on European-sourced reagents. Community hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize resistance-profiling accuracy over per-test economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume analyzer placements with bundled reagent commitments, bypassing distributor markups for integrated delivery networks. PCR master mix production clusters in Germany and the United States, with lyophilized enzyme manufacturing drawing from specialized fermentation facilities in Switzerland and Japan. Supply chain risk centers on single-source dependency for thermostable polymerase enzymes produced at limited GMP-certified sites. Distribution runs through national reference laboratory networks that consolidate purchasing power across hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The H. pylori test market functions as a stable compounder anchored by recurring reagent revenue streams from installed molecular diagnostic platforms. Antimicrobial stewardship mandates sustain replacement demand for resistance-profiling capabilities across academic medical centers.
For Market Incumbents: To counter reimbursement compression from CMS schedule stagnation, consolidate hospital network accounts through instrument placement contracts with per-test consumable minimums. Deepen backward integration into lyophilized reagent manufacturing to maintain CE marking compliance as ECHA REACH restrictions tighten. Prioritize CLIA complexity reclassification petitions for moderate-complexity PCR workflows. For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms represent the most penetrable buyer archetype as urban United States patients bypass primary care gatekeepers. Capture home collection stool antigen demand through e-commerce distribution partnerships with established laboratory networks. Lead with privacy-forward positioning and same-day result delivery guarantees. For Investors and Strategic Acquirers: Roll-up economics work for regional diagnostic distributors with flexible sourcing capabilities because laboratory consolidation trends concentrate purchasing power among fewer high-volume accounts. Target mid-scale kit assemblers with established CLIA-waived format approvals and geographic exclusivity arrangements. Monitor FDA guidance updates on in vitro diagnostic premarket pathways as inflection indicators for platform technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Complexity Reclassification Petition | FDA moderate-complexity approval unlocks hospital laboratory PCR adoption beyond academic centers. |
| Lyophilized Reagent Manufacturing Scale-Up | ECHA REACH compliance preserves European market access for histopathological staining protocols. |
| Direct-to-Consumer Channel Launch | Telehealth integration captures patient preference for privacy in urban United States markets. |
| Resistance Panel Bundling | Clarithromycin and metronidazole susceptibility testing aligns with WHO antimicrobial stewardship frameworks. |
| Hospital System Partnership | Integrated delivery network contracts secure recurring reagent revenue through analyzer placement. |
Research Methodology
Multiple input streams — primary interviews with diagnostic laboratory directors, regulatory affairs specialists at IVD manufacturers, and GPO contracts managers — were reconciled against secondary validation from FDA 510(k) filings, CMS reimbursement schedules, and hospital procurement databases. Conversations with gastroenterology practice administrators and biomedical engineers informed workflow integration assessments. Bottom-up test volume estimates across stool antigen, urea breath, and PCR segments were triangulated with top-down market sizing from instrument placement disclosures.
Historical volume trajectories were cross-referenced against panel input from reference laboratory executives to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated test format, technology platform, end-user channel, and application purpose dimensions. CAGRs were derived from fitted trend analysis of reagent consumption patterns and instrument installed base expansion. Antimicrobial resistance prevalence rates and stewardship guideline adoption timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; diagnostic laboratory and hospital channels carry tighter precision than emerging home care direct-to-consumer volumes. Forecasts reflect assumptions regarding CLIA complexity reclassification timing, CMS reimbursement stability, and ECHA REACH enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market