
 Clinical Trial Kits Market | 2026-2036
Clinical Trial Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Kits Market Intelligence
The shift from single-source to multi-source kit procurement is restructuring supply relationships across clinical trial logistics. Charles River Laboratories leverages its integrated discovery-to-clinic platform to anchor end-to-end kit customization services. Almac Group differentiates through global depots and patient-centric packaging capabilities. Q2 Solutions competes on laboratory-integrated kit design that tightens specimen integrity controls from collection to analysis.
Clinical trial kits are pre-assembled, protocol-specific collections of medical devices, collection containers, transport media, and documentation designed to standardize specimen acquisition and chain-of-custody compliance across geographically dispersed investigational sites. These kits typically incorporate temperature-stabilizing components, tamper-evident seals, and barcoded tracking elements to maintain sample viability and regulatory traceability from patient to analytical laboratory. Blood collection kits dominate current product volume due to universal protocol requirements, while monitoring kits represent the fastest-expanding category as wearable-integrated decentralized trials proliferate. Among end users, contract research organizations capture disproportionate kit procurement volume by aggregating sponsor demand across multiple concurrent studies.
FDA oversight of investigational device exemptions and ICH E6(R2) Good Clinical Practice standards shape kit design, labeling, and distribution compliance obligations for all US-targeted trials. EMA's Clinical Trials Regulation and EU MDR requirements for device components further constrain material selection and supplier qualification pathways for European protocols. Stakeholders must monitor evolving regulatory divergence between FDA decentralized trial guidance and national European competent authority interpretations as they calibrate kit standardization versus regional customization strategies.
Market Dynamics
Decentralized trial infrastructure expansion is forcing kit providers to reconfigure distribution networks for direct-to-patient delivery models. The FDA's risk-based monitoring framework and ICH E6(R2) guidelines are compressing timelines for protocol-specific customization while elevating chain-of-custody documentation requirements.
Growth Catalysts
- Decentralized trial protocols:Direct-to-patient kit delivery eliminates site visits and expands recruitment pools into rural geographies previously excluded from participation.
- FDA risk-based monitoring:The agency's 2013 guidance and subsequent ICH E6(R2) adoption mandate centralized monitoring capabilities that kit-level data capture must support.
- Wearable device convergence:Continuous glucose monitors, activity trackers, and cardiac patches require specialized collection containers with integrated sensor calibration materials.
Market Restraints
- Specialized polymer supply concentration:Medical-grade polypropylene and temperature-stabilizing phase-change materials depend on concentrated petrochemical feedstock suppliers in the US Gulf Coast.
- EMA-EU MDR device component rules:European Medical Device Regulation reclassification of collection needles and lancets triggers new notified body involvement and extended qualification timelines.
- Biological specimen transport substitutes:Local laboratory processing networks in urban clusters reduce dependency on centralized kit-based collection for standard analytes.
Strategic Opportunities
- India clinical trial expansion:CDSCO streamlined approval pathways and regional ethics committee harmonization create demand for temperature-stable kits suited to tropical distribution.
- Cell and gene therapy vectors:Cryogenic collection and liquid nitrogen-compatible packaging for CAR-T and gene editing trials command premium positioning.
- Direct-to-patient pharmacy integration:Partnerships with specialty pharmacy distributors enable kit co-delivery with investigational medicinal products.
Industry Challenges
- Qualified cold chain engineering talent:Thermal packaging design for ultra-low temperature specimens requires scarce expertise in phase-change material selection and container qualification.
- Multi-regulatory label harmonization:Reconciling FDA, EMA, and PMDA labeling requirements for a single kit SKU extends development cycles and inventory complexity.
- Legacy site management system integration:Sponsor and CRO inventory platforms require custom API development for real-time kit tracking visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Kits Market |
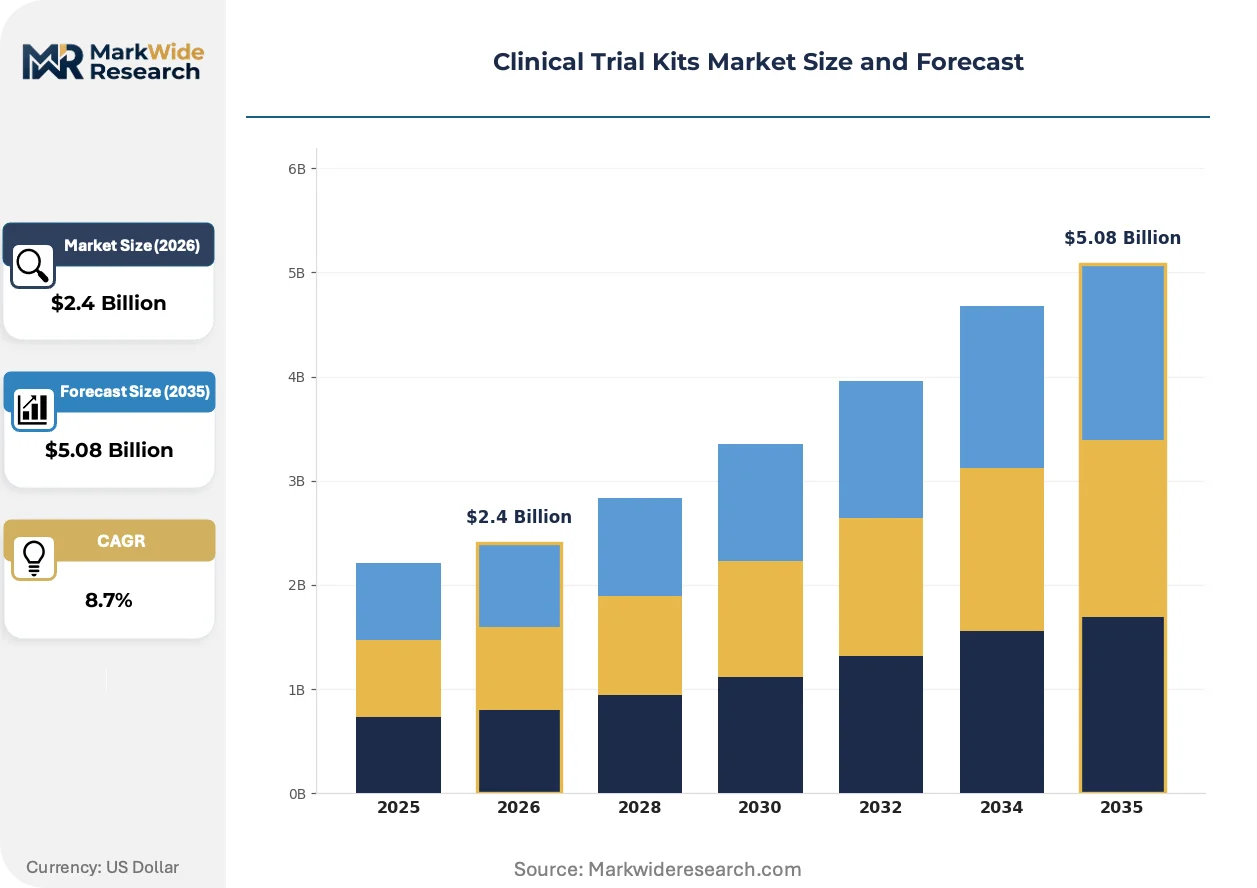
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Collection Kits, Sample Transport Kits, Test Kits, Monitoring Kits End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Diagnostic Laboratories Application: Oncology Trials, Cardiovascular Trials, Infectious Disease Trials, Neurology Trials Distribution Channel: Online, Direct Sales, Distributors, Partnerships |
| Companies Covered | Charles River Laboratories, Almac Group, Brooks Life Sciences (Azenta, Inc.), Cerba Research, Precision Medicine Group, LLC., Patheon (Thermo Fisher Scientific, Inc.), LabConnect, Q2 Solutions, Labcorp Drug Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Kits Market Strategic Shifts & Innovations
Digital tracking technologies and sustainable material substitutions are redefining kit architecture. Temperature integrity verification and patient adherence monitoring now merge into unified data streams.
Near-field communication chips embedded in kit exteriors enable automated receipt confirmation and temperature excursion logging without manual data entry. Large CROs and academic medical centers are piloting NFC-enabled workflows across infectious disease and oncology protocols. This connectivity layer is integrating with sponsor inventory management systems to compress reconciliation cycles from weeks to hours.
EMA's Clinical Trials Regulation harmonization and EU MDR device component requirements are forcing material requalification for European-protocol kits. Suppliers must document full polymer supply chains and sterilization validation to maintain CE marking on collection devices. Oncology and rare disease trials targeting European sites face the steepest compliance recalibration.
Site-less trial models are consolidating procurement authority at sponsor headquarters rather than distributing purchasing to individual investigators. Centralized kit specification and direct-to-patient fulfillment replace site-level vendor selection. This concentration is most visible in US-based biopharma sponsors running multi-continental Phase III programs.
Clinical Trial Kits Market Segmentation
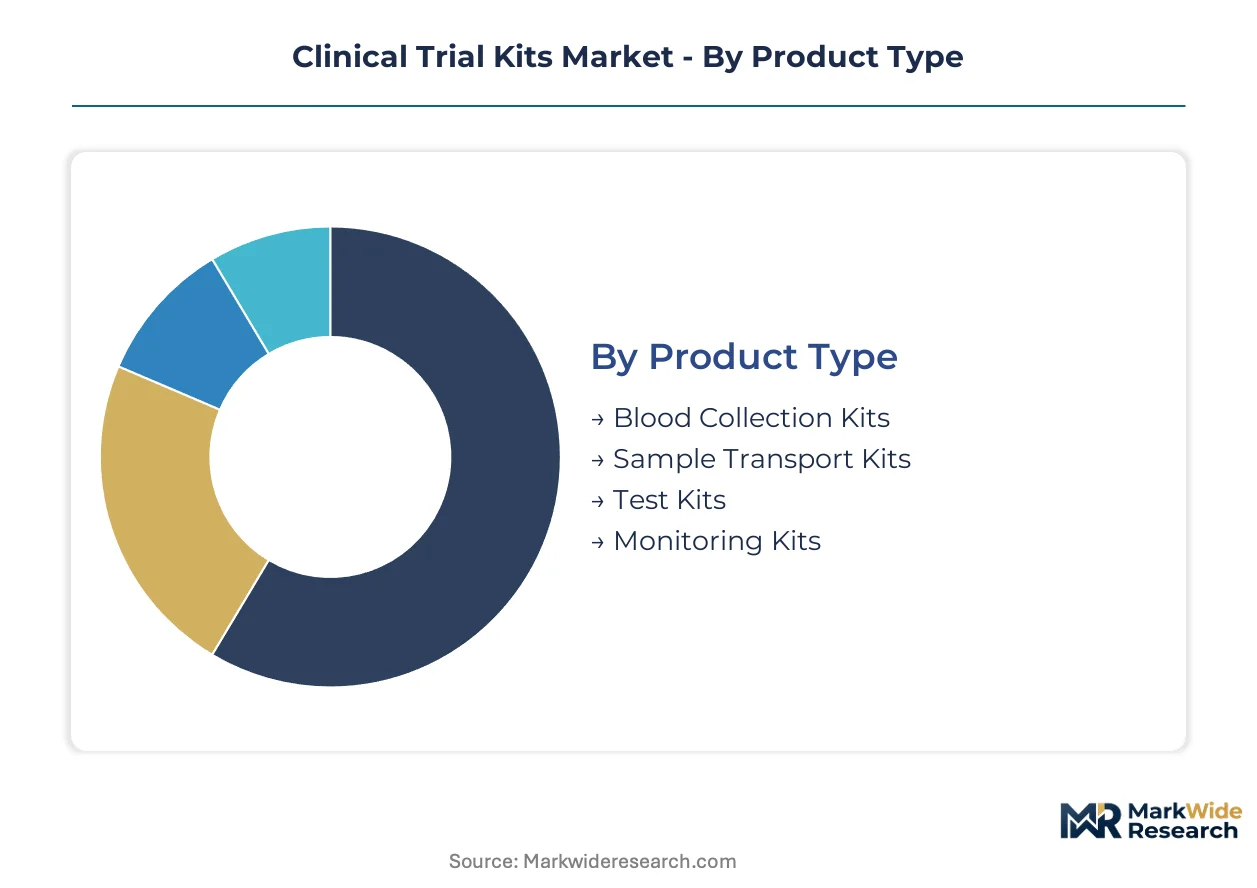
Kit specification varies sharply across trial phases and therapeutic areas. Procurement patterns diverge between centralized sponsor purchasing and distributed site-level ordering. Understanding these segment boundaries illuminates where standardization yields efficiency versus where customization commands premium positioning.
Product Type:
Standardization pressure from ICH E6(R2) compliance competes against protocol-specific customization demands across the product spectrum.
- Blood Collection Kits:Pre-configured assemblies of vacuum tubes, needles, and anticoagulant vials calibrated to specific analyte requirements. Demand concentrates in cardiovascular and metabolic trials across United States biopharma clusters, constrained by FDA device component validation timelines.
- Monitoring Kits:Wearable-integrated containers with sensor calibration materials and continuous data capture documentation. Expansion is steepest in decentralized oncology protocols where patient adherence tracking replaces site visits.
- Sample Transport Kits:Temperature-stabilized packaging with phase-change materials for specimen integrity during multi-day transit. CDSCO-registered trials in India drive tropical-climate engineering requirements.
- Test Kits:Point-of-care diagnostic assemblies for rapid site-level result generation. Research Triangle infectious disease studies prioritize same-day pathogen detection.
Most installed capacity flows through blood collection kits. Expansion is steepest in monitoring kits.
End User:
Procurement authority consolidation distinguishes sponsor-direct purchasing from aggregated CRO demand.
- Contract Research Organizations:Multi-study procurement platforms aggregate kit volumes across concurrent protocols, enabling SKU rationalization and inventory pooling. Boston-based CROs drive standardization for global Phase III programs.
- Pharmaceutical Companies:Sponsor-level specification of kit components ensures protocol-to-protocol consistency for regulatory submission packages. Internal quality teams mandate vendor qualification thresholds that exclude smaller suppliers.
- Research Institutions:Academic medical centers with NIH-funded investigator-initiated studies require flexible small-batch customization. Budget constraints favor modular kit architectures over fully integrated assemblies.
- Diagnostic Laboratories:Reference lab networks processing specimens from multiple trial sites specify collection-to-analysis compatibility. Labcorp and Quest integration requirements influence container dimension standards.
Contract research organizations command the largest procurement volumes. Pharmaceutical companies are gaining share fastest through centralized sourcing mandates.
Application:
Therapeutic area complexity dictates kit sophistication tiers from basic phlebotomy to cryogenic cell therapy handling.
- Oncology Trials:Immuno-oncology protocols require cryogenic collection systems for CAR-T cell preservation and liquid nitrogen-compatible packaging. FDA breakthrough therapy designation timelines compress kit development cycles.
- Infectious Disease Trials:Biosafety level considerations and cold chain requirements for mRNA vaccine studies dominate kit architecture. Tropical field trials in India necessitate extended temperature stability beyond standard 48-hour windows.
- Cardiovascular Trials:Established biomarker panels permit higher kit standardization with modular add-on components for emerging proteomic assays.
- Neurology Trials:Cerebrospinal fluid collection kits with specialized needle gauges and low-volume containers address rare disease population constraints.
Oncology trials absorb the most complex kit engineering resources. Infectious disease trials are expanding most quickly post-pandemic protocol proliferation.
Distribution Channel:
Direct-to-patient fulfillment models are restructuring traditional site-centric logistics networks.
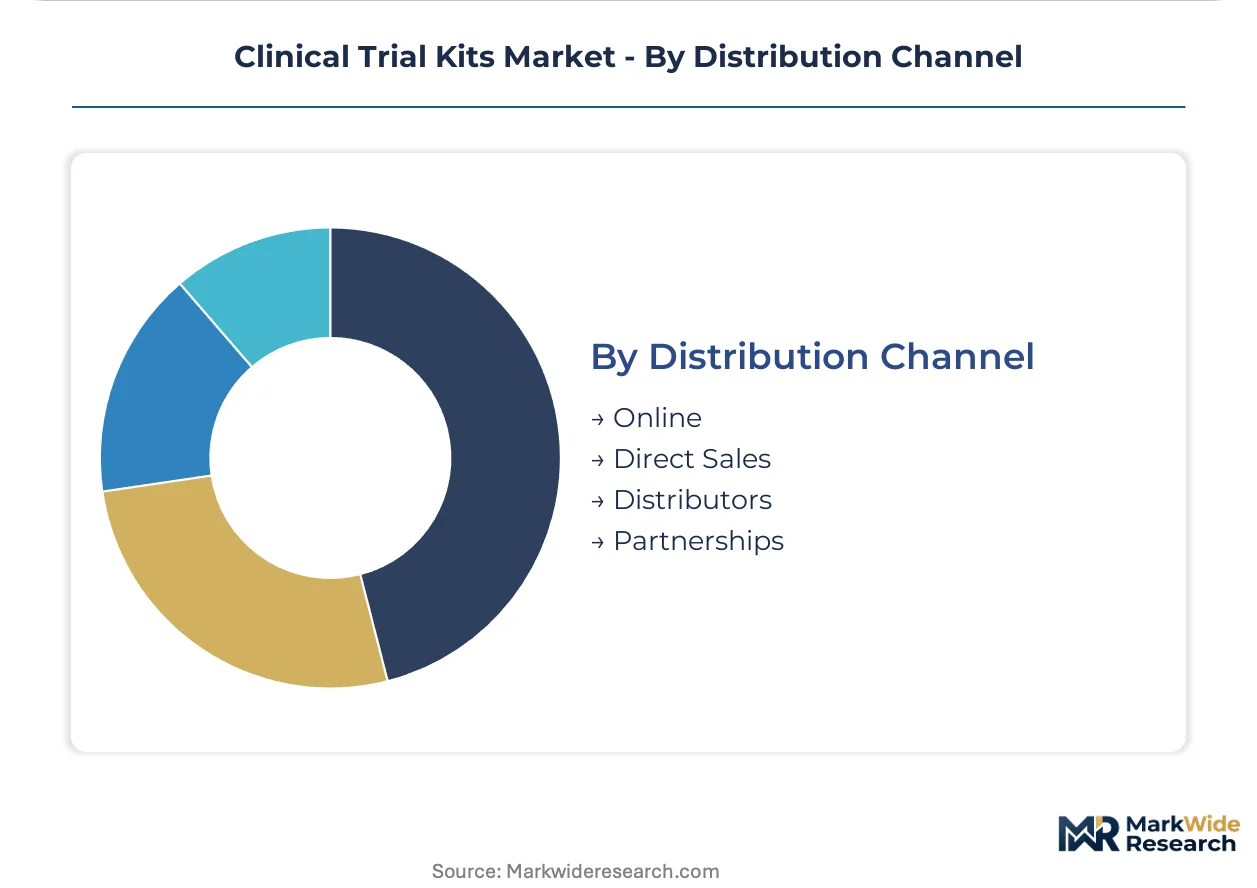
- Direct Sales:Sponsor-to-manufacturer relationships enable protocol-specific customization with dedicated production lines. Large pharmaceutical companies in Boston and Research Triangle bypass intermediary markup for Phase III programs.
- Distributors:Regional logistics providers with temperature-controlled warehousing serve mid-tier sponsors without internal supply chain infrastructure.
- Online:E-procurement platforms with real-time inventory visibility support investigator-initiated studies and adaptive trial amendments.
- Partnerships:Specialty pharmacy co-delivery arrangements integrate investigational medicinal products with corresponding collection kits.
Direct sales channels handle the highest-value customized volumes. Partnership models are climbing the fastest as decentralized trials mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing clinical trial kit production toward jurisdictions with streamlined device approval pathways and lower qualification overhead. Manufacturers are relocating temperature-stabilizing packaging operations to exploit gaps between FDA validation timelines and CDSCO fast-track procedures.
United States
FDA risk-based monitoring mandates and ICH E6(R2) compliance requirements drive kit standardization for decentralized oncology protocols. The agency's breakthrough therapy designation compresses development cycles for CAR-T collection systems. Boston's biopharma corridor anchors end-to-end kit customization demand for Phase III programs.
Germany
EMA Clinical Trials Regulation harmonization and EU MDR device reclassification elevate polymer supply chain documentation burdens. REACH compliance for sterilization additives constrains material substitution flexibility. The Rhine-Ruhr logistics cluster hosts temperature-controlled depots serving pan-European infectious disease trials.
India
CDSCO streamlined approval pathways and regional ethics committee harmonization accelerate kit procurement for tropical field studies. The regulator's tropical climate stability requirements extend standard temperature windows beyond 48 hours. Hyderabad's vaccine manufacturing ecosystem generates adjacent demand for biosafety-level collection containers.
Japan
PMDA decentralized trial guidance and JIS sterilization standards shape kit architecture for Asia-Pacific protocol exports. The regulator's patient-centric packaging requirements influence global design templates. Osaka's medical device cluster specializes in compact collection systems for aging-population neurology studies.
Switzerland
Swissmedic's alignment with FDA and EMA standards positions the country as a regulatory bridge for multi-continental trials. The regulator's precision medicine incentives attract CAR-T and gene editing protocol sponsors. Basel's pharmaceutical headquarters concentration drives sponsor-direct kit specification authority.
Clinical Trial Kits Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cryogenic specialization and direct-to-patient logistics integration. Market structure concentrates around integrated CRO-affiliated suppliers and independent kit specialists with global depot networks. Three archetypes dominate: laboratory-integrated platforms, patient-centric packaging specialists, and temperature-stability engineering boutiques. Capacity expansion and strategic partnerships represent the dominant competitive moves as sponsors consolidate procurement authority.
Within the integrated platform tier, Charles River Laboratories and Q2 Solutions exemplify end-to-end service anchoring. Almac Group occupies a position bridging global depot infrastructure with patient-centric design capabilities. These three entities represent how kit provision is consolidating toward entities capable of spanning discovery-to-clinic workflows while maintaining multi-regulatory label harmonization competence.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Almac Group |
| Brooks Life Sciences (Azenta, Inc.) |
| Cerba Research |
| Precision Medicine Group, LLC. |
| Patheon (Thermo Fisher Scientific, Inc.) |
| LabConnect |
| Q2 Solutions |
| Labcorp Drug Development |
| Others |
Cost & Logistics Intelligence
Cold chain engineering talent concentration in the US Gulf Coast and Rhine-Ruhr corridor creates labor-cost differentials that widen pricing spreads between premium cryogenic kits and standard phlebotomy assemblies. FDA validation timelines and EU MDR reclassification burdens feed into tiered cost structures that sponsors navigate through centralized procurement mandates.
Pricing Analysis
Distributor margin layers compress as sponsor-direct purchasing concentrates procurement authority at headquarters. Three-tier pricing structure across premium cryogenic, standard temperature-controlled, and economy ambient kits reflects customization depth and regulatory documentation burden. Pricing pressure stems from CRO volume aggregation and SKU rationalization programs. Academic medical centers and investigator-initiated studies exhibit highest price sensitivity, while CAR-T sponsors accept premium positioning for liquid nitrogen-compatible packaging.
Supply Chain Analysis
Workforce availability constraints in medical-grade polymer compounding concentrate production in the United States, Germany, and China. Medical-grade polypropylene, phase-change materials, and sterilization-grade resins draw from petrochemical feedstock networks vulnerable to Gulf Coast weather disruptions. Single-source vulnerability in temperature-stabilizing component suppliers elevates qualification risk for European protocol kits. Distribution runs through global depot networks with regional temperature-controlled warehousing, shifting toward direct-to-patient fulfillment as decentralized trials mature.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through cryogenic specialization and direct-to-patient logistics integration, with cost-down pressure from CRO procurement consolidation offset by premium-tier demand for cell and gene therapy vectors.
For Market Incumbents: To counter CRO volume aggregation and sponsor procurement centralization, incumbents should anchor multi-regulatory label harmonization capabilities as a defensive moat while adding captive cold chain engineering capacity in India to exploit CDSCO fast-track timelines and tropical-climate kit demand. For New Entrants and Emerging Players: The price-point gap between premium cryogenic systems and economy blood collection kits creates entry space for mid-tier temperature-stabilized packaging specialists. New entrants should target infectious disease trials in India requiring extended tropical stability windows, leveraging partnerships with regional logistics providers for depot infrastructure without capital-heavy buildout. For Investors and Strategic Acquirers: Large CROs and laboratory-integrated platforms are the most active acquirers in this space, consolidating kit provision toward end-to-end service anchoring. Acquisition targets should display cryogenic engineering competence or direct-to-patient fulfillment integration. Watch FDA decentralized trial guidance evolution as the signal indicating inflection toward site-less procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Label Harmonization | Compresses development cycles for sponsors running FDA-EMA-PMDA concurrent trials. |
| Cryogenic Packaging Engineering Buildout | Captures premium positioning in CAR-T and gene editing protocol expansion. |
| Direct-to-Patient Logistics Integration | Aligns kit fulfillment with decentralized trial infrastructure requirements. |
| India Depot Network Expansion | Exploits CDSCO streamlined pathways for tropical-climate stability demand. |
| CRO Procurement Platform Partnership | Secures volume aggregation access through multi-study kit specification authority. |
Research Approach
Multiple input streams — regulatory filing databases, sponsor procurement system disclosures, and cold chain engineering qualification records — were reconciled against secondary validation from trade customs data and clinical trial registry entries. Primary interviews with kit procurement managers at CROs, regulatory affairs leads at pharmaceutical sponsors, depot operations directors, and biomedical engineers at academic medical centers were cross-referenced with FDA device registration filings, EMA Clinical Trials Regulation guidance documents, CDSCO approval pathway records, and ICH E6(R2) implementation case studies. Bottom-up kit volume estimates and top-down market sizing were triangulated for consistency.
Historical shipment patterns were cross-referenced against panel input from supply chain executives to anchor projection trajectories across the analysis window. Segmentation modeling incorporated product type complexity tiers, end-user procurement authority structures, therapeutic area kit sophistication requirements, and regional regulatory cluster divergence. CAGRs were derived from protocol volume growth assumptions and kit value-per-trial expansion factors, with specific weighting for decentralized trial adoption curves and cell therapy protocol proliferation.
Caveats apply where FDA decentralized trial guidance evolution, EU MDR device reclassification timelines, or CDSCO regulatory harmonization shifts could materially shift the outlook. Forecasts embed assumptions about sponsor procurement centralization momentum and CRO consolidation patterns that remain contingent on clinical trial funding environments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market