
 Tumor Marker Testing Market | 2026-2036
Tumor Marker Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Marker Testing Market Analytics
The capability gap between automated high-throughput platforms and manual benchtop workflows is redrawing competitive boundaries in tumor marker testing. F. Hoffmann-La Roche Ltd leverages its installed base of cobas analyzers to sustain recurring revenue streams across major hospital networks. Abbott anchors its position through point-of-care immunoassay systems that extend access beyond centralized labs. Thermo Fisher Scientific competes by supplying end-to-end PCR and NGS workflows that integrate sample prep with analytics.
Tumor marker testing encompasses laboratory and point-of-care methods that detect cancer-associated proteins, genes, or metabolites in blood, tissue, or other biospecimens, typically achieving sensitivity thresholds in the nanogram-per-milliliter range for serum-based assays. These tests serve primary purposes of cancer screening, differential diagnosis, prognosis stratification, and therapy response monitoring across oncology care pathways. ELISA-based platforms still occupy the largest installed base for routine protein marker quantification, while next-generation sequencing applications are expanding fastest as oncologists demand comprehensive genomic profiling from single specimens. Hospitals represent the most mature end-user channel with established reimbursement, though diagnostic laboratories are capturing margin pools through specialized esoteric testing menus that command premium pricing.
FDA premarket review under the in vitro diagnostics framework and CLIA laboratory certification requirements shape product development timelines and commercial access for tumor marker assays in the United States. EMA's In Vitro Diagnostic Regulation in Europe imposes stricter clinical evidence standards and post-market surveillance obligations that filter smaller manufacturers from the market. Stakeholders must monitor evolving payer coverage policies for liquid biopsy applications and prepare for parallel regulatory submissions across multiple jurisdictions as companion diagnostic requirements tighten.
Market Dynamics
Multiplexed assay platforms are compressing testing economics by enabling simultaneous detection of protein and genomic markers from single specimens, forcing laboratories to consolidate vendor relationships around integrated workflow providers rather than maintaining fragmented point solutions.
Growth Catalysts
- CLIA laboratory certification expansion:Diagnostic laboratories in the United States are leveraging elevated quality benchmarks to capture esoteric testing volumes previously retained by hospital systems, creating pull-through for high-complexity assay menus.
- Companion diagnostic pathways:FDA premarket review frameworks for oncology therapeutics are mandating parallel diagnostic development, embedding tumor marker tests into drug approval timelines and securing reimbursement anchoring.
- Liquid biopsy penetration:Blood-based circulating tumor DNA analysis is displacing tissue biopsy requirements in recurrence monitoring applications, opening addressable volume in colorectal and lung cancer surveillance protocols.
Market Restraints
- Reimbursement compression:CMS national coverage determinations for multi-cancer early detection assays are constraining price realization for novel liquid biopsy platforms, compressing margin structures for test developers.
- Sample type fragmentation:Tumor marker testing requires harmonization across serum, plasma, tissue, and circulating cell-free DNA matrices, creating technical validation burden that delays assay commercialization timelines.
- Intellectual property thickets:Gene patent estates surrounding BRCA, EGFR, and KRAS biomarkers impose licensing complexity that filters smaller diagnostic developers from high-value oncology segments.
Strategic Opportunities
- Japan's centralized screening networks:METI-supported cancer screening infrastructure investments are creating procurement concentration for high-throughput automated platforms capable of processing population-scale volumes.
- Point-of-care decentralization:Abbott's handheld immunoassay architecture is demonstrating feasibility for community clinic deployment, opening channel expansion beyond tertiary hospital reference laboratories.
- EMA MDR transition tailwinds:Stricter clinical evidence requirements under Europe's In Vitro Diagnostic Regulation are accelerating market consolidation, creating acquisition targets for well-capitalized platform holders with established notified body relationships.
Industry Challenges
- Bioinformatics talent scarcity:Next-generation sequencing interpretation requires computational pathology expertise that outstrips current training pipeline output, constraining laboratory expansion timelines for complex genomic assays.
- Legacy LIS integration friction:Hospital information systems built on HL7 v2 messaging standards require middleware development to accommodate NGS data volumes, delaying enterprise-wide workflow automation.
- Proficiency testing logistics:CAP and EMQN external quality assessment programs impose specimen shipping and turnaround requirements that strain international laboratory networks, particularly for unstable circulating biomarker analytes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Marker Testing Market |
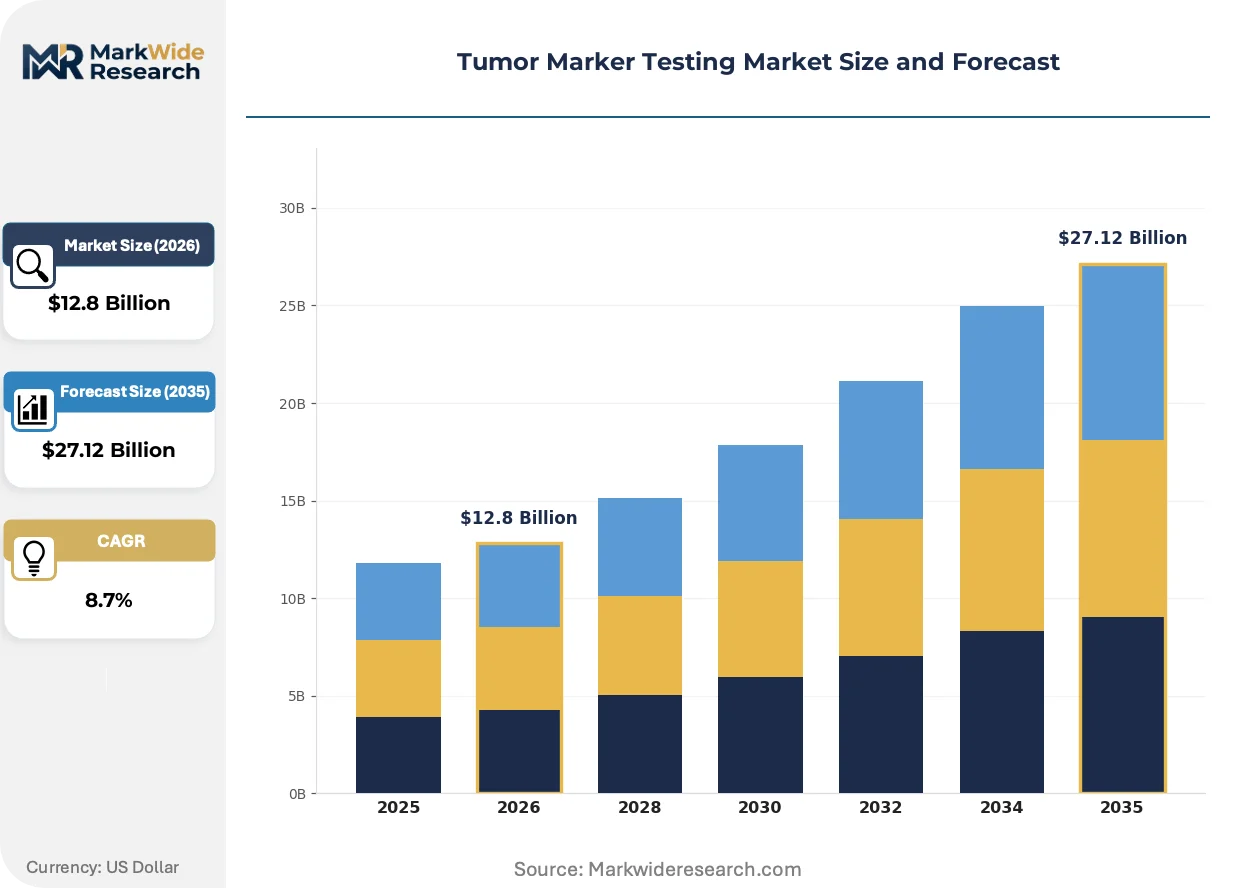
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CEA, CA 125, PSA, AFP End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutes Technology: ELISA, PCR, Next-Gen Sequencing, Immunohistochemistry Application: Screening, Diagnosis, Prognosis, Treatment Monitoring |
| Companies Covered | Abbott, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, QIAGEN, Illumina, Agilent Technologies, Quest Diagnostics, Bio-Rad Laboratories, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Marker Testing Market Evolving Landscape
Assay miniaturization and digital pathology convergence are redrawing the boundary between centralized reference laboratories and distributed testing nodes, compressing the traditional hub-and-spoke specimen logistics model that has dominated oncology diagnostics for decades.
Digital PCR technology is bifurcating the rare mutation detection landscape, enabling absolute quantification of circulating tumor DNA at allelic fractions below 0.1% without standard curve dependency. Academic medical centers in Germany and Japan are adopting these platforms for minimal residual disease monitoring, displacing quantitative PCR workflows that dominated the prior decade. This technical capability is compressing competitive differentiation around absolute sensitivity specifications rather than relative fold-change detection.
EMA's In Vitro Diagnostic Regulation is imposing post-market surveillance obligations that extend beyond device performance to encompass clinical utility evidence generation across the product lifecycle. Manufacturers must maintain performance registries that feed into periodic safety updates, increasing regulatory affairs headcount requirements by approximately forty percent for mid-sized diagnostic firms. European notified bodies are prioritizing oncology companion diagnostics for review, creating queue displacement for routine protein marker assays.
Oncology practices are consolidating purchasing authority into centralized procurement committees that negotiate multi-year assay contracts spanning chemistry, immunoassay, and molecular platforms. Hospital networks in the United States are unbundling reagent supply from instrument placement agreements, shifting commercial terms toward per-test consumable pricing with volume tier commitments. This behavioral shift is most visible in multi-site health systems operating across California, Texas, and Florida, where laboratory standardization initiatives are eliminating site-specific vendor fragmentation.
Tumor Marker Testing Market Segmentation
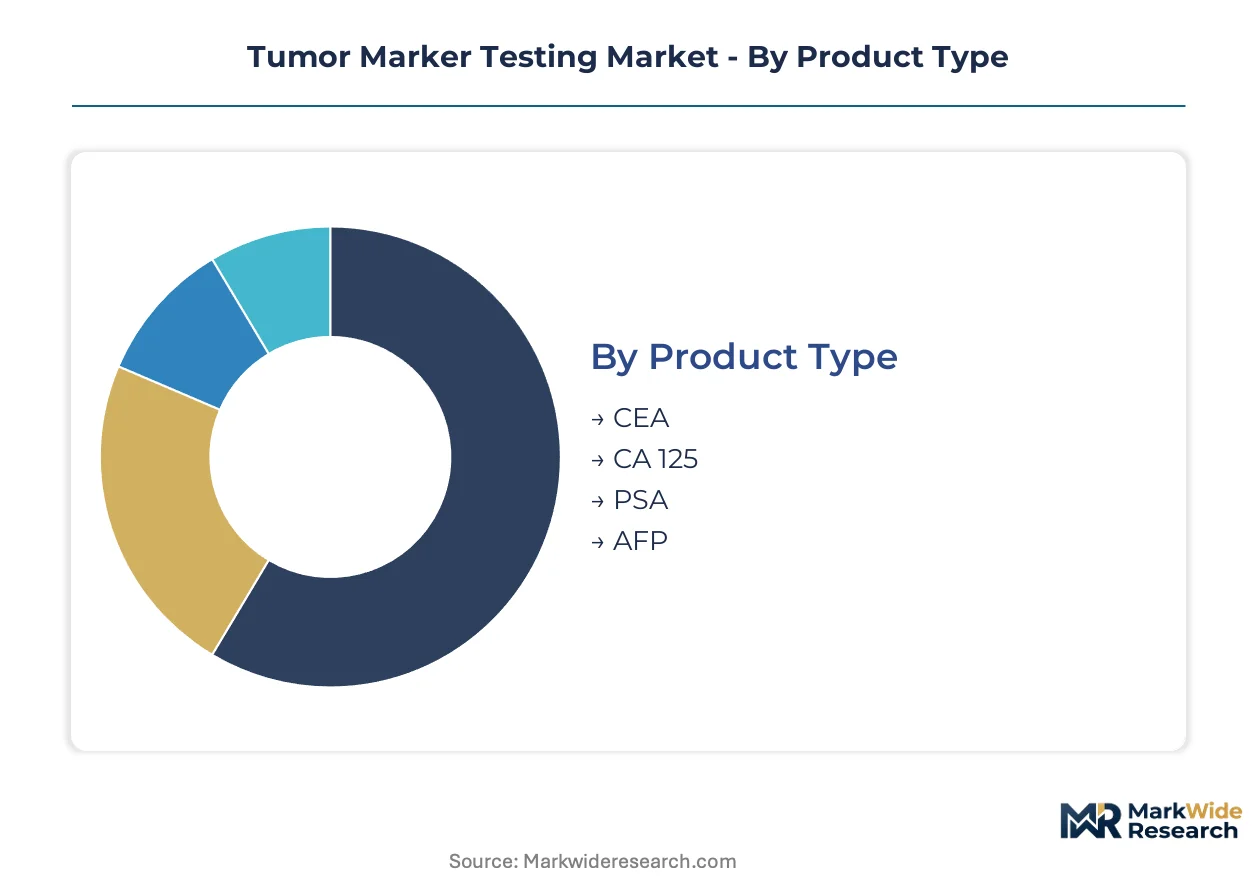
Tumor marker testing segments fragment across biomarker specificity, technological capability, and care setting economics. Substitution pressure from liquid biopsy platforms and multiplexed genomic assays is redrawing traditional boundaries between protein-based and nucleic acid-based detection methods.
Product Type:
CEA and PSA face the strongest substitution threat as multi-cancer early detection panels displace single-analyte screening protocols in health system procurement.
- CEA:Carcinoembryonic antigen assays detect colorectal cancer recurrence through serum quantification with established CMS reimbursement codes. Hospital laboratories in the United States retain substantial volumes for post-surgical surveillance despite emerging ctDNA alternatives.
- PSA:Prostate-specific antigen testing dominates urology clinic workflows with point-of-care immunoassay availability, though precision medicine guidelines are narrowing appropriate-use criteria and compressing screening frequency recommendations.
- CA 125:Carbohydrate antigen 125 monitoring for ovarian cancer progression maintains strong adoption in gynecologic oncology practices.
- AFP:Alpha-fetoprotein hepatocellular carcinoma surveillance persists in cirrhosis patient populations with high-risk stratification protocols.
PSA anchors the volume base while CEA gains share at the steepest rate through expanded recurrence monitoring indications.
End User:
Cost tier stratification separates capital-intensive automated platforms from manual workflow alternatives, concentrating margin capture in high-complexity certification tiers.
- Diagnostic Laboratories:CLIA-certified reference laboratories command premium pricing for esoteric molecular assays through specialized technical capabilities and direct-to-consumer marketing channels. Quest Diagnostics and LabCorp network expansion is consolidating outpatient specimen flow.
- Hospitals:Acute care institutions integrate tumor marker testing into episode-based reimbursement bundles, prioritizing rapid turnaround for inpatient oncology consultations. Health system consolidation in Texas and Florida is standardizing instrument platforms across multi-site networks.
- Clinics:Community-based point-of-care deployment extends access beyond tertiary centers with waived-complexity immunoassay systems.
- Research Institutes:Academic medical centers drive biomarker discovery through translational research protocols and clinical trial enrollment screening.
Hospitals anchor the volume base while diagnostic laboratories gain share at the steepest rate through centralized esoteric testing capture.
Technology:
Application maturity curves separate legacy protein quantification methods from emerging nucleic acid platforms, with reimbursement timelines lagging technical capability by several years.
- Next-Gen Sequencing:Comprehensive genomic profiling from single specimens enables simultaneous detection of mutations, copy number alterations, and microsatellite instability. Foundation Medicine and Tempus are scaling CLIA laboratory capacity to meet oncologist demand for therapy-matching panels.
- ELISA:Enzyme-linked immunosorbent assays retain the largest installed base for routine protein marker quantification with cost-per-test economics that sustain high-frequency monitoring protocols.
- PCR:Quantitative polymerase chain reaction dominates circulating tumor DNA detection with established clinical validity for EGFR mutation monitoring in non-small cell lung cancer.
- Immunohistochemistry:Tissue-based protein expression analysis remains essential for PD-L1 companion diagnostic scoring and HER2 status determination in breast cancer.
ELISA anchors the volume base while next-gen sequencing gains share at the steepest rate through companion diagnostic mandate expansion.
Application:
Customer type differentiation separates population-scale screening programs from individualized therapy management, with procurement authority concentrating in distinct stakeholder committees.
- Treatment Monitoring:Serial biomarker quantification during therapy enables early response assessment and progression detection, with liquid biopsy adoption accelerating in colorectal and lung cancer surveillance protocols.
- Diagnosis:Differential diagnostic applications combine multiple tumor markers to distinguish malignant from benign conditions in symptomatic patient presentations.
- Screening:Asymptomatic population testing faces reimbursement compression as multi-cancer early detection assays seek national coverage determination from CMS.
- Prognosis:Baseline biomarker elevation stratifies recurrence risk and informs adjuvant therapy intensity decisions in curative-intent treatment pathways.
Diagnosis anchors the volume base while treatment monitoring gains share at the steepest rate through circulating biomarker assay expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across major oncology diagnostics markets. Germany and Japan exhibit low price sensitivity for companion diagnostic assays due to structured reimbursement pathways, while diagnostic laboratories in the United States face acute margin pressure from Medicare coverage determinations.
United States
Hospital network consolidation in Texas, Florida, and California is standardizing instrument platforms across multi-site laboratory systems. FDA premarket review frameworks for companion diagnostics mandate parallel assay development with oncology therapeutics, embedding testing into drug approval timelines. The Greater Boston corridor anchors translational research capacity, with academic medical centers driving biomarker discovery through clinical trial enrollment protocols.
Germany
Academic medical centers in Munich and Heidelberg are adopting digital PCR platforms for minimal residual disease monitoring, displacing quantitative PCR workflows. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards and post-market surveillance obligations that filter smaller manufacturers. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity, with centralized procurement committees negotiating multi-year assay contracts spanning chemistry and molecular platforms.
Japan
METI-supported cancer screening infrastructure investments are creating procurement concentration for high-throughput automated platforms capable of processing population-scale volumes. PMDA regulatory pathways prioritize oncology companion diagnostics for accelerated review, compressing commercialization timelines for assay developers. The Kanto region around Tokyo anchors centralized screening network deployment, with diagnostic laboratories capturing esoteric testing volumes through specialized technical capabilities.
China
NMPA regulatory reforms are streamlining in vitro diagnostic registration pathways for innovative tumor marker assays, though clinical evidence requirements remain stringent compared to Western frameworks. The Yangtze River Delta region, particularly Shanghai and Suzhou, concentrates domestic diagnostic platform manufacturing and CLIA-equivalent laboratory certification expansion. Local developers are scaling next-generation sequencing capacity to meet oncologist demand for comprehensive genomic profiling.
United Kingdom
NHS England's specialized commissioning frameworks are consolidating tumor marker testing procurement into regional laboratory hubs, eliminating site-specific vendor fragmentation. MHRA post-Brexit regulatory autonomy permits divergence from EMA timelines, though CE marking remains essential for Northern Ireland market access. The Cambridge-London corridor maintains translational research density, with academic-industry partnerships driving liquid biopsy assay validation for colorectal cancer surveillance protocols.
Tumor Marker Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Roche, Abbott, and Thermo Fisher anchoring the upper echelon through installed base advantages and end-to-end workflow integration. The middle tier comprises regional reference laboratories and platform specialists competing on assay menu breadth or technical specialization in circulating biomarker detection. Three archetypes dominate: integrated diagnostic conglomerates with analyzer-installed bases, CLIA-certified esoteric testing laboratories with direct-to-consumer channels, and NGS platform suppliers with bioinformatics service layers. Competitive moves concentrate on multi-year reagent supply contracts with volume tier commitments and strategic acquisitions of notified body relationships to navigate EMA MDR transition requirements.
Within the integrated diagnostic tier, F. Hoffmann-La Roche Ltd leverages its Swiss conglomerate structure and cobas analyzer installed base to sustain recurring revenue streams across major hospital networks. Abbott occupies a position exemplifying point-of-care decentralization strategy through handheld immunoassay architecture extending access beyond tertiary reference laboratories. Thermo Fisher Scientific represents the end-to-end workflow archetype, supplying integrated PCR and NGS platforms that consolidate sample preparation with analytics for laboratory customers.
| Leading Market Players |
|---|
| Abbott |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| Illumina |
| Agilent Technologies |
| Quest Diagnostics |
| Bio-Rad Laboratories |
| bioMérieux |
| Others |
Value Network & Pricing Analysis
Digital PCR platform substitution for quantitative PCR workflows simultaneously redraws supply geography toward Germany and Japan while compressing pricing economics around absolute sensitivity specifications rather than relative fold-change detection. Assay developers face margin pressure as health systems unbundle reagent supply from instrument placement agreements and shift toward per-test consumable pricing with volume tier commitments.
Pricing Analysis
After-sales revenue from multi-year reagent supply contracts and service maintenance agreements drives lifetime value capture for automated platform manufacturers. The dominant pricing structure operates through tiered consumable contracts with volume commitments, where price differentiation rests on CLIA certification tier and installed base scale. Pricing pressure stems from CMS national coverage determinations constraining reimbursement for novel liquid biopsy platforms, with diagnostic laboratories exhibiting acute price sensitivity while academic medical centers remain relatively insulated.
Supply Chain Analysis
Inventory lead times for specialized enzymes and oligonucleotide reagents extend commercialization timelines for assay developers awaiting critical raw material lots. Supply concentrates in the United States, Germany, and Japan for high-throughput automated analyzers, while China and South Korea anchor manufacturing for PCR and NGS platform components. The supply chain draws from fluorophore chemistries, polymerase enzymes, and synthetic DNA oligos as critical inputs, with single-source vulnerability around proprietary reagent formulations. Distribution runs through centralized procurement committees at hospital networks and regional laboratory hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tumor marker testing market fragments across technology generations, with liquid biopsy penetration and multiplexed assay expansion creating white-space niches for specialized entrants. Demand-side consolidation into multi-year assay contracts spanning chemistry and molecular platforms rewards scale while leaving gaps in point-of-care decentralization and bioinformatics service layers.
For Market Incumbents: Secure installed base loyalty through backward integration into critical reagent manufacturing and accelerated FDA companion diagnostic pathway investments. Roche's cobas analyzer ecosystem and Thermo Fisher's end-to-end NGS workflows demonstrate defensive positioning against emerging digital PCR specialists. Capacity addition in Japan's METI-supported screening networks and CLIA laboratory certification expansion in the United States anchor geographic defense. For New Entrants and Emerging Players: Lead with bioinformatics interpretation services and minimal residual disease monitoring applications as the most penetrable white-space targets. Community clinic point-of-care deployment in the United States and digital PCR platform adoption in German academic medical centers offer channel expansion beyond consolidated hospital procurement committees. A go-to-market angle emphasizing absolute quantification sensitivity specifications without standard curve dependency differentiates against entrenched quantitative PCR workflows. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform holders with established notified body relationships and CLIA laboratory infrastructure. Long-term viability across the analysis window hinges on companion diagnostic mandate expansion and liquid biopsy reimbursement stabilization. Acquisition target archetypes include mid-sized diagnostic firms with EMA MDR transition readiness and specialized circulating biomarker assay menus. The signal to watch is CMS national coverage determination timelines for multi-cancer early detection assays as an inflection indicator for liquid biopsy platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Expansion | Diagnostic laboratories capture esoteric testing volumes previously retained by hospital systems. |
| Companion Diagnostic Pathway Investment | FDA premarket review frameworks embed tumor marker tests into oncology drug approval timelines. |
| Digital PCR Platform Deployment | Academic medical centers in Germany and Japan adopt absolute quantification for minimal residual disease monitoring. |
| Point-of-Care Immunoassay Architecture | Abbott's handheld systems extend access beyond tertiary reference laboratories into community clinics. |
| EMA MDR Notified Body Relationship Acquisition | Stricter clinical evidence requirements filter smaller manufacturers and accelerate market consolidation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket notification filings, CMS national coverage determinations, EMA In Vitro Diagnostic Regulation guidance documents, and CLIA laboratory certification databases. Primary interviews engaged diagnostic laboratory directors, hospital purchasing committee members, regulatory affairs specialists at assay developers, and biomedical engineers at academic medical centers. Bottom-up triangulation across instrument placement data, reagent consumption estimates, and test volume projections converges with top-down analysis of oncology care pathway expenditure flows.
Segmentation dimensions modeled span biomarker specificity across CEA, PSA, CA 125, and AFP assays; technology platforms including ELISA, PCR, next-generation sequencing, and immunohistochemistry; end-user channels separating hospitals, diagnostic laboratories, clinics, and research institutes; and application categories across screening, diagnosis, prognosis, and treatment monitoring. CAGRs were derived from regression analysis of historical test volume trajectories and reimbursement rate evolution across the projection horizon, with specific inputs including companion diagnostic approval timelines and liquid biopsy platform adoption curves in colorectal and lung cancer surveillance protocols.
The analysis sits within stated boundaries; outcomes outside stable FDA premarket review timelines, sustained CLIA certification expansion, and consistent payer coverage policy for circulating biomarker assays would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory pathway efficiency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market