
 Master Patient Index Software Market | 2026-2036
Master Patient Index Software Market Size, Share, and Industry Trends Forecast 2026-2036
Master Patient Index Software Market Analysis
Modular bundling of identity resolution with enterprise EMR suites is broadening procurement options for mid-sized hospital networks. Epic Systems Corporation leverages its captive EHR installed base to anchor MPI modules within integrated clinical workflows. Oracle Corporation competes through cloud-native architecture that extends patient-matching capabilities across multi-site health systems. NextGate specializes in standalone enterprise master person index platforms that occupy a distinct niche among payers and health information exchanges.
Master Patient Index software constitutes an enterprise identity management layer that probabilistically and deterministically links patient demographic, clinical, and administrative records across disparate information systems using match algorithms, unique identifiers, and referential data enrichment. Its primary commercial purpose is eliminating duplicate and overlaid records to ensure clinical continuity, billing accuracy, and population health analytics integrity. Cloud-based solutions lead deployment preferences as health systems prioritize elastic infrastructure and reduced data-center overhead, while hybrid architectures capture growing interest among organizations with strict latency or sovereignty constraints. Machine learning represents the fastest-expanding technology segment as vendors embed neural matching models to improve match rates on incomplete or transposed demographic fields.
FDA oversight of software-as-medical-device classifications, HIPAA security and breach notification rules, and ONC interoperability certification requirements collectively shape product roadmaps and market access conditions for MPI vendors operating in the United States. The EU AI Act and GDPR cross-border data transfer restrictions impose additional compliance burdens on vendors serving European health networks. Stakeholders must monitor evolving federal match-rate performance thresholds and state-level health data exchange mandates to calibrate R&D investment and partnership strategies.
Market Dynamics
Machine learning match algorithms are compressing implementation timelines for patient identity resolution, forcing vendors to retrain neural models on incomplete demographic data while maintaining deterministic audit trails for HIPAA compliance.
Growth Catalysts
- ONC Interoperability Certification:Federal mandates for standardized patient matching APIs accelerate replacement cycles among US hospital networks seeking incentive payments.
- Cloud-Native Architecture Migration:Elastic infrastructure deployment eliminates data-center overhead for mid-sized health systems prioritizing operational agility.
- Health Information Exchange Expansion:State-level data sharing mandates in Massachusetts, New York, and California create procurement pull for enterprise MPI platforms.
Market Restraints
- Cross-Border Data Friction:GDPR Article 44 transfer restrictions impose architectural constraints on US-based vendors serving European health networks.
- Algorithmic Bias Liability:EU AI Act high-risk system classifications trigger compliance costs for probabilistic matching engines used in clinical decision support.
- Legacy System Entrenchment:Decades-old patient registration databases in county hospitals resist deterministic linking without expensive middleware.
Strategic Opportunities
- Rural Hospital Consolidation:Underserved networks in Montana, Idaho, and Wyoming present greenfield deployment potential for SaaS-based identity platforms.
- Payer-Provider Convergence:Vertical integration between insurance carriers and delivery systems creates demand for unified master person indices spanning claims and clinical data.
- API-First Distribution:Embedded marketplace models on Epic App Orchard and Oracle Cloud Marketplace reduce direct sales friction for specialized vendors.
Industry Challenges
- Data Stewardship Talent Scarcity:Shortage of health informaticists trained in probabilistic record linkage and referential data quality management constrains implementation velocity.
- Multi-Site Integration Complexity:Merged health systems struggle to reconcile divergent patient matching rules across acquired facility EHR instances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Master Patient Index Software Market |
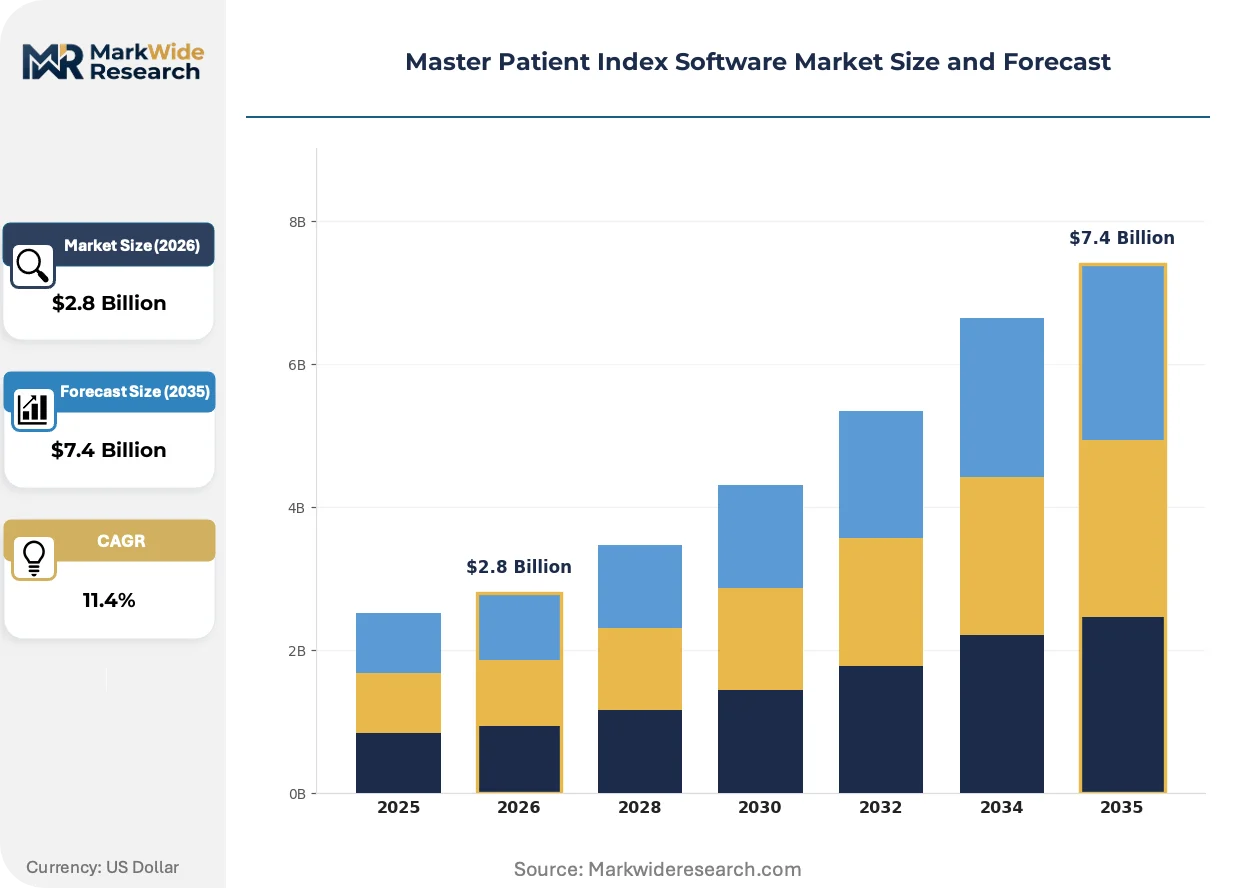
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Federated Solutions End User: Healthcare Providers, Health Information Exchanges, Payer Organizations, Research Institutions Deployment Model: Public Cloud, Private Cloud, On-Premises, Hosted Solutions Technology: Machine Learning, Blockchain, Data Integration, Interoperability Standards |
| Companies Covered | Optum Inc, GE Healthcare, McKesson Corporation, InterSystems Corporation, Epic Systems Corporation, Oracle Corporation, Siemens Healthineers AG, NextGate, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Master Patient Index Software Market Emerging Trajectories
Neural matching architectures and federated identity frameworks are compressing the traditional boundary between enterprise MPI platforms and consumer-facing patient portals, creating new competitive terrain for vendors.
Probabilistic machine learning engines are consolidating patient matching workflows previously handled by separate deterministic rules engines and manual data stewardship queues. Large integrated delivery networks in Texas and Florida deploy these models to resolve transposed name fields and address variants without human intervention. The technology is consolidating vendor market positions by collapsing the distinction between real-time registration matching and retrospective duplicate cleanup.
HIPAA Security Rule updates and FDA software-as-medical-device guidance are tightening validation requirements for algorithmic patient identification systems. Vendors must now document match-rate performance across demographic subgroups and maintain deterministic audit trails for regulatory inspection. US health systems responding to these pressures demand pre-certified platforms with baked-in bias testing and explainable match scoring.
Subscription-based procurement is displacing perpetual license models as hospital CFOs prioritize operational expenditure predictability over capital-intensive upfront deployment. Mid-sized networks in the Midwest negotiate three-year SaaS contracts with embedded professional services for data migration and staff training. This shift concentrates vendor revenue into recurring streams while compressing implementation timelines to under ninety days for cloud-native deployments.
Master Patient Index Software Market Segmentation
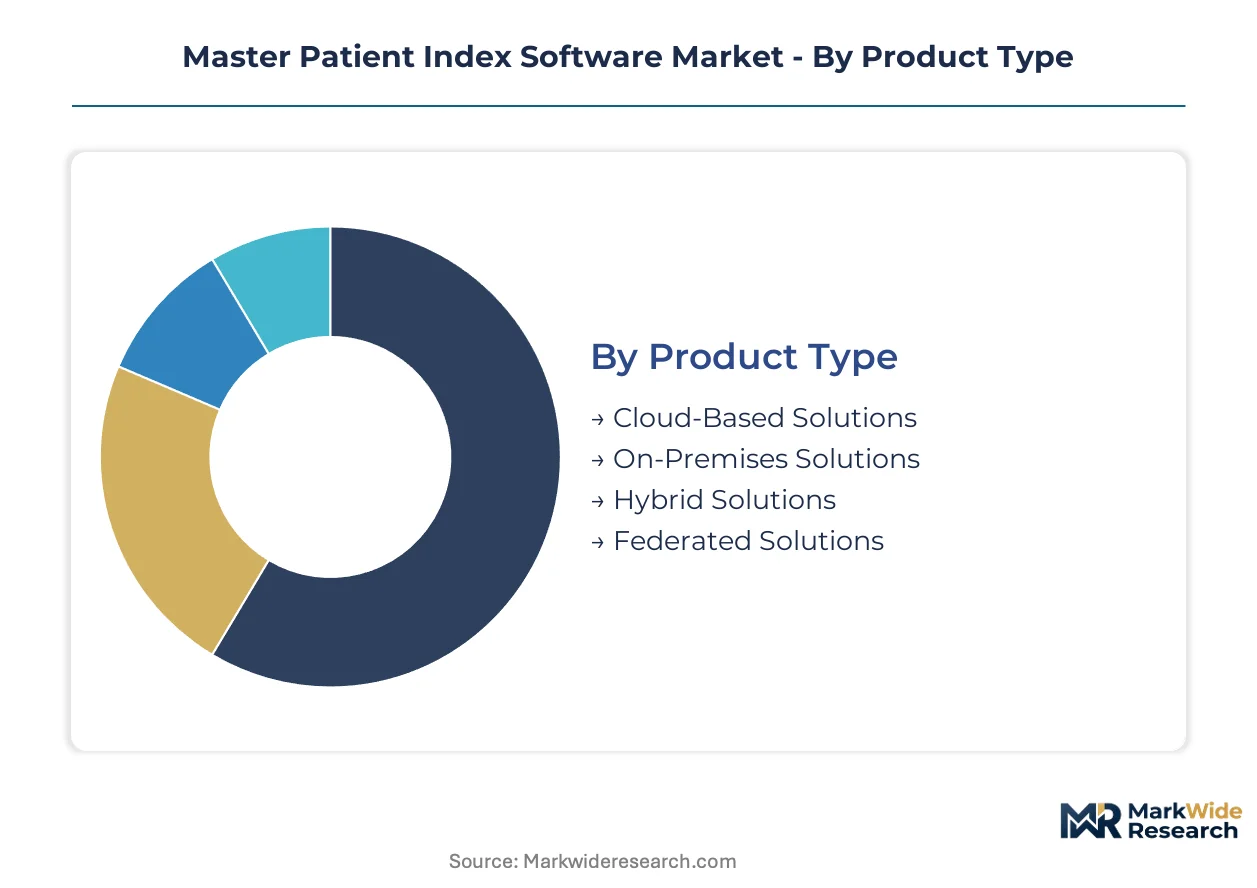
Segmentation of the Master Patient Index Software Market reveals how procurement decisions split across infrastructure maturity, regulatory posture, and clinical workflow integration requirements. Vendors calibrate platform architecture to match the specific identity resolution complexity and data sovereignty constraints of each buyer category.
Product Type:
Cloud-native elasticity distinguishes commercial winners from legacy incumbents struggling with data-center overhead.
- Cloud-Based Solutions:Elastic infrastructure eliminates capital expenditure for server procurement and facility maintenance. Texas Health Resources and Kaiser Permanente deploy these platforms to synchronize patient records across dozens of acute-care sites without on-site hardware. HIPAA Business Associate Agreements with AWS and Azure govern data residency.
- On-Premises Solutions:Air-gapped installations persist in Department of Veterans Affairs facilities and certain Defense Health Agency installations where classified or sensitive personnel data precludes external hosting. Deterministic matching engines run on dedicated hardware with manual override protocols for disputed records.
- Hybrid Solutions:Split architectures route real-time registration queries through cloud APIs while retaining longitudinal patient histories in local data warehouses.
- Federated Solutions:Distributed query frameworks enable patient matching without centralizing records, addressing GDPR Article 44 transfer restrictions for cross-border health networks.
Mature deployment sits with On-Premises Solutions. Newer deployment is concentrated in Cloud-Based Solutions.
End User:
Procurement authority concentrates where clinical and financial risk from identity errors is highest.
- Healthcare Providers:Integrated delivery networks in Florida and California absorb the largest share of enterprise MPI licensing. Duplicate record rates above 10 percent trigger Joint Commission scrutiny and revenue cycle leakage, driving replacement cycles.
- Health Information Exchanges:State-designated entities in Massachusetts and New York mandate patient-matching accuracy thresholds for participation. These organizations operate as neutral intermediaries, requiring vendor-agnostic matching algorithms that function across Epic, Cerner, and Meditech instances.
- Payer Organizations:Vertical integration with provider networks creates demand for unified master person indices spanning claims adjudication and clinical data.
- Research Institutions:NIH-funded clinical trial networks deploy specialized MPI modules to link participant records across multi-site studies while preserving blinding protocols.
Procurement volume concentrates with Healthcare Providers. Steepest expansion trajectory belongs to Health Information Exchanges.
Deployment Model:
Latency tolerance and data residency requirements dictate infrastructure selection.
- Public Cloud:Shared-tenant infrastructure from AWS, Azure, and Google Cloud dominates mid-sized hospital network procurement. ONC certification requirements now mandate specific API implementations that public cloud environments support natively.
- Private Cloud:Single-tenant virtualized environments serve Catholic health systems and other mission-driven networks with strict governance over physical infrastructure location.
- On-Premises:Bare-metal installations persist where network connectivity to cloud regions is unreliable or where state Medicaid agencies impose data localization requirements.
- Hosted Solutions:Managed service providers operate dedicated environments in co-location facilities, splitting operational responsibility between vendor and customer.
Public Cloud captures the majority of new contracts. Private Cloud retains position where data sovereignty is non-negotiable.
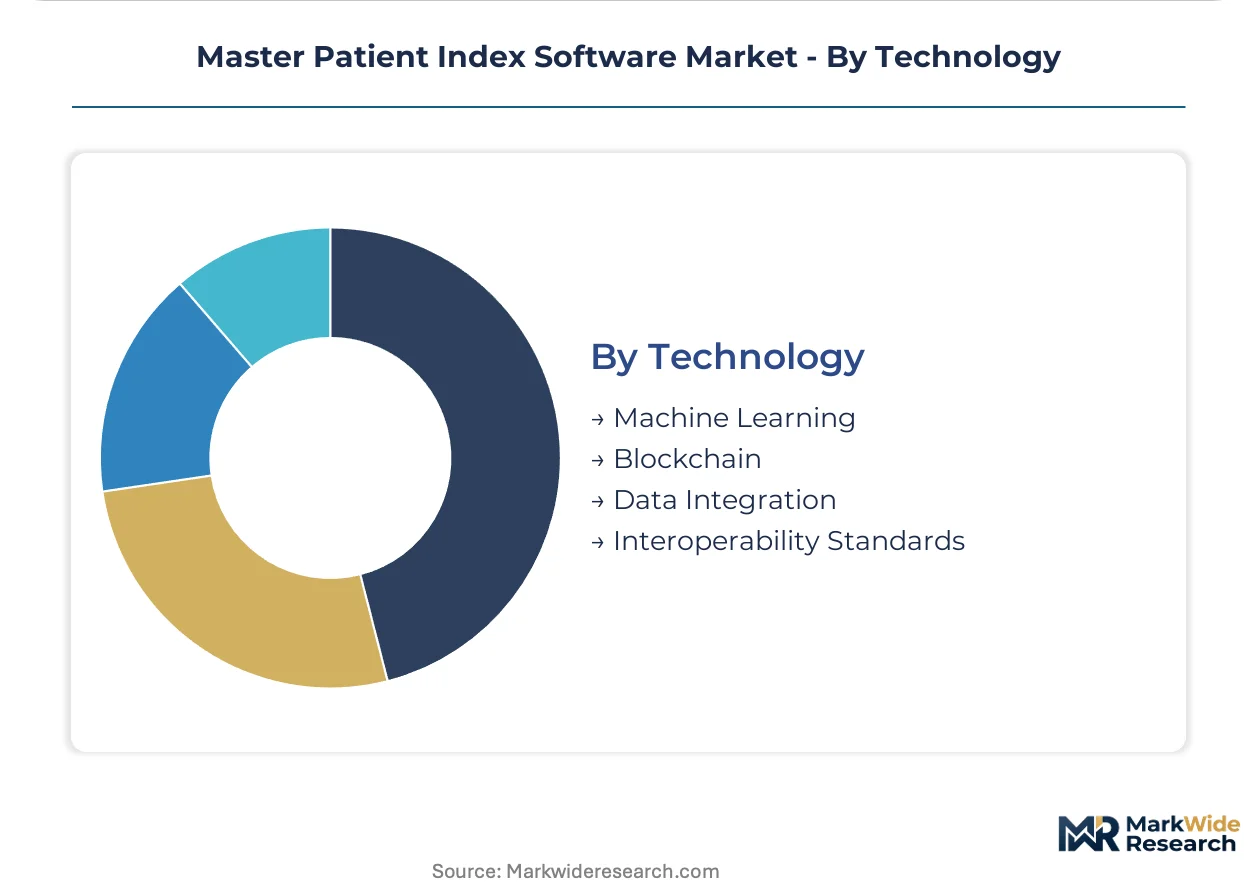
Technology:
Algorithmic sophistication now separates commodity matching engines from differentiated platforms.
- Machine Learning:Neural matching models from NextGate and Verato resolve transposed name fields, phonetic variants, and address changes without deterministic rule maintenance. FDA software-as-medical-device guidance now requires documented performance across demographic subgroups for these probabilistic systems.
- Blockchain:Distributed ledger pilots in Estonia and Dubai test patient-controlled identity credentials, though production deployment remains limited by transaction throughput constraints.
- Data Integration:ETL pipelines and master data management workflows remain essential for retrospective duplicate cleanup in merged health systems.
- Interoperability Standards:HL7 FHIR R4 and the ONC United States Core Data for Interoperability mandate specific patient matching API implementations that vendors must certify.
Machine Learning commands R&D investment and pricing premiums. Interoperability Standards function as table stakes for market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban corridors and rural health shortage areas are concentrating federal incentive dollars for patient-matching infrastructure. Tax-advantaged capital flows toward health systems modernizing identity resolution platforms.
United States
ONC interoperability certification mandates and Medicaid incentive programs drive hospital procurement cycles. HIPAA Security Rule updates tighten algorithmic validation requirements for probabilistic matching engines. Texas Health Resources and Kaiser Permanente anchor multi-site deployments across dozens of acute-care facilities.
Germany
EU AI Act high-risk system classifications impose compliance burdens on probabilistic patient-matching platforms. The country's national pharmaceutical regulator enforces documentation standards for software-as-medical-device classifications. Berlin-Brandenburg health networks pilot federated identity frameworks addressing GDPR cross-border transfer restrictions.
United Kingdom
NHS Digital transformation programs mandate standardized patient identifiers across integrated care systems. The national health technology regulator enforces cybersecurity standards for cloud-hosted clinical data platforms. London/Southeast hospital networks consolidate procurement authority for enterprise MPI licensing.
Japan
METI digital health initiatives accelerate cloud migration for mid-sized hospital networks. The national pharmaceutical and medical device agency tightens software validation requirements for clinical decision support systems. Kanto/Tokyo metropolitan health systems deploy elastic infrastructure for multi-site patient record synchronization.
India
CDSCO medical device software regulations and national digital health mission programs expand addressable market for identity resolution platforms. The central drug standard control organization aligns with international software-as-medical-device frameworks. Maharashtra and Karnataka health information exchanges mandate vendor-agnostic matching algorithms across heterogeneous EHR environments.
Master Patient Index Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. Enterprise software conglomerates leverage captive installed bases to anchor MPI modules within integrated clinical workflows. Pure-play identity resolution vendors occupy distinct niches among payers and health information exchanges. Two dominant competitive moves concentrate vendor strategy: cloud-native architecture migration and embedded marketplace distribution through EHR platform app stores.
Among diversified technology conglomerates, Oracle Corporation exemplifies cloud-native positioning for multi-site health systems. Epic Systems Corporation anchors integrated workflow bundling for captive EHR installed bases. NextGate occupies a specialist position in standalone enterprise master person index platforms serving neutral health information exchange intermediaries.
| Leading Market Players |
|---|
| Optum Inc |
| GE Healthcare |
| McKesson Corporation |
| InterSystems Corporation |
| Epic Systems Corporation |
| Oracle Corporation |
| Siemens Healthineers AG |
| NextGate |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud-native certification tiers bifurcate procurement economics between elastic SaaS deployments and air-gapped deterministic engines, concentrating vendor margins in recurring subscription streams while legacy on-premises installations absorb capital-intensive hardware overhead and extended implementation timelines.
Pricing Analysis
Expedited deployment timelines command pricing premiums, with cloud-native implementations under ninety days attracting standard-rate contracts while legacy data-center migrations with custom middleware negotiate discounted perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels segments by match-rate performance thresholds and embedded machine learning sophistication. Cost compression in mid-sized hospital network procurement intensifies as CFOs prioritize operational expenditure predictability over capital-intensive upfront deployment. Health information exchanges demonstrate highest price sensitivity due to neutral intermediary mandates, while integrated delivery networks in Texas and Florida absorb premium positioning for multi-site synchronization capabilities.
Supply Chain Analysis
Regional distribution centers in AWS US-East, Azure Central US, and Google Cloud Iowa anchor downstream fulfillment for elastic infrastructure procurement. Software development draws from engineering talent pools in India, Poland, and Romania for probabilistic algorithm refinement. Referential data enrichment feeds from LexisNexis, Experian Health, and proprietary vendor-curated identity graphs. Single-source vulnerability concentrates in AWS GovCloud for federal healthcare deployments. Distribution runs through Epic App Orchard and Oracle Cloud Marketplace for embedded marketplace models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream identity data assets and downstream clinical workflow embedding defines competitive positioning, with machine learning R&D and EHR platform partnerships representing the dominant levers vendors are pursuing.
For Market Incumbents: Anchor cloud-native architecture migration to defend against specialized pure-play entrants, while consolidating deterministic audit trail capabilities to preempt FDA software-as-medical-device enforcement actions. Deepen backward integration into referential data assets to secure proprietary enrichment moats. Prioritize Epic App Orchard and Oracle Cloud Marketplace channel control to reduce direct sales friction. For New Entrants and Emerging Players: Enter via rural hospital consolidation in Montana, Idaho, and Wyoming where greenfield SaaS deployment faces minimal legacy entrenchment. Target health information exchanges in Massachusetts and New York demanding vendor-agnostic matching algorithms across heterogeneous EHR environments. Pursue API-first distribution through embedded marketplace models rather than direct enterprise sales cycles. For Investors and Strategic Acquirers: Re-rating potential sits with machine learning-native specialists given FDA validation requirements for probabilistic matching engines. Long-term viability over the analysis window favors platforms with pre-certified bias testing and explainable match scoring. Monitor ONC interoperability certification threshold adjustments as the primary inflection signal for replacement cycle acceleration. Decision-makers should treat outputs as directional within the stated assumption set.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Elastic infrastructure eliminates data-center overhead for mid-sized health systems prioritizing operational agility. |
| Machine Learning Model Certification | FDA software-as-medical-device guidance mandates documented match-rate performance across demographic subgroups. |
| EHR Platform Partnership | Epic App Orchard and Oracle Cloud Marketplace distribution reduces direct sales friction for specialized vendors. |
| Referential Data Asset Acquisition | Proprietary identity graph enrichment secures differentiation in probabilistic matching accuracy. |
| Health Information Exchange Integration | State-level mandates in Massachusetts and New York create procurement pull for vendor-agnostic platforms. |
Methodological Framework
Document review covered FDA software-as-medical-device guidance, ONC interoperability certification requirements, HIPAA Security Rule updates, and CMS Medicare reimbursement data, complemented by interviews with health informaticists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers responsible for patient identity resolution infrastructure. Secondary validation drew from hospital procurement databases, state health information exchange participation records, and EHR vendor SEC filings. Bottom-up and top-down triangulation reconciled deployment volume estimates with aggregate market sizing.
Segmentation outputs across deployment model, organization size, integration complexity, and regional adoption pattern informed the analytical framework over the projection horizon. CAGRs derived from elasticity modeling of replacement cycle acceleration under federal incentive programs and cloud migration mandates. Forecast inputs incorporated health system consolidation velocity and machine learning match-rate improvement curves without deterministic rule maintenance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement delays or ONC interoperability certification threshold modifications. Outputs reflect assumptions regarding federal match-rate performance incentives and state-level data sharing mandate expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
ICD-10 Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Medical Simulation Software Market