
 Latin America Clinical Laboratory Services Market | 2026-2036
Latin America Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Clinical Laboratory Services Market Analytics
Brazil's private laboratory network is expanding through hub-and-spoke collection models that extend reach into secondary cities. DASA leverages vertical integration across imaging, diagnostics, and delivery to sustain margin capture in southeastern Brazil. Fleury competes on brand strength among affluent urban patients while Grupo LAPI anchors public-sector contracts through cost-efficient regional coverage. Quest Diagnostics Incorporated extends North American quality protocols to its Latin American partnerships, differentiating on standardized reporting.
Clinical laboratory services encompass the collection, processing, analysis, and interpretation of biological specimens using automated analyzers, reagent-based assays, and quality-controlled protocols to inform medical decisions. These services operate under ISO 15189 accreditation standards that mandate traceability, proficiency testing, and turnaround-time thresholds for patient safety. Molecular diagnostics leads technology-based revenue within the service type landscape, while immunoassays occupy the highest test-volume position across hospital end users. Reagents command recurring revenue streams that outpace systems in margin stability, and research laboratories represent the fastest-growing end-user channel as academic consortia expand genomic and infectious-disease surveillance programs.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce Good Laboratory Practice standards that shape equipment validation requirements and reagent import pathways across the region. These regulators mandate periodic proficiency testing and calibration traceability, which elevates capital requirements for market entry and favors accredited multi-site operators. Stakeholders must monitor how emerging digital pathology and remote diagnostic platforms interact with existing accreditation frameworks and reimbursement policies.
Market Dynamics
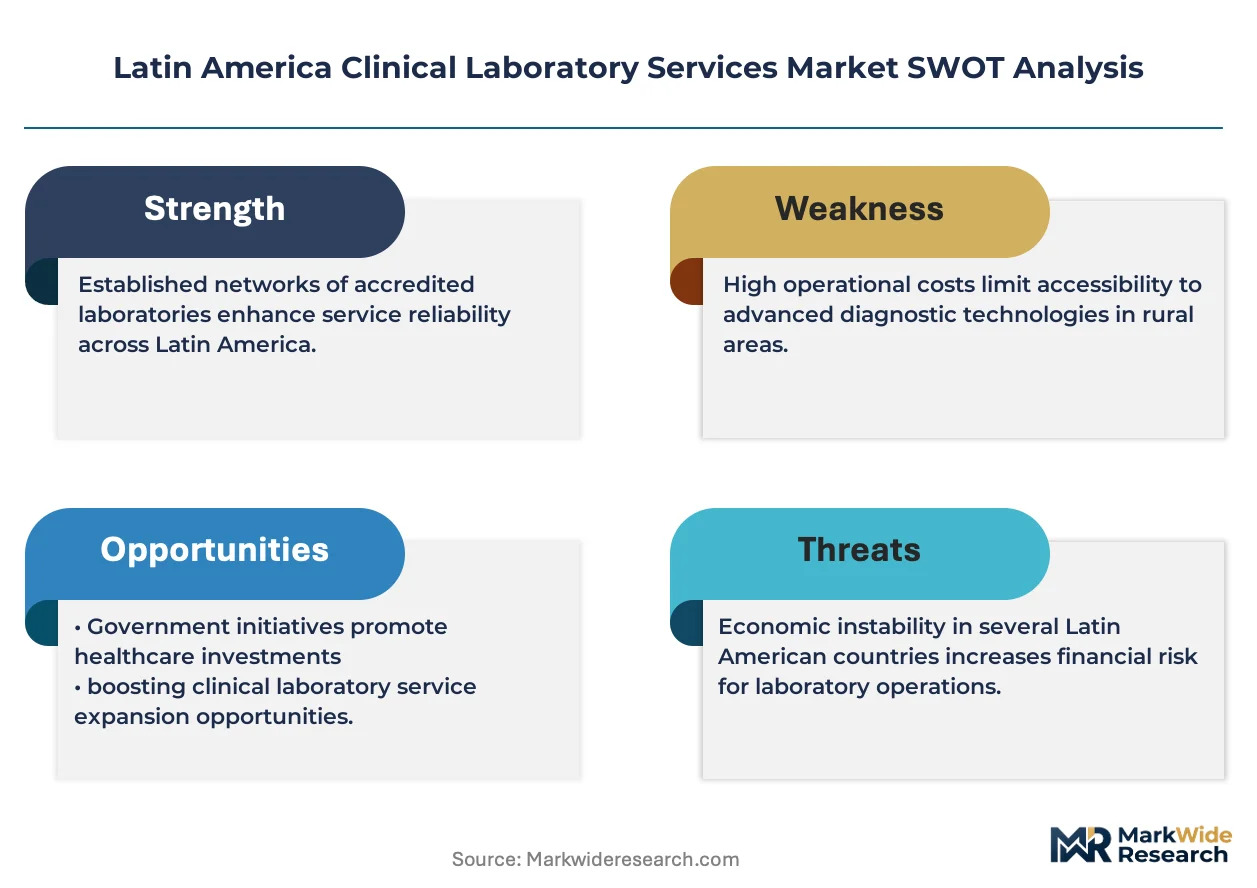
ISO 15189 accreditation mandates are compressing operational timelines for clinical laboratories across Brazil, Mexico, and Argentina while elevating capital requirements for multi-site compliance. Hospital networks and private diagnostic chains must now synchronize proficiency testing, calibration traceability, and turnaround-time thresholds across decentralized collection points.
Growth Catalysts
- Chronic disease surveillance:Hospital-based laboratories in São Paulo state and Mexico's central corridor are expanding test volumes for diabetes and cardiovascular monitoring, driven by aging demographics and private healthcare network consolidation.
- ANVISA diagnostic quality standards:Brazil's updated laboratory accreditation requirements are accelerating equipment validation protocols and reagent import pathway formalization, favoring accredited multi-site operators.
- Molecular diagnostics capability:Academic consortia across Colombia and Chile are deploying genomic and infectious-disease surveillance programs, converting research laboratories into the fastest-growing end-user channel.
Market Restraints
- Reagent import dependency:Latin American laboratories rely on concentrated North American and European suppliers for specialized immunoassay and molecular diagnostic consumables, exposing margins to currency volatility and customs clearance friction.
- Proficiency testing costs:COFEPRIS in Mexico and INVIMA in Colombia mandate periodic external quality assessment programs that impose recurring operational burdens on single-site and rural laboratories.
- Technical workforce scarcity:Certified clinical laboratory scientists with molecular diagnostics training remain concentrated in metropolitan São Paulo, Mexico City, and Buenos Aires, constraining hub-and-spoke model expansion.
Strategic Opportunities
- Digital pathology platforms:Remote diagnostic and telepathology systems are integrating with existing laboratory information management systems, enabling specialist access for secondary cities in Brazil's Northeast and Mexico's Yucatán Peninsula.
- Public-private laboratory partnerships:Grupo LAPI's cost-efficient regional coverage model in Brazil demonstrates viable pathways for anchoring public-sector contracts while maintaining private-pay revenue streams.
- Genomic medicine expansion:Pharmacogenomics and liquid biopsy applications are penetrating oncology and cardiology practices in Santiago and Bogotá, creating demand for specialized molecular testing infrastructure.
Industry Challenges
- Laboratory information system integration:Hospital networks struggle to harmonize legacy equipment from multiple manufacturers with centralized data platforms, delaying real-time reporting capabilities.
- ISO 15189 certification timelines:Multi-site operators face 12-to-18-month accreditation cycles for each new collection facility, compressing expansion velocity in competitive metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Clinical Laboratory Services Market |
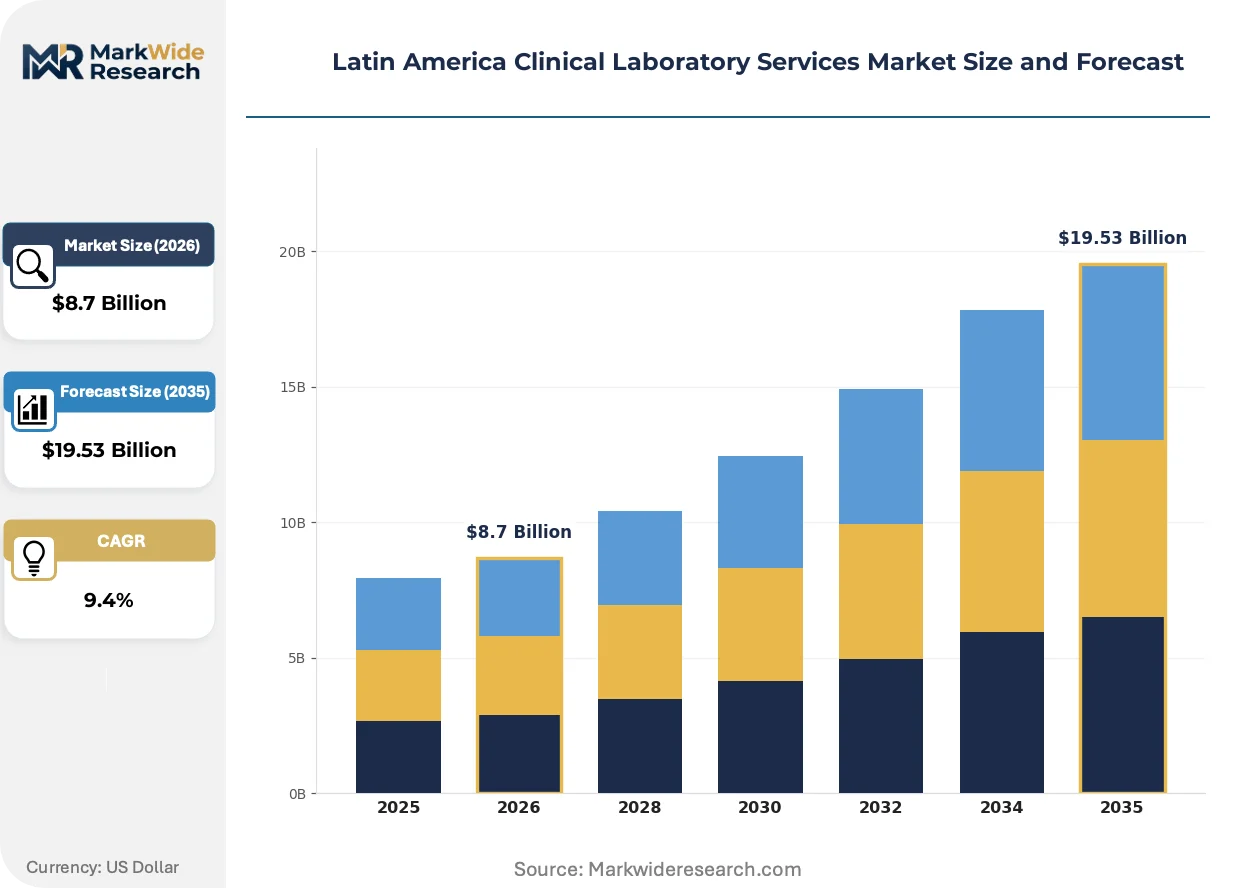
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Testing, Pathology Services, Blood Testing, Genetic Testing End User: Hospitals, Clinics, Research Laboratories, Academic Institutions Technology: Molecular Diagnostics, Immunoassays, Hematology Analyzers, Blood Gas Analyzers Product Type: Reagents, Systems, Consumables, Software |
| Companies Covered | Grupo LAPI, Laboratory Corporation of America Holdings (LabCorp), DASA, QIAGEN, OPKO Health, Inc., Fleury, Quest Diagnostics Incorporated, Siemens Healthcare GmbH, Laboratorio Chopo, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Clinical Laboratory Services Market Evolving Landscape
Automation and artificial intelligence are compressing diagnostic turnaround times while reconfiguring workforce deployment across Latin American laboratory networks. These shifts are simultaneously elevating quality thresholds and reshaping competitive differentiation in consolidated urban markets.
Next-generation sequencing platforms are integrating with automated sample preparation workflows to enable same-day genomic results for oncology and infectious-disease applications. Hospital-based laboratories in São Paulo and Mexico City are adopting these systems at accelerated pace to retain referral volumes from academic medical centers. The technology is integrating molecular diagnostics into routine clinical decision-making, displacing sequential testing protocols that previously required days.
ANVISA's updated Good Laboratory Practice enforcement is mandating electronic data integrity systems and audit trail capabilities for all accredited facilities. This regulatory pressure is forcing capital investment in laboratory information management system upgrades across Brazil's private diagnostic chains. Medium-sized operators in Rio de Janeiro and Minas Gerais states are consolidating to spread compliance costs across larger test volumes.
Hub-and-spoke collection models are replacing standalone full-service laboratories in secondary Brazilian and Mexican cities. DASA's southeastern Brazil network demonstrates how centralized testing facilities paired with rapid logistics can capture suburban and exurban patient volumes. This restructuring is most visible in Brazil's Campinas, Curitiba, and Porto Alegre corridors, where private healthcare networks are unbundling collection from analysis to optimize asset utilization.
Latin America Clinical Laboratory Services Market Segmentation
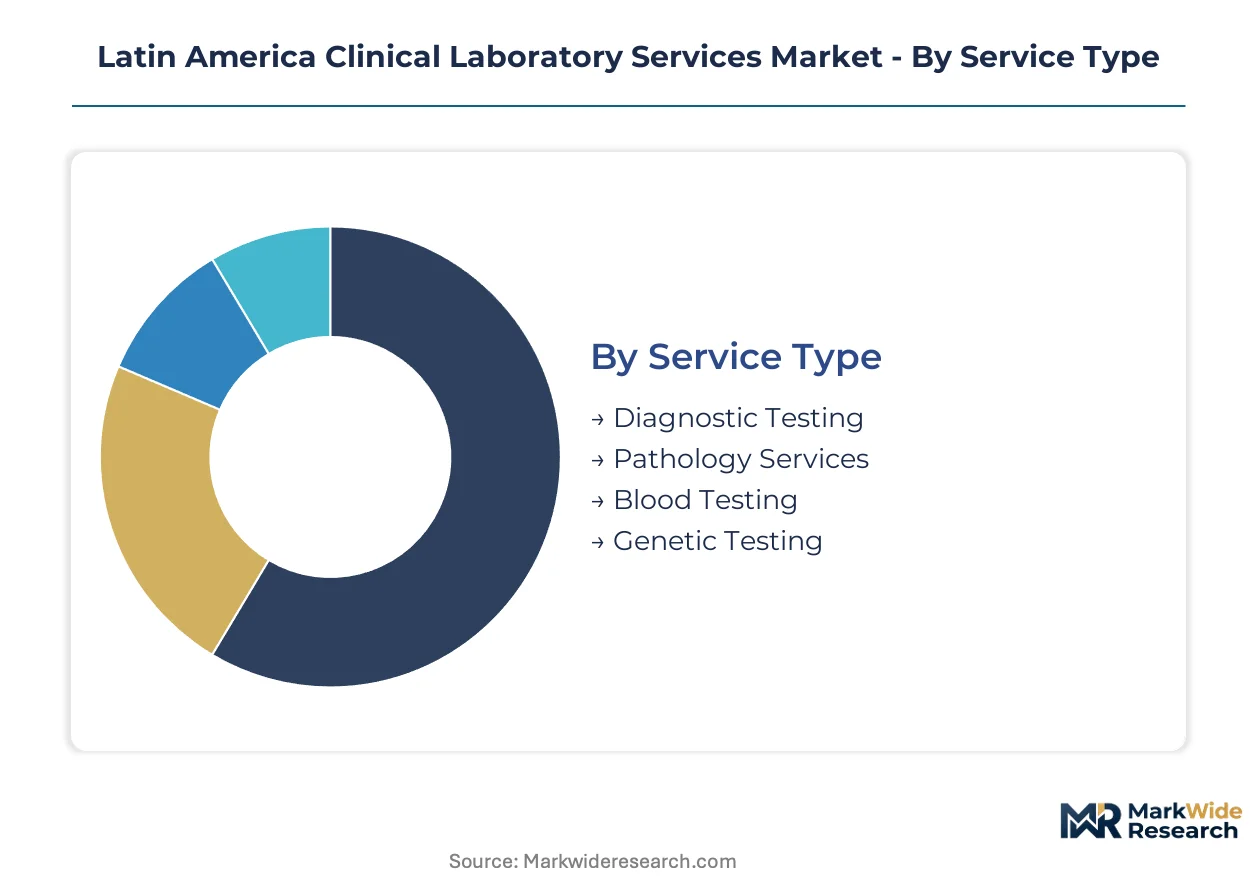
Clinical laboratory services fragment across multiple dimensions that determine procurement patterns, margin structures, and accreditation requirements. Understanding how service types, technologies, and product categories interlock reveals where capital concentrates and which segments drive workflow redesign across Brazil, Mexico, and Argentina.
Service Type:
Standalone diagnostic testing commands dedicated laboratory infrastructure, while pathology and genetic services increasingly embed within hospital networks and academic consortia.
- Diagnostic Testing:Routine chemistry panels, electrolyte analysis, and organ function assays processed on automated analyzers with ISO 15189-mandated turnaround thresholds. São Paulo's hospital networks and Mexico's central corridor private chains are expanding test volumes for diabetes and cardiovascular monitoring, driven by aging demographics and chronic disease surveillance protocols.
- Pathology Services:Tissue processing, histopathology, and cytopathology requiring specialized technician certification and physical slide archives. Brazil's DASA and Fleury networks concentrate anatomic pathology capacity in southeastern hubs, while digital pathology platforms extend specialist access to secondary cities in Brazil's Northeast and Mexico's Yucatán Peninsula.
- Blood Testing:Transfusion medicine, coagulation studies, and blood bank screening with strict cold-chain logistics.
- Genetic Testing:Pharmacogenomics and hereditary disease screening penetrating oncology practices in Santiago and Bogotá.
Diagnostic testing leads volumes today; genetic testing is gaining share fastest.
End User:
Procurement authority concentrates differently across institutional buyers, with research laboratories converting federal funding into specialized molecular infrastructure while hospitals optimize throughput economics.
- Hospitals:High-volume centralized laboratories serving inpatient and emergency departments with 24-hour stat testing capabilities. Brazil's ANVISA updated diagnostic quality standards are accelerating equipment validation protocols and reagent import pathway formalization, favoring accredited multi-site hospital operators over single-facility competitors.
- Research Laboratories:Genomic and infectious-disease surveillance programs deployed by academic consortia across Colombia and Chile. These facilities represent the steepest expansion trajectory as federal research funding and international health security initiatives convert basic science capacity into clinical service revenue.
- Clinics:Limited-service collection points feeding hub-and-spoke networks.
- Academic Institutions:Teaching hospitals with dual clinical-training and patient-service missions.
Hospitals anchor current revenue; research laboratories are expanding most quickly.
Technology:
Capital intensity varies sharply across technology tiers, with molecular platforms requiring specialized workforce training while immunoassay analyzers achieve faster depreciation through higher daily test volumes.
- Molecular Diagnostics:PCR, nucleic acid amplification, and next-generation sequencing platforms integrating with automated sample preparation workflows. Hospital-based laboratories in São Paulo and Mexico City are adopting these systems at accelerated pace to retain referral volumes from academic medical centers, displacing sequential testing protocols that previously required days.
- Immunoassays:Antibody-antigen detection systems for endocrine, infectious disease, and tumor marker applications with the highest test-volume position across hospital end users. These analyzers occupy the core production floor space in Brazil's Grupo LAPI regional coverage model and Mexico's private diagnostic chains.
- Hematology Analyzers:Cell counting and differential systems with rapid turnaround for emergency departments.
- Blood Gas Analyzers:Point-of-care and laboratory-based systems for critical care monitoring.
Immunoassays dominate throughput today; molecular diagnostics commands premium expansion.
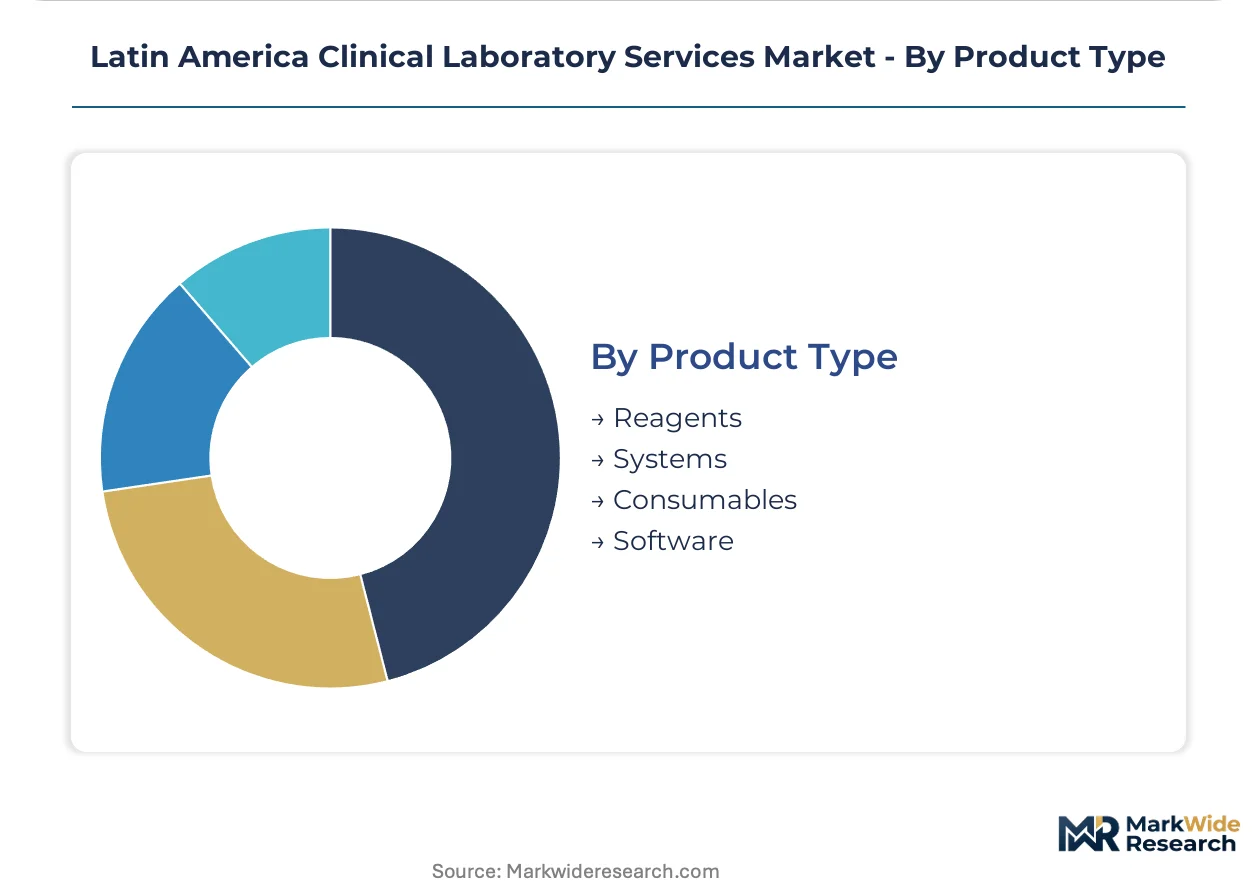
Product Type:
Recurring revenue stability concentrates in consumables and reagents, while systems sales carry higher upfront margin volatility tied to currency fluctuations and import clearance timelines.
- Reagents:Specialized immunoassay and molecular diagnostic consumables with recurring revenue streams that outpace systems in margin stability. Latin American laboratories rely on concentrated North American and European suppliers, exposing procurement to currency volatility and customs clearance friction.
- Systems:Automated analyzers and platform hardware with 7-10 year depreciation cycles and significant capital deployment requirements. ANVISA's updated Good Laboratory Practice enforcement is mandating electronic data integrity capabilities, forcing laboratory information management system upgrades across Brazil's private diagnostic chains.
- Consumables:Pipette tips, collection tubes, and disposables with volume-scaled pricing.
- Software:Laboratory information management systems and middleware for device integration.
Reagents anchor recurring revenue; software is penetrating fastest as compliance mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest share of clinical laboratory capacity while Mexico's central corridor concentrates the fastest-growing private diagnostic networks. Argentina, Chile, and Colombia each present distinct regulatory and infrastructure profiles that shape market entry economics.
Brazil
São Paulo state anchors the nation's laboratory density with hospital networks expanding chronic disease test volumes for diabetes and cardiovascular monitoring. ANVISA's updated Good Laboratory Practice standards mandate electronic data integrity systems and audit trail capabilities across all accredited facilities. DASA's southeastern hub-and-spoke network demonstrates centralized testing paired with rapid logistics to capture suburban patient volumes.
Mexico
Private healthcare networks in Mexico City's central corridor are consolidating laboratory procurement to optimize throughput economics. COFEPRIS enforces periodic external quality assessment programs that impose recurring operational burdens on single-site operators. The Yucatán Peninsula is adopting digital pathology platforms to extend specialist access beyond metropolitan centers.
Argentina
Hospital-based laboratories in Buenos Aires retain the highest concentration of certified clinical laboratory scientists with molecular diagnostics training. The country's national pharmaceutical regulator mandates calibration traceability for all diagnostic equipment validation protocols. Secondary cities face workforce scarcity that constrains hub-and-spoke model expansion into Córdoba and Rosario corridors.
Chile
Academic consortia in Santiago are deploying genomic and infectious-disease surveillance programs that convert research capacity into clinical service revenue. The national health regulator requires ISO 15189 accreditation for all facilities processing specimens from public health programs. Pharmacogenomics applications are penetrating oncology practices in the Santiago metropolitan cluster.
Colombia
INVIMA's Good Laboratory Practice standards shape equipment validation requirements and reagent import pathways for hospital networks in Bogotá. Research laboratories represent the steepest expansion trajectory as federal funding converts basic science infrastructure into molecular diagnostics capability. The capital's academic medical centers are integrating next-generation sequencing platforms with automated sample preparation workflows.
Latin America Clinical Laboratory Services Market Competitive Landscape
Brazilian operators anchor the scale-driven tier; North American and European specialists hold technology and protocol differentiation. The market presents moderate consolidation with multi-site diagnostic chains capturing metropolitan volumes while single-site laboratories face accreditation cost pressure. Three archetypes dominate: vertically integrated hub-and-spoke networks, premium-brand urban specialists, and cost-efficient regional coverage operators. Competitive moves concentrate on hub-and-spoke geographic expansion and laboratory information system integration partnerships.
Within the Brazilian integrated network tier, DASA and Fleury exemplify contrasting positioning strategies. DASA leverages southeastern Brazil density across imaging, diagnostics, and delivery capabilities. Fleury competes on brand recognition among affluent urban patients in São Paulo's premium healthcare segment. Grupo LAPI anchors cost-efficient regional coverage that secures public-sector contracts while maintaining private-pay revenue streams. Quest Diagnostics Incorporated extends North American quality protocols to Latin American partnerships, differentiating on standardized reporting frameworks.
| Leading Market Players |
|---|
| Grupo LAPI |
| Laboratory Corporation of America Holdings (LabCorp) |
| DASA |
| QIAGEN |
| OPKO Health, Inc. |
| Fleury |
| Quest Diagnostics Incorporated |
| Siemens Healthcare GmbH |
| Laboratorio Chopo |
| Others |
Value Network & Pricing Analysis
Backward integration into reagent manufacturing anchors both supply security and pricing power for Brazil's largest diagnostic chains, as ANVISA's import pathway formalization elevates the strategic value of captive sourcing arrangements. This structural choice separates accredited multi-site operators from single-facility competitors exposed to currency volatility and customs clearance friction.
Pricing Analysis
Capacity additions in São Paulo state are reshaping price floors for routine chemistry panels and immunoassay bundles, compressing margins for standalone laboratories while preserving premium capture at molecular diagnostics tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 15189 accreditation status and turnaround-time guarantees, with public-sector procurement tenders driving cost compression in regional coverage contracts. Price differentiation hinges on electronic data integrity capabilities mandated by ANVISA's updated Good Laboratory Practice standards. Private healthcare networks in Mexico's central corridor exhibit lowest price sensitivity due to consolidated procurement authority, while single-site rural laboratories in Brazil's Northeast face acute margin pressure from proficiency testing cost burdens.
Supply Chain Analysis
ANVISA's equipment validation protocols and INVIMA's calibration traceability mandates are gating supplier qualification, extending procurement cycles for automated analyzers and molecular diagnostic platforms. Reagent supply concentrates in the United States, Germany, and Japan for specialized immunoassay consumables and nucleic acid amplification chemistries. Component dependencies span optical detection modules, precision fluidics systems, and temperature-controlled reagent cartridges. Single-source vulnerability runs through concentrated North American suppliers for next-generation sequencing consumables, exposing Brazilian and Mexican laboratories to tariff exposure and logistics chokepoints at port-of-entry customs clearance. Distribution runs through hub-and-spoke networks anchored by DASA's southeastern Brazil density and Grupo LAPI's regional coverage model, with rapid logistics partnerships extending reach into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with ANVISA's electronic data integrity mandates and ISO 15189 accreditation requirements shifting procurement authority toward operators with proven compliance infrastructure and multi-site standardization capabilities.
For Market Incumbents: Deepen laboratory information management system integration partnerships to harmonize legacy equipment from multiple manufacturers with centralized data platforms, defending against emerging digital pathology platforms that threaten real-time reporting differentiation. Prioritize accreditation investment in Rio de Janeiro and Minas Gerais states where medium-sized operators face consolidation pressure, capturing test volume aggregation before cost-efficient regional coverage models anchor public-sector contracts. For New Entrants and Emerging Players: Capture genomic medicine expansion opportunities in Santiago and Bogotá where pharmacogenomics and liquid biopsy applications are penetrating oncology practices without entrenched incumbent relationships. Target research laboratories in Colombia and Chile as the most penetrable end-user channel, converting federal funding and international health security initiatives into specialized molecular infrastructure partnerships. Deploy automated sample preparation workflows as the go-to-market angle to displace sequential testing protocols that previously required days. For Investors and Strategic Acquirers: Roll-up economics work for cost-efficient regional coverage operators because ANVISA's 12-to-18-month accreditation cycles for each new collection facility compress expansion velocity and favor acquisition over greenfield development. Long-term viability centers on platforms with demonstrated public-private contract anchoring capability and proven logistics integration for hub-and-spoke model execution. Monitor digital pathology platform adoption rates in Brazil's Northeast and Mexico's Yucatán Peninsula as the signal indicating inflection in specialist access decentralization.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Multi-Site Accreditation | ANVISA mandates compress operational timelines while elevating capital barriers for market entry. |
| Reagent Import Pathway Formalization | COFEPRIS and INVIMA enforcement exposes margins to currency volatility and customs friction. |
| Digital Pathology Platform Integration | Remote diagnostic systems extend specialist access beyond São Paulo and Mexico City metropolitan clusters. |
| Hub-and-Spoke Network Expansion | DASA's southeastern Brazil density demonstrates centralized testing paired with rapid suburban logistics capture. |
| Genomic Medicine Infrastructure Buildout | Academic consortia in Santiago and Bogotá convert federal funding into clinical service revenue streams. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Chile, and Colombia, with primary inputs from each market's hospital procurement committees, clinical laboratory directors, regulatory affairs specialists at ANVISA and COFEPRIS, and biomedical engineers at academic medical centers. Secondary validation draws from ANVISA diagnostic quality standard filings, COFEPRIS external quality assessment program disclosures, ISO 15189 accreditation registries, hospital procurement databases, and GPO contracts. Bottom-up test volume modeling triangulates against top-down healthcare expenditure allocation analysis.
Granularity-level framing segments the market by service type, technology platform, end-user institution, and product category, with additional modeling at the state and metropolitan cluster level for Brazil and Mexico. CAGRs derive from test volume expansion trajectories, reimbursement rate evolution, and capital deployment patterns across the projection horizon. Industry-specific forecast inputs include chronic disease surveillance protocol adoption rates and molecular diagnostics capability deployment timelines at academic medical centers.
Regulatory enforcement intensity shifts, currency volatility spikes, and workforce training pipeline constraints are the dominant revision risks that could materially alter trajectory assumptions. A model refresh is warranted upon material change in ANVISA accreditation mandate timelines or COFEPRIS reagent import pathway requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
LIMS Market
Laboratory Services
Pathology Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Global Virology Specimen Collection Market