
 Pharmaceutical Dissolution Testing Services Market | 2026-2036
Pharmaceutical Dissolution Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Dissolution Testing Services Market Intelligence
The shift from captive in-house dissolution laboratories toward outsourced multi-vendor partnerships is broadening the addressable base for contract testing providers. Thermo Fisher Scientific leverages its integrated analytical instrument and services portfolio to anchor large-scale pharmaceutical accounts. Eurofins Scientific SE sustains geographic density across North American and European regulatory jurisdictions. Catalent, Inc. competes through specialized biologics formulation support that embeds dissolution testing within broader development workflows.
Pharmaceutical dissolution testing services encompass analytical methodologies that quantify drug release kinetics from solid dosage forms under standardized hydrodynamic and physicochemical conditions, typically employing USP apparatus configurations at 37°C with specified dissolution media. These services verify batch uniformity, support bioequivalence determinations, and enable formulation optimization across oral solid dose pipelines. Method development and validation services command premium pricing due to regulatory stringency and technical complexity, while automated systems adoption is displacing manual equipment in high-throughput quality control environments. Contract laboratories represent the fastest-growing end-user channel as mid-tier pharmaceutical companies abandon capital-intensive in-house analytical infrastructure.
FDA bioequivalence requirements and USP general chapters directly shape dissolution testing scope and frequency across generic and innovator drug programs. EMA guidelines and the EU's Falsified Medicines Directive reinforce demand for documented batch-release testing within European supply chains. Stakeholders must monitor evolving regulatory harmonization between FDA, EMA, and emerging market agencies to anticipate shifts in method validation requirements and cross-border testing acceptability.
Market Dynamics
Contract laboratories are capturing dissolution testing volumes as mid-tier pharmaceutical companies dismantle in-house analytical infrastructure to preserve capital for core R&D programs. This structural migration from captive facilities to outsourced partnerships is redrawing competitive boundaries across the analytical services landscape.
Growth Catalysts
- FDA ANDA bioequivalence standards:Tightened requirements for generic drug approvals are expanding mandatory dissolution testing protocols across abbreviated new drug applications.
- Biopharmaceutical pipeline complexity:Complex generic development programs for modified-release formulations require specialized dissolution method development services.
- United States regulatory filing concentration:The surge in ANDA submissions from domestic and international sponsors concentrates demand for US-based contract testing capacity.
Market Restraints
- Specialized equipment capital intensity:USP apparatus 4 flow-through cell systems and automated sampling platforms require substantial upfront investment, limiting laboratory expansion flexibility.
- Skilled analytical chemist scarcity:Method development and validation expertise in dissolution science remains concentrated among a narrow pool of experienced practitioners.
- European Falsified Medicines Directive compliance costs:Batch-release documentation requirements impose additional quality system overhead on contract laboratories serving EU supply chains.
Strategic Opportunities
- India CDSCO generic export certification:Contract laboratories supporting ANDA-bound products from Indian manufacturing sites can capture testing volumes tied to US market entry.
- Biologics formulation integration:Embedding dissolution testing within broader development workflows for complex parenteral and oral biologic formulations creates service bundling potential.
- High-throughput automation convergence:Robotics and online UV-Vis detection systems are compressing turnaround times for quality control batch testing.
Industry Challenges
- Method transfer standardization delays:Sponsor-to-contractor analytical method transfers frequently encounter reproducibility failures requiring iterative troubleshooting.
- Legacy data management system integration:Laboratory information management system migrations from paper-based or hybrid electronic records impose validation burdens and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Dissolution Testing Services Market |
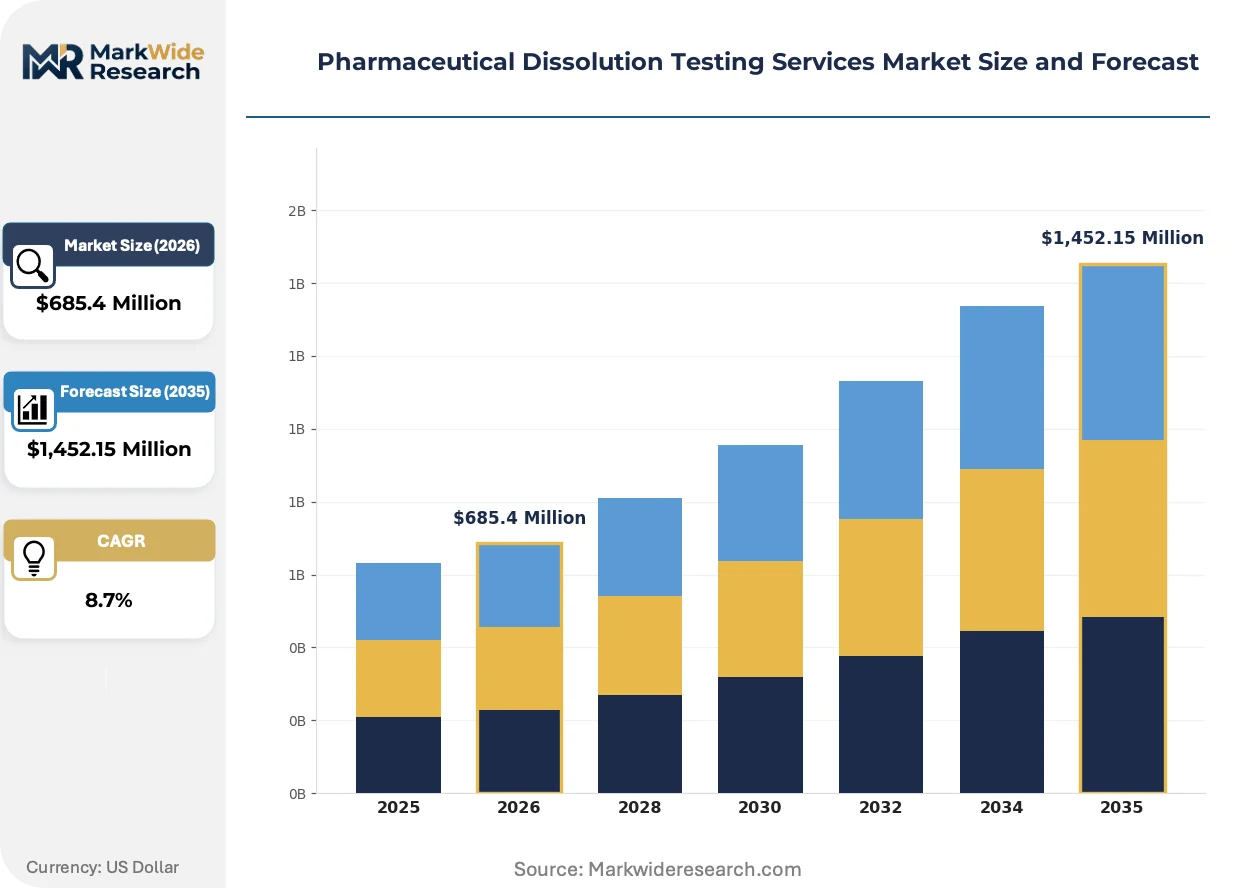
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Method Development, Validation, Stability Testing, Routine Testing End User: Pharmaceutical Companies, Contract Laboratories, Research Institutions, Regulatory Agencies Technology: Automated Systems, Manual Equipment, USP Compliant Systems, Bioavailability Testing Application: Formulation Development, Quality Control, Research & Development, Compliance Testing |
| Companies Covered | Intertek Group Plc, Danaher Corporation (Cytiva), Thermo Fisher Scientific Inc., Avivia BV, Almac Group, Charles River Laboratories International, Inc., Catalent, Inc., Eurofins Scientific SE, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Dissolution Testing Services Market Strategic Shifts & Innovations
Automation and regulatory harmonization are converging to compress dissolution testing timelines while elevating data integrity requirements. These forces are reshaping capital deployment patterns and competitive differentiation strategies across contract analytical services.
Robotic sample handling and online analytical detection systems are overtaking manual USP apparatus configurations in high-throughput quality control environments. Large-volume pharmaceutical manufacturers are adopting these platforms to achieve 24-hour batch release cycles. The technology is overtaking labor-intensive workflows and compressing per-test economics for contract laboratories competing on speed.
EMA guidelines on bioequivalence for immediate-release oral dosage forms are tightening dissolution profile comparison criteria for generic drug approvals. This regulatory evolution is expanding method validation scope and documentation requirements for European market access. Complex generic sponsors are responding by front-loading dissolution development resources earlier in formulation design.
Mid-tier pharmaceutical companies are consolidating vendor relationships around integrated analytical service partnerships rather than fragmenting testing across multiple specialized providers. This procurement consolidation is displacing transactional testing arrangements with multi-year framework agreements. The pattern is most visible among US-based generic companies restructuring post-ANDA approval supply chains.
Pharmaceutical Dissolution Testing Services Market Segmentation
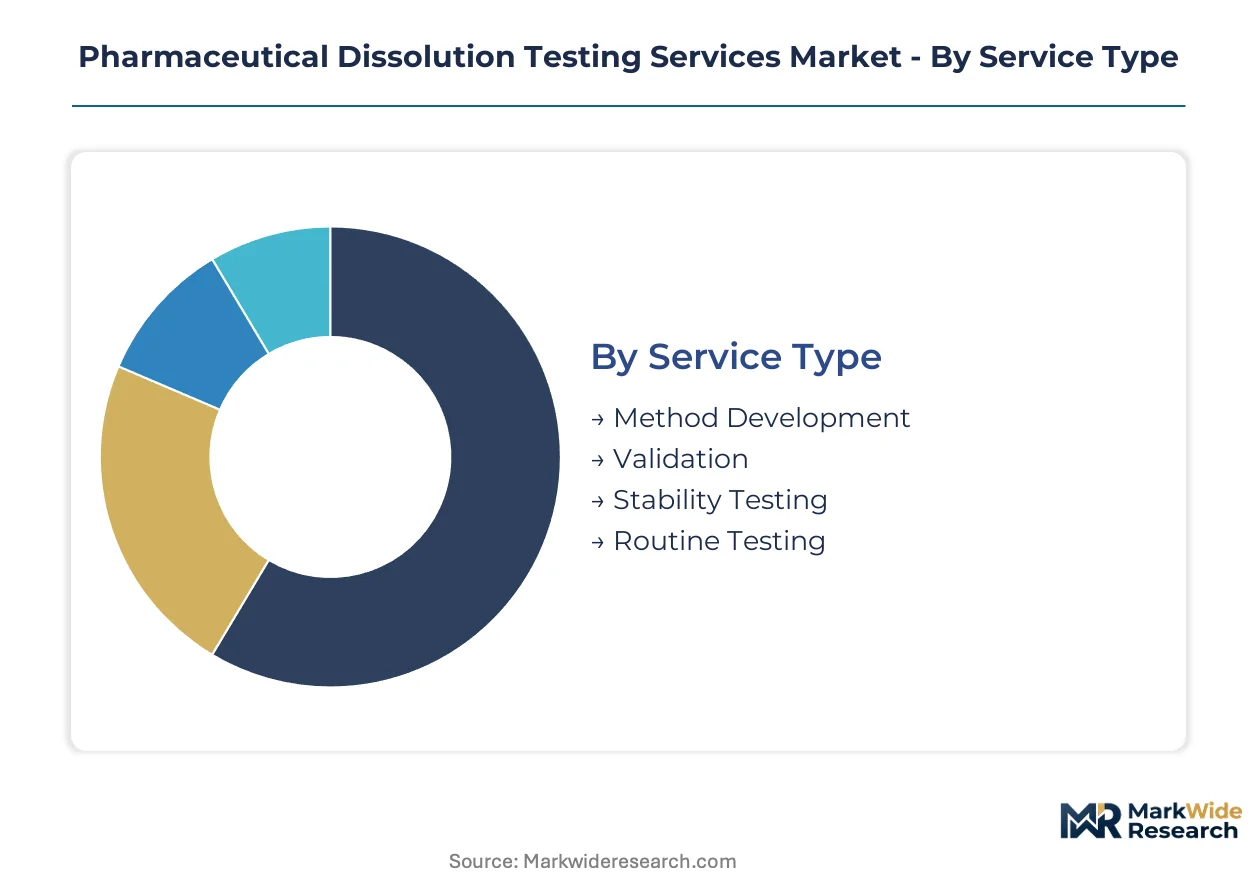
Dissolution testing service providers must align capabilities across distinct technical workflows, customer capital structures, and regulatory submission pathways. Segmentation reveals where method complexity commands premium pricing versus where automation drives volume economics.
Service Type:
Method development and validation services capture premium margins through regulatory stringency, while routine testing scales through automation and throughput efficiency.
- Method Development:Custom dissolution protocols for novel formulations, modified-release designs, and complex generics require iterative physicochemical optimization. US generic sponsors front-load these investments to preempt FDA bioequivalence queries during ANDA review cycles.
- Validation:Formal demonstration of analytical method robustness, precision, and specificity under ICH Q2(R1) guidelines. European market entry demands comprehensive validation packages that extend project timelines but lock in multi-year testing relationships.
- Stability Testing:Long-term dissolution profile monitoring under ICH storage conditions.
- Routine Testing:High-volume batch release and quality control dissolution analysis.
Today's leader: Method Development. Tomorrow's challenger: Routine Testing.
End User:
Customer type determines pricing power, contract duration, and technical support intensity across the service portfolio.
- Pharmaceutical Companies:Innovator and generic drug manufacturers with captive analytical needs. Large US generic sponsors are dismantling in-house dissolution laboratories and migrating testing to outsourced partnerships, expanding addressable contract volumes.
- Contract Laboratories:Third-party analytical service providers serving as intermediaries or overflow capacity. Mid-tier CDMOs in India and the United States are consolidating vendor relationships around integrated testing partnerships rather than fragmented transactional arrangements.
- Research Institutions:Academic and government laboratories conducting preclinical formulation research.
- Regulatory Agencies:Government laboratories performing reference testing and compliance verification.
Pharmaceutical Companies anchor current revenue. Contract Laboratories are climbing the fastest as outsourcing accelerates.
Technology:
Equipment sophistication separates high-throughput quality control environments from specialized bioequivalence studies.
- Automated Systems:Robotic sample handling, online UV-Vis detection, and unattended USP apparatus operation. Large-volume manufacturers in the United States deploy these platforms to compress batch release cycles toward 24-hour turnaround targets.
- Manual Equipment:Traditional USP apparatus 1 and 2 configurations with operator-dependent sampling. Smaller generic sponsors and research institutions retain manual systems for low-volume or developmental work where capital constraints outweigh throughput needs.
- USP Compliant Systems:Standardized apparatus meeting United States Pharmacopeia general chapter requirements.
- Bioavailability Testing:In vitro-in vivo correlation studies linking dissolution profiles to pharmacokinetic outcomes.
Automated Systems dominate new capital deployment. USP Compliant Systems retain installed base defense.
Application:
Development stage dictates method complexity, documentation requirements, and regulatory submission urgency.
- Formulation Development:Early-stage dissolution screening to guide excipient selection and release kinetics design. Complex generic sponsors embed dissolution testing earlier in formulation workflows to preempt EMA and FDA bioequivalence challenges for modified-release products.
- Quality Control:Batch release testing against validated specification criteria. The EU Falsified Medicines Directive intensifies documentation and traceability requirements for European supply chain entry, elevating quality system overhead.
- Research & Development:Exploratory dissolution studies for pipeline compounds and novel dosage forms.
- Compliance Testing:Regulatory submission support and agency query response.
Quality Control commands current volume. Formulation Development offers steepest expansion trajectory as complex generics multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's pharmaceutical corridor anchors global dissolution testing demand through dense concentrations of generic sponsors and contract research organizations serving FDA submission pathways.
United States
ANDA filing volumes from domestic and international sponsors concentrate testing demand in New Jersey, Massachusetts, and North Carolina clusters. FDA bioequivalence standards for complex generics expand method development scope. Philadelphia-area contract laboratories absorb overflow from sponsor dismantling of captive analytical infrastructure.
Germany
EMA bioequivalence guidelines for immediate-release formulations tighten dissolution profile comparison criteria across generic development programs. The EU Falsified Medicines Directive elevates batch-release documentation requirements for European supply chain entry. Bavaria-based analytical service providers capture validation-intensive projects from mid-tier pharmaceutical sponsors.
India
CDSCO export certification requirements for ANDA-bound products drive contract testing partnerships with US-facing laboratories. Hyderabad and Ahmedabad manufacturing clusters outsource dissolution method development to preserve capital for core R&D. Mumbai-based service providers integrate testing within broader generic development workflows.
Switzerland
Swissmedic regulatory alignment with EMA standards positions Basel and Zurich laboratories as European validation hubs. Complex biologics formulation programs embed dissolution testing within integrated development services. The country's precision instrumentation heritage supports high-throughput automation deployment.
United Kingdom
Post-Brexit regulatory divergence from EMA creates dual validation requirements for UK-EU market access. Southeast England analytical clusters specialize in method transfer troubleshooting for sponsor-contractor transitions. MHRA consultation procedures extend timelines but lock in multi-year testing relationships.
Pharmaceutical Dissolution Testing Services Market Key Industry Players
Global majors compete with regional champions across regulatory jurisdiction coverage and specialized formulation expertise. The vendor base stratifies into three tiers: integrated life science conglomerates with instrument-service bundling, mid-scale contract research organizations with geographic density, and niche specialists in complex dosage form analytics. Dominant competitive moves include laboratory automation capital deployment and multi-year framework agreements replacing transactional testing arrangements.
Among integrated analytical conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation (Cytiva) exemplify instrument-to-service vertical bundling strategies. Eurofins Scientific SE and Charles River Laboratories International, Inc. occupy positions within the mid-tier geographic expansion archetype. Catalent, Inc. and Almac Group represent formulation-embedded testing specialists serving biologics development workflows.
| Leading Market Players |
|---|
| Intertek Group Plc |
| Danaher Corporation (Cytiva) |
| Thermo Fisher Scientific Inc. |
| Avivia BV |
| Almac Group |
| Charles River Laboratories International, Inc. |
| Catalent, Inc. |
| Eurofins Scientific SE |
| Agilent Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up contract laboratory networks in the United States and Europe have consolidated analytical capacity while enforcing pricing discipline through multi-year framework agreements. This ownership pattern concentrates supply-side leverage among Thermo Fisher Scientific, Eurofins Scientific SE, and Charles River Laboratories, compressing procurement options for mid-tier pharmaceutical sponsors seeking dissolution testing services.
Pricing Analysis
Input-cost pass-through from specialized USP apparatus 4 flow-through cell systems and robotic sampling platforms elevates method development and validation pricing above routine batch-release testing. Three-tier pricing structure across premium, standard, and economy levels separates FDA submission-grade validation packages from developmental screening and high-throughput QC contracts. Pricing pressure stems from Indian CDSCO export certification demands compressing margins on ANDA-bound testing volumes. Large US generic sponsors exhibit lowest price sensitivity due to regulatory submission urgency, while mid-tier research institutions face capital constraints that favor manual equipment configurations.
Supply Chain Analysis
Single-source vulnerability sits with German precision instrumentation manufacturers supplying automated dissolution apparatus to North American contract laboratories. Equipment manufacturing concentrates in Germany, Switzerland, and the United States, while consumables and reagents draw from domestic chemical supply networks. Supply chain risk centers on tariff exposure for EU-manufactured analytical instruments entering US pharmaceutical corridors. Distribution runs through direct manufacturer-to-laboratory relationships for capital equipment, with reagent supply channeled through regional chemical distributors serving New Jersey and Massachusetts testing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as FDA and EMA bioequivalence standards tighten dissolution profile comparison criteria, shifting sponsor procurement toward premium validation capabilities over commodity testing.
For Market Incumbents: Deepen vertical integration into automated USP apparatus manufacturing to capture equipment-service bundling economics and defend against instrument-to-service conglomerates. Invest in FDA 483 response expertise and method transfer standardization protocols to lock in multi-year framework agreements with generic sponsors dismantling captive laboratories. For New Entrants and Emerging Players: Enter via CDSCO export certification partnerships serving Hyderabad and Ahmedabad manufacturing clusters seeking US-facing dissolution validation. Target mid-tier Indian generic developers as the most penetrable segment, leveraging lower-cost analytical chemist talent pools and 24-hour turnaround commitments against established US laboratory timelines. For Investors and Strategic Acquirers: Contract development and manufacturing organizations with integrated analytical services are the most active acquirer in this space, seeking dissolution testing capabilities to embed within broader formulation development workflows. Acquisition target archetype: regional contract laboratories with FDA inspection history and validated USP methods transferable across sponsor portfolios. Watch ANDA approval velocity as the signal indicating inflection in outsourced testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Automation Deployment | Robotic USP apparatus configurations compress batch release cycles toward 24-hour targets for large-volume manufacturers. |
| Regulatory Validation Investment | FDA bioequivalence method development capabilities lock in multi-year testing relationships with ANDA sponsors. |
| Geographic Expansion | Philadelphia-area and Bavaria-based laboratory capacity captures overflow from sponsor dismantling of captive infrastructure. |
| Biologics Formulation Integration | Embedding dissolution testing within complex parenteral development workflows creates service bundling potential. |
| High-Throughput Quality Control Scaling | Online UV-Vis detection systems displace manual workflows in contract laboratories competing on speed. |
Research Approach
Bottom-up pharmaceutical sponsor modeling reconciled against top-down contract laboratory capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, analytical development directors, contract laboratory procurement managers, and ANDA program executives were cross-validated against secondary sources including FDA ANDA filing databases, EMA bioequivalence submission records, USP general chapter documentation, and SEC 10-K disclosures from listed analytical service providers.
Historical dissolution testing volume trends across pharmaceutical and generic drug development pipelines established baseline growth patterns without year-specific anchoring. Segmentation modeling incorporated service type, end-user category, technology tier, and application stage dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from sponsor R&D spending trajectories, ANDA approval rates, and contract laboratory revenue expansion patterns across the projection horizon.
Inputs from FDA filing databases and EMA submission portals were available through the study window; gaps in private contract laboratory pricing disclosures introduce uncertainty bands around revenue estimates. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and automation adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global CA 125 Test Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Home Care Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Global Bioburden Testing Market
Testing Services
Target-Based ADME/ Tox Assay Market