
 Dry Eye Disease Market | 2026-2036
Dry Eye Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Eye Disease Market Intelligence
Subscription models for chronic therapies are decoupling product sales from one-time prescriptions, creating recurring revenue streams for manufacturers. AbbVie Inc. leverages its established pharmaceutical channels to promote its portfolio of eye care treatments. Novartis AG competes through extensive R&D in novel anti-inflammatory compounds for ocular conditions. Meanwhile, Alcon Inc. dominates the surgical and vision care space with a comprehensive device and consumable offering.
Dry eye disease is a multifactorial condition of the ocular surface characterized by a loss of homeostasis of the tear film. It is clinically identified by symptoms of discomfort and visual disturbance, with tear film instability and hyperosmolarity as key etiological markers. Anti-inflammatory drugs like cyclosporine and lifitegrast represent a high-margin product category, requiring prescriptions and consistent clinical oversight. Therapies targeting Evaporative Dry Eye, the most common form, are a primary focus for pipeline development across the industry.
Regulatory pathways defined by the FDA in the United States and the EMA in Europe dictate clinical trial requirements for new drug approvals. In parallel, Japan's PMDA sets specific standards for regenerative medicine and advanced therapy products targeting ocular surface diseases. These frameworks shape market access and influence investment in specific therapeutic modalities over others. Stakeholders must now decide whether to prioritize novel mechanisms of action or pursue lifecycle management for existing blockbuster drugs.
Market Dynamics
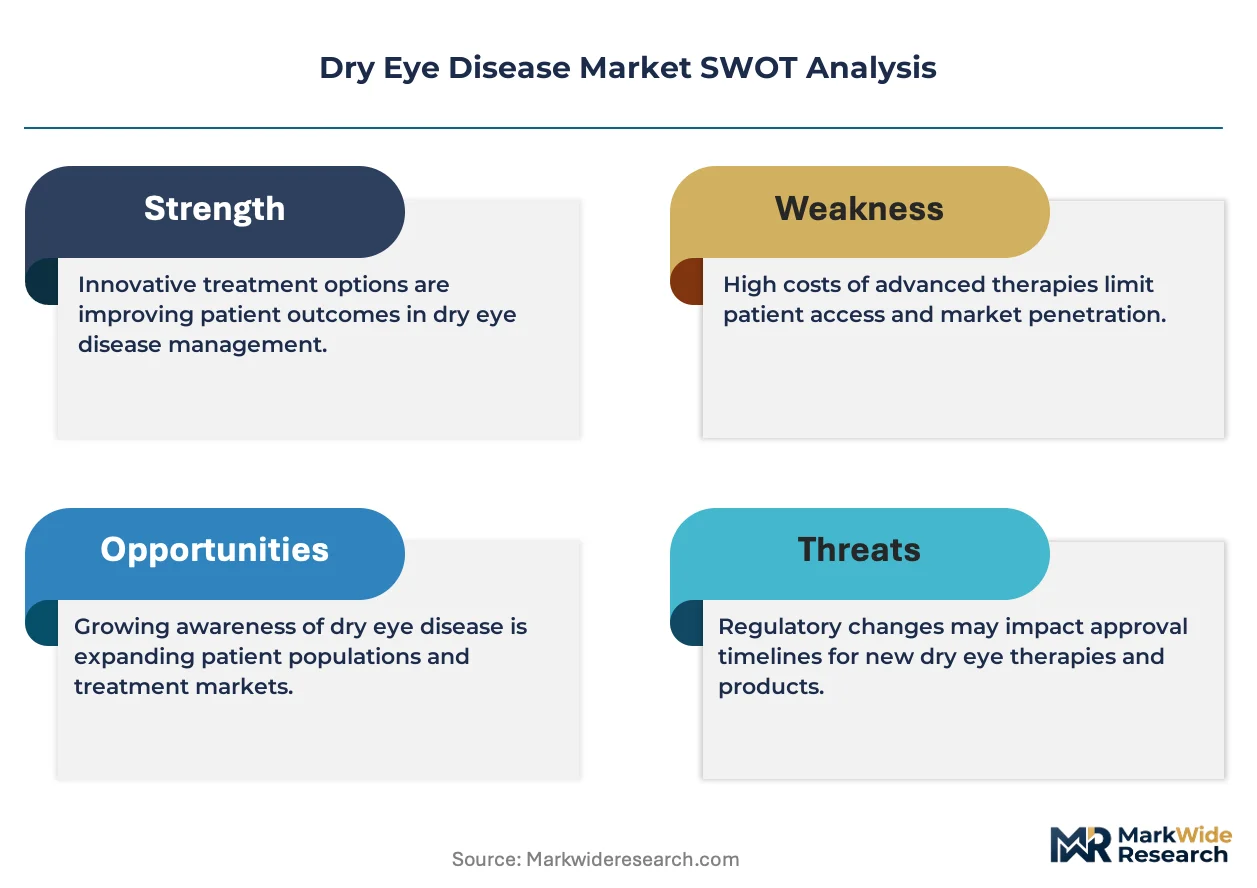
The central structural force shaping the market is the clinical pivot from palliative symptom relief towards treating the underlying pathophysiology, particularly Meibomian Gland Dysfunction. This shift redefines therapeutic goals and elevates the role of advanced diagnostics in patient management.
Growth Catalysts
- Novel Formulations:The development of advanced lipid-based emulsions and non-aqueous solutions that specifically target tear film stability and reduce evaporation represents a primary technological driver for the evaporative dry eye segment.
- Aging Demographics:Countries with rapidly aging populations, including Japan and Germany, exhibit a higher prevalence of chronic conditions like dry eye, creating a concentrated and sustained source of patient demand for new therapies.
- Specialized Care Models:The expansion of dedicated Specialized Ophthalmology Centers facilitates the adoption of advanced diagnostic tools and supports the prescription of higher-margin, long-term therapies requiring consistent clinical monitoring.
Market Restraints
- Reimbursement Hurdles:The high cost of prescription anti-inflammatory drugs like cyclosporine and lifitegrast faces resistance from payers, limiting patient access in markets without favorable reimbursement policies for chronic therapies.
- Regulatory Fragmentation:Divergent clinical trial requirements between the FDA in the United States, the EMA in Europe, and Japan's PMDA increase the cost and complexity of securing simultaneous multi-market approvals for new drugs.
- OTC Substitution:A wide availability of low-cost over-the-counter artificial tears and lubricating gels provides a first-line palliative option that can delay or prevent patients with mild-to-moderate symptoms from seeking a formal diagnosis and prescription treatment.
Strategic Opportunities
- Regenerative Medicine in Japan:Specific regulatory pathways established by Japan's PMDA for advanced therapy products create a targeted opportunity for companies developing regenerative treatments for ocular surface diseases to prioritize market entry in Japan.
- Digital Health Integration:The convergence of mobile applications for symptom tracking and treatment adherence with subscription-based drug delivery models offers a new channel for improving patient outcomes and building brand loyalty.
- Emerging Market Penetration:Large, urbanizing countries with growing middle-class populations and increasing screen time represent significant untapped markets where diagnostic infrastructure and therapeutic awareness are still developing.
Industry Challenges
- Clinical Trial Endpoints:The multifactorial nature of dry eye disease complicates the design of clinical trials, as regulators demand demonstration of efficacy on both objective signs and subjective patient-reported symptoms, which do not always correlate.
- Chronic Therapy Adherence:Ensuring long-term patient compliance with prescribed treatment regimens is a major operational challenge, as poor adherence can undermine therapeutic efficacy and impact the recurring revenue streams essential for manufacturers.
- Diagnostic Standardization Gaps:The absence of a single, universally accepted gold standard for diagnosing and staging dry eye disease leads to inconsistencies in clinical practice and complicates patient selection for global clinical studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Eye Disease Market |
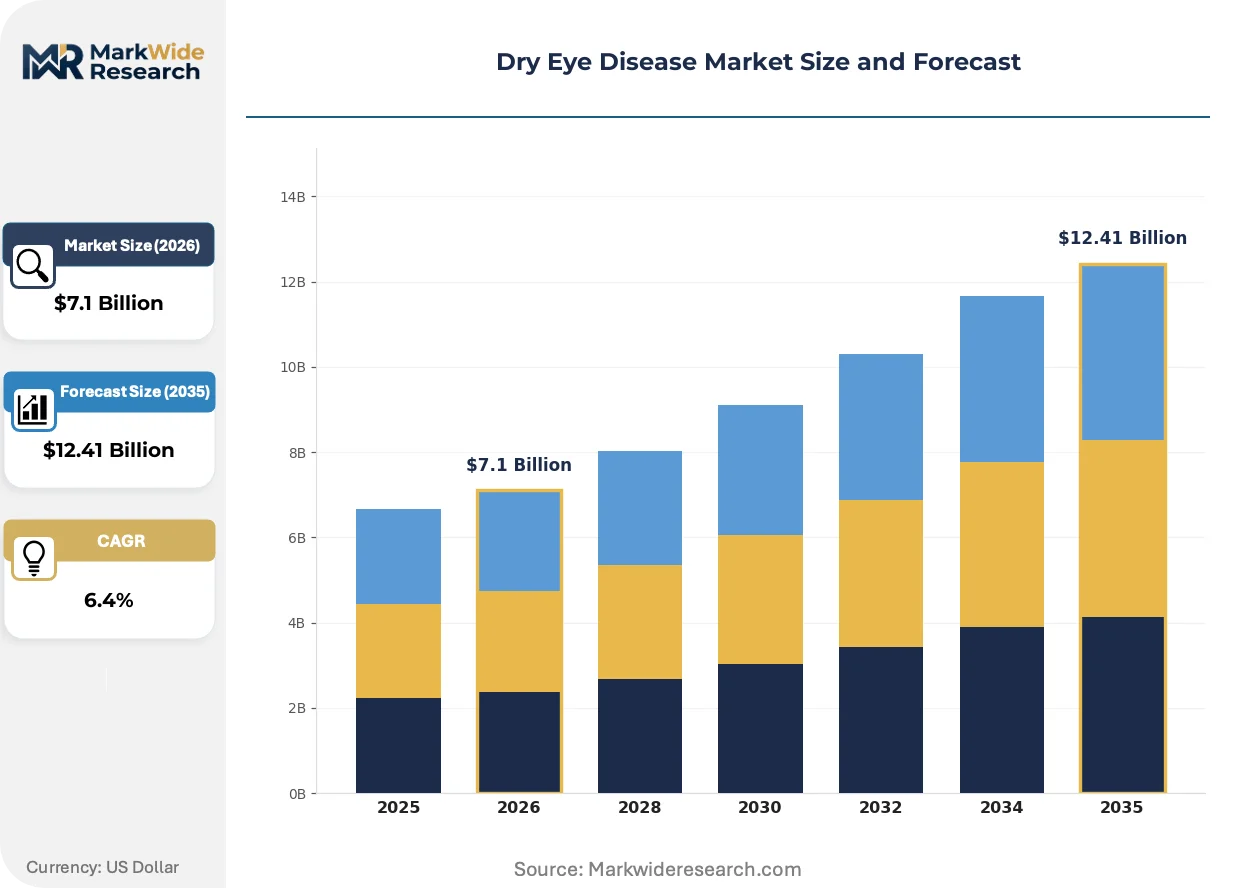
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $12.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-inflammatory Drugs, Punctal Plugs, Nutritional Supplements, Lipid-Based Formulations Therapy Area: Evaporative Dry Eye, Aqueous Deficient Dry Eye, Mixed Dry Eye, Meibomian Gland Dysfunction, Cicatricial Conjunctivitis End User: Eye Care Clinics, Specialized Ophthalmology Centers, Optical Retailers, Ambulatory Surgical Centers Delivery Mode: Topical Drops, Eyelid Cleansers, Ocular Inserts, Oral Supplements, Therapeutic Devices |
| Companies Covered | Santen Pharmaceutical Co., Ltd., Johnson & Johnson Vision, AbbVie Inc., Ocular Therapeutix, Inc., Sun Pharmaceutical Industries Ltd., Novartis AG, Bausch + Lomb Corporation, Otsuka Pharmaceutical Co., Ltd., Alcon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Eye Disease Market Strategic Shifts & Innovations
The market's evolution is defined by a significant shift away from merely managing symptoms with artificial tears toward disease-modifying interventions. This pivot is driven by deeper biological understanding and enables the development of therapies targeting specific etiologies like inflammation or glandular dysfunction.
Intranasal neurostimulation devices provide a non-pharmacological method for activating the trigeminal parasympathetic pathway to increase natural tear production. Specialized ophthalmology centers and patients seeking alternatives to eye drops are the primary adopters of this technology. This device-based approach is absorbing a patient segment previously reliant on prescription drops, establishing a distinct therapeutic category that bridges the gap between drugs and surgical interventions.
The FDA's guidance on clinical trial design for dry eye therapies increasingly emphasizes the co-primary endpoints of both an objective sign and a subjective symptom. This dual requirement elevates the burden of proof for new drug candidates, compelling sponsors to invest in more complex study designs. This regulatory standard most affects developers of novel-mechanism drugs, who must demonstrate superiority or differentiation beyond the established benchmarks of existing treatments.
Subscription-based delivery models are altering how patients access and adhere to chronic dry eye treatments. This approach often bypasses traditional pharmacy refill cycles for certain therapies, establishing a direct channel between manufacturers and end-users that enhances adherence. This trend is most prominent in the United States, where established direct-to-patient marketing and mail-order infrastructure facilitate the growth of such programs.
Dry Eye Disease Market Segmentation
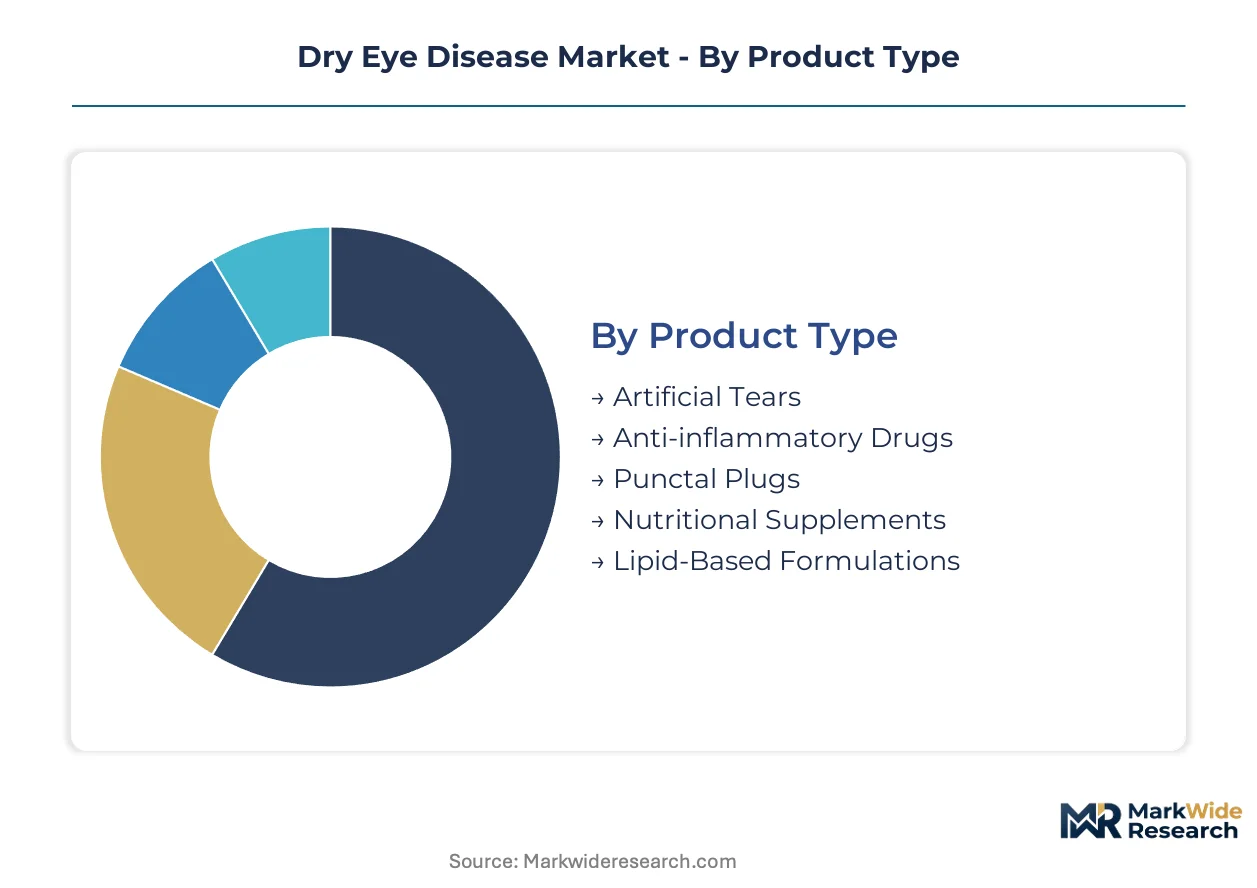
The Dry Eye Disease Market segmentation delineates distinct pathways for diagnosis, treatment, and patient care, reflecting the multifactorial nature of the condition. Understanding these segments is crucial for manufacturers to target product development and for healthcare providers to tailor therapeutic strategies effectively. Each category reveals specific trends in patient needs and clinical practice.
Product Type:
Patient preference and clinical necessity often dictate the selection of dry eye product types.
- Artificial Tears:These over-the-counter solutions provide symptomatic relief and lubrication for mild-to-moderate dry eye, acting as a first-line palliative option for many patients.
- Anti-inflammatory Drugs:Prescription medications like cyclosporine and lifitegrast target the underlying inflammation contributing to dry eye disease. Demand concentrates in the United States where favorable reimbursement exists for chronic conditions.
- Punctal Plugs:Small, biocompatible devices are inserted into tear ducts to block drainage, thereby retaining natural tears on the ocular surface for an extended period.
- Nutritional Supplements:Oral supplements, particularly those rich in omega-3 fatty acids, support tear film health and reduce systemic inflammation from within the body.
- Lipid-Based Formulations:These advanced emulsions and non-aqueous solutions aim to restore the tear film's lipid layer, primarily addressing evaporative dry eye and Meibomian Gland Dysfunction. Pipeline development across Europe focuses on these novel mechanisms.
Anti-inflammatory Drugs lead on scale; Lipid-Based Formulations lead on momentum.
Therapy Area:
The specific pathology of dry eye disease guides therapeutic application and pipeline investment.
- Evaporative Dry Eye:This common form results from rapid tear evaporation, often due to Meibomian Gland Dysfunction, and is a primary focus for industry pipeline development. Treatments aim to stabilize the tear film and reduce surface evaporation.
- Aqueous Deficient Dry Eye:This condition involves insufficient tear production by the lacrimal glands, requiring therapies that stimulate natural tear secretion or supplement tear volume.
- Mixed Dry Eye:Patients often present with both evaporative and aqueous deficient components, necessitating a comprehensive and often multi-modal treatment approach for optimal outcomes.
- Meibomian Gland Dysfunction:Characterized by blockages or abnormalities in the meibomian glands, this condition is a major cause of evaporative dry eye and drives demand for targeted lipid-based therapies. Clinical pivots now emphasize treating this underlying pathophysiology.
- Cicatricial Conjunctivitis:A severe and less common form of dry eye, this condition involves scarring of the conjunctiva, often requiring specialized and aggressive therapeutic interventions.
Therapies for Evaporative Dry Eye command significant R&D investment, while Meibomian Gland Dysfunction addresses a broad patient base.
End User:
The patient's point of access and the complexity of required care influence the choice of end-user segment.
- Eye Care Clinics:General ophthalmology and optometry practices serve as primary diagnostic and treatment points, prescribing a broad range of products from artificial tears to initial anti-inflammatory regimens. These clinics form the backbone of patient intake.
- Specialized Ophthalmology Centers:These dedicated facilities adopt advanced diagnostics and offer higher-margin, long-term therapies requiring consistent clinical monitoring for chronic dry eye conditions. Countries like Germany are expanding these specialized models.
- Optical Retailers:These outlets primarily provide over-the-counter artificial tears and lubricating gels, serving patients with milder symptoms or those seeking initial palliative relief.
- Ambulatory Surgical Centers:These centers focus on surgical interventions for severe dry eye cases or related ocular conditions, though their direct role in chronic dry eye management is more limited.
The shift towards specialized care models is evident, with Specialized Ophthalmology Centers driving adoption of advanced treatments.
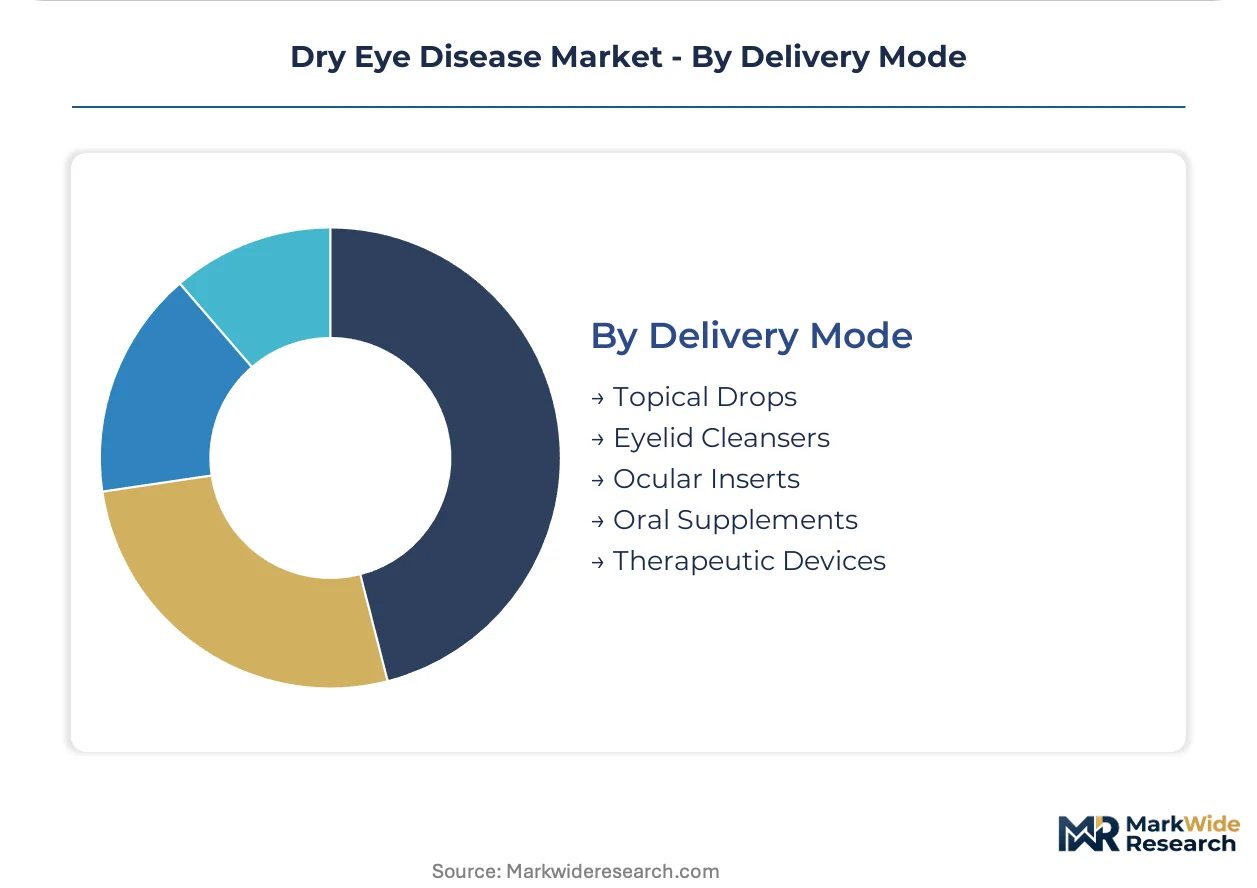
Delivery Mode:
Patient comfort, adherence, and the specific mechanism of action determine the preferred delivery mode for dry eye treatments.
- Topical Drops:This traditional and widely accepted delivery method includes artificial tears, anti-inflammatory drops, and cyclosporine formulations applied directly to the ocular surface. They remain the most common first-line treatment.
- Eyelid Cleansers:Products designed to clean the eyelids and eyelashes are crucial for managing blepharitis and Meibomian Gland Dysfunction, often used as an adjunctive therapy.
- Ocular Inserts:Small, dissolvable inserts placed in the eye slowly release medication over time, aiming to improve adherence and sustained drug delivery.
- Oral Supplements:Systemic treatments, such as omega-3 fatty acids, are taken orally to reduce inflammation and support overall ocular surface health.
- Therapeutic Devices:This category encompasses innovative non-pharmacological approaches like intranasal neurostimulation devices or thermal pulsation systems for Meibomian Gland Dysfunction. These devices offer alternatives for patients seeking non-drug options.
While Topical Drops remain foundational, innovation in Therapeutic Devices offers new avenues for patient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's advanced healthcare infrastructure and aging population drive significant demand for dry eye disease treatments, while the United States focuses on novel drug development and market access. These distinct market dynamics shape regional investment priorities and regulatory engagement. Each geography presents unique opportunities for therapeutic innovation.
United States
Demand for high-margin anti-inflammatory drugs like cyclosporine and lifitegrast is robust in the United States. The FDA's rigorous clinical trial requirements for dry eye therapies emphasize co-primary endpoints of signs and symptoms. Major pharmaceutical companies headquartered in the Northeast Corridor, such as in New Jersey, continue to invest heavily in ocular disease R&D.
Japan
Japan exhibits a high prevalence of chronic dry eye due to its rapidly aging demographics and extensive screen time. The PMDA has established specific regulatory pathways for regenerative medicine targeting ocular surface diseases. Pharmaceutical clusters in the Kanto region, including Tokyo, are actively pursuing advanced therapy products for this condition.
Germany
An aging population and expanding specialized ophthalmology centers contribute to consistent demand for advanced dry eye treatments in Germany. The EMA's regulatory framework for medical devices and pharmaceuticals influences product availability across the European Union. Munich's biotech sector shows interest in lipid-based formulations and non-aqueous solutions.
China
China's large population and increasing digital device usage are expanding its patient base for dry eye disease. The NMPA is streamlining approval processes for innovative ophthalmic drugs, creating market entry opportunities. Major cities like Shanghai are developing robust healthcare infrastructure to support specialized eye care clinics.
India
Rising awareness and improving diagnostic capabilities are boosting demand for dry eye therapies in India's urban centers. The CDSCO regulates pharmaceutical products, ensuring quality and safety standards for ophthalmic formulations. Hyderabad, a prominent pharmaceutical hub, sees growing R&D activity in affordable dry eye solutions.
Dry Eye Disease Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the dry eye disease market. The market exhibits a tiered structure, with established pharmaceutical giants dominating high-margin prescription therapies and smaller innovators focusing on niche technologies. Strategic archetypes include integrated pharmaceutical developers, specialized device manufacturers, and vision care solution providers. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Within the integrated pharmaceutical developer archetype, AbbVie Inc. and Novartis AG occupy significant positions, leveraging extensive R&D capabilities for novel anti-inflammatory compounds. Alcon Inc., a Swiss-American company, represents a leading player in the surgical and vision care space with comprehensive device offerings. These companies continue to shape therapeutic options across the global dry eye market.
| Leading Market Players |
|---|
| Santen Pharmaceutical Co., Ltd. |
| Johnson & Johnson Vision |
| AbbVie Inc. |
| Ocular Therapeutix, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Bausch + Lomb Corporation |
| Otsuka Pharmaceutical Co., Ltd. |
| Alcon Inc. |
| Others |
Cost & Logistics Intelligence
Specialized ophthalmologists in the United States command higher labor costs, influencing the premium pricing of advanced diagnostic services and high-margin prescription therapies, contrasting with lower-cost palliative options.
Pricing Analysis
Capacity additions in China's pharmaceutical sector are reshaping price floors for generic active pharmaceutical ingredients. Subscription models for chronic therapies decouple product sales from one-time prescriptions, creating recurring revenue streams. Price differentiation stems from regulatory approval status by the FDA or EMA, brand premium for novel mechanisms, and comprehensive after-sales support for therapeutic devices. Pricing pressure stems from payer resistance to high-cost prescription drugs, particularly in markets without favorable reimbursement policies. Patients seeking basic palliative relief are most price-sensitive, while those with severe chronic conditions requiring specialized care exhibit lower price sensitivity.
Supply Chain Analysis
Strict regulatory qualification by the PMDA or FDA gates market entry for advanced therapy products and novel drug candidates. Geographic supply for advanced R&D and manufacturing concentrates in the United States, Japan, and Germany. The industry draws from active pharmaceutical ingredients for anti-inflammatory compounds and specialized lipids for advanced formulations. Single-source vulnerability for key components in therapeutic devices represents a structural risk. Distribution runs through established pharmaceutical channels for prescription drugs and optical retailers for over-the-counter solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry eye disease market presents a geographic-arbitrage play, with Japan's specific PMDA regulatory pathways for regenerative medicine offering a distinct advantage over the more complex multi-market approvals required in Europe.
For Market Incumbents: Deepen pipeline diversification into novel lipid-based formulations and anti-inflammatory compounds to counter the threat of OTC substitution. Invest in lifecycle management for existing blockbuster drugs, ensuring sustained efficacy and patient adherence through digital health integration. Control distribution channels by expanding specialized ophthalmology centers, thereby mitigating reimbursement hurdles for high-margin therapies. For New Entrants and Emerging Players: Japan's PMDA regulatory pathways for advanced therapy products open a window for specialized regenerative medicine developers. Target the underpenetrated emerging markets with basic diagnostic infrastructure and affordable solutions for mild-to-moderate dry eye. A direct-to-patient subscription model for treatment adherence offers a viable go-to-market angle. For Investors and Strategic Acquirers: Integrated pharmaceutical developers are the most active acquirers in this space, seeking to expand their ocular care portfolios for sustained demand. Long-term viability is anchored in aging demographics and increasing digital device usage over the coming decade. Focus on specialized device manufacturers or companies developing novel mechanisms of action for Meibomian Gland Dysfunction. A signal to watch is the successful demonstration of objective biomarker correlation with subjective symptom improvement in late-stage clinical trials.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel anti-inflammatory compounds in the United States. |
| Regulatory Approval Pathway | Streamlines product launches for advanced therapy products within Japan. |
| Product Launch | Introduces non-pharmacological intranasal neurostimulation devices to a broader patient base. |
| Strategic Partnership | Leverages established pharmaceutical channels for wider distribution of specialized treatments. |
| Pipeline Diversification | Mitigates risk by addressing multiple dry eye etiologies, including Meibomian Gland Dysfunction. |
Research Approach
Bottom-up patient population modeling reconciled against top-down pharmaceutical sales tracking forms the analytical core for this study. Primary interviews with specialized ophthalmologists, pharmaceutical R&D leads, regulatory affairs specialists, and patient advocacy groups provided qualitative insights. Secondary validation drew from FDA filings, EMA submissions, PMDA guidelines, and academic literature.
Historical trendline analysis of market growth and technological adoption informed the quantitative framework. The analytical framework projects market expansion across the analysis window, segmenting by product type, therapy area, end user, delivery mode, and regional regulatory cluster. Compound annual growth rates were derived through regression analysis and validated by expert consensus. Key forecast inputs include demographic shifts, screen time prevalence, and R&D pipeline progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or major clinical trial failures. These forecasts reflect assumptions regarding market access and reimbursement policy. A model refresh is warranted upon material change in treatment guideline evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market