
 Global Apoptosis Assays Market | 2026-2036
Global Apoptosis Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Apoptosis Assays Market Foresight
Specialty reagent distribution is fragmenting as direct-to-lab digital procurement erodes traditional distributor margins. Becton, Dickinson and Company leverages its flow cytometry installed base to bundle apoptosis assay consumables. Thermo Fisher Scientific, Inc. anchors North American supply through its Gibco cell culture cross-sell architecture. Bio-Rad Laboratories, Inc. competes on qPCR-adjacent workflow integration for caspase detection protocols.
Apoptosis assays quantify programmed cell death through biomarker detection, typically measuring caspase enzymatic activity, phosphatidylserine externalization, or DNA fragmentation endpoints with sensitivity thresholds reaching picogram-level analyte concentrations. These tools enable go/no-go decisions in oncology drug candidate toxicity profiling and mechanism-of-action studies. Caspase activity and flow cytometry assay types command premium pricing due to their adoption in late-stage discovery workflows. Fluorescence and luminescence detection technologies dominate instrument placement in high-throughput screening facilities, while colorimetric formats retain share in academic settings with constrained capital budgets.
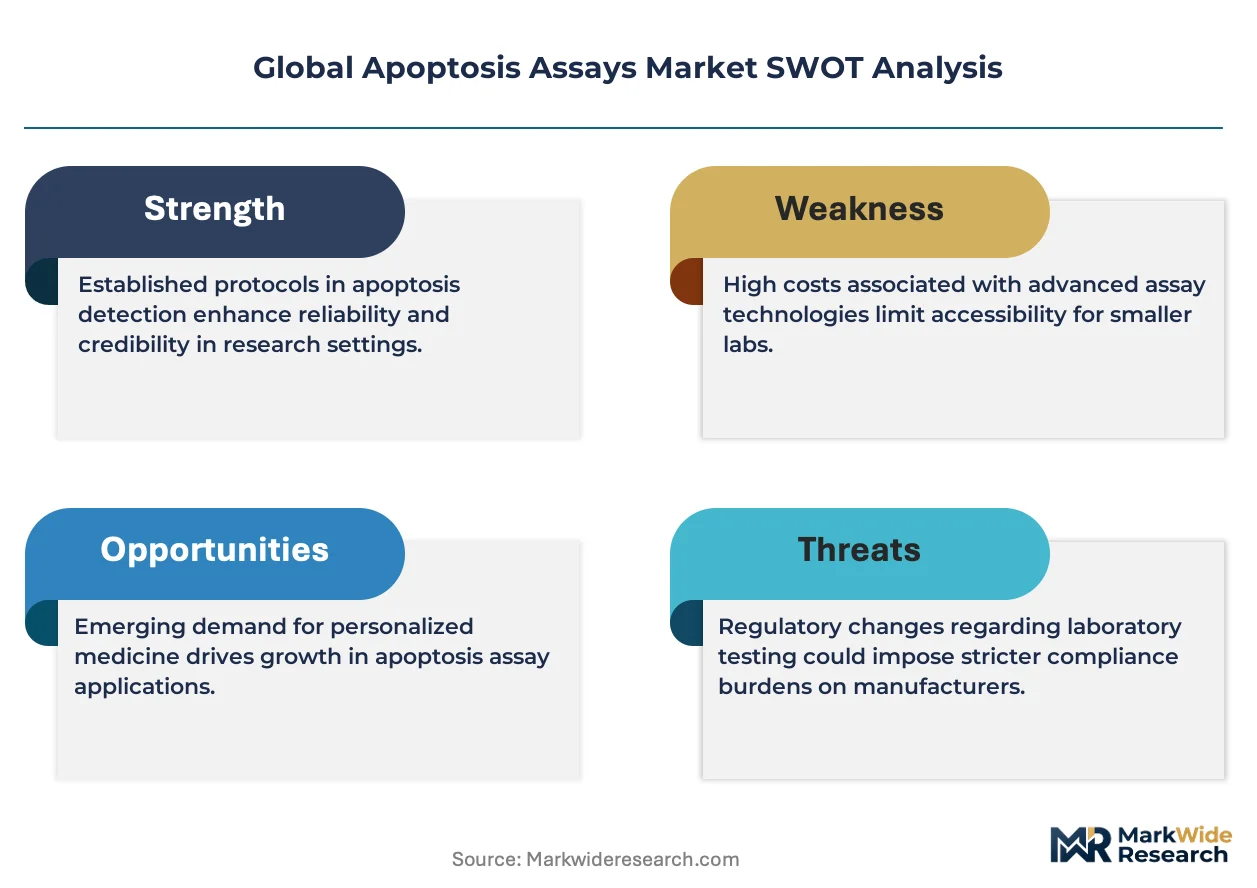
FDA guidance on in vitro diagnostic analytical validation shapes assay performance claims for clinical laboratory end users. EMA's ICH Q2(R1) implementation and REACH chemical substance registration requirements influence reagent composition disclosures and European market access conditions. China's NMPA innovation channel for companion diagnostics creates regulatory tailwinds for apoptosis biomarker assay developers. Stakeholders must monitor evolving pharmacogenomic labeling requirements that could reposition apoptosis assays from research tools to regulated diagnostic inputs.
Market Dynamics
Automated high-content imaging platforms are compressing manual protocol timelines from days to hours, forcing assay vendors to bundle software analytics with consumable contracts or lose placement in pharmaceutical screening facilities.
Growth Catalysts
- Oncology pipeline expansion:Pharmaceutical companies advancing immuno-oncology candidates require standardized apoptosis readouts for toxicity profiling, creating recurring reagent procurement volumes.
- NMPA innovation channel:China's streamlined companion diagnostic pathway accelerates regulatory clearance for apoptosis biomarker assays, opening clinical laboratory adoption.
- Flow cytometry platform density:Existing installed bases in translational research centers lower switching costs for assay consumable suppliers.
Market Restraints
- Antibody raw material concentration:Specialty reagent supply concentrates among limited contract manufacturing organizations, exposing assay producers to batch variability risk.
- ICH Q2(R1) validation burden:EMA implementation of analytical validation guidelines extends development timelines for European market entry.
- Luminescence detection capex thresholds:High-throughput screening facilities require six-figure instrument investments that constrain academic budget accessibility.
Strategic Opportunities
- Point-of-care translation:Miniaturized caspase detection formats could penetrate decentralized oncology monitoring in Germany's ambulatory care network.
- AI-assisted image analysis:Machine learning integration with high-content platforms enables morphometric apoptosis scoring without expert pathologist review.
- Direct-to-lab digital procurement:Manufacturer-hosted e-commerce portals bypass distributor markups and capture demand signals from principal investigators.
Industry Challenges
- Multiplex assay standardization:Absence of universal reference materials for simultaneous caspase-DNA fragmentation panels complicates cross-study comparability.
- Legacy LIMS integration:Automated imaging platforms require custom API development to connect with institutional data management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Apoptosis Assays Market |
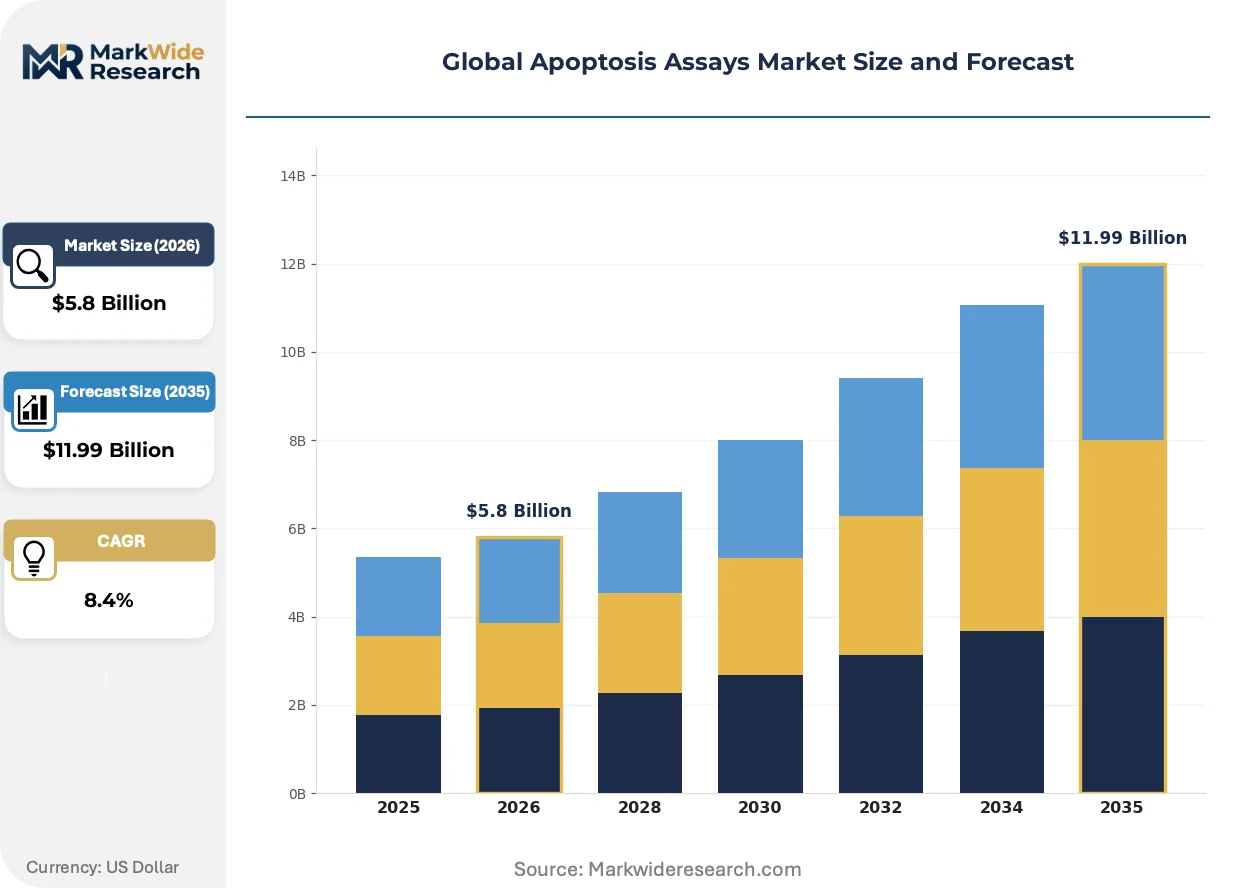
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assay Type: Flow Cytometry, ELISA, Western Blotting, Immunohistochemistry, TUNEL, Caspase Activity Technology: Fluorescence, Luminescence, Colorimetric, Chemiluminescence, Microscopy, MicroplateReader Application: Cancer Research, Drug Discovery, Neurodegeneration Studies, Toxicology Screening, Immunology, Cell Biology End User: Pharmaceutical Companies, Academic Institutes, Biotechnology Firms, Contract Research Organizations, Clinical Laboratories, Government Agencies |
| Companies Covered | Becton, Dickinson and Company, Sartorius AG, Thermo Fisher Scientific, Inc., Bio-Techne Corporation, Abcam plc, Merck KGaA, Promega Corporation, Danaher Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Apoptosis Assays Market Shifts & Advancements
Workflow integration and detection sensitivity thresholds are reshaping competitive positioning, with vendors racing to compress assay turnaround times while expanding multiplexing capabilities beyond traditional single-parameter readouts.
High-content imaging systems with integrated machine learning classification are digitizing apoptosis morphology scoring that previously required manual microscopy review. Contract research organizations running large oncology screens have adopted these platforms at replacement cycle rates of 18-24 months. The technology is digitizing pathologist labor out of routine screening decisions, compressing per-sample analysis costs and enabling overnight batch processing.
REACH chemical substance registration requirements are forcing reagent composition disclosures that expose proprietary formulation elements. European assay suppliers now face competitive intelligence vulnerability as competitors reverse-engineer buffer compositions from safety data sheets. The regulation most impacts specialty phosphatidylserine detection reagents, where suppliers are responding by developing non-hazardous substitute chemistries.
Research principal investigators increasingly specify detection technology by grant funder requirements rather than laboratory preference. National Institutes of Health data sharing mandates favor luminescence formats with standardized output files, displacing fluorescence protocols in United States academic procurement. This specification cascade is most visible in National Cancer Institute-funded consortia where cross-site comparability trumps local optimization.
Global Apoptosis Assays Market Segmentation
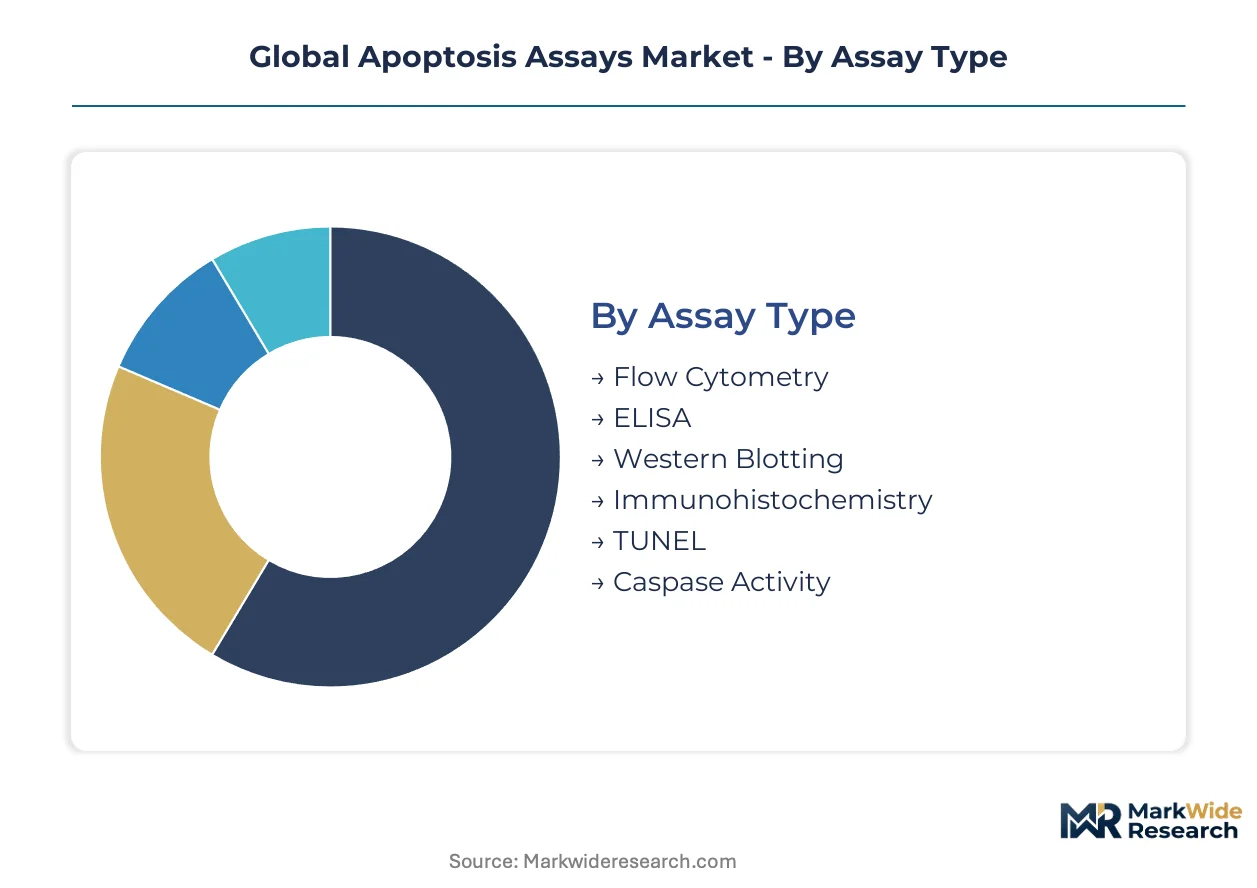
Apoptosis assay procurement patterns diverge sharply by workflow complexity and detection sensitivity requirements. Pharmaceutical screening facilities prioritize throughput and automation compatibility, while academic laboratories optimize for capital efficiency and protocol flexibility.
Assay Type:
Cost tier stratification separates premium-positioned multiplex formats from entry-level single-parameter kits.
- Caspase Activity:Enzymatic detection of initiator and executioner caspases delivers picogram-level sensitivity for mechanism-of-action studies. United States-based immuno-oncology programs drive recurring reagent procurement volumes for this format.
- Flow Cytometry:Multi-parameter phosphatidylserine externalization assays integrate with existing BD Biosciences and Beckman Coulter instrument bases. Germany's translational research centers represent concentrated demand for Annexin V protocols.
- ELISA:Plate-based quantification of soluble apoptosis markers serves toxicology screening with moderate throughput requirements.
- Western Blotting:Protein-level detection of cleaved caspase substrates retains share in hypothesis-driven academic research.
- Immunohistochemistry:Tissue-section morphology scoring supports clinical pathology applications with pathologist review requirements.
- TUNEL:Terminal transferase-mediated DNA fragmentation labeling provides late-apoptotic endpoint detection for fixed samples.
Caspase Activity commands the established base. The steepest expansion runs through Flow Cytometry.
Technology:
Application requirements determine detection modality selection, with grant funder mandates increasingly overriding laboratory preference.
- Luminescence:ATP-coupled caspase substrates enable homogeneous detection without wash steps. National Institutes of Health data sharing mandates favor standardized luminescence output formats in United States academic consortia.
- Fluorescence:Multi-wavelength excitation supports multiplexed apoptosis-necrosis discrimination. China's expanding oncology research infrastructure drives instrument placement for FITC-Annexin V protocols.
- Colorimetric:Visible-spectrum absorbance detection operates without dedicated luminometers, preserving accessibility for budget-constrained settings.
- Chemiluminescence:Enhanced sensitivity for low-abundance analytes supports high-content imaging integration.
- Microscopy:Morphometric scoring of apoptotic bodies requires expert pathologist review or AI-assisted classification.
- Microplate Reader:Standardized 96- and 384-well formats enable high-throughput screening automation in pharmaceutical facilities.
Fluorescence retains the installed base. Luminescence is climbing the fastest on regulatory specification tailwinds.
Application:
Customer type concentration varies by therapeutic area maturity and funding availability.
- Cancer Research:Immuno-oncology pipeline expansion generates standardized apoptosis readout requirements for combination therapy toxicity profiling. Contract research organizations in the United States run large-scale screens with 18-24 month platform replacement cycles.
- Drug Discovery:Lead optimization stages require go/no-go cytotoxicity data with cross-site comparability. Germany's pharmaceutical cluster demands validated assay kits with batch-to-batch consistency documentation.
- Neurodegeneration Studies:Neuronal apoptosis models for Alzheimer's and Parkinson's disease research utilize specialized primary cell protocols.
- Toxicology Screening:Regulatory submission packages require OECD-compliant in vitro test methods with defined sensitivity thresholds.
- Immunology:T-cell apoptosis assays support checkpoint inhibitor mechanism studies.
- Cell Biology:Fundamental research applications span diverse model organisms with variable reagent standardization.
Cancer Research holds the revenue concentration. Drug Discovery is gaining share fastest on pharmaceutical outsourcing trends.
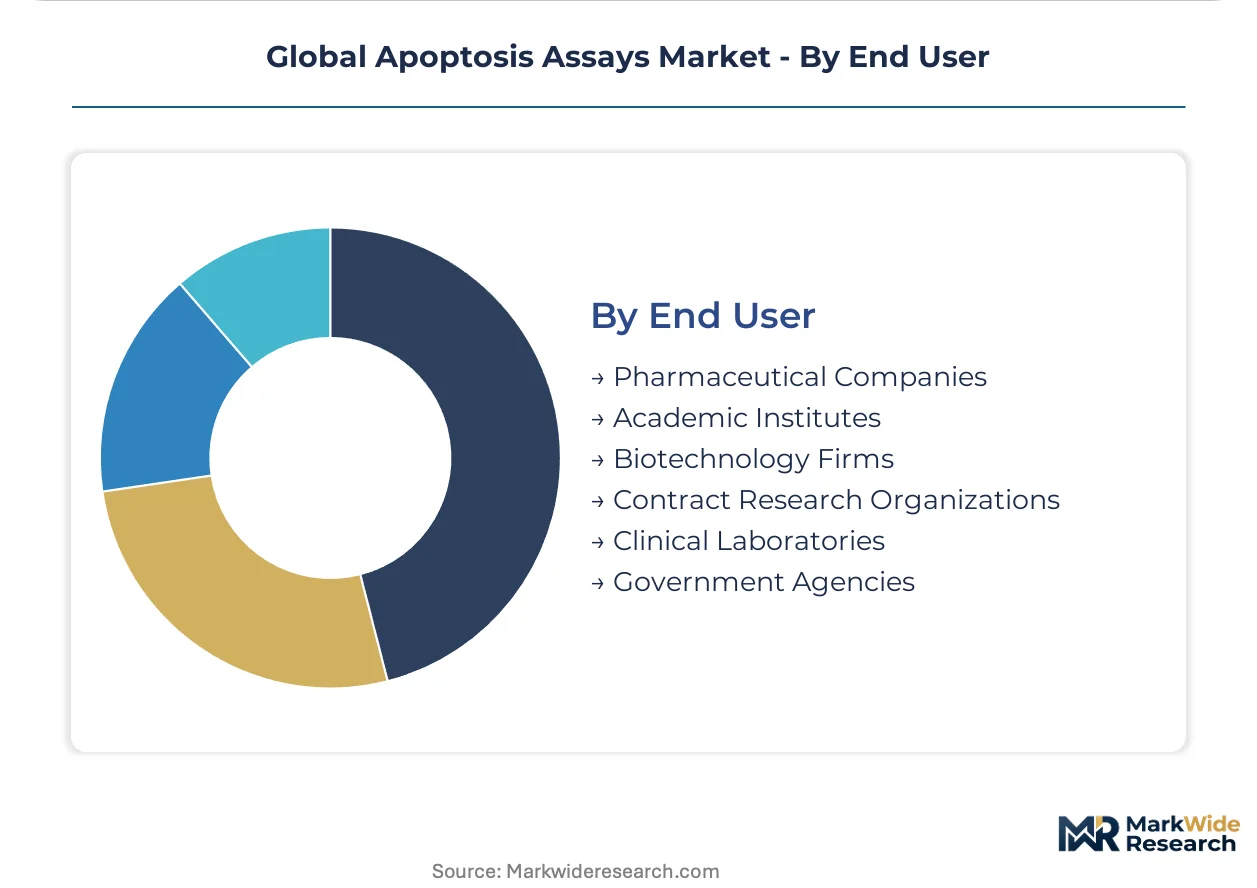
End User:
Procurement authority and volume scale separate enterprise-level reagent contracts from principal investigator-driven purchases.
- Pharmaceutical Companies:Centralized procurement functions negotiate multi-year consumable agreements tied to high-content imaging platform placements. United States headquarters locations coordinate global assay standardization.
- Contract Research Organizations:Competitive bidding for large oncology screens drives assay kit cost-per-sample optimization. China's domestic CRO sector expands capacity with NMPA-aligned validation protocols.
- Academic Institutes:Grant-funded laboratories prioritize capital-efficient colorimetric formats with publication-grade sensitivity.
- Biotechnology Firms:Venture-backed companies balance speed-to-data against reagent cost constraints in early development.
- Clinical Laboratories:FDA and EMA diagnostic validation requirements limit adoption to regulated assay formats with analytical performance claims.
- Government Agencies:National laboratory networks fund reference material development and inter-laboratory comparison studies.
Pharmaceutical Companies anchor procurement volume. Contract Research Organizations show the steepest expansion trajectory on outsourcing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assay vendors command pricing premiums in the United States that exceed German rates by 15-20 percent, reflecting concentrated pharmaceutical procurement power and NIH funding density. China's NMPA pathway compresses regulatory timelines but demands localized validation protocols that fragment pricing standardization.
United States
Immuno-oncology pipelines at Boston and San Francisco biotech clusters drive caspase activity kit volumes. FDA guidance on companion diagnostic analytical validation shapes performance claims for clinical laboratory end users. The National Cancer Institute's funded consortia in Bethesda standardize luminescence output formats across multi-site studies.
Germany
Translational research centers in Heidelberg and Munich concentrate demand for Annexin V flow cytometry protocols. EMA's ICH Q2(R1) implementation extends development timelines for assay market entry. The country's pharmaceutical cluster around Frankfurt demands validated kits with batch-to-batch consistency documentation.
China
Domestic CRO sector expansion in Shanghai and Suzhou accelerates NMPA-aligned validation protocol adoption. The innovation channel for companion diagnostics creates regulatory tailwinds for apoptosis biomarker assay developers. Beijing's national laboratory networks fund reference material development for inter-laboratory comparison studies.
Japan
PMDA's structured consultation pathways for in vitro diagnostics influence assay performance claim documentation. Tokyo and Osaka academic medical centers prioritize high-content imaging platform integration. METI funding for precision medicine infrastructure supports automated screening facility upgrades.
United Kingdom
London's contract research organizations compete for large oncology screens with cost-per-sample optimization pressures. MHRA post-Brexit regulatory divergence from EMA creates dual validation requirements for European market access. The Cambridge life sciences cluster drives demand for multiplex assay standardization.
Global Apoptosis Assays Market Competitive Landscape
Platform-integrated suppliers and specialty reagent developers split the market into distinct capability tiers. Consolidation pressures concentrate around flow cytometry installed bases and cross-sell architectures. Three archetypes dominate: diversified life sciences conglomerates with consumable bundling power; mid-scale reagent specialists with workflow-specific positioning; and emerging digital-native distributors bypassing traditional channels. Competitive moves center on software analytics bundling and direct-to-lab e-commerce portal deployment.
Among diversified conglomerates, Becton, Dickinson and Company and Thermo Fisher Scientific, Inc. exemplify platform-anchored bundling strategies. Bio-Rad Laboratories, Inc. occupies a position within the workflow-integrated specialist tier. These three entities represent contrasting approaches to capturing recurring reagent procurement volumes through instrument base density versus protocol-specific integration.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Sartorius AG |
| Thermo Fisher Scientific, Inc. |
| Bio-Techne Corporation |
| Abcam plc |
| Merck KGaA |
| Promega Corporation |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply & Pricing Matrix
Antibody raw material concentration among contract manufacturing organizations in China and the United States funnels margin capture toward specialty reagent formulators with captive buffer chemistry expertise. Assay vendors with backward integration into detection substrate production retain pricing power against distributors facing digital procurement disintermediation.
Pricing Analysis
Configured-to-order multiplex panel pricing commands 40-50 percent premiums over standard single-parameter caspase kits. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with FDA-analytical-grade tiers serving clinical laboratories and research-grade formats targeting academic budgets. Cost compression in economy-tier colorimetric formats is intensifying because direct-to-lab e-commerce portals eliminate distributor markups. Academic institutes exhibit the highest price sensitivity, while pharmaceutical screening facilities prioritize throughput over per-kit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize relationships between reagent vendors and contract research organizations in China, Germany, and the United States. Specialty phosphatidylserine detection chemistries draw from fluorophore suppliers concentrated in Japan and Germany, with Annexin V protein production anchored in Chinese fermentation facilities. Single-source vulnerability around high-purity caspase substrates creates exposure to batch variability events. Distribution runs through manufacturer-direct portals and specialty life sciences distributors serving principal investigators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical procurement functions negotiating multi-year consumable agreements, fragmenting pricing leverage for mid-scale reagent specialists without platform bundling power.
For Market Incumbents: Harden instrument base lock-in by bundling software analytics with high-content imaging consumable contracts. Deepen backward integration into detection substrate chemistry to secure margin pools threatened by REACH disclosure requirements. Prioritize API development for automated platform connectivity with institutional LIMS architectures. For New Entrants and Emerging Players: China's domestic CRO sector expansion represents the most penetrable white-space target, given NMPA-aligned validation protocol demand outpacing local supply capacity. Germany's ambulatory oncology monitoring network offers point-of-care caspase detection entry with miniaturized format innovation. Pursue direct-to-lab digital procurement channels bypassing established distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward workflow-integrated specialists with qPCR-adjacent positioning and cross-sell architecture potential. Long-term viability favors vendors capturing recurring reagent volumes through platform density rather than transactional kit sales. Monitor FDA pharmacogenomic labeling guidance expansion as the signal indicating apoptosis assay reclassification from research tool to regulated diagnostic input.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Image Analysis Integration | Machine learning classification reduces pathologist labor costs in CRO screening facilities. |
| Direct-to-Lab Digital Portal Deployment | Manufacturer-hosted e-commerce captures demand signals from NIH-funded principal investigators. |
| Non-Hazardous Reagent Chemistry Development | REACH-compliant substitutes protect proprietary formulations from competitive reverse-engineering. |
| Companion Diagnostic Validation Pathway | NMPA innovation channel clearance opens clinical laboratory adoption in China's domestic market. |
| Multiplex Assay Standardization Program | Universal reference materials enable cross-study comparability for caspase-DNA fragmentation panels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, high-content imaging platform engineers, and contract research organization procurement managers; and secondary validation against FDA 510(k) filings, EMA ICH Q2(R1) implementation guidance, NMPA companion diagnostic pathway documentation, and ClinicalTrials.gov apoptosis endpoint specifications. Bottom-up triangulation across assay kit vendor revenue disclosures and top-down pharmaceutical R&D spending allocation models converged on segment-level demand estimates.
Forecast inputs incorporated assay type segmentation by detection sensitivity threshold, technology modality by grant funder specification patterns, application tier by therapeutic area maturity, and end-user concentration by procurement authority. CAGRs were derived from pharmaceutical pipeline expansion trajectories and translational research funding disbursement trends across the analysis window. Instrument replacement cycle dynamics and regulatory validation timeline compression factored into regional adoption curve modeling.
Practitioners should monitor NMPA policy evolution, NIH data sharing mandate expansion, and REACH chemical disclosure requirement tightening for early signals of demand pattern shifts. Forecasts reflect assumptions around immuno-oncology pipeline continuity and automated platform displacement rates. Macroeconomic contraction in research funding, regulatory reclassification of apoptosis biomarkers, or breakthrough alternative cytotoxicity assay technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market