
 Cardiology Genomic Testing Market | 2026-2036
Cardiology Genomic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiology Genomic Testing Market Analytics
Hospital cardiology departments is bifurcating from research laboratories as the dominant procurement channel for inherited cardiovascular panels. Thermo Fisher Scientific leverages its integrated instrument-reagent workflow to sustain high-throughput sequencing operations in major health systems. Illumina anchors the upstream platform supply chain, while QIAGEN specializes in sample preparation automation that differentiates its position in clinical-grade nucleic acid processing.
Cardiology genomic testing applies DNA and RNA analysis methods to identify germline and somatic variants associated with heritable cardiovascular conditions, employing targeted gene panels of 30–200 cardiomyopathy-related loci and whole exome sequencing with mean read depths exceeding 100x to guide therapeutic decisions and family screening. Sequencing platforms occupy the largest value share due to reagent pull-through economics, while next-generation sequencing technology leads growth velocity as panel density expands and turnaround times compress below ten days. Microarray-based genotyping retains relevance in population-scale pharmacogenomic screening but yields narrower margins per test than comprehensive sequencing workflows.
The US FDA regulates these assays as in vitro diagnostics or laboratory-developed tests depending on commercial distribution model, while the EMA's in vitro diagnostic regulation in Europe mandates notified body certification for high-risk genetic tests by designated conformity assessment deadlines. ISO 15189 accreditation shapes laboratory quality frameworks that determine payer reimbursement eligibility across multiple jurisdictions. Stakeholders must monitor evolving evidentiary standards for clinical utility that determine coverage policies from Medicare and major private insurers.
Market Dynamics
The transition from single-gene Sanger sequencing to multiplexed next-generation sequencing panels is compressing per-test costs while expanding variant detection scope, fundamentally restructuring how hospital laboratories procure cardiovascular genetic diagnostics.
Growth Catalysts
- Breakthrough Device Designation:The US FDA's expedited premarket pathway accelerates commercialization timelines for inherited cardiomyopathy assays, reducing regulatory friction for novel panel submissions.
- Academic Medical Center Integration:Major teaching hospitals embed genomic cardiology into hypertrophic cardiomyopathy care protocols, creating institutional demand pull for comprehensive screening services.
- Family Cascade Screening Protocols:Cardiogenetic counseling programs identify at-risk relatives through proband-initiated testing, expanding addressable patient populations beyond index cases.
Market Restraints
- Platform Reagent Lock-In:Sequencing consumables tie laboratories to specific instrument ecosystems, creating switching costs that limit vendor diversification and compress negotiating leverage.
- Clinical Utility Evidence Gaps:Medicare and private payers demand prospective outcome data linking genetic findings to therapeutic decisions, delaying reimbursement coverage for expanded panels.
- Variant Interpretation Bottlenecks:Ambiguous pathogenicity classifications for rare variants necessitate expert review boards, constraining laboratory throughput and extending report turnaround times.
Strategic Opportunities
- Pharmacogenomic Expansion:Warfarin and clopidogrel response genotyping integration into anticoagulation clinics creates new reimbursement codes for preemptive cardiovascular pharmacogenetics.
- Direct-to-Consumer Channel Development:Telemedicine-enabled genetic counseling platforms bypass traditional hospital laboratory procurement, capturing patient-initiated screening demand.
- Polygenic Risk Score Commercialization:Genome-wide association data aggregation enables coronary artery disease risk stratification beyond monogenic conditions, opening population-scale screening applications.
Industry Challenges
- Bioinformatics Specialist Scarcity:Variant curation and clinical interpretation require dual-trained personnel fluent in both cardiac phenotyping and genomic annotation, creating recruitment bottlenecks.
- Laboratory Information System Integration:Genomic results require structured data exchange with electronic health records, forcing costly middleware development for health system interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiology Genomic Testing Market |
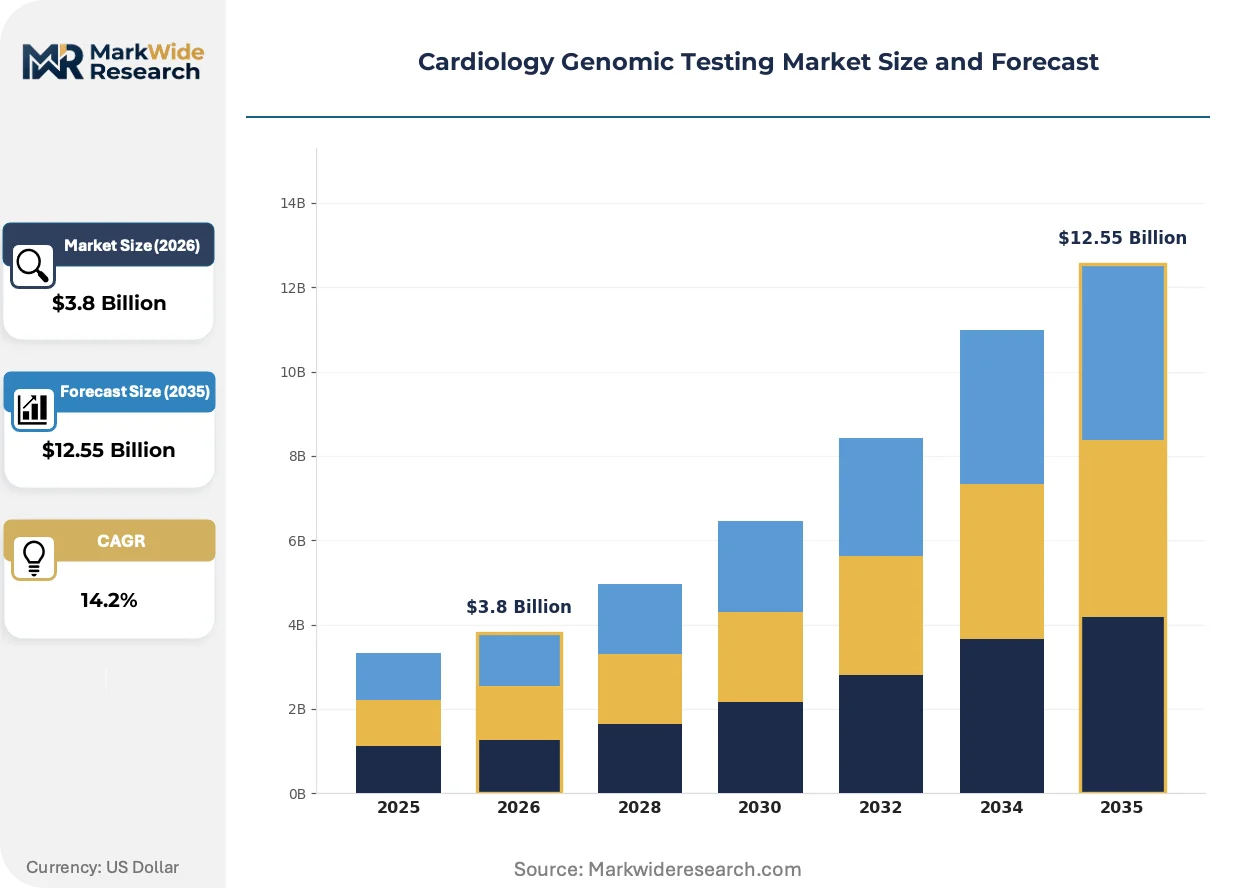
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
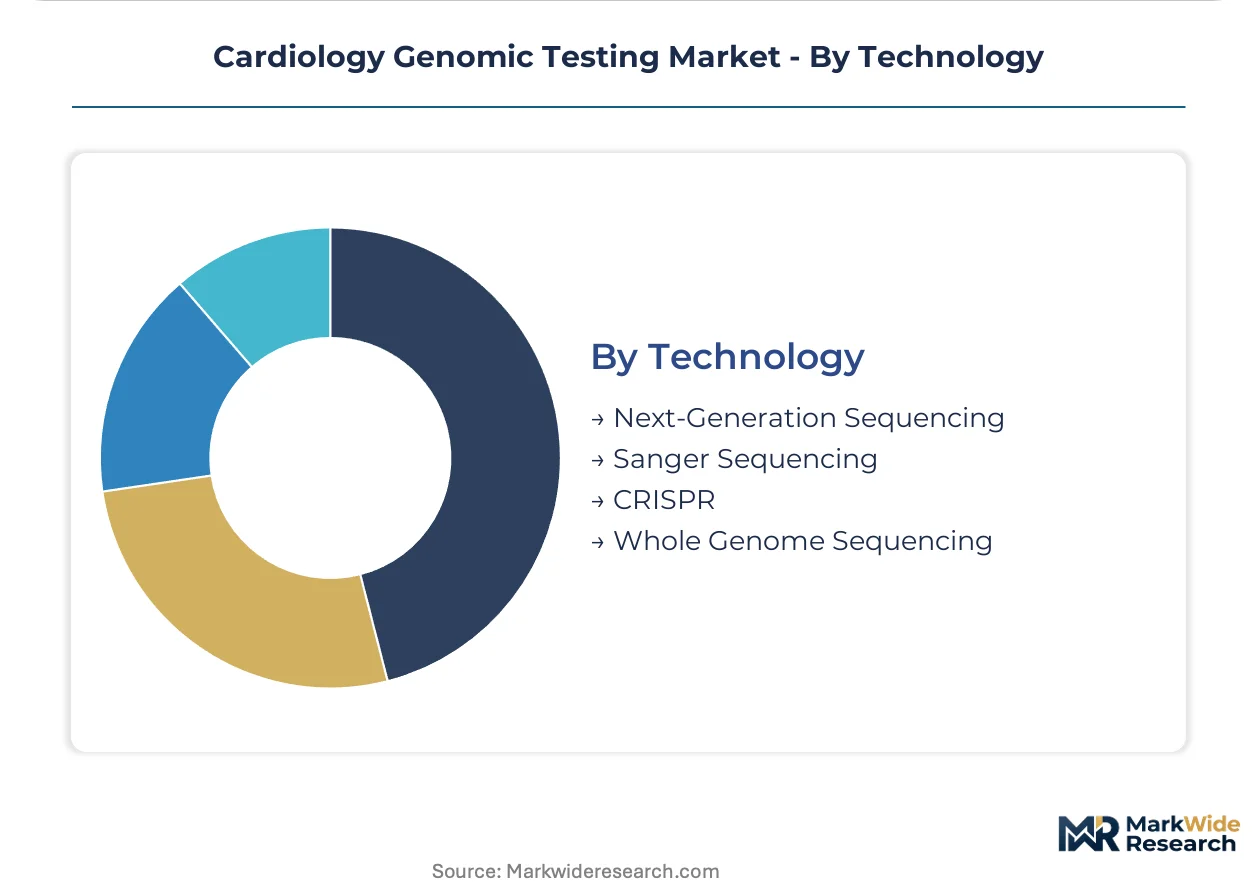
| Segmentation | Test Type: Sequencing, PCR, Microarray, Genotyping End User: Hospitals, Clinics, Research Labs, Diagnostic Centers Application: Cardiomyopathy, Aortic Disorders, Arrhythmias, Ischemic Heart Disease Technology: Next-Generation Sequencing, Sanger Sequencing, CRISPR, Whole Genome Sequencing |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., QIAGEN N.V., F. Hoffmann-La Roche Ltd., Laboratory Corporation of America Holdings, Quest Diagnostics Incorporated, Invitae Corporation, GeneDx Inc., Myriad Genetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiology Genomic Testing Market Evolving Landscape
Long-read sequencing platforms and artificial intelligence variant classification tools are converging to resolve complex structural variants and reduce interpretation burden, altering competitive requirements for clinical-grade cardiogenetic services.
Third-generation sequencing technology is decomposing the technical barriers that previously limited detection of large structural variants and repeat expansions in cardiomyopathy genes. Pediatric cardiology departments at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center pilot these platforms for unresolved cases with negative panel results. The technology is decomposing the distinction between targeted panel testing and whole-genome sequencing, forcing laboratories to reconsider tiered testing algorithms and pricing architectures.
The European Union's In Vitro Diagnostic Regulation mandates notified body certification for high-risk genetic tests by designated conformity assessment deadlines, imposing new quality management system requirements on laboratories. Commercial test developers must compile clinical evidence dossiers meeting Common Specifications for performance evaluation. Medium-sized European reference laboratories face capital-intensive compliance investments or market exit, consolidating supply toward multinational diagnostic manufacturers with established regulatory affairs infrastructure.
Hospital procurement committees now bundle genomic testing contracts with enterprise-wide bioinformatics infrastructure agreements, displacing transactional reagent purchasing. Integrated delivery networks negotiate multi-year sole-source arrangements covering sequencing platforms, variant interpretation software, and genetic counseling services. This consolidation is most visible in United States health systems exceeding five billion dollars in annual operating revenue, where supply chain rationalization overrides test-level cost minimization.
Cardiology Genomic Testing Market Segmentation
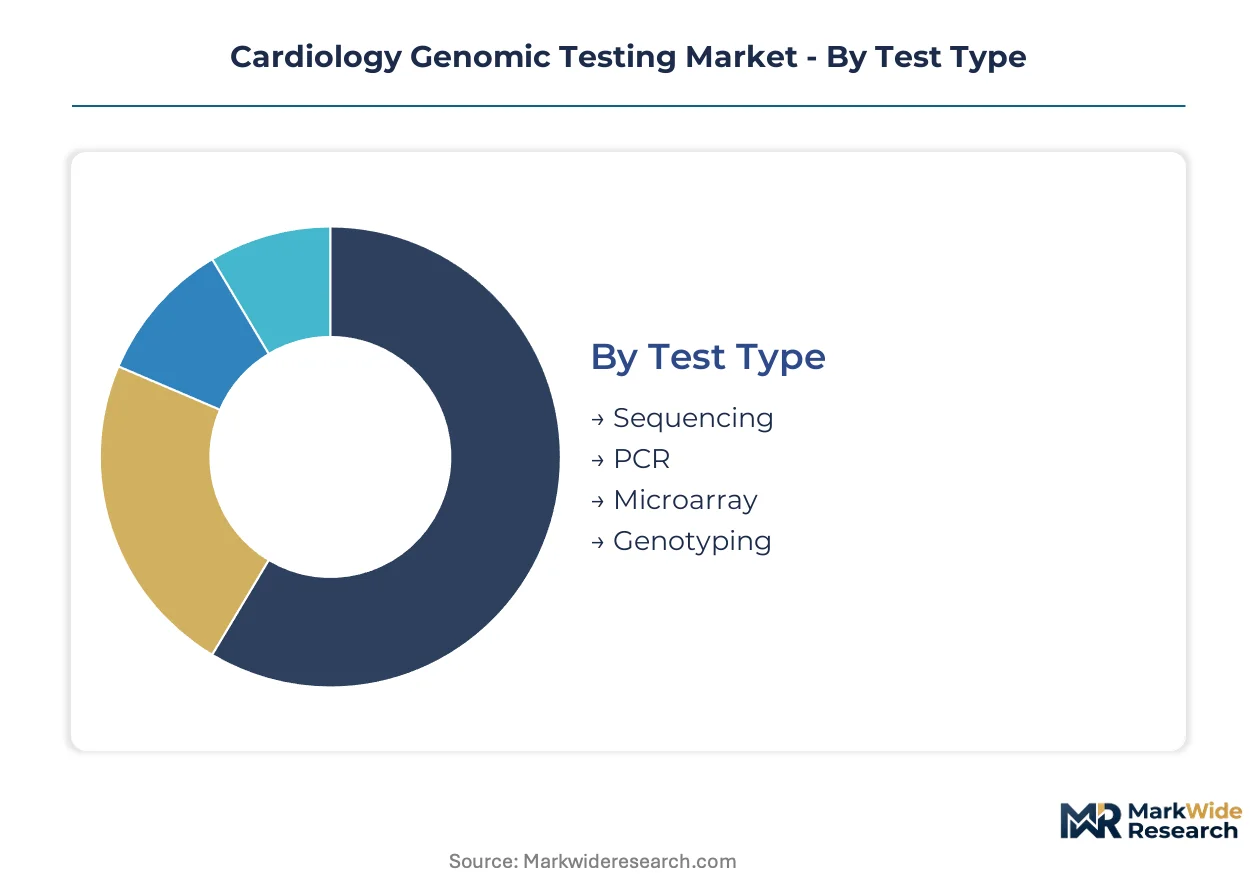
Segmentation in cardiology genomic testing reveals how procurement channels, clinical workflows, and technical capabilities intersect. Understanding these divisions helps stakeholders align platform investments with reimbursement pathways and patient access points.
Test Type:
Sequencing dominates domestic hospital procurement, while PCR and microarray retain stronger export orientation to price-sensitive health systems.
- Sequencing:Next-generation sequencing platforms generate mean read depths exceeding 100x across 30–200 cardiomyopathy-related loci. Academic medical centers in the United States concentrate demand for comprehensive panels that compress turnaround below ten days.
- PCR:Polymerase chain reaction assays deliver rapid, cost-effective detection of known pathogenic variants in single-gene disorders. Community hospitals and regional diagnostic centers prioritize PCR for hypertrophic cardiomyopathy hotspot screening where panel breadth is secondary to speed.
- Microarray:Array-based genotyping supports population-scale pharmacogenomic screening with standardized variant detection.
- Genotyping:Targeted SNP analysis enables warfarin and clopidogrel response prediction in anticoagulation clinics.
Sequencing holds the largest share; momentum sits with PCR as point-of-care protocols expand.
End User:
Procurement patterns diverge sharply between integrated health systems with captive laboratory infrastructure and independent reference laboratories serving dispersed clinical sites.
- Hospitals:Hospital-based cardiology departments now lead procurement volume for inherited cardiovascular panels, displacing research laboratories as the dominant channel. Major United States health systems exceeding five billion dollars in annual revenue negotiate multi-year sole-source agreements bundling platforms, software, and genetic counseling.
- Diagnostic Centers:Independent reference laboratories serve outpatient cardiology practices lacking in-house sequencing capacity. These facilities compete on turnaround time and payer contract breadth rather than panel customization.
- Clinics:Outpatient cardiology clinics increasingly rely on send-out arrangements or telemedicine-enabled genetic counseling platforms.
- Research Labs:Academic research laboratories focus on novel variant discovery and polygenic risk score development rather than clinical-grade diagnostic throughput.
Hospitals command the dominant revenue position; diagnostic centers are climbing fastest as independent practice consolidation accelerates.
Application:
Clinical utility evidence and established reimbursement codes concentrate investment in heritable cardiomyopathies, while arrhythmia testing faces steeper evidentiary hurdles.
- Cardiomyopathy:Hypertrophic and dilated cardiomyopathy panels represent the most mature reimbursement category, with Medicare and major private insurers covering proband testing and family cascade screening. The United States FDA's Breakthrough Device Designation pathway has accelerated multiple submissions in this category.
- Arrhythmias:Long QT syndrome and Brugada syndrome testing commands premium pricing but requires specialized electrophysiology interpretation. Academic medical centers embed these assays into sudden cardiac death prevention protocols.
- Aortic Disorders:Marfan syndrome and familial thoracic aortic aneurysm panels serve surgical planning and surveillance interval determination.
- Ischemic Heart Disease:Polygenic risk score applications for coronary artery disease remain investigational, with limited payer coverage pending prospective outcome data.
Cardiomyopathy holds the largest share; momentum sits with arrhythmia testing as electrophysiology-genetics integration deepens.
Technology:
Platform selection determines reagent lock-in economics and structural variant detection capabilities that differentiate laboratory service offerings.
- Next-Generation Sequencing:NGS platforms anchor the upstream supply chain, enabling multiplexed panel expansion and per-test cost compression. Illumina's instrument ecosystem dominates high-throughput operations in major health systems.
- Whole Genome Sequencing:WGS is decomposing the distinction between targeted panels and comprehensive genome analysis, forcing reconsideration of tiered testing algorithms. Boston Children's Hospital and Cincinnati Children's Hospital Medical Center pilot third-generation platforms for unresolved negative panel cases.
- Sanger Sequencing:Single-gene confirmation testing retains role in variant validation and small-scale assays.
- CRISPR:Gene editing technology supports research applications and potential therapeutic development rather than current diagnostic workflows.
Next-generation sequencing holds the largest share; whole genome sequencing is expanding most quickly as long-read platforms resolve complex structural variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sequencing instruments and reagent systems to United States academic medical centers, establishing the primary transatlantic trade corridor in cardiovascular genomic diagnostics.
United States
Academic medical centers in Boston and Cincinnati embed cardiogenetic screening into hypertrophic cardiomyopathy care protocols. The FDA's Breakthrough Device Designation pathway accelerates premarket review timelines for inherited condition assays. Major health systems exceeding five billion dollars in annual operating revenue negotiate multi-year sole-source agreements bundling platforms, software, and genetic counseling services.
Germany
Reference laboratories in Baden-Württemberg and Bavaria specialize in clinical-grade nucleic acid processing for export markets. The EMA's In Vitro Diagnostic Regulation mandates notified body certification for high-risk genetic tests, imposing quality management system requirements on domestic laboratories. Heidelberg and Munich anchor precision medicine clusters where university hospitals integrate genomic cardiology into standard care pathways.
United Kingdom
NHS England's Genomic Medicine Service embeds inherited cardiovascular condition testing into mainstream clinical practice. The Medicines and Healthcare products Regulatory Agency oversees conformity assessment for in vitro diagnostics entering the national market. London and Cambridge concentrate commercial laboratory operations serving both domestic demand and European export contracts.
China
Domestic sequencing platform manufacturers compete with imported systems in tertiary hospital cardiology departments. The National Medical Products Administration regulates in vitro diagnostics through risk-based classification and clinical trial requirements. Beijing and Shanghai host clinical research organizations conducting cardiogenetic studies for multinational diagnostic developers.
Japan
University hospitals in Tokyo and Osaka adopt next-generation sequencing panels for familial cardiomyopathy screening. The Pharmaceuticals and Medical Devices Agency reviews genetic testing systems through a structured premarket consultation framework. The Ministry of Economy, Trade and Industry supports precision medicine infrastructure investments through targeted R&D programs.
Cardiology Genomic Testing Market Competitive Landscape
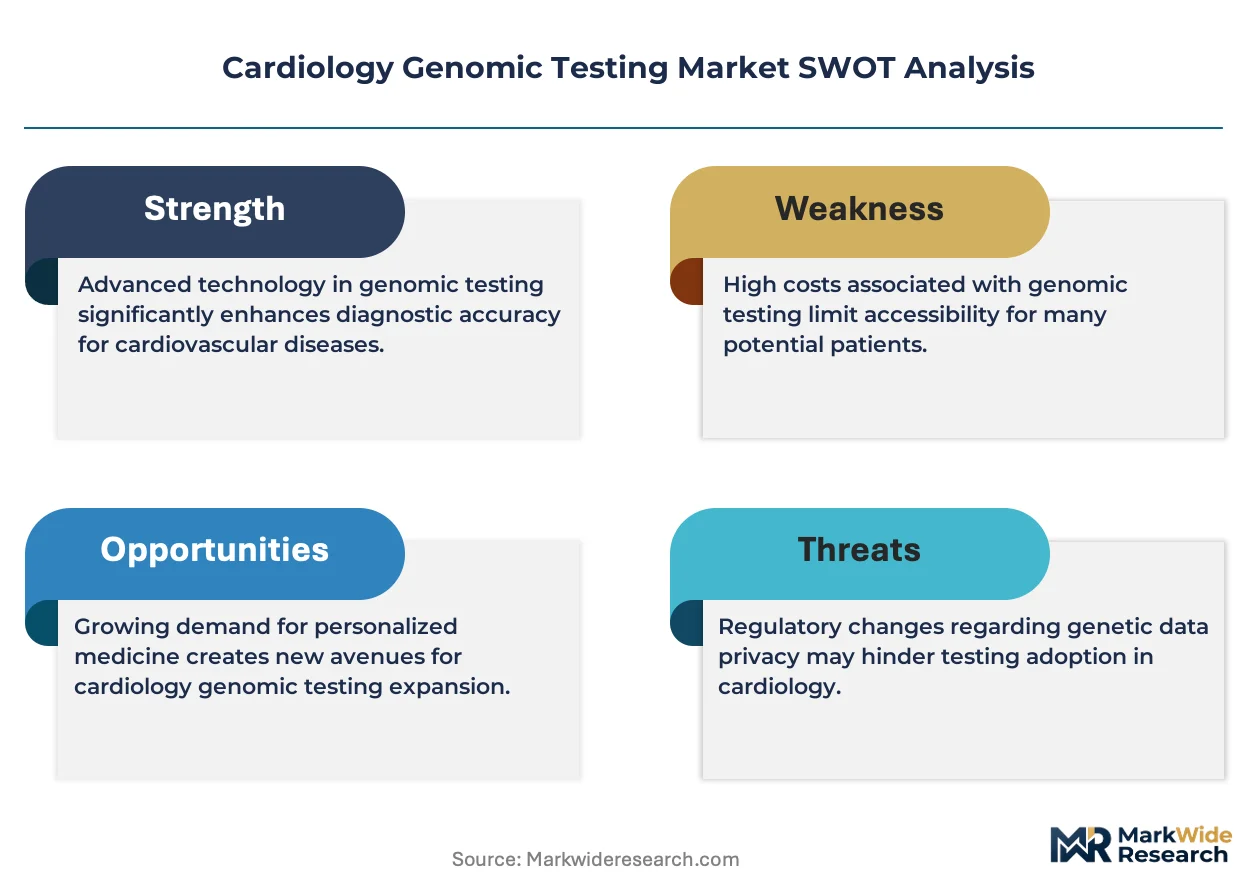
Listed leaders compete with private specialists across platform supply and laboratory service provision. The vendor base separates into instrument manufacturers with reagent pull-through economics, independent reference laboratories competing on turnaround time, and integrated health systems with captive testing capacity. Three archetypes dominate: upstream platform suppliers, midstream sample preparation specialists, and downstream clinical testing services. Consolidation concentrates among multinational diagnostic manufacturers acquiring regional reference laboratories, while technology licensing agreements proliferate between instrument makers and bioinformatics developers.
Within the platform supply tier, Illumina Inc. and Thermo Fisher Scientific Inc. anchor the upstream sequencing ecosystem, with QIAGEN N.V. occupying a distinct position in sample preparation automation. These three entities exemplify the instrument-reagent lock-in dynamics that shape hospital procurement committee decisions across major health systems.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| F. Hoffmann-La Roche Ltd. |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics Incorporated |
| Invitae Corporation |
| GeneDx Inc. |
| Myriad Genetics Inc. |
| Others |
Value Network & Pricing Analysis
ISO 15189 accreditation gates both laboratory qualification and reimbursement eligibility, creating tiered price differentiation between accredited hospital laboratories and non-accredited reference facilities while simultaneously restricting supply to certified vendors capable of supporting quality management system documentation.
Pricing Analysis
Next-generation sequencing platform pricing compresses against third-generation long-read systems entering pilot deployment, while Sanger confirmation testing retains premium per-sample economics in low-volume variant validation workflows. Three-tier pricing structure across comprehensive panels, targeted hotspot assays, and pharmacogenomic genotyping reflects certification grade and turnaround time commitments. Cost compression in high-throughput sequencing consumables intensifies as health systems negotiate multi-year sole-source agreements bundling instruments, reagents, and bioinformatics. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize panel breadth and interpretation quality over per-test minimization.
Supply Chain Analysis
Reagent manufacturing concentration in the United States, Germany, and China creates single-source vulnerability for sequencing consumables tied to specific instrument ecosystems. Supply chains draw from specialized polymerase enzymes, fluorescently labeled nucleotides, and semiconductor-based flow cells as critical input categories. Tariff exposure on Chinese-sourced sample preparation plastics and European-manufactured optical components threatens margin stability for mid-sized reference laboratories. Distribution runs through direct vendor-to-health-system contracts for major platforms, while independent reference laboratories source through authorized distributors competing on logistics speed and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from telemedicine-enabled direct-to-consumer genetic counseling platforms that bypass traditional hospital laboratory procurement channels and capture patient-initiated screening demand.
For Market Incumbents: Secure captive supply agreements for third-generation sequencing platforms before long-read technology decomposes panel-based pricing architectures. Anchor hospital procurement committees with bundled bioinformatics infrastructure that raises switching costs against emerging platform competitors. Defensive consolidation into genetic counseling services creates vertical integration barriers against direct-to-consumer channel entrants.
For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-tracks regulatory clearance for inherited cardiomyopathy assays, enabling accelerated market entry against entrenched reference laboratories. Target independent diagnostic centers serving outpatient cardiology practices lacking in-house sequencing capacity as the most penetrable channel. Deploy telemedicine-enabled genetic counseling as the primary go-to-market angle to circumvent hospital procurement committee gatekeeping.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical-grade long-read sequencing infrastructure as third-generation platforms require specialized facilities and expert interpretation capacity. Five-to-ten year viability favors laboratories with established payer contracts and health system integration depth over pure technology developers. Acquisition target archetype: mid-sized reference laboratories with ISO 15189 accreditation and existing cardiogenetic test menus. Monitor FDA Breakthrough Device Designation awards as the signal to watch for commercialization timeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage determination for expanded cardiomyopathy panels shapes addressable patient populations. |
| Hospital System Partnership | Multi-year sole-source agreements with health systems exceeding five billion dollars in revenue anchor platform demand. |
| Software Companion Development | AI variant classification tools reduce interpretation burden and accelerate report turnaround times. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance enables European market access for high-risk genetic tests. |
| Platform Integration | Long-read sequencing adoption resolves structural variant detection gaps in negative panel cases. |
Research Methodology
A standing panel of hospital laboratory directors, genetic counselors, cardiology department chiefs, payer medical policy leads, and diagnostic manufacturer product managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) and Breakthrough Device Designation filings, EMA In Vitro Diagnostic Regulation guidance documents, CMS Medicare coverage determinations, and hospital procurement database records. Bottom-up test volume estimates triangulated against top-down health system spending allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including academic medical center sequencing capacity disclosures, diagnostic manufacturer instrument placement announcements, and payer contract coverage expansions. Segmentation modeling incorporated test type, technology generation, end-user channel, and clinical application dimensions. CAGRs derived from logistic adoption curves fitted to historical penetration data and projected reimbursement pathway maturation, with sensitivity analysis around FDA review timeline scenarios and EMA notified body certification completion rates.
Decision-makers should treat outputs as directional under assumptions of stable Medicare coverage policy and continued FDA Breakthrough Device pathway utilization; material deviation in payer evidentiary requirements would warrant model refresh. Practitioners should keep alternative scenarios live as European notified body certification deadlines and pharmacogenomic reimbursement code developments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market