
 Renal Function Test Market | 2026-2036
Renal Function Test Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Function Test Market Analytics
European reagent manufacturing capacity is shifting toward automated chemistry analyzer consumables as labs consolidate procurement. Siemens Healthineers leverages its installed base of integrated chemistry systems to sustain recurring revenue from renal test menus. Abbott Laboratories anchors its position through point-of-care creatinine devices deployed in emergency departments. F. Hoffmann-La Roche Ltd competes on immunoassay precision for glomerular filtration rate estimation in reference laboratories.
Renal function tests measure biomarkers including serum creatinine, blood urea nitrogen, and electrolyte concentrations to assess kidney filtration performance and electrolyte balance, typically processed on clinical chemistry analyzers with spectrophotometric or enzymatic detection methods. The serum creatinine test segment dominates routine screening volumes due to standardization under international calibration traceability programs. Point-of-care testing technology is expanding fastest in physician offices and home care settings where rapid turnaround influences clinical decision-making. Diagnostic laboratories retain the largest margin pool through bundled electrolyte panel pricing and automated high-throughput processing.
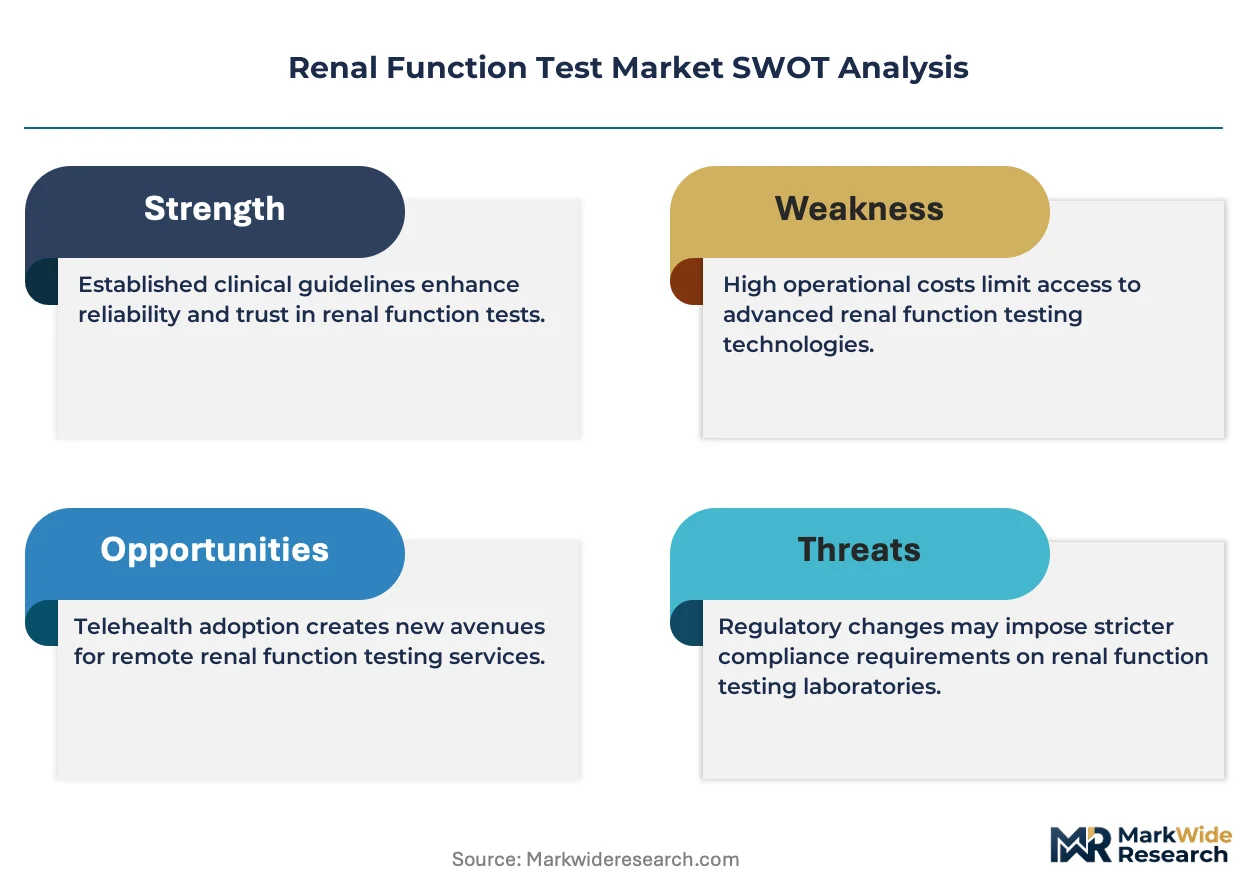
FDA premarket notification requirements shape point-of-care renal device commercialization timelines, while Clinical Laboratory Improvement Amendments govern laboratory-developed test validity for specialized renal panels. The EU In Vitro Diagnostic Regulation mandates performance evaluations for creatinine and eGFR assays sold in European member states. Stakeholders must monitor evolving reimbursement thresholds for chronic kidney disease screening codes across public and private payers.
Market Dynamics
Medicare reimbursement policies for preventive renal screening in diabetic populations are compressing diagnostic timelines and reshaping how laboratories configure their test panels. This structural pull toward early detection is forcing equipment manufacturers to prioritize throughput and automation over standalone device sales.
Growth Catalysts
- Preventive Screening Mandates:Medicare reimbursement codes now cover annual renal function testing for high-risk diabetic enrollees, expanding routine screening volumes in physician networks.
- Enzymatic Creatinine Methods:Laboratories are replacing Jaffe kinetic assays with enzymatic detection to eliminate bilirubin interference and improve result accuracy in icteric samples.
- Integrated Chemistry Systems:Health systems consolidating laboratory procurement favor vendors offering bundled electrolyte and renal panels on unified analyzer platforms.
Market Restraints
- Reagent Supply Concentration:European manufacturing clusters control bulk enzyme production for creatinine assays, exposing distributors to single-source dependency risks.
- Calibration Traceability Costs:International standardization programs require isotope dilution mass spectrometry reference materials, elevating quality control expenditures for mid-sized laboratories.
- Point-of-Care Accuracy Limitations:Capillary whole blood creatinine devices demonstrate wider coefficient of variation compared to venous serum methods, restricting their deployment in nephrology referral settings.
Strategic Opportunities
- Home-Based Monitoring:Connected creatinine meters with cellular data transmission are penetrating dialysis patient populations seeking to reduce clinic visit frequency.
- Cystatin C Immunoassays:Manufacturers are adding cystatin C to routine panels for glomerular filtration rate estimation independent of muscle mass variability.
- EU MDR Performance Evaluations:The In Vitro Diagnostic Regulation mandates clinical evidence for eGFR assays, creating first-mover advantages for vendors with pre-submitted technical documentation.
Industry Challenges
- Cross-Platform Standardization:Laboratories operating mixed vendor environments struggle to harmonize eGFR reporting across analyzers with different calibration schemes.
- CLIA Complexity for POCT:Physician offices deploying waived creatinine devices face personnel competency documentation requirements under Clinical Laboratory Improvement Amendments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Function Test Market |
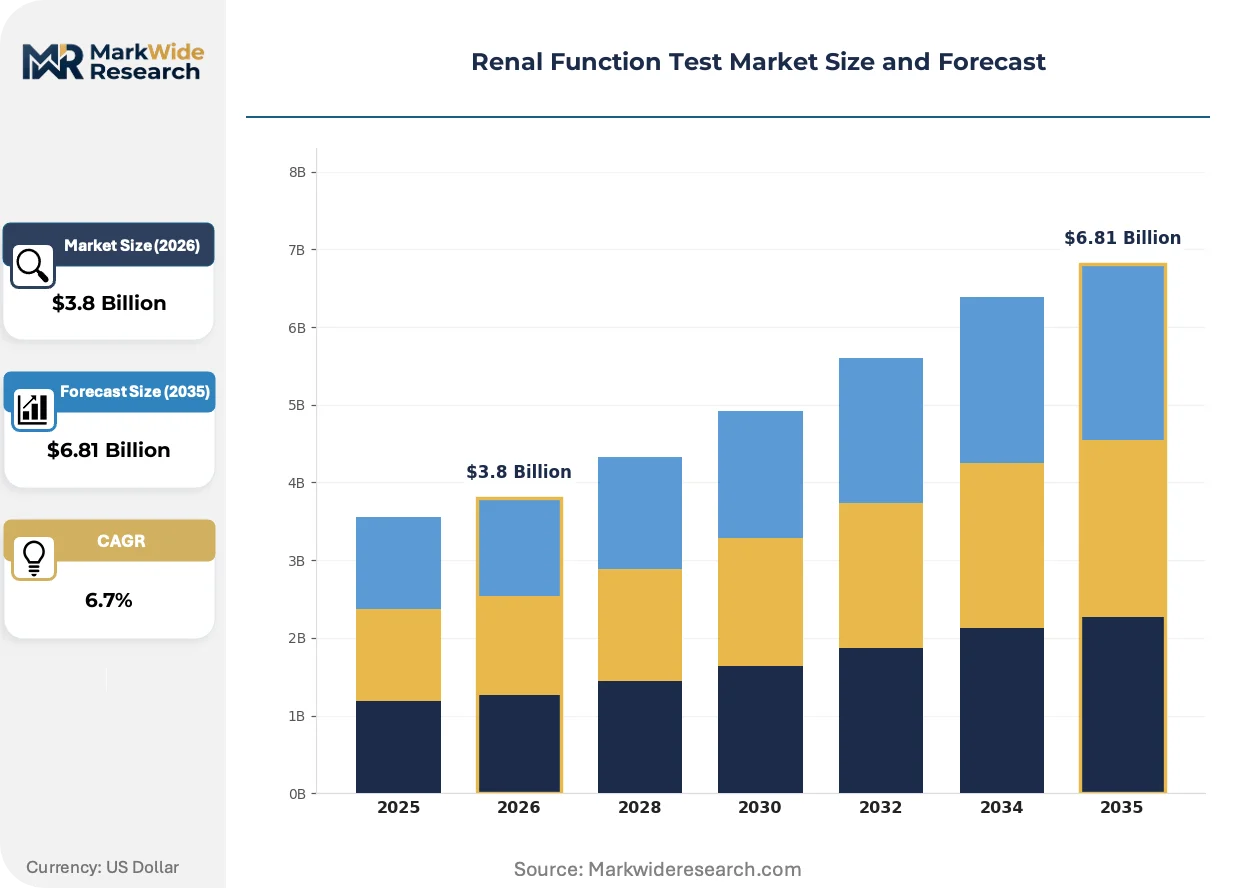
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum Creatinine Test, Blood Urea Nitrogen Test, Glomerular Filtration Rate Test, Electrolyte Panel Technology: Chemistry Analyzer, Point-of-Care Testing, Immunoassay, Microfluidics End User: Hospitals, Diagnostic Laboratories, Home Care, Physician Offices Application: Chronic Kidney Disease, Acute Kidney Injury, Drug Monitoring, Routine Screening |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Danaher Corporation, Quest Diagnostics, Sysmex Corporation, Randox Laboratories Ltd, Laboratory Corporation of America Holdings, Nova Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Function Test Market Evolving Landscape
Artificial intelligence interpretation of renal biomarker patterns is compressing the diagnostic pathway from sample to clinical decision. These computational advances are converging with miniaturized sensor platforms to redefine where testing occurs.
Microfluidic cartridge systems for creatinine and blood urea nitrogen are electrifying point-of-care deployment in emergency departments and urgent care centers. Hospital systems adopting these platforms report 40-minute turnaround improvements over central laboratory send-outs. This velocity is compressing admission decision timelines and displacing stat laboratory calls for routine renal assessment.
The EU In Vitro Diagnostic Regulation is tightening clinical evidence requirements for creatinine assays marketed in member states. Manufacturers must now submit performance evaluation reports demonstrating traceability to ID-MS reference methods. Reference laboratories in Germany and France are prioritizing vendors with completed MDR technical documentation, accelerating procurement consolidation toward established suppliers.
Health system purchasing cooperatives are unbundling renal test pricing from comprehensive chemistry panel contracts. Independent laboratories in Texas and Florida now negotiate standalone electrolyte pricing through group purchasing organizations. This disaggregation is most visible in Medicare Advantage networks seeking to optimize medical loss ratios through reference laboratory switching.
Renal Function Test Market Segmentation
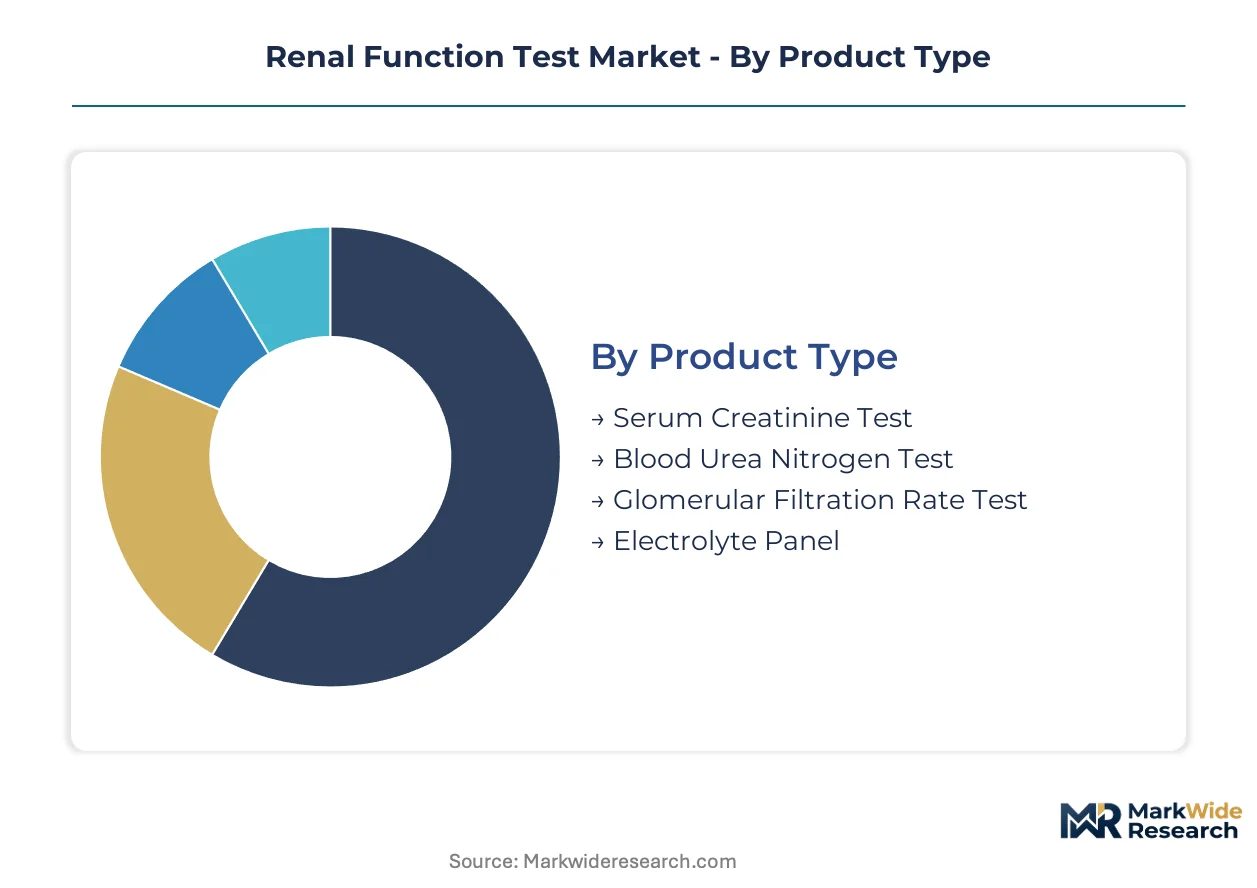
Renal function test segmentation reveals divergent margin structures across testing modalities. Laboratories prioritize throughput economics while point-of-care settings trade accuracy for velocity. Understanding these trade-offs illuminates where equipment vendors and reagent suppliers can defend pricing power.
Product Type:
Laboratory procurement committees weight test standardization against panel bundling economics when selecting renal assays for routine chemistry menus.
- Serum Creatinine Test:Enzymatic detection methods now dominate reference laboratory workflows, eliminating Jaffe assay interference from bilirubin and ketones. United States Medicare Advantage networks concentrate screening volumes here due to established reimbursement codes for diabetic monitoring.
- Blood Urea Nitrogen Test:Spectrophotometric quantification of urea nitrogen serves as a complementary filtration marker, though dietary protein variability limits standalone diagnostic utility. Hospital systems in Germany and France bundle BUN with electrolyte panels on automated chemistry platforms to maximize analyzer utilization rates.
- Glomerular Filtration Rate Test:Calculated estimates from creatinine or cystatin C equations guide nephrology referral decisions.
- Electrolyte Panel:Sodium, potassium, and chloride measurements accompany renal markers in bundled pricing contracts.
Serum creatinine leads on scale; cystatin C-enhanced GFR estimation leads on momentum.
Technology:
Capital deployment cycles separate installed-base vendors from disruptive entrants, with health system consolidation favoring unified platform commitments over best-of-breed point solutions.
- Chemistry Analyzer:High-throughput spectrophotometric systems process 800-1,200 tests hourly on integrated reagent cartridges. Siemens Healthineers and Roche Diagnostics sustain recurring revenue through closed consumable ecosystems tied to these analyzers.
- Point-of-Care Testing:Capillary whole blood devices deliver 3-5 minute creatinine results in emergency departments. Texas and Florida urgent care chains are expanding deployment fastest where admission decisions hinge on rapid renal assessment.
- Immunoassay:Cystatin C quantification requires antibody-based detection unavailable on standard chemistry analyzers.
- Microfluidics:Cartridge-based systems miniaturize multi-analyte panels for decentralized deployment.
Chemistry analyzers lead on scale; microfluidic platforms lead on momentum.
End User:
Reimbursement pathway complexity shapes where testing volume concentrates, with Medicare preventive screening mandates pulling routine work toward physician-accessible settings.
- Hospitals:Integrated health systems operate centralized laboratories serving multiple facilities through hub-and-spoke logistics. Academic medical centers in Boston and Cleveland maintain reference-grade calibration programs for complex renal case referrals.
- Diagnostic Laboratories:Independent reference labs compete on bundled electrolyte pricing through group purchasing organizations. Quest Diagnostics and LabCorp leverage national collection networks to capture Medicare Advantage contract switching.
- Home Care:Connected creatinine meters with cellular transmission reduce dialysis patient clinic visit frequency.
- Physician Offices:Waived testing under CLIA guidelines enables rapid screening in primary care workflows.
Diagnostic laboratories lead on scale; home care leads on momentum.
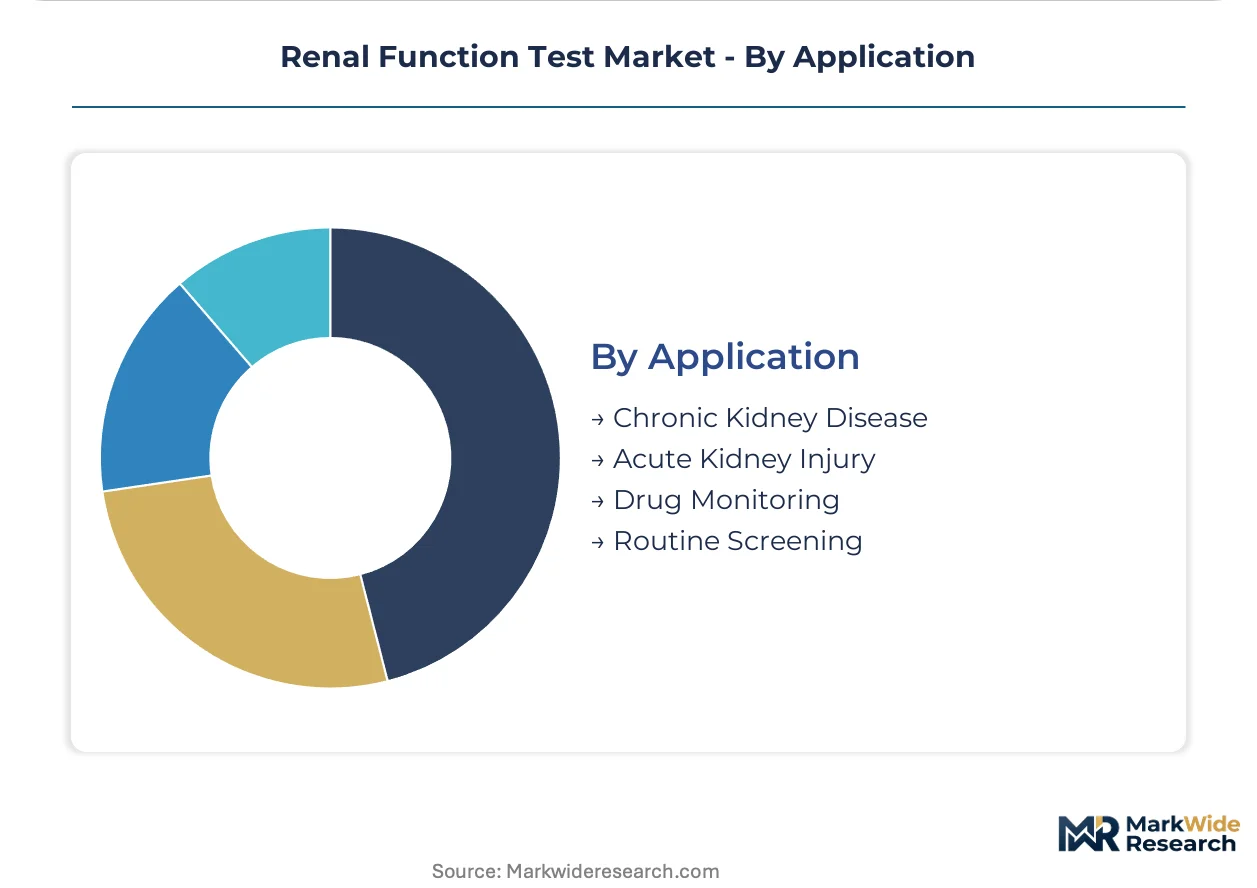
Application:
Clinical utility varies across disease states, with chronic condition monitoring offering predictable volume against acute settings demanding faster turnaround.
- Chronic Kidney Disease:Stage-based monitoring protocols require quarterly creatinine and eGFR surveillance for progression tracking. United States nephrology practices drive consistent demand through Medicare quality metrics tied to early detection.
- Acute Kidney Injury:ICU and emergency department surveillance demands hourly creatinine trending for contrast-induced nephropathy prevention. Cleveland Clinic and Mayo Clinic systems have implemented automated alert systems triggering nephrology consultation.
- Drug Monitoring:Nephrotoxic medication surveillance requires timed creatinine clearance assessments.
- Routine Screening:Asymptomatic population testing expands through employer wellness programs.
Chronic kidney disease leads on scale; acute kidney injury surveillance leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting reagent manufacturing toward jurisdictions with streamlined quality certification pathways, while diagnostic volume concentrates where preventive screening reimbursement is most favorable.
United States
Medicare Advantage networks in Texas and Florida are driving point-of-care creatinine deployment through bundled preventive screening contracts. FDA premarket notification pathways for waived testing devices compress commercialization timelines for new entrants. The Cleveland Clinic and Mayo Clinic systems anchor reference-grade calibration programs in Ohio and Minnesota.
Germany
Reference laboratories in Berlin and Munich prioritize vendors with completed EU MDR technical documentation for creatinine assays. The country's national pharmaceutical regulator enforces performance evaluation requirements that accelerate procurement consolidation toward established suppliers. Siemens Healthineers leverages its installed base in Baden-Württemberg for recurring chemistry analyzer revenue.
China
Domestic enzyme production for creatinine assays is expanding in Jiangsu and Zhejiang provinces to reduce import dependency. The National Medical Products Administration streamlines registration for in-vitro diagnostic reagents with traceable reference materials. Shanghai-based diagnostic chains are consolidating procurement around automated chemistry platforms.
Japan
Academic medical centers in Tokyo and Osaka maintain stringent calibration programs for glomerular filtration rate estimation. The Pharmaceuticals and Medical Devices Agency enforces post-market surveillance for point-of-care renal devices. Sysmex Corporation anchors its position through integrated hematology-chemistry systems deployed in Kansai region hospitals.
India
Diagnostic laboratory chains in Maharashtra and Karnataka are expanding renal test panels for diabetic population screening. The Central Drugs Standard Control Organization regulates import licensing for creatinine assay reagents. Mumbai-based reference laboratories compete on bundled electrolyte pricing through corporate health checkup contracts.
Renal Function Test Market Competitive Landscape
United States producers anchor one tier through integrated health system contracts; European specialists hold another through automated chemistry analyzer ecosystems. The vendor base stratifies across three tiers: multinational conglomerates with closed consumable platforms, mid-scale regional reagent suppliers, and point-of-care device specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers prioritizing recurring revenue streams over standalone equipment sales.
Within the multinational conglomerate tier, Abbott Laboratories, F. Hoffmann-La Roche Ltd, and Siemens Healthineers exemplify divergent strategic positioning. Abbott occupies a position emphasizing point-of-care deployment in emergency settings. Roche exemplifies precision-focused immunoassay competition for reference laboratory contracts. Siemens anchors its market presence through installed-base leverage in integrated chemistry systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Danaher Corporation |
| Quest Diagnostics |
| Sysmex Corporation |
| Randox Laboratories Ltd |
| Laboratory Corporation of America Holdings |
| Nova Biomedical |
| Others |
Value Network & Pricing Analysis
Biomedical engineer concentrations in Massachusetts and North Carolina sustain premium pricing for enzymatic creatinine reagents while labor-cost differentials between European manufacturing clusters and Asian assembly sites widen spreads between reference-grade and economy-tier assay pricing.
Pricing Analysis
Distributor margins on enzymatic creatinine reagents typically capture 15-25 percent of landed cost before hospital group purchasing organizations negotiate volume rebates. Price differentiation hinges on ID-MS traceability certification and bundled electrolyte panel contracts. Pricing pressure stems from Medicare reimbursement compression for routine screening codes. Independent reference laboratories exhibit highest price sensitivity; academic medical centers prioritize calibration reliability over per-test cost.
Supply Chain Analysis
Enzyme feedstock supply rests on fermentation capacity concentrated in Germany, Denmark, and the Netherlands. Key inputs include recombinant creatininase, buffer reagents, and spectrophotometric calibration standards. Single-source vulnerability pervades specialty enzyme production where regulatory qualification timelines deter supplier switching. Distribution runs through regional reagent distributors serving consolidated health system laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renal function test market compounds steadily as chronic kidney disease prevalence rises with aging diabetic populations across developed economies.
For Market Incumbents: Acquire point-of-care device platforms to preempt disintermediation from decentralized testing. Siemens Healthineers and Roche Diagnostics should consolidate cystatin C immunoassay capacity before EU MDR documentation requirements harden procurement barriers. Defensive patent filings around microfluidic cartridge designs will block emerging entrants from emergency department placement. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass incumbent distributor relationships for waived creatinine devices in urgent care chains. Home-based monitoring for dialysis populations offers the most penetrable white-space segment. Pursue FDA 510(k) clearance with predicate device strategies rather than de novo pathways to compress time-to-revenue. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European reagent suppliers lacking completed MDR technical documentation. Five-to-ten year viability favors vendors with captive enzyme production and locked hospital system contracts. Watch FDA guidance on artificial intelligence-enabled renal biomarker interpretation as an inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Performance Evaluation Completion | Accelerates procurement consolidation toward documented vendors in Germany and France. |
| Enzymatic Method Patent Expansion | Extends exclusivity periods for bilirubin-resistant creatinine detection chemistry. |
| Hospital System Partnership | Locks recurring revenue through closed consumable ecosystems on unified analyzers. |
| Home Care Cellular Connectivity Integration | Captures dialysis patient monitoring volume outside traditional clinic settings. |
| Cystatin C Panel Addition | Differentiates GFR estimation from muscle-mass-dependent creatinine methods. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market gathered through structured interviews with clinical laboratory directors, hospital purchasing committee members, IVD regulatory affairs specialists, and reagent distribution executives. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation filings, CMS Medicare reimbursement code updates, and hospital procurement database extracts. Bottom-up test volume modeling triangulated against top-down healthcare expenditure allocations.
Granularity was maintained at the test-type, technology-platform, and end-user-setting levels across the projection horizon. Segmentation dimensions included assay methodology, analyzer throughput tier, and care setting acuity. CAGRs were derived from logistic diffusion curves fitted to Medicare screening penetration rates and diabetes prevalence forecasts. Industry-specific inputs encompassed enzymatic reagent conversion timelines and point-of-care waived test adoption curves.
The model assumes a particular technology adoption path; alternative pathways for microfluidic cartridge platforms would alter the outlook if hospital capital expenditure cycles accelerate. Forecasts reflect assumptions about reimbursement stability and regulatory documentation burdens. Supply concentration in European enzyme manufacturing and FDA premarket notification timelines warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market