
 Azimuth Thrusters Market | 2026-2036
Azimuth Thrusters Market Size, Share, and Industry Trends Forecast 2026-2036
Azimuth Thrusters Market Analysis
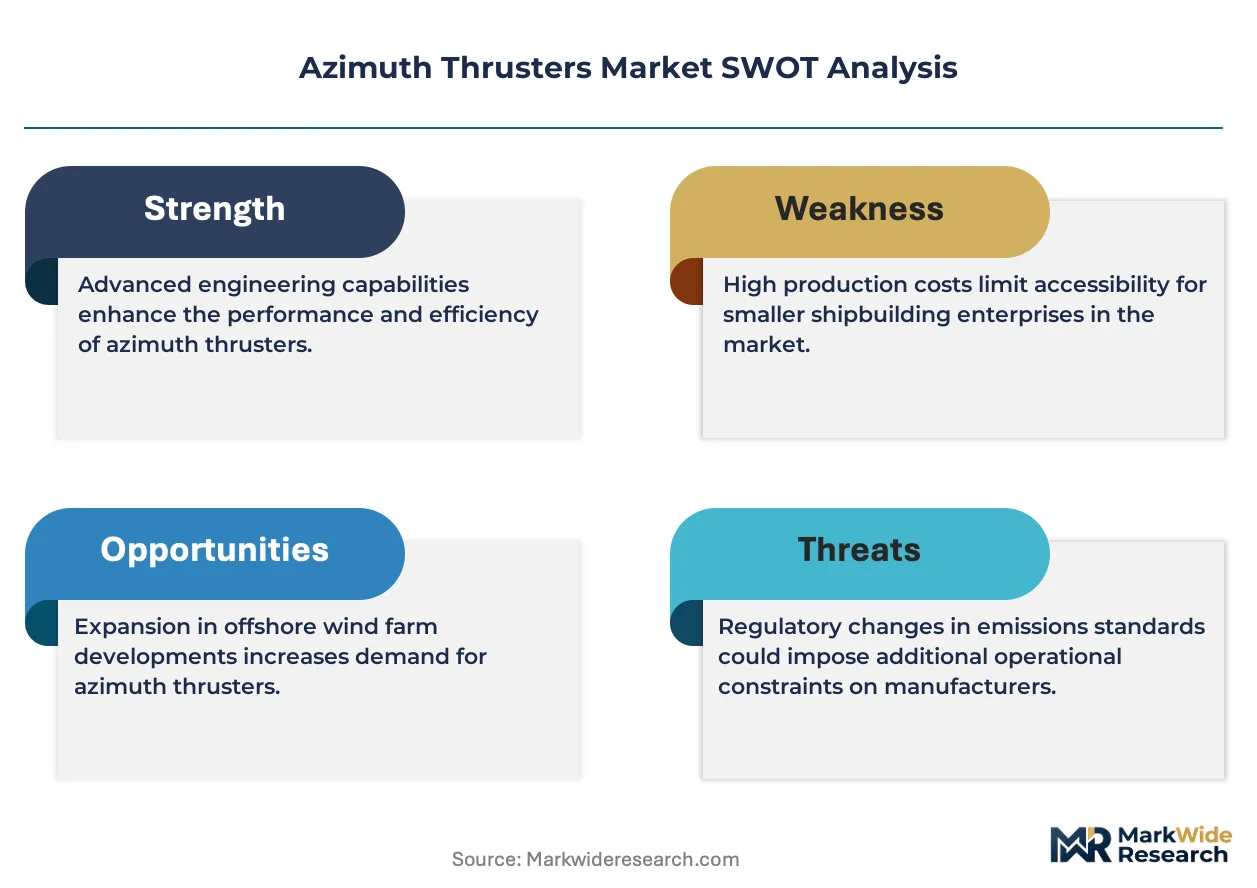
Maintenance and lifecycle service contracts are shifting how azimuth thruster vendors capture value beyond hardware sales. Brunvoll leverages its integrated service network across Nordic shipyards to lock in long-term aftermarket revenue. Kongsberg anchors its position through deep R&D investment in condition-monitoring systems that predict thruster wear before failure. Wärtsilä Corporation dominates the high-power electric segment by controlling proprietary motor-drive technology that competitors cannot easily replicate.
An azimuth thruster is a steerable propulsion unit where the propeller rotates through 360 degrees around a vertical axis, typically rated from 500 kW to over 20 MW and built from nickel-aluminum-bronze propellers mounted in hydrodynamically optimized nozzles. Electric thrusters lead the type category as ship operators prioritize fuel efficiency and emission compliance over lower first-cost mechanical alternatives. The offshore support end-user segment commands the deepest margin pools because dynamic positioning requirements demand redundant thruster arrays with intensive service obligations.
IMO Tier III nitrogen oxide limits and the EU MRV monitoring framework compel fleet operators to specify electric and hybrid thruster configurations that cut fuel consumption during station-keeping operations. Classification societies including DNV and Lloyd's Register now embed thruster reliability metrics into vessel notation rules, effectively gating market access for unproven suppliers. Stakeholders must track how fuel-cell shore-power integration at ports reshapes thruster duty cycles and sizing specifications for next-generation vessel designs.
Market Dynamics
Electric propulsion architectures are compressing mechanical drivetrain demand as IMO decarbonization timelines harden. Shipyards now specify integrated podded systems rather than separate engine-gearbox-thruster assemblies, redrawing supplier power across the maritime value chain.
Growth Catalysts
- IMO Tier III NOx mandates:European flag states enforce nitrogen oxide limits that disqualify conventional mechanical thrusters from newbuild contracts. Operators retrofit existing fleets with electric azimuth units to retain port access.
- Deepwater exploration:Brazil's pre-salt fields and West African offshore blocks require dynamic positioning systems with redundant thruster arrays. Drillship contractors specify 15+ MW electric units per vessel.
- Nickel-aluminum-bronze casting advances:Foundries in Norway and Finland now produce cavitation-resistant propellers with 40% longer service intervals. Extended maintenance cycles reduce drydock downtime for offshore support operators.
Market Restraints
- Copper-nickel alloy price volatility:Propeller material costs swing with LME metal indices, squeezing thruster OEM margins on fixed-price shipyard contracts.
- High-voltage motor supply concentration:Permanent magnet motor production clusters in China and Germany. Non-Chinese thruster builders face 18-month lead times for 10+ MW electric motors.
- Classification society certification timelines:DNV and Lloyd's Register type-approval processes for novel thruster designs extend 24-36 months, delaying commercialization of experimental nozzle geometries.
Strategic Opportunities
- Fuel-cell shore power integration:Norwegian ports install hydrogen bunkering that enables zero-emission thruster testing. Shipyards in Bergen and Ålesund attract green vessel R&D contracts.
- Autonomous vessel retrofits:Unmanned surface vehicle developers repurpose compact azimuth thrusters from decommissioned offshore supply vessels. Second-life component markets emerge in Singapore and Rotterdam.
- EU Green Deal maritime funding:Innovation grants cover 40% of electric propulsion retrofit costs for vessels under 5,000 gross tons. Greek and Italian ferry operators accelerate fleet conversion programs.
Industry Challenges
- Marine electrical engineer scarcity:Shipyards in Norway and Germany compete for technicians qualified in medium-voltage drive commissioning. Training programs at Aalesund University College cannot match industry absorption rates.
- Legacy hydraulic steering integration:Retrofitting electric azimuth units onto 1990s-era vessels requires custom adapter plates and control system bridges. Engineering hours balloon on one-off conversion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azimuth Thrusters Market |
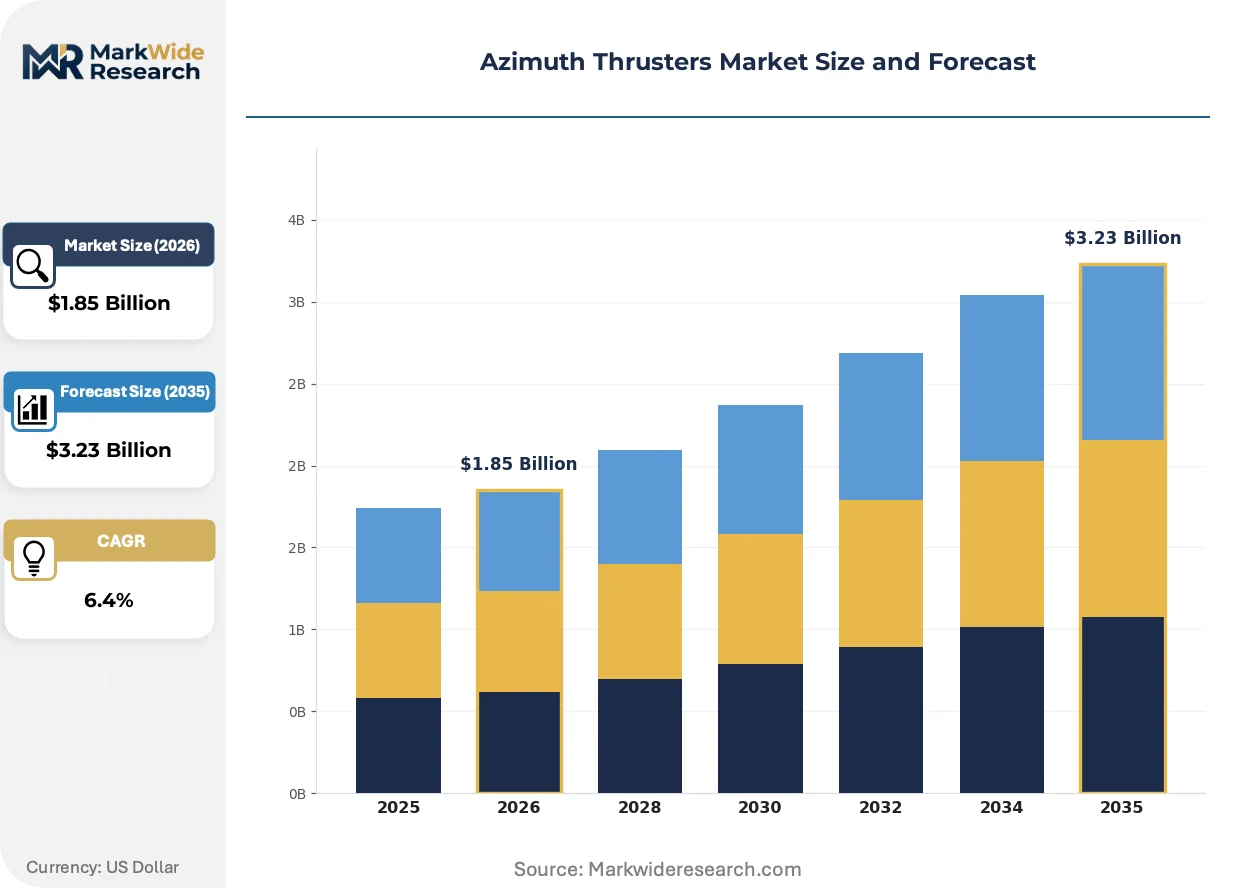
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Hydraulic, Mechanical, Hybrid End User: Commercial Vessels, Offshore Support, Naval, Yachting Installation: Retrofit, New Build, Integrated, Modular Application: Dynamic Positioning, Maneuvering, Towing, Sailing |
| Companies Covered | Brunvoll, IHI, SCHOTTEL Group, Steerprop, Thrustmaster, Rolls-Royce, Kongsberg, Wärtsilä Corporation, ABB Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azimuth Thrusters Market Emerging Trajectories
Permanent magnet motor technology is compressing thruster footprint and maintenance intervals simultaneously. Ship operators now prioritize integrated electric systems over mechanical alternatives, forcing traditional gearbox suppliers to reposition or exit.
Permanent magnet synchronous motor technology is decentralizing thruster power distribution architecture. These motors eliminate separate gearbox rooms by mounting directly to the propeller shaft. Offshore vessel operators in the North Sea adopt them for 20% fuel savings during dynamic positioning. The shift collapses demand for standalone reduction gear manufacturers and redraws shipyard electrical contracting scopes.
EU F-Gas Regulation restrictions on synthetic lubricants are forcing thruster seal material redesigns. Fluoropolymer compounds face phase-down schedules that disqualify legacy stern tube sealing systems. European ferry operators pressure suppliers for bio-compatible alternatives. Classification societies in Hamburg and Oslo fast-track approval protocols for plant-based hydraulic fluids.
Condition-based maintenance contracts are displacing fixed-interval service agreements. Offshore vessel managers in Norway now pay per operational hour with remote vibration monitoring. Kongsberg's cloud analytics platform transmits thruster health data to shoreside teams. Greek and Cypriot tanker fleets lag this transition, retaining traditional drydock schedules due to lower digital infrastructure investment.
Azimuth Thrusters Market Segmentation
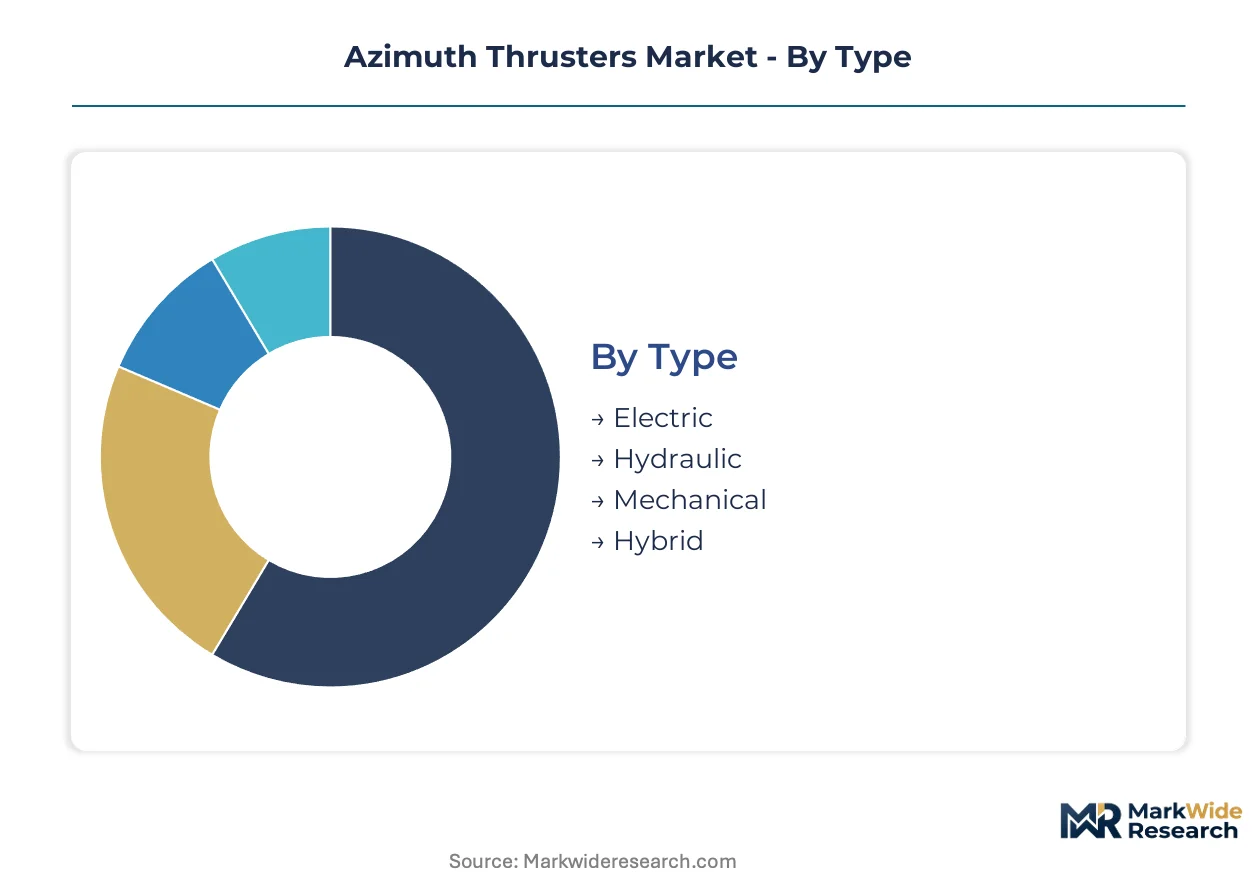
Segmentation in azimuth thrusters reveals how propulsion technology embeds into vessel architecture. Electric and hybrid configurations now dominate newbuild specifications as shipyards integrate power systems at the hull design stage rather than retrofitting later.
Type:
Standalone thruster units serve conventional mechanical installations, while integrated electric systems embed motor drives directly into podded housings.
- Electric:Permanent magnet synchronous motors mount directly to propeller shafts, eliminating separate gearbox rooms. Offshore vessel operators in Norway specify these for dynamic positioning fuel savings. IMO Tier III compliance requirements in European flag states accelerate displacement of mechanical alternatives.
- Hybrid:Dual-mode systems combine diesel-mechanical cruising with electric silent-running for naval and research applications. Shipyards in Bergen and Ålesund attract green vessel R&D contracts through hydrogen-ready hybrid configurations. EU Green Deal maritime funding covers substantial retrofit costs for vessels under 5,000 gross tons.
- Hydraulic:Fluid-power thrusters persist in heavy-towing applications requiring instantaneous torque response.
- Mechanical:Conventional engine-gearbox assemblies now concentrate in emerging-market shipyards with limited electrical infrastructure.
Volume placements concentrate in Electric; the faster expansion belongs to Hybrid.
End User:
Margin structures diverge sharply between price-sensitive commercial fleets and specification-intensive offshore contractors.
- Offshore Support:Drillship contractors demand redundant thruster arrays rated 15+ MW per unit for station-keeping in Brazil's pre-salt fields and West African deepwater blocks. Dynamic positioning requirements mandate intensive service contracts that deepen vendor relationships beyond hardware sales.
- Commercial Vessels:Ferry operators across Greece and Italy accelerate electric conversion programs under EU innovation grants. Classification societies embed reliability metrics into vessel notation rules, gating market access for unproven suppliers.
- Naval:Military specifications prioritize acoustic signature suppression and shock resistance over commercial efficiency metrics.
- Yachting:Superyacht builders in the Netherlands and Germany specify compact podded units for maneuverability in confined marinas.
Revenue concentration sits with Offshore Support; Commercial Vessels are gaining share fastest through fleet retrofit mandates.
Installation:
Shipyard build strategies determine whether thrusters arrive as pre-integrated packages or field-assembled components.
- New Build:Integrated podded systems specified at the design stage allow optimized hull forms and power distribution architectures. Shipyards now contract electrical scope separately from traditional mechanical suppliers, redrawing value chain boundaries.
- Integrated:Factory-tested thruster-motor-drive packages reduce commissioning time and warranty disputes. Norwegian yards leverage Brunvoll's service network for long-term aftermarket lock-in.
- Retrofit:Legacy hydraulic steering integration requires custom adapter plates and control system bridges, ballooning engineering hours on one-off conversion projects.
- Modular:Containerized thruster units enable rapid replacement in remote operating locations with limited drydock access.
Contract flow favors New Build; Integrated configurations are climbing the fastest as shipyards seek risk transfer to OEMs.
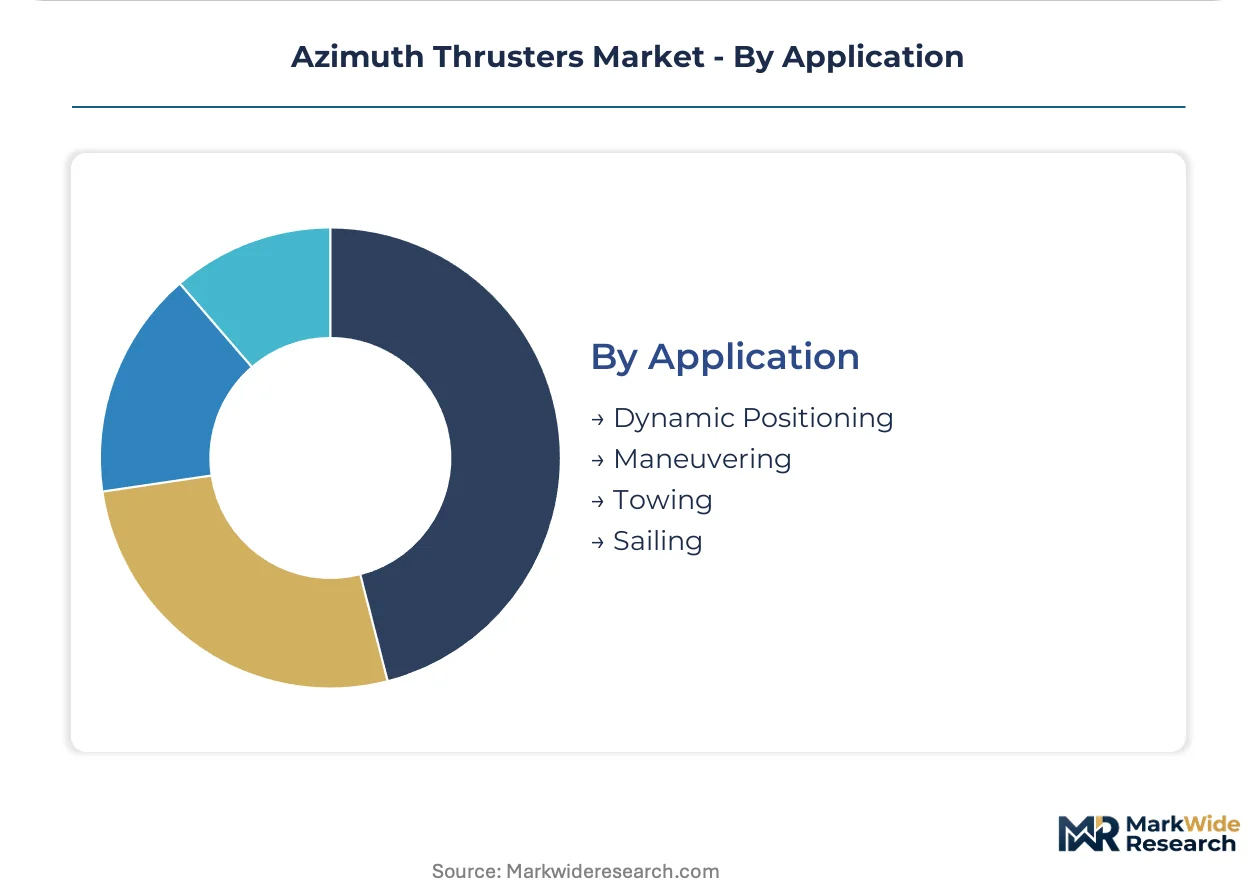
Application:
Operational duty cycles determine thruster sizing, redundancy requirements, and control system complexity.
- Dynamic Positioning:Redundant azimuth arrays maintain vessel station without anchors in deepwater drilling and subsea construction. Condition-based maintenance contracts with per-operational-hour pricing now displace fixed-interval service agreements for offshore vessel managers.
- Maneuvering:Harbor tugs and escort vessels require rapid thrust vectoring for ship-assist operations. Port authorities in Rotterdam and Singapore specify bollard pull certification that validates thruster performance under load.
- Towing:Continuous high-load operations demand cavitation-resistant nickel-aluminum-bronze propellers with extended service intervals.
- Sailing:Auxiliary thrusters on wind-assisted cargo vessels provide harbor maneuverability without compromising sailing efficiency.
Specification intensity peaks in Dynamic Positioning; Maneuvering applications are expanding most quickly through port automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bergen anchors the densest maritime technology cluster for azimuth thruster engineering, with Norwegian shipyards and propulsion specialists concentrating R&D investment along the country's western fjord coastline.
Norway
Offshore vessel operators in the North Sea specify permanent magnet electric thrusters for dynamic positioning fuel savings. The Norwegian Maritime Authority enforces IMO Tier III compliance timelines that accelerate displacement of mechanical alternatives. Shipyards in Ålesund and Bergen attract green vessel R&D contracts through hydrogen-ready hybrid configurations.
Germany
Foundries in northern Germany produce cavitation-resistant nickel-aluminum-bronze propellers with extended service intervals. The KBA and federal maritime regulators align with EU MRV monitoring frameworks that compel fleet operators toward electric configurations. The Hamburg industrial corridor concentrates thruster seal material redesigns for bio-compatible hydraulic fluid compatibility.
China
State-owned shipyards in Dalian and Shanghai scale production of integrated podded systems for domestic offshore support fleets. MIIT dual carbon goals pressure operators to specify electric propulsion architectures over conventional mechanical drivetrains. The Yangtze River Delta clusters permanent magnet motor manufacturing despite 18-month lead times for 10+ MW units.
Brazil
Drillship contractors in the pre-salt fields demand redundant thruster arrays rated 15+ MW per vessel for station-keeping operations. ANVISA and the national petroleum regulator coordinate environmental compliance that shapes vessel specification requirements. The Rio de Janeiro maritime services corridor concentrates dynamic positioning system integration for deepwater exploration blocks.
Singapore
Port authorities specify bollard pull certification for harbor tugs and escort vessels requiring rapid thrust vectoring. The Maritime and Port Authority aligns with IMO decarbonization mandates through green port initiatives. The Jurong ship repair cluster emerges as a secondary market for repurposed compact azimuth thrusters from decommissioned offshore supply vessels.
Azimuth Thrusters Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the azimuth thruster supply base. Integrated foundry-and-assembly operations in Norway and Germany control proprietary nickel-aluminum-bronze casting techniques that extend propeller service intervals. Three archetypes dominate: full-system integrators with captive motor-drive technology, component specialists focused on hydrodynamic nozzle optimization, and service-network operators capturing aftermarket revenue through condition-monitoring contracts. Consolidation pressures favor acquisition of permanent magnet motor suppliers by thruster OEMs seeking to compress lead times.
Among Nordic integrated system providers, Brunvoll and Kongsberg occupy positions that exemplify the full-stack archetype, combining foundry operations with electrical system integration. Wärtsilä Corporation represents the scale-driven multinational tier with manufacturing footprints spanning multiple regulatory jurisdictions. These three anchors demonstrate how geographic clustering around Bergen and Oslo correlates with regulatory proximity to IMO headquarters and EU maritime policy centers.
| Leading Market Players |
|---|
| Brunvoll |
| IHI |
| SCHOTTEL Group |
| Steerprop |
| Thrustmaster |
| Rolls-Royce |
| Kongsberg |
| Wärtsilä Corporation |
| ABB Marine |
| Others |
Supply Flow & Price Mechanics
Performance-tier divergence between IMO Tier III-certified electric thrusters and conventional mechanical units manifests in both pricing premiums and supply chain fragmentation. Certification-grade stratification concentrates high-value production in Norwegian and German foundries with captive nickel-aluminum-bronze casting capabilities, while commodity mechanical assemblies migrate to emerging-market shipyards with limited electrical infrastructure.
Pricing Analysis
Margin tightening in the electric thruster tier reflects permanent magnet motor supply concentration in China and Germany. Three-tier pricing structure across IMO-certified premium, CE-marked standard, and uncertified economy levels tracks certification burden and after-sales service bundling. Cost-down pressure on mechanical alternatives accelerates as Brazilian and West African drillship contractors specify redundant electric arrays. Offshore support operators show lowest price sensitivity due to dynamic positioning downtime costs; commercial ferry fleets under EU retrofit grants exhibit highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with permanent magnet motor production clustered in China's Yangtze River Delta and Germany's industrial corridor. Nickel-aluminum-bronze propeller casting draws from Norwegian and Finnish foundries; high-voltage drive electronics sources from German and Chinese suppliers. Tariff exposure on copper-nickel alloy imports squeezes OEM margins under fixed-price shipyard contracts. Distribution runs through integrated OEM service networks in Bergen, Hamburg, and Singapore rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around captive motor-drive technology and foundry-integrated operations as permanent magnet supply shortages and IMO certification timelines force out component-assemblers without backward integration into propeller casting.
For Market Incumbents: Lock in long-term service contracts with North Sea offshore operators through condition-monitoring platforms that predict thruster wear before failure. Acquire or joint-venture with permanent magnet motor suppliers to compress 18-month lead times that currently constrain 10+ MW electric thruster output. Defend against emerging Chinese podded-system competitors by embedding proprietary nozzle hydrodynamics into DNV type-approval protocols.
For New Entrants and Emerging Players: Digital-channel route through cloud-based thruster health analytics offers lowest barrier to incumbent service networks. Target Greek and Cypriot tanker fleets that lag condition-based maintenance adoption due to lower digital infrastructure investment. Pursue EU Green Deal maritime funding coverage for electric retrofit engineering on vessels under 5,000 gross tons.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-system integrators seeking captive foundry capacity. Five-to-ten-year viability favors targets with proven nickel-aluminum-bronze casting techniques and established DNV or Lloyd's Register type-approval records. Watch hydrogen bunkering infrastructure deployment at Norwegian ports as signal for fuel-cell shore-power integration demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Supply Agreement | Secures 10+ MW electric thruster production capacity against 18-month lead time constraints. |
| DNV Type-Approval Investment | Accelerates commercialization timelines for novel nozzle geometries from 36 months toward 24. |
| Condition-Monitoring Platform Launch | Captures per-operational-hour service revenue from Norwegian offshore vessel operators. |
| Hydrogen-Ready Hybrid Configuration | Positions for EU Green Deal funding and Norwegian port hydrogen bunkering infrastructure. |
| Nickel-Aluminum-Bronze Foundry Acquisition | Integrates 40% service interval extension technology into captive manufacturing. |
Methodological Framework
Document review covered Lloyd's Register and DNV classification society filings, EU MRV monitoring framework submissions, and IMO Tier III compliance databases, complemented by interviews with offshore vessel fleet managers, shipyard procurement directors, thruster OEM technical leads, and permanent magnet motor supply chain managers. Secondary validation drew from Norwegian Maritime Authority enforcement records, Brazilian ANVISA environmental compliance filings, and Chinese MIIT dual carbon policy documentation. Bottom-up thruster unit demand estimates triangulated against top-down offshore exploration capex projections.
Cross-reference between historical installation data and panel input from shipyard electrical contracting teams shaped the analytical framework across the analysis window. Segmentation dimensions modeled include propulsion architecture type, end-user vessel category, installation timing, and operational application duty cycle. CAGRs derived from unit shipment trajectories weighted by permanent magnet motor supply constraints and classification society certification pipeline status. Forecast inputs incorporated nickel-aluminum-bronze alloy price indices and hydrogen bunkering infrastructure deployment schedules.
Inputs from classification society type-approval registries were available through the study window; gaps in real-time shipyard order book visibility introduce uncertainty bands around retrofit volume assumptions. Forecasts reflect documented assumptions regarding IMO enforcement timelines and permanent magnet motor supply expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
North Sea Offshore Support Vessels Market
Marine
Marine Electronics Market
Marine
Pneumatic Marine Fender Market
Marine
Marine Shackle Market
Marine
Marine Turbocharger Market
Marine
Ship Rudders Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Marine Bearings Market
Marine
Boat Ladder Market
Marine
Marine Fender Systems Market
Marine
Recreational Vessel Battery Market
Marine
Marine Stabilizers Market
Marine
Marine VFD Market
Marine
Marine Fin Stabilizer Market
Marine
Marine Winch Motors Market
Marine
Singapore Container Transshipment Market