
 Marine Transport Refrigeration Unit Market | 2026-2036
Marine Transport Refrigeration Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Transport Refrigeration Unit Market Analytics
Chinese reefer container manufacturing capacity is expanding to meet surging export demand for temperature-controlled shipping. Carrier Transicold leverages its integrated systems portfolio to anchor long-term service contracts with major shipping lines. Daikin competes on compressor efficiency and low-GWP refrigerant leadership across Asian trade routes. Mitsubishi Heavy Industries sustains its position through specialized naval and commercial marine climate systems with rigorous salt-corrosion engineering.
Marine transport refrigeration units are engineered climate systems designed to maintain precise temperature, humidity, and atmospheric conditions within intermodal containers and vessel holds, typically operating across ranges from minus 30 degrees Celsius to plus 30 degrees Celsius depending on cargo requirements. These systems employ vapor compression or direct expansion cycles with marine-grade coatings to protect against salt spray, vibration, and extended operational cycles in open-ocean environments. Reefer containers dominate unit volume due to standardization across global shipping fleets, while integrated systems command premium positioning through factory-installed hold configurations on specialized vessels. Direct expansion technology leads in retrofit applications where space constraints limit cascade system installation, though vapor compression retains widest adoption for new-build reefer fleets.
The International Maritime Organization enforces carbon intensity indicators that compel fleet operators to document and reduce refrigerant leakage rates, directly shaping procurement specifications for new marine refrigeration units. EPA SNAP program restrictions on high-GWP hydrofluorocarbons in the United States parallel EU F-Gas Regulation phase-down schedules, creating dual-compliance pressure for transoceanic carriers operating across both jurisdictions. Stakeholders must monitor refrigerant transition timelines and certify technician training pipelines before regulatory deadlines tighten market access for legacy equipment categories.
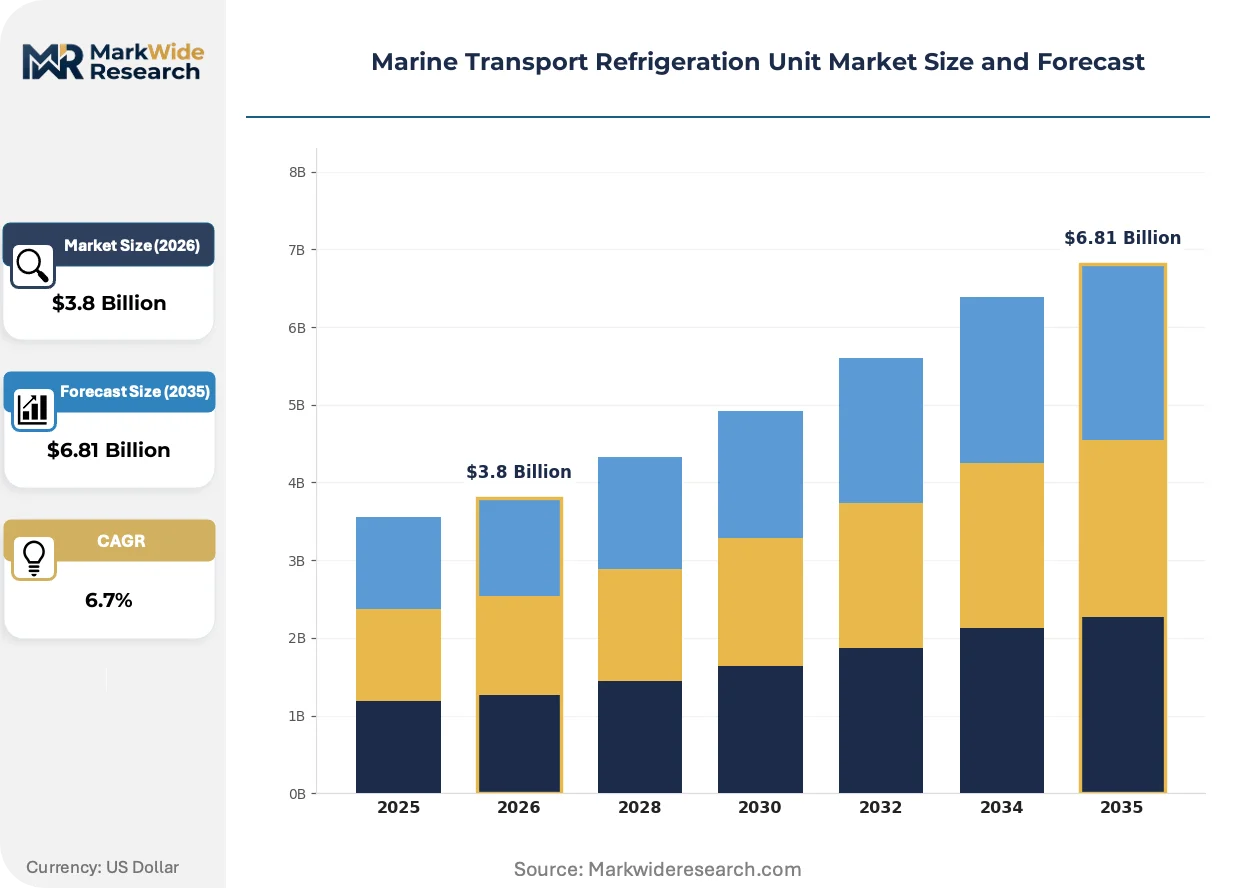
Market Dynamics
The International Maritime Organization's carbon intensity indicators and refrigerant phase-down mandates are compressing replacement cycles and forcing carriers to pre-commit capital to low-GWP fleet retrofits ahead of regulatory deadlines.
Growth Catalysts
- EU F-Gas Regulation phase-down:The European Union's staged hydrofluorocarbon reduction creates predictable replacement demand for reefer containers operating on transatlantic routes. Fleet operators must document leakage rates and accelerate unit turnover to maintain port access.
- Biologics cold-chain expansion:Temperature-sensitive pharmaceutical cargo now commands dedicated reefer allocations on major shipping lines. Vaccine and cell-therapy distribution requirements tighten temperature-band tolerances to plus-or-minus two degrees Celsius.
- China port infrastructure investment:Qingdao, Shanghai, and Ningbo-Zhoushan container terminal expansions incorporate electrified reefer plug infrastructure. Export-oriented food processing clusters in Shandong and Guangdong provinces drive concentrated procurement of forty-foot high-cube reefer units.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and compressor housing materials face commodity market swings that compress manufacturer margins and trigger quarterly price adjustment clauses in long-term supply agreements.
- Compressor supply concentration:Scroll and semi-hermetic compressor production clusters in Germany and Japan create vulnerability to single-source dependencies for marine-rated units with salt-spray certification.
- Technical limitation in ammonia systems:Toxicity classification and crew safety protocols prevent ammonia-based refrigeration from penetrating containerized shipping despite superior thermodynamic efficiency in stationary cold storage.
Strategic Opportunities
- India pharmaceutical export corridor:Cold-chain infrastructure gaps between Mumbai and Mundra ports create demand for integrated reefer monitoring systems. DGFT export incentive schemes support temperature-controlled logistics investments.
- CO2 transcritical technology convergence:Subcritical cascade and transcritical direct expansion architectures merge for container applications above minus twenty degrees Celsius. R-744 systems eliminate synthetic refrigerant compliance costs entirely.
- Telematics-enabled service contracts:Real-time container monitoring platforms allow manufacturers to unbundle hardware from performance-guaranteed uptime agreements. Shipping lines convert capex to opex while transferring operational risk.
Industry Challenges
- Marine refrigeration technician certification:EPA Section 608 and EU F-Gas certification timelines lag fleet retrofit schedules. Training pipeline capacity constraints delay installation crews for low-GWP system rollouts.
- Retrofit integration complexity:Legacy reefer container chassis from the 2010-2015 build wave require structural modification to accommodate larger CO2 heat exchangers and high-pressure piping runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Transport Refrigeration Unit Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reefer Containers, Portable Units, Integrated Systems, Split Systems Technology: Direct Expansion, Vapor Compression, Cascade, Absorption End User: Shipping Lines, Freight Forwarders, Logistics Providers, Food Distributors Application: Food Transport, Pharmaceutical Shipping, Chemical Storage, Blood Transport |
| Companies Covered | Daikin, Mitsubishi Heavy Industries, Carrier Transicold, Webasto, Klinge Corporation, SEA Mark Reefer Solutions, Guchen Thermo, Heinen & Hopman, DOMETIC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Transport Refrigeration Unit Market Evolving Landscape
Digital monitoring platforms and synthetic refrigerant alternatives are compressing the traditional ten-year reefer replacement cycle while elevating performance guarantees to contractual centerpieces.
Predictive maintenance algorithms using vibration and refrigerant pressure telemetry are automating service dispatch and parts pre-positioning. Major shipping lines now mandate IoT-enabled units on new-build orders. Container fleet operators reduce unplanned downtime by shifting from calendar-based to condition-based maintenance intervals.
EPA SNAP program restrictions on high-GWP hydrofluorocarbons parallel EU F-Gas Regulation enforcement timelines. Transoceanic carriers face dual-compliance pressure when operating across both jurisdictions. Refrigerant transition deadlines compress procurement windows as operators avoid stranded asset risk on legacy R-404A and R-134a systems.
Pharmaceutical shippers now require continuous temperature documentation with blockchain-verified chain-of-custody records. Container lessors respond by embedding multi-sensor data loggers with cellular satellite backup. This specification escalation concentrates demand on premium reefer categories equipped with redundant power and communication systems.
Marine Transport Refrigeration Unit Market Segmentation
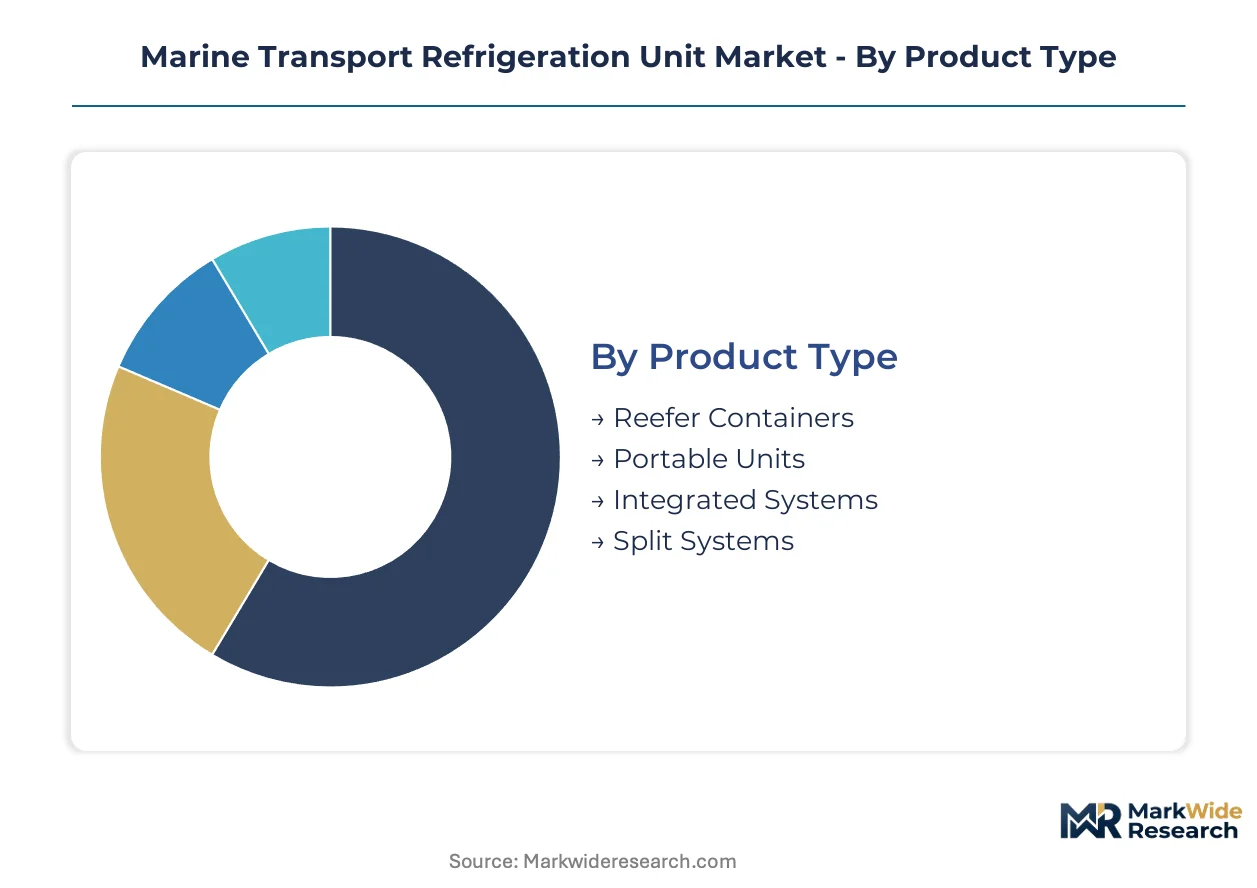
Marine transport refrigeration unit procurement patterns diverge sharply across product architectures, cooling technologies, and cargo categories. Segment boundaries determine pricing tiers, regulatory compliance pathways, and aftermarket service attachment rates for manufacturers and fleet operators alike.
Product Type:
Supply concentration in reefer container manufacturing clusters around Chinese port cities, where vertical integration from compressor assembly to container fabrication compresses lead times and unit economics.
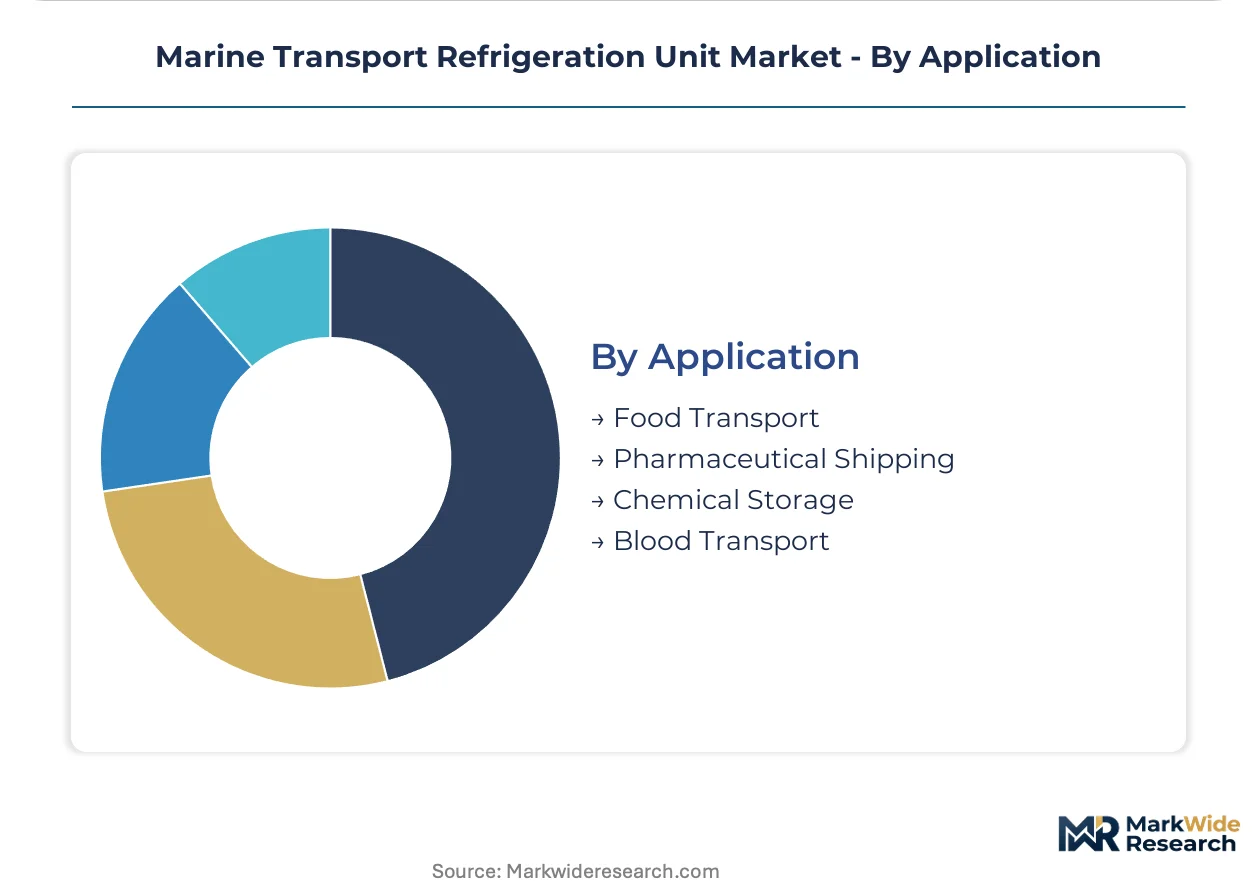
- Reefer Containers:Standardized forty-foot and twenty-foot intermodal units with built-in compressor decks and electric power interfaces. Demand concentrates in Shanghai, Qingdao, and Ningbo-Zhoushan terminal expansions where electrified plug infrastructure supports fleet electrification mandates.
- Portable Units:Modular clip-on refrigeration decks for dry container retrofits and temporary cold storage. Pharmaceutical distributors in Mumbai and Mundra deploy these for lane-testing before committing to dedicated reefer fleet investments.
- Integrated Systems:Factory-installed hold configurations for specialized vessels with multi-zone climate control.
- Split Systems:Separated compressor and evaporator arrangements for space-constrained deck layouts.
Reefer containers absorb the bulk of installed capacity; portable units are expanding most quickly.
Technology:
Cost tier differentiation separates established vapor compression architectures from emerging low-GWP alternatives requiring specialized technician certification and component sourcing.
- Vapor Compression:Dominant thermodynamic cycle using synthetic refrigerants in hermetic and semi-hermetic compressor configurations. EPA SNAP and EU F-Gas phase-down schedules force refrigerant transitions from R-404A to R-452A blends, compressing replacement cycles.
- Direct Expansion:Refrigerant-fed evaporators without secondary coolant loops, preferred for retrofit applications where space constraints limit cascade system installation. Cold-chain logistics providers favor these for rapid deployment on aging chassis.
- Cascade:Staged refrigeration using two distinct working fluids for ultra-low temperature applications.
- Absorption:Heat-driven cooling cycles utilizing waste heat from vessel engines, limited by thermal efficiency constraints.
Vapor compression retains the largest installed base; direct expansion is gaining share fastest in retrofit-heavy procurement cycles.
End User:
Customer type determines contract structure, with shipping lines demanding performance-guaranteed uptime agreements while freight forwarders prioritize capital flexibility.
- Shipping Lines:Container fleet owners specifying IoT-enabled units with predictive maintenance telemetry. Maersk, MSC, and CMA CGM mandate blockchain-verified temperature documentation for pharmaceutical cargo lanes.
- Freight Forwarders:Non-asset logistics providers leasing reefer capacity on demand, converting capex to opex through container lessor relationships.
- Logistics Providers:Integrated cold-chain operators managing multi-modal temperature-controlled distribution.
- Food Distributors:Export-oriented processors in Shandong and Guangdong provinces procuring forty-foot high-cube units for seafood and produce shipments.
Shipping lines command the largest order volumes; logistics providers are scaling fastest through telematics-enabled service contract adoption.
Application:
Application-driven specifications tighten temperature-band tolerances and redundant system requirements, elevating unit costs and service intensity.
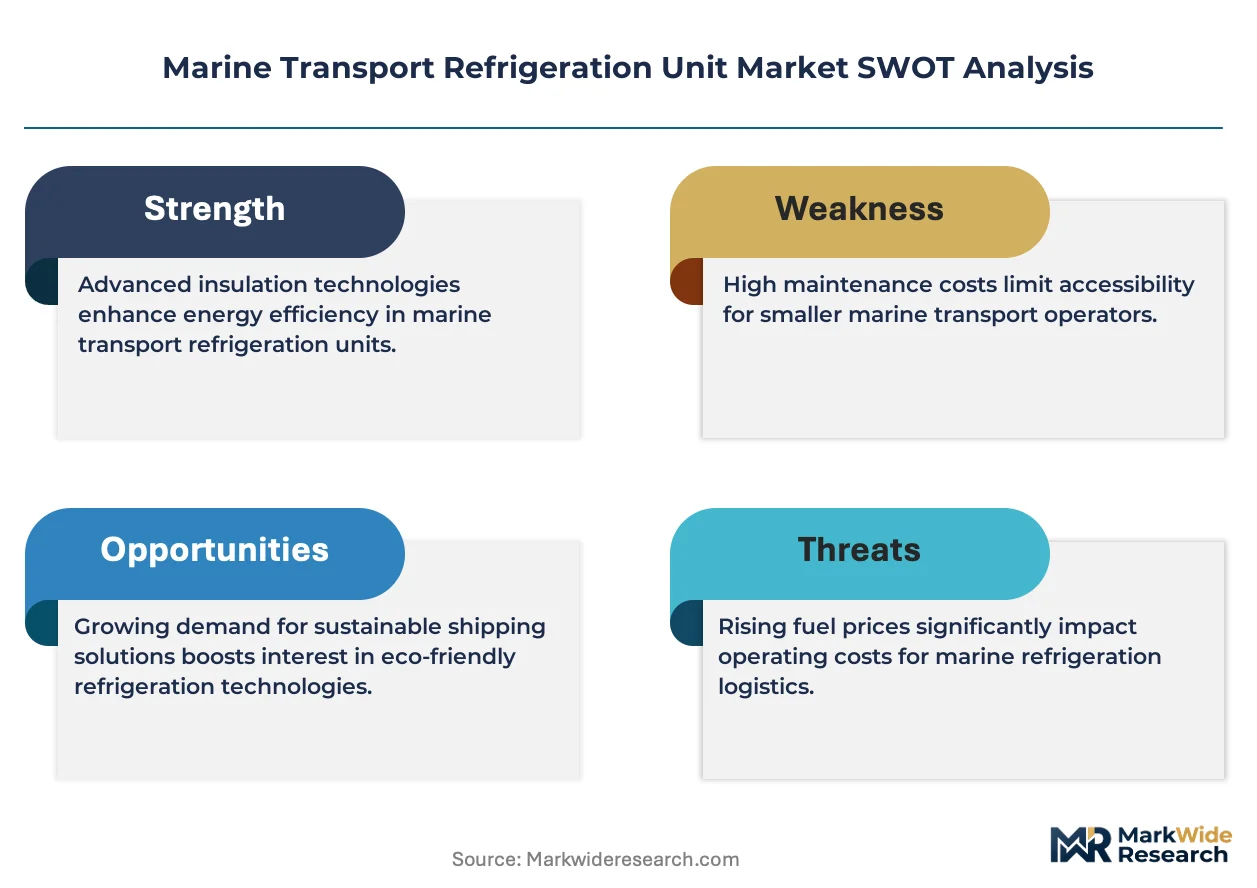
- Food Transport:Temperature ranges from minus thirty to plus thirty degrees Celsius for frozen, chilled, and controlled-atmosphere cargo. Chinese export processors drive concentrated demand for high-cube reefer units with modified atmosphere capabilities.
- Pharmaceutical Shipping:Plus-or-minus two degrees Celsius tolerance requirements for vaccines, biologics, and cell therapies. FDA and EMA distribution guidelines mandate continuous monitoring with cellular satellite backup.
- Chemical Storage:Hazardous material classifications requiring explosion-proof electrical enclosures and specialized refrigerant containment.
- Blood Transport:Narrow temperature bands with emergency backup power systems for medical supply chains.
Food transport accounts for the greatest unit deployment; pharmaceutical shipping follows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum sourcing corridors in Chile and Indonesia anchor heat exchanger supply chains for marine refrigeration manufacturing clusters. Port electrification investments and cold-chain infrastructure buildouts concentrate demand across four strategic markets.
China
Qingdao, Shanghai, and Ningbo-Zhoushan container terminal expansions incorporate electrified reefer plug infrastructure. MEE dual carbon goals accelerate fleet turnover toward low-GWP refrigerant systems. Export-oriented food processing clusters in Shandong and Guangdong provinces drive concentrated procurement of forty-foot high-cube reefer units.
Germany
Scroll and semi-hermetic compressor production clusters serve marine-rated units with salt-spray certification requirements. EU F-Gas Regulation phase-down schedules force refrigerant transitions from R-404A to R-452A blends. Hamburg and Bremerhaven port authorities mandate leakage rate documentation for reefer fleet access.
United States
EPA SNAP program restrictions on high-GWP hydrofluorocarbons parallel EU enforcement timelines for transoceanic carriers. FDA distribution guidelines tighten temperature-band tolerances for pharmaceutical cargo. Port infrastructure investments in Los Angeles and Savannah support electrified reefer plug deployment.
India
Cold-chain infrastructure gaps between Mumbai and Mundra ports create demand for integrated reefer monitoring systems. DGFT export incentive schemes support temperature-controlled logistics investments. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat anchor biologics cold-chain expansion.
Japan
METI energy efficiency standards shape compressor design specifications for marine applications. Specialized naval and commercial marine climate systems require rigorous salt-corrosion engineering protocols. Industrial concentrations in Nagoya and Osaka sustain precision manufacturing capabilities for vessel-integrated refrigeration.
Marine Transport Refrigeration Unit Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telematics-enabled service contract differentiation. The vendor base spans integrated systems specialists, compressor technology leaders, and container-focused fabricators with regional manufacturing footprints. Three archetypes dominate: diversified climate-control conglomerates, marine-specialized engineering houses, and container OEM-integrated component suppliers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as refrigerant transition deadlines compress procurement windows.
Among diversified climate-control conglomerates, Daikin and Mitsubishi Heavy Industries exemplify scale-driven positioning across Asian trade routes. Carrier Transicold anchors the integrated systems tier through service contract relationships with major shipping lines. These three entities represent distinct strategic postures: compressor efficiency leadership, specialized marine engineering capabilities, and fleet-wide performance guarantee structures.
| Leading Market Players |
|---|
| Daikin |
| Mitsubishi Heavy Industries |
| Carrier Transicold |
| Webasto |
| Klinge Corporation |
| SEA Mark Reefer Solutions |
| Guchen Thermo |
| Heinen & Hopman |
| DOMETIC Group |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply for low-GWP refrigerant systems and reserve premium-tier pricing access for OEMs with certified technician training pipelines and documented leakage-rate compliance. Carrier Transicold and Daikin leverage these certification barriers to unbundle hardware from performance-guaranteed service contracts, converting shipping line capex to recurring opex while compressing margin pressure on non-certified competitors.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium reefer units from commodity hardware, with IoT-enabled uptime guarantees commanding contract premiums over standard manufacturer warranties. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service attachment rates. Pricing pressure stems from copper and aluminum commodity volatility compressing heat exchanger margins. Freight forwarders exhibit highest price sensitivity through lease-rate negotiations, while pharmaceutical shippers prioritize temperature-band compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale shipping line demand, while specialized distributors serve retrofit and portable unit segments. Manufacturing concentration centers on China, Germany, and Japan for compressor assembly and salt-spray-certified marine components. Heat exchanger production draws from Chilean copper and Indonesian aluminum sourcing corridors. Single-source vulnerability in scroll compressor supply from German and Japanese production clusters creates procurement risk. Distribution runs through container OEM-integrated channels and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine transport refrigeration market sits in a refrigerant technology-transition phase, with CO2 transcritical systems displacing legacy R-404A and R-134a vapor compression architectures across new-build reefer fleets.
For Market Incumbents: Acquire telematics platform capabilities to anchor performance-guaranteed service contracts and defend against emerging IoT-native entrants. Backward integration into compressor salt-spray certification capabilities secures supply continuity against German and Japanese single-source dependencies. Invest in CO2 transcritical R&D to maintain technical leadership as EU F-Gas deadlines compress replacement cycles.
For New Entrants and Emerging Players: AI-driven predictive maintenance algorithms offer a technology-first wedge into the pharmaceutical shipping segment, where temperature-band compliance requirements exceed incumbent service capabilities. Target India's Mumbai-Mundra pharmaceutical export corridor, where cold-chain infrastructure gaps and DGFT incentive schemes create penetrable white space. Pursue telematics-enabled uptime guarantee contracts as the primary go-to-market angle.
For Investors and Strategic Acquirers: EPA SNAP program enforcement acceleration is the leading indicator that refrigerant transition timelines will compress procurement windows and strand legacy system inventories. The five-to-ten year viability window favors acquisition targets with certified low-GWP technician training pipelines and established shipping line service relationships. Monitor IMO carbon intensity indicator compliance rates as the critical inflection signal for fleet retrofit demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Technology Licensing | Eliminates synthetic refrigerant compliance costs under EU F-Gas and EPA SNAP regulations. |
| Predictive Maintenance Platform Integration | Enables condition-based service contracts with Maersk and MSC through IoT telemetry. |
| Backward Integration into Compressor Manufacturing | Reduces single-source dependency on German and Japanese salt-spray-certified suppliers. |
| Pharmaceutical Cold-Chain Certification Investment | Secures plus-or-minus two degrees Celsius compliance for vaccine and biologics distribution. |
| India Distribution Channel Expansion | Captures DGFT-supported logistics investments between Mumbai and Mundra port corridors. |
Research Methodology
Independent corroboration across reefer container fleet operators, compressor OEM procurement teams, and cold-chain logistics executives underwrites the qualitative findings in this study. Primary interviews with shipping line technical directors, marine refrigeration service technicians, and port authority infrastructure planners combined with secondary validation from IMO regulatory filings, EPA SNAP program documentation, and EU F-Gas implementation reports. Customs trade data for reefer container imports and compressor component shipments anchored supply-side sizing. Bottom-up unit economics triangulated against top-down fleet penetration estimates across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, cooling technology, and end-user segments. The analytical framework modeled reefer container versus portable unit deployment, vapor compression versus direct expansion technology share, and shipping line versus freight forwarder procurement patterns throughout the forecast period. CAGRs derived from regression-based trend extrapolation adjusted for regulatory deadline clustering and fleet replacement cycle compression. Industry-specific forecast inputs incorporated IMO carbon intensity indicator compliance trajectories and pharmaceutical cold-chain infrastructure buildout schedules.
Several conditions sit outside the modeled scope, including geopolitical trade disruption affecting Chilean copper and Indonesian aluminum supply corridors, and accelerated ammonia toxicity reclassification permitting containerized shipping adoption. Forecasts reflect base-case assumptions regarding refrigerant transition timeline adherence and technician certification pipeline expansion. Periodic stress-testing of base assumptions is recommended against IMO enforcement variance and commodity price volatility scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Offshore AUV and ROV Market
Marine
Trim Tabs Market
Marine
Marine Fasteners Market
Marine
Electric Outboard Engines Market
Marine
Marine Navigation System Market
Marine
Ship Rudders Market
Marine
Integrated Bridge System for Ships Market
Marine
Sliding Fender Market
Marine
Boat Cleat Market
Marine
Buoys and Beacon Market
Marine
Marine Chronometers Market
Marine
Furnace Boats Market
Marine
Rescue Boats Market
Marine
Marine Communication Market
Marine
LNG Bunkering Vessel Market
Marine
Boat Console Market