
 Marine Turbocharger Market | 2026-2036
Marine Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Turbocharger Market Intelligence
Performance-based maintenance contracts is realigning how marine turbocharger suppliers capture lifetime value from vessel operators. MAN Energy Solutions leverages its integrated service network to anchor long-term aftermarket revenue across European and Asian fleets. Mitsubishi Heavy Industries Marine Machinery & Equipment sustains manufacturing scale through captive supply to Japanese shipyards. ABB Turbocharging competes on digital diagnostics platforms that reduce unplanned downtime for container line customers.
A marine turbocharger is a forced-induction device that recovers exhaust gas energy to compress intake air, typically achieving pressure ratios of 3.5:1 to 5.5:1 in large two-stroke marine diesel engines, thereby increasing power density and reducing specific fuel oil consumption per kilowatt-hour. Its primary commercial purpose is enabling compliance with International Maritime Organization emission standards while maintaining propulsion efficiency on ocean-going vessels. Exhaust gas turbochargers occupy the dominant share of installed base due to mechanical simplicity and proven reliability on slow-speed engines. Electric turbochargers represent the fastest-growing product category as ship operators retrofit auxiliary power recovery systems. Two-stage turbocharging technology commands premium positioning where high-pressure ratios are required for dual-fuel engine architectures.
The International Maritime Organization enforces nitrogen oxide and sulfur oxide emission limits through MARPOL Annex VI, directly mandating turbocharger efficiency upgrades as a compliance pathway for existing fleets. The EU Green Deal extends these requirements for vessels calling at European ports, while China's Ministry of Ecology and Environment implements parallel domestic standards through its GB marine engine emission regulations. Classification societies including Lloyd's Register and DNV refine type-approval testing protocols that determine which turbocharger designs qualify for newbuild installations. Stakeholders must monitor how ammonia and methanol fuel transitions reshape compressor mapping requirements and material specifications for next-generation turbocharger platforms.
Market Dynamics
Two-stage turbocharging architecture is forcing a fundamental reconfiguration of supplier capabilities as ship operators pursue dual-fuel engine retrofits to meet tightening IMO emission mandates. Compressor mapping requirements for ammonia and methanol combustion cycles are compressing the viable supplier base toward integrated system providers with in-house casting and precision machining capacity.
Growth Catalysts
- IMO MARPOL Annex VI Phase III:Nitrogen oxide emission limits for newbuild vessels operating in emission control areas mandate turbocharger efficiency upgrades, creating retrofit demand across existing container and bulk carrier fleets.
- Two-stage turbocharging:High-pressure ratio architectures enable dual-fuel engine operation on methanol and ammonia, positioning early adopters for compliance with anticipated 2027 fuel standards.
- Chinese shipbuilding concentration:Yards in Shanghai, Dalian, and Guangzhou anchor procurement volumes for newbuild turbocharger installations, concentrating demand within state-backed vessel construction programs.
Market Restraints
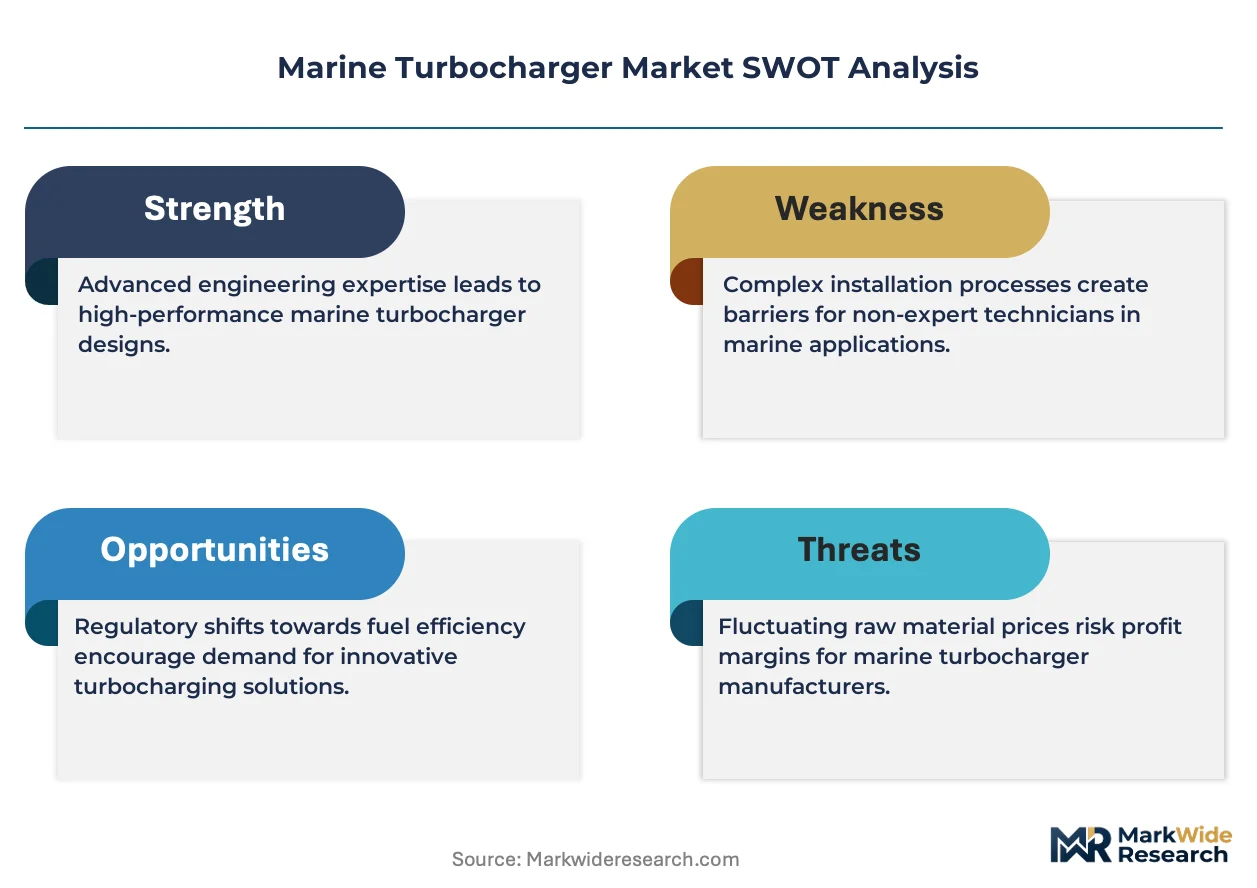
- Superalloy input volatility:Inconel and titanium aluminide prices fluctuate with aerospace demand cycles, compressing margin predictability for precision turbine wheel castings.
- Japanese supplier concentration:Captive supply relationships between Mitsubishi Heavy Industries and domestic shipyards limit third-party access to premium newbuild contracts in the region.
- Electric turbocharger technical limitation:Power density constraints in marine auxiliary applications restrict deployment to vessels above specific deadweight thresholds, excluding coastal and feeder segments.
Strategic Opportunities
- Vietnam and Indonesia shipbuilding:Emerging yards in Haiphong and Batam lack established supplier relationships, creating entry points for European and Korean turbocharger manufacturers with localized service networks.
- EU Green Deal port compliance:Vessels calling at Rotterdam, Hamburg, and Antwerp face supplementary emission verification requirements, accelerating demand for turbocharger performance monitoring and certification services.
- Digital diagnostics convergence:Integration of vibration sensors with cloud-based compressor mapping algorithms enables predictive maintenance contracts that capture lifetime aftermarket value from container line operators.
Industry Challenges
- Thermofluids simulation expertise:Shortage of engineers capable of modeling transient compressor surge behavior in dual-fuel combustion environments delays product development cycles for next-generation turbocharger platforms.
- DNV and Lloyd's Register type-approval timelines:Extended certification protocols for ammonia-compatible material specifications compress new product launch windows and extend capital lockup periods.
- Legacy engine integration complexity:Retrofit installations on slow-speed two-stroke engines built before 2010 require custom adapter castings and control system modifications, fragmenting project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Turbocharger Market |
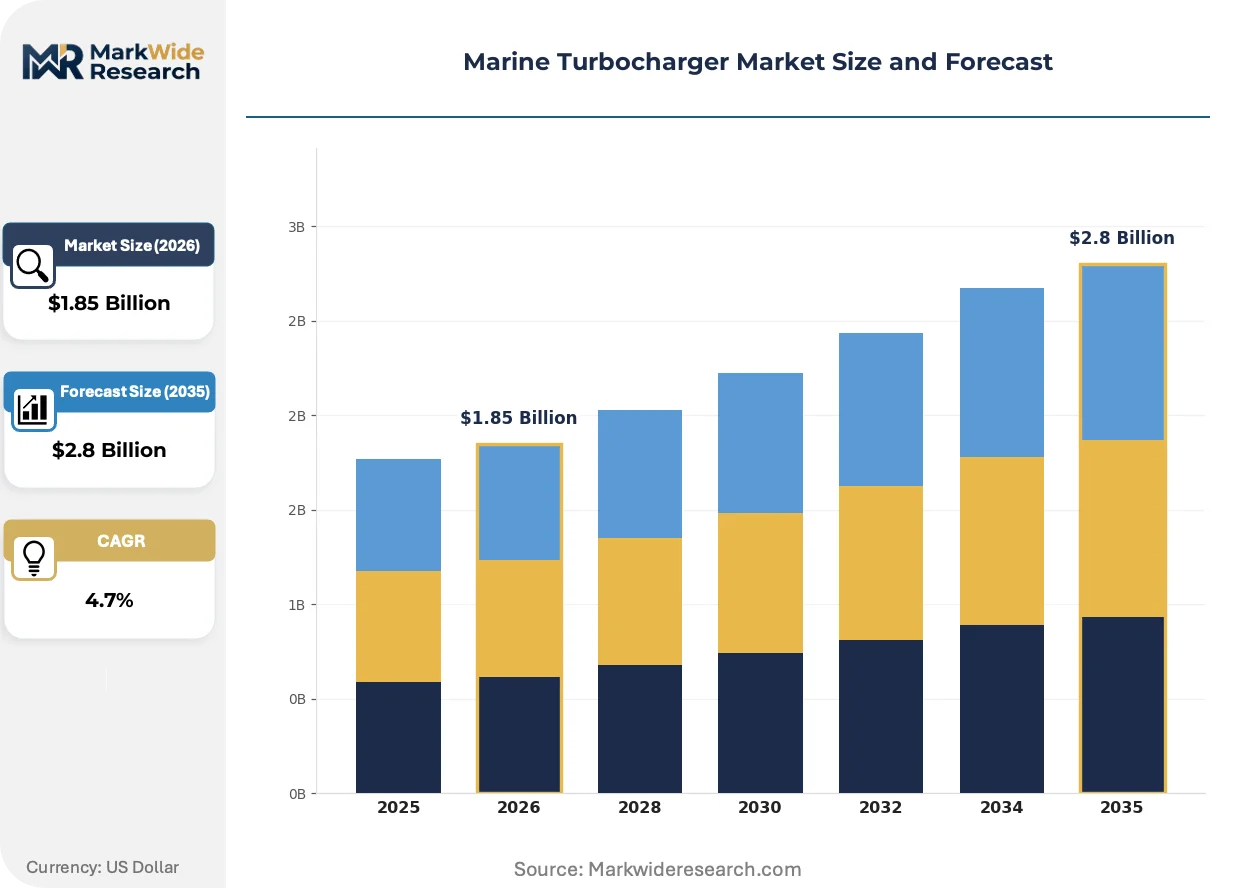
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Gas Turbochargers, Electric Turbochargers, Variable Geometry Turbochargers, Radial Turbos, Axial Turbos Technology: Single-Stage Turbocharging, Two-Stage Turbocharging, Electric Assisted Turbocharging, Sequential Turbocharging, Mixed-Flow Turbocharging Application: Container Ships, Bulk Carriers, Tankers, Offshore Supply Vessels, Passenger Ferries End User: Shipyards, Marine Engine Manufacturers, Vessel Operators, Maintenance Service Providers |
| Companies Covered | MAN Energy Solutions, Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd., ABB Turbocharging, Cummins Inc., BorgWarner Turbo Systems, Napier Turbochargers Ltd., Rolls-Royce Power Systems, Kawasaki Heavy Industries, Ltd., Kompressorenbau Bannewitz GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Turbocharger Market Strategic Shifts & Innovations
Digitalization of compressor performance monitoring is compressing maintenance intervals and enabling new service revenue models. Material science advances in ceramic matrix composites and additive manufacturing are reshaping turbine wheel production economics.
Two-stage turbocharging is consolidating technical leadership among integrated marine propulsion suppliers. The architecture achieves pressure ratios exceeding 5.5:1 required for methanol and ammonia dual-fuel combustion. Container lines operating Asia-Europe routes are specifying two-stage systems on newbuild orders above 15,000 TEU capacity. This technology is consolidating aftermarket service relationships toward suppliers with proprietary compressor mapping databases and global technician networks.
The EU Green Deal extends MARPOL Annex VI requirements through its FuelEU Maritime initiative, mandating well-to-wake emission intensity reductions for vessels calling at European ports. Ship operators must document turbocharger efficiency contributions to overall propulsion system performance. Container segments with high port rotation frequency in Rotterdam, Antwerp, and Hamburg face the most acute compliance cost pressure and are prioritizing turbocharger upgrade programs.
Performance-based maintenance contracts are displacing traditional time-based service agreements among major container line operators. Turbocharger suppliers now guarantee availability metrics and absorb unplanned downtime risk through remote monitoring platforms. This model compresses supplier margins on initial hardware sales while extending revenue capture over vessel operational lifespans. European and Asian flag fleets with centralized technical management functions are adopting these contracts most aggressively.
Marine Turbocharger Market Segmentation
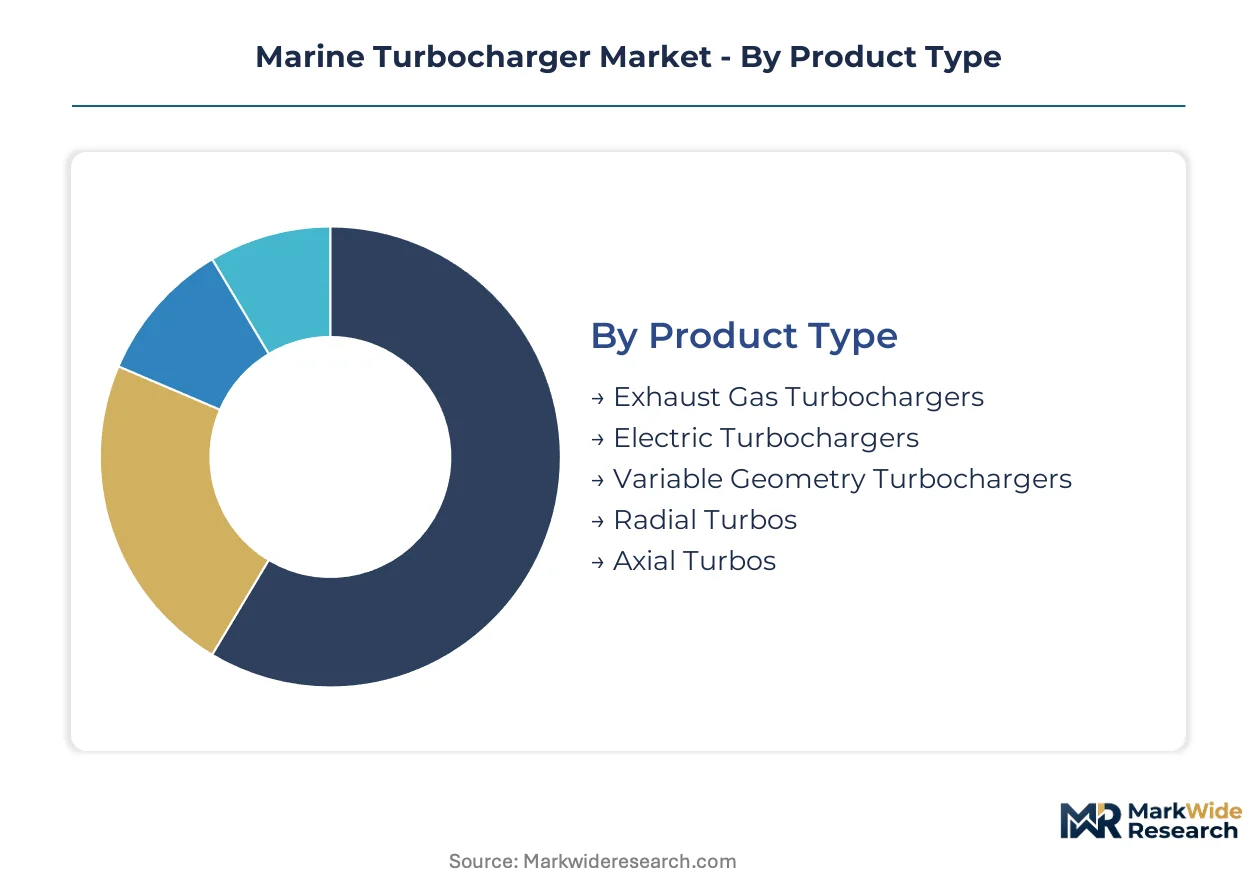
Marine turbocharger segmentation reveals how technology integration depth varies across vessel architectures and operational profiles. Procurement patterns diverge sharply between newbuild specifications and aftermarket retrofit programs.
Product Type:
Integration depth spans standalone mechanical systems through electrically hybridized architectures, with standalone units dominating legacy fleets and embedded electric systems capturing newbuild specifications.
- Exhaust Gas Turbochargers:Mechanical systems recover exhaust thermal energy through radial or axial turbine configurations, achieving pressure ratios of 3.5:1 to 5.5:1 on large two-stroke marine diesel engines. Demand concentrates in Chinese and South Korean shipyards for container ship newbuilds, driven by IMO MARPOL Annex VI Phase III compliance requirements for nitrogen oxide emission limits.
- Electric Turbochargers:Hybrid architectures integrate motor-generator units for auxiliary power recovery and transient boost compensation, enabling fuel efficiency gains in variable-load operations. Procurement clusters among European container lines operating Asia-Europe routes, constrained by power density limitations that restrict deployment to vessels above specific deadweight thresholds.
- Variable Geometry Turbochargers:Adjustable vane geometries optimize compressor performance across engine load ranges.
- Radial Turbos:Compact centrifugal compressor designs suit medium-speed four-stroke engines in auxiliary applications.
- Axial Turbos:Large-flow designs dominate slow-speed two-stroke propulsion engines above 60 MW output.
Volume placements concentrate in Exhaust Gas Turbochargers; the faster expansion belongs to Electric Turbochargers.
Technology:
Technology tiers reflect cost differentiation between established single-stage architectures and premium two-stage systems required for dual-fuel engine transitions.
- Single-Stage Turbocharging:Conventional designs deliver pressure ratios up to 4.5:1 through single compressor-turbine pairs, maintaining cost efficiency for standard marine diesel operations. Demand persists in Japanese shipyards through captive supply relationships with domestic turbocharger manufacturers, though growth is constrained by inability to meet methanol and ammonia combustion pressure requirements.
- Two-Stage Turbocharging:Cascaded low-pressure and high-pressure compressor stages achieve pressure ratios exceeding 5.5:1, enabling dual-fuel engine architectures for methanol and ammonia combustion cycles. Adoption concentrates among container lines specifying newbuild vessels above 15,000 TEU capacity on Asia-Europe routes, positioning operators for anticipated 2027 fuel standards.
- Electric Assisted Turbocharging:Motor-driven compressors supplement exhaust turbine output during low-load operations.
- Sequential Turbocharging:Multiple turbocharger stages activate progressively across engine speed ranges.
- Mixed-Flow Turbocharging:Hybrid compressor geometries balance efficiency and surge margin for variable-speed applications.
Cost leadership sits with Single-Stage Turbocharging; the steepest expansion trajectory belongs to Two-Stage Turbocharging.
Application:
Application segments map to vessel deployment patterns and regulatory exposure, with deep-sea routes facing the most stringent emission verification requirements.
- Container Ships:High-power propulsion systems above 40 MW require turbocharger pressure ratios above 4.5:1 for efficient slow-steaming operations. Procurement concentrates in Shanghai and South Korean shipyards, driven by EU Green Deal port compliance requirements for vessels calling at Rotterdam, Hamburg, and Antwerp.
- Bulk Carriers:Lower power density requirements and slower speed profiles accommodate simpler turbocharger configurations. Demand clusters in Chinese state-backed vessel construction programs, constrained by fragmented ownership structures that complicate centralized technical management and performance-based maintenance contract adoption.
- Tankers:Specialized safety requirements and cargo heating loads create distinct compressor mapping specifications.
- Offshore Supply Vessels:Dynamic positioning operations demand rapid transient response from turbocharger systems.
- Passenger Ferries:Coastal route restrictions and noise regulations favor compact, low-emission turbocharger designs.
Procurement volume clusters in Container Ships; the fastest share gains are occurring in Tankers as dual-fuel retrofits accelerate.
End User:
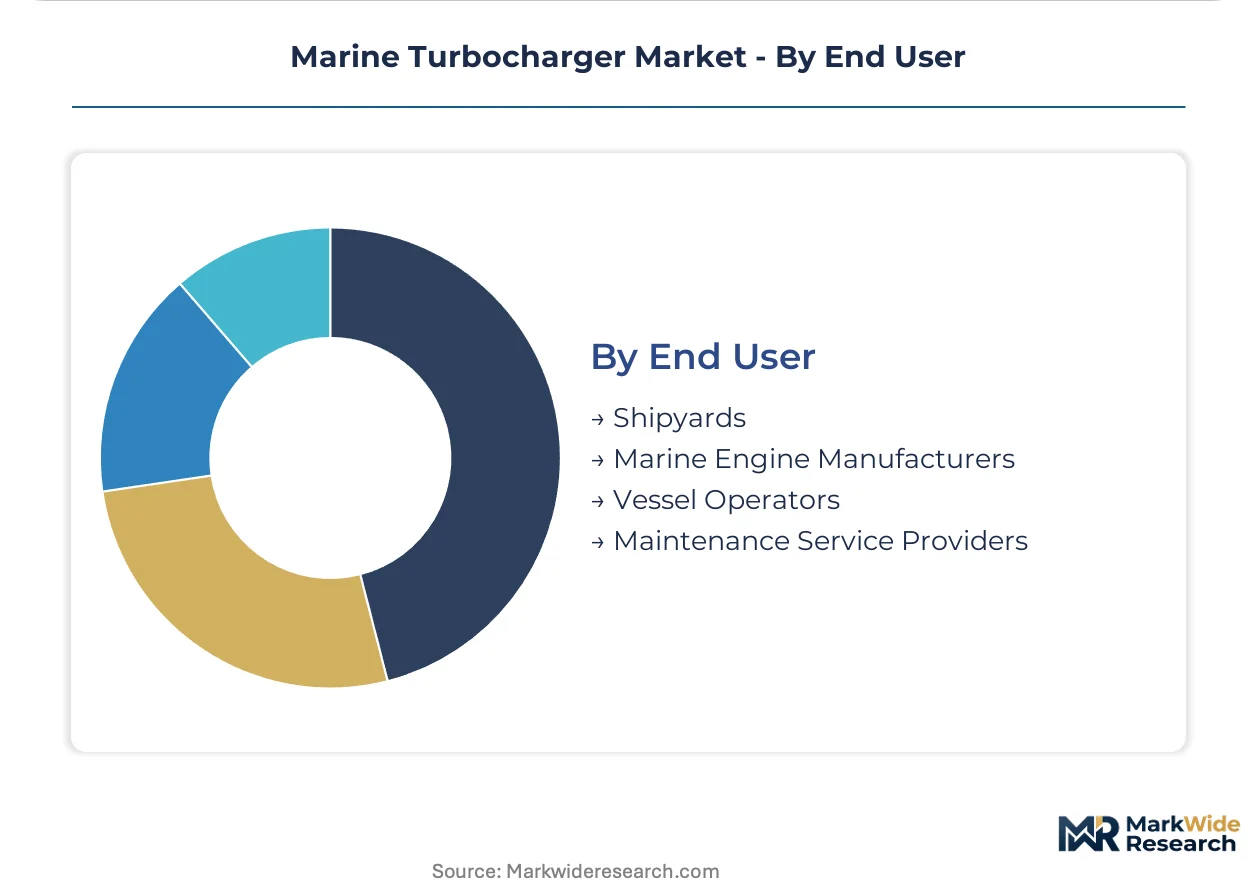
End user categories reflect divergent procurement authority and lifecycle value capture models across the vessel value chain.
- Shipyards:Newbuild specifications integrate turbocharger selection into overall propulsion system design, with procurement concentrated in Chinese, South Korean, and Japanese yards. Volume anchors in Shanghai, Dalian, and Guangzhou construction programs, though Japanese supplier concentration limits third-party access to premium contracts through captive supply relationships.
- Marine Engine Manufacturers:Integrated propulsion system providers specify turbocharger architectures as part of engine platform development. Demand clusters among European and Asian engine builders developing dual-fuel platforms for methanol and ammonia, requiring close collaboration on compressor mapping and material specifications.
- Vessel Operators:Retrofit upgrade decisions and aftermarket service contract negotiations shift procurement authority toward fleet technical managers.
- Maintenance Service Providers:Independent repair networks capture aftermarket revenue through component reconditioning and field service operations.
Contract value concentrates in Shipyards; the most rapid relationship expansion is occurring with Vessel Operators through performance-based maintenance agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Asian shipbuilding centers while European operators drive retrofit demand through port compliance mandates. Chinese and South Korean yards anchor newbuild turbocharger procurement volumes. Container lines and bulk carriers in Europe and North America generate aftermarket upgrade requirements.
China
State-backed vessel construction programs in Shanghai, Dalian, and Guangzhou anchor global newbuild turbocharger demand. The Ministry of Ecology and Environment enforces GB marine engine emission regulations that parallel IMO standards. Yangtze River Delta shipyards specify two-stage turbocharging systems for dual-fuel container vessels above 15,000 TEU.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive procurement for ultra-large container ships and LNG carriers. The Korean Register refines type-approval protocols for ammonia-compatible turbocharger materials. Ulsan and Geoje shipbuilding clusters concentrate newbuild installations with integrated propulsion system specifications.
Japan
Captive supply relationships between Mitsubishi Heavy Industries and domestic shipyards limit third-party access to premium contracts. METI coordinates national shipbuilding competitiveness initiatives targeting next-generation fuel transitions. Nagasaki and Kobe manufacturing clusters sustain precision casting capacity for turbine wheel production.
Germany
MAN Energy Solutions leverages its integrated service network to capture aftermarket revenue from European container fleets. The EU Green Deal FuelEU Maritime initiative mandates well-to-wake emission documentation for vessels calling at Hamburg and Bremerhaven. Engine research clusters in Augsburg and Hamburg drive compressor mapping development for methanol combustion cycles.
Singapore
The Maritime and Port Authority enforces supplementary emission verification for vessels bunkering in the world's largest transshipment hub. Ship repair yards in Tuas and Sembcorp anchor turbocharger retrofit activity for Asia-Europe container lines. Technical management centers coordinate performance-based maintenance contracts across regional fleets.
Marine Turbocharger Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the marine turbocharger value chain. Integrated marine propulsion suppliers with in-house casting and precision machining capacity capture premium two-stage system contracts. Three archetypes dominate: European engine-integrated providers, Japanese captive manufacturers, and independent turbocharger specialists. Competitive dynamics center on strategic partnerships for dual-fuel compressor development and geographic expansion through localized service networks.
Among European engine-integrated providers, MAN Energy Solutions and ABB Turbocharging occupy positions as archetypal integrated system suppliers. Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd. exemplifies the Japanese captive manufacturing model. These three companies represent distinct strategic postures: European players compete on digital diagnostics platforms and global service reach, while Japanese manufacturers sustain scale through domestic shipyard relationships.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd. |
| ABB Turbocharging |
| Cummins Inc. |
| BorgWarner Turbo Systems |
| Napier Turbochargers Ltd. |
| Rolls-Royce Power Systems |
| Kawasaki Heavy Industries, Ltd. |
| Kompressorenbau Bannewitz GmbH |
| Others |
Cost & Logistics Intelligence
IMO MARPOL Annex VI Phase III compliance gates qualified supply access and premium-tier pricing power, as only turbocharger architectures certified for nitrogen oxide emission limits command placement on newbuild vessels above 15,000 TEU. Shipyards in Shanghai and Ulsan restrict procurement to suppliers with validated compressor mapping databases, compressing the viable vendor base and sustaining margin premiums for integrated system providers.
Pricing Analysis
Margin tightening in two-stage turbocharging reflects superalloy input volatility and extended DNV type-approval timelines for ammonia-compatible materials. Three-tier pricing structure separates premium two-stage systems from standard single-stage architectures and economy radial configurations for auxiliary engines. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression accelerates in single-stage segments as Chinese shipyards consolidate procurement volumes. Bulk carrier operators exhibit highest price sensitivity; container lines operating EU port rotations show lowest sensitivity due to compliance-driven specification mandates.
Supply Chain Analysis
Precision casting engineer shortages in Nagasaki and Augsburg constrain turbine wheel production capacity for next-generation dual-fuel platforms. Manufacturing concentrates in Japan, Germany, and South Korea, with raw material sourcing drawing from Inconel suppliers in aerospace-linked supply chains and titanium aluminide feedstock from specialty foundries. Supply chain risk centers on single-source vulnerability for superalloy ingots qualified to Lloyd's Register material specifications. Distribution runs through shipyard-integrated procurement channels and engine manufacturer captive supply networks, with aftermarket service parts flowing through regional technical management centers in Singapore and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where IMO MARPOL Annex VI Phase III creates a barrier-to-entry moat, as certification investment requirements exceed capital access for non-integrated competitors.
For Market Incumbents: Acquire precision machining and superalloy casting assets to secure turbine wheel supply autonomy against aerospace demand cycles. Defensive consolidation should prioritize compressor mapping database expansion and DNV pre-certification of ammonia-compatible material specifications. MAN Energy Solutions and ABB Turbocharging anchor positions through integrated service networks; Mitsubishi Heavy Industries sustains scale via captive Japanese shipyard relationships.
For New Entrants and Emerging Players: EU Green Deal FuelEU Maritime port compliance requirements in Rotterdam and Hamburg open a window for digital diagnostics platform specialists to capture performance-based maintenance contracts from container line technical managers. White-space targets include Vietnam and Indonesia shipbuilding yards lacking established supplier relationships, and electric turbocharger retrofits for coastal feeder vessels above specific deadweight thresholds. Go-to-market positioning should emphasize localized technician networks and cloud-based compressor mapping algorithms.
For Investors and Strategic Acquirers: Two-stage turbocharger adoption rates on methanol-dual-fuel newbuilds above 15,000 TEU is the leading indicator that integrated system providers will consolidate aftermarket value capture. Long-term viability favors vertically integrated specialists with in-house casting capacity and proprietary compressor mapping databases. Acquisition target archetype: mid-scale turbocharger designers with DNV pre-certified ammonia material specifications and established service presence in Chinese or South Korean shipbuilding clusters. Monitor Lloyd's Register type-approval timeline compression as inflection signal for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Secures turbine wheel supply autonomy against aerospace demand volatility and Inconel price cycles. |
| DNV Pre-Certification for Ammonia Materials | Compresses type-approval timelines and accelerates product launch windows for dual-fuel platforms. |
| Digital Diagnostics Platform Deployment | Enables predictive maintenance contracts that absorb unplanned downtime risk for container line operators. |
| Localized Service Network Expansion | Captures aftermarket revenue from emerging Vietnamese and Indonesian shipbuilding yards lacking supplier relationships. |
| Performance-Based Maintenance Contract Structuring | Extends revenue capture across vessel operational lifespans while compressing initial hardware margins. |
Research Approach
Multi-period observation of turbocharger installation rates, shipyard order backlogs, and IMO compliance retrofit announcements anchored the trend analysis, supplemented by interviews with marine engine procurement directors, fleet technical managers at container lines, shipyard propulsion system engineers, classification society surveyors, and aftermarket service network heads. Secondary validation drew from Lloyd's Register type-approval registries, DNV maritime emission compliance databases, Korean Register certification filings, and customs trade data for superalloy component flows. Bottom-up vessel-by-vessel turbocharger specification tracking triangulated against top-down shipbuilding output projections.
Segment-weighting across product type, technology tier, vessel application, and end-user procurement authority structured the analytical framework. Modeled dimensions included exhaust gas versus electric turbocharger architectures, single-stage versus two-stage compression systems, container ship versus bulk carrier versus tanker deployments, and shipyard versus vessel operator versus engine manufacturer purchasing channels. CAGRs derived from regression analysis of historical installation volumes against projected newbuild output and regulatory compliance retrofit cycles, with specific inputs for methanol and ammonia dual-fuel engine adoption curves and EU Green Deal port compliance enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for electric turbocharger power density breakthroughs or accelerated ammonia fuel infrastructure rollout would alter the outlook. Forecasts reflect assumptions regarding IMO enforcement consistency, superalloy supply stability, and classification society certification timeline norms. Material deviation in MARPOL Annex VI Phase III implementation schedules, Lloyd's Register material specification changes, or Chinese shipbuilding subsidy policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Yacht Painting and Maintenance Market
Marine
Mooring Ropes Market
Marine
Sailboat Market
Marine
Integrated Bridge System for Ships Market
Marine
Jack-Up Vessels Market
Marine
Marine Shackle Market
Marine
Marine Trenchers Market
Marine
Electric Outboard Engines Market
Marine
Europe Recreational Boating Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
North Sea Offshore Support Vessels Market