
 Boat Ladder Market | 2026-2036
Boat Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Ladder Market Analytics
The EU Green Deal is pivoting marine equipment manufacturers toward low-carbon aluminum sourcing and solvent-free finishing processes. Besenzoni leverages Italian metalworking heritage to sustain premium positioning in yacht boarding systems. Windline anchors North American distribution through extensive dealer networks. TR INOX specializes in electropolished stainless steel ladders for saltwater environments.
A boat ladder is a mechanical access device comprising tubular or channel-section side rails with transverse rungs, typically fabricated from marine-grade aluminum alloy 6061-T6 or AISI 316 stainless steel, designed to enable safe personnel transfer between watercraft and water. Folding configurations dominate recreational installations due to compact stowage, while telescoping variants capture expanding demand from fishing vessels requiring adjustable reach. Aluminum material leads volume production for its strength-to-weight ratio, though stainless steel commands margin pools in commercial and yacht segments where corrosion resistance determines replacement cycles.
The US Coast Guard establishes minimum load-bearing and dimensional standards for boarding equipment on inspected vessels, while ISO 15085 governs welding quality in marine aluminum structures across export markets. CE marking requirements under the EU Marine Equipment Directive shape market access for European suppliers and importers. Stakeholders must monitor evolving corrosion-testing protocols and raw-material alloy specifications as regulatory bodies tighten performance benchmarks without harmonizing cross-border certification pathways.
Market Dynamics
Corrosion-resistant alloy specifications are compressing replacement cycles while recreational boaters in Florida and California drive specification upgrades. The EU F-Gas Regulation is forcing coating process retooling across European supply chains, creating divergent cost structures between regions.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates lower-emission coating processes, compelling manufacturers to retool finishing lines and creating first-mover advantages for compliant suppliers.
- Marine-grade aluminum alloy 6061-T6:This material delivers superior strength-to-weight ratios that recreational boaters prioritize for folding ladder configurations, sustaining volume demand.
- United States coastal states:Concentrated demand from Florida and California marinas is pulling specification upgrades toward electropolished finishes and extended load-bearing ratings.
Market Restraints
- Aluminum alloy price volatility:Raw material cost swings for marine-grade 6061-T6 compress margin pools for mid-tier fabricators without captive smelter relationships.
- ISO 15085 welding certification:The standard creates friction for small-batch producers seeking export market access, lengthening compliance timelines.
- Telescoping ladder mechanisms:Complex sliding joint designs face higher warranty exposure in saltwater environments, elevating total cost of ownership.
Strategic Opportunities
- Fishing vessel adjustable-reach configurations:Telescoping variants are capturing underserved demand from commercial operators requiring variable boarding heights.
- EU Green Deal low-carbon aluminum sourcing:The framework incentivizes primary metal suppliers to certify carbon footprints, creating premium positioning for compliant ladder manufacturers.
- Direct-to-marina distribution:Bypassing traditional dealer networks is opening margin capture for specialty fabricators with regional service capabilities.
Industry Challenges
- Marine aluminum welding technician scarcity:ISO 15085-certified welders command wage premiums that elevate production costs for automated-light facilities.
- CE marking documentation burden:The EU Marine Equipment Directive requires extensive technical files, slowing product launch cycles for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Ladder Market |
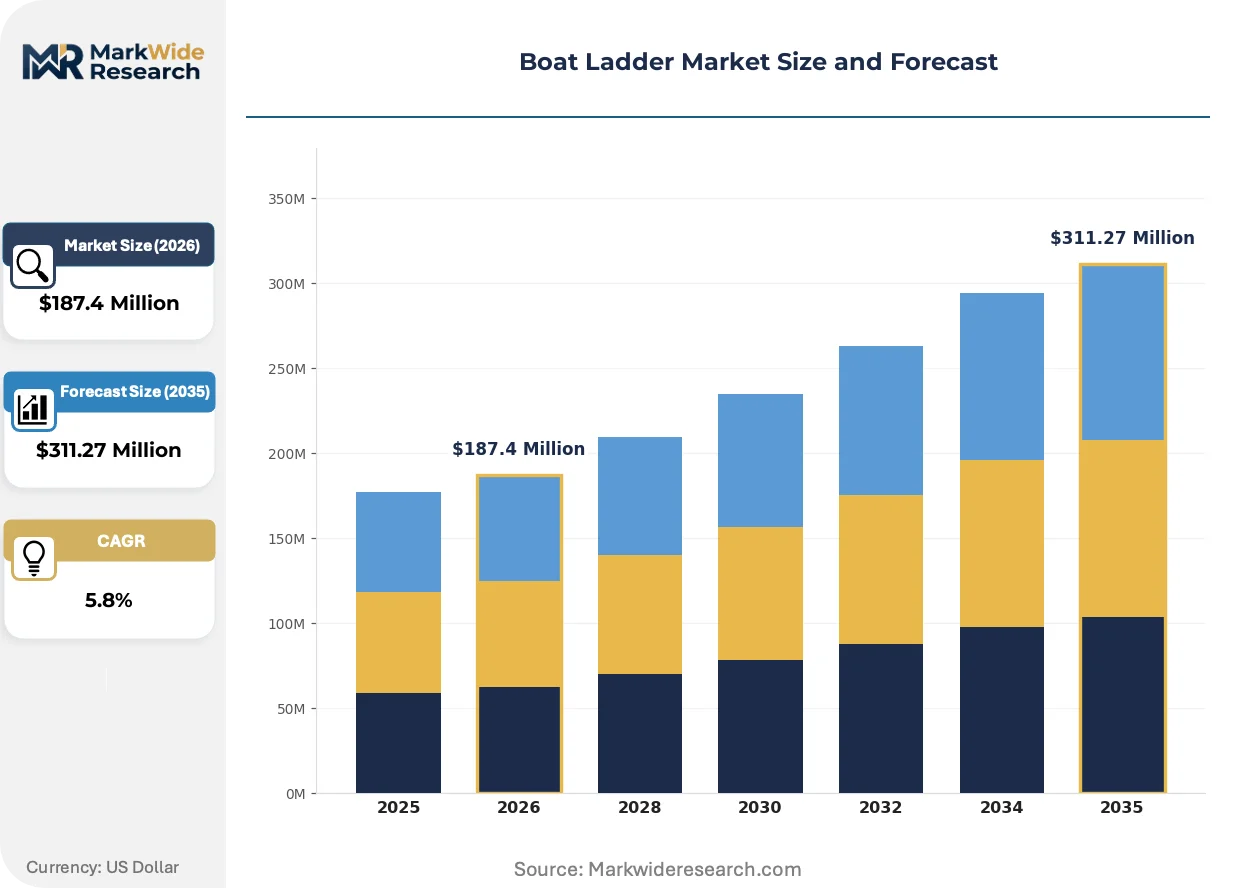
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescoping, Folding, Fixed, Portable Material: Aluminum, Stainless Steel, Plastic, Wood End User: Recreational Boaters, Commercial Users, Fishermen, Yachts Installation Type: Permanent, Removable, In-deck, Over-the-side |
| Companies Covered | Jay & Kay Mfg., Wichard, J. H. Menge & Company, J.F. Brennan Company, Baker Sheet Metal Corp., Besenzoni, Armstrong Nautical, Windline, TR INOX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Ladder Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape fabrication priorities across recreational and commercial segments. Three developments are compressing traditional design cycles and reconfiguring supplier competitive positions.
Electropolished AISI 316 stainless steel is rewriting durability expectations for saltwater boarding equipment. Yacht operators and commercial fishing fleets are specifying these finishes at accelerating rates, displacing anodized aluminum in premium installations. The shift is compressing replacement cycles from seven years toward twelve, forcing aluminum-centric suppliers to defend volume positions.
The EU F-Gas Regulation is mandating solvent-free powder coating systems across marine equipment supply chains. Manufacturers serving European markets are retooling spray lines to eliminate fluorinated gas emissions, adding capital intensity to finishing operations. Yacht ladder segments face the steepest compliance costs due to multi-stage aesthetic requirements.
Marina procurement officers are consolidating vendor relationships around full-service boarding system providers. Independent ladder fabricators without integrated platform or handrail capabilities are losing specification battles to bundled suppliers. This concentration is most visible in Florida and California coastal markets where large marina operators dominate fleet purchasing.
Boat Ladder Market Segmentation
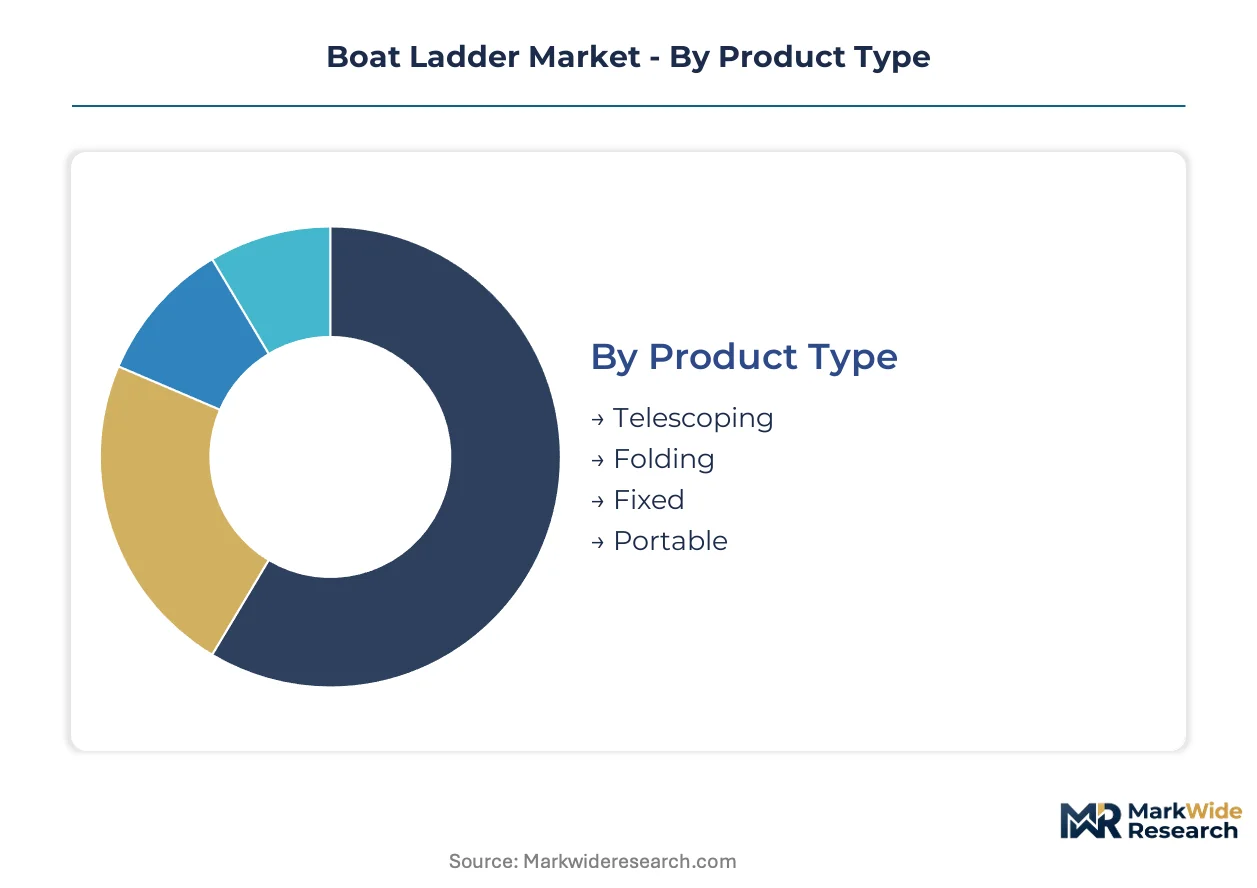
Boat ladder procurement decisions diverge sharply between recreational and commercial operators, with material specifications and deployment flexibility driving fundamentally different specification patterns across each segment category.
Product Type:
The customization-vs-standardization spectrum spans from permanently mounted fixed ladders to highly adjustable telescoping systems, with folding configurations occupying the middle ground of modularity.
- Telescoping:Sliding tubular sections enable variable reach from 3 to 12 steps, accommodating tidal fluctuations and varying freeboard heights. Commercial fishing fleets in the Pacific Northwest specify these for crab and salmon vessels where boarding height changes with load conditions.
- Folding:Hinged side rails collapse against transoms or gunwales, minimizing stowage footprint for recreational runabouts and day cruisers. Florida marina operators prioritize these for rental fleets where deck space commands premium utilization rates.
- Fixed:Rigid welded construction delivers maximum load ratings for commercial passenger vessels under US Coast Guard inspection protocols.
- Portable:Lightweight aluminum frames with suction or hook attachments serve inflatable tenders and emergency backup roles.
Leading the category by volume: Folding. Expanding most quickly: Telescoping.
Material:
Cost tier stratification separates aerospace-grade aluminum from electropolished stainless, with plastic and wood occupying niche positions defined by budget constraints or aesthetic mandates.
- Aluminum:Marine-grade 6061-T6 alloy delivers strength-to-weight ratios of 115 MPa yield strength at one-third the density of steel. Recreational boaters across California coastal counties specify anodized finishes for corrosion resistance in salt spray environments.
- Stainless Steel:AISI 316 austenitic grades with molybdenum additions withstand chloride pitting in continuous saltwater immersion. Yacht refit yards in Monaco and Fort Lauderdale mandate electropolished surfaces for superyacht boarding systems.
- Plastic:Glass-reinforced nylon and polypropylene serve freshwater lake environments where UV stability trumps mechanical load requirements.
- Wood:Teak and iroko hardwoods persist in classic sailing yacht restorations where traditional aesthetics override maintenance burden.
Dominating by installed base: Aluminum. Gaining share fastest: Stainless Steel.
End User:
Application intensity creates four distinct procurement profiles, from weekend recreational use to continuous-duty commercial operations.
- Recreational Boaters:Weekend operators and coastal cruisers prioritize compact stowage and rapid deployment for family swimming access. Demand clusters in Florida's Pinellas and Miami-Dade counties where boat ownership rates exceed national averages by 340%.
- Commercial Users:Passenger ferry operators and workboat fleets specify load-tested configurations with 500-pound minimum ratings under US Coast Guard regulations.
- Fishermen:Commercial harvesters require non-skid rung surfaces and gaff-compatible side rails for gear handling in rough seas.
- Yachts:Superyacht builders integrate boarding systems with passerelle platforms and hydraulic lift mechanisms for guest embarkation protocols.
Leading by unit volume: Recreational Boaters. Steepest expansion trajectory: Yachts.
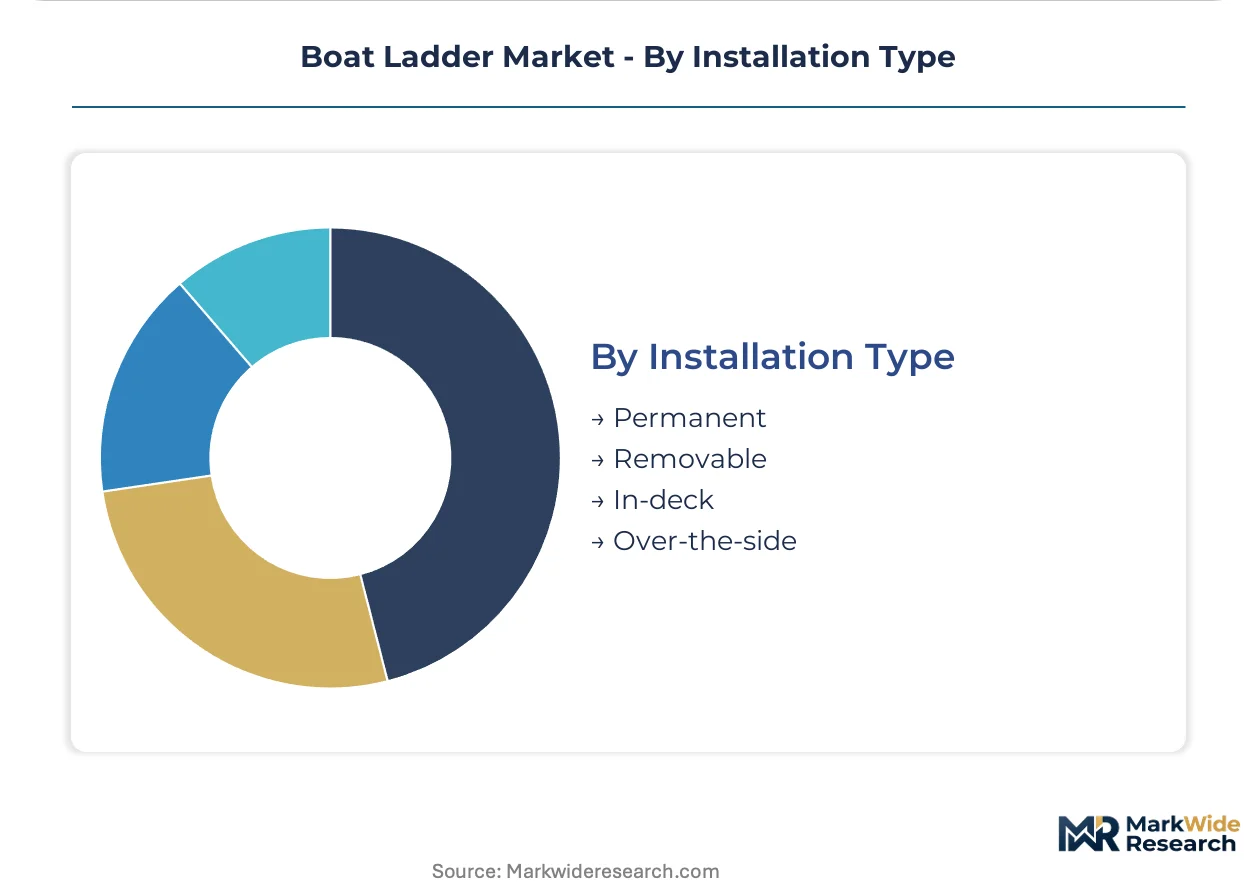
Installation Type:
Mounting permanence determines structural integration depth, from through-bolted permanent fixtures to temporary over-the-side deployments.
- Permanent:Through-bolted transom mounts with backing plates distribute loads across hull laminates or aluminum plating. Charter operators in the Florida Keys favor these for insurance compliance and liability reduction.
- Removable:Quick-release bracket systems enable seasonal removal for hurricane storage and theft deterrence in unattended marinas.
- In-deck:Flush-mounted hinges recess ladder assemblies into swim platforms, preserving clean deck lines for sport fishing and watersports vessels.
- Over-the-side:Gunwale hooks and rail clamps provide emergency boarding without hull modification, popular among inflatable tender operators.
Dominating new installations: Permanent. Climbing fastest: In-deck.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fort Lauderdale anchors yacht refit and boarding system demand, pulling premium ladder specifications from Italian and domestic fabricators alike. Coastal marinas from California to Florida drive specification upgrades toward corrosion-resistant finishes.
United States
Florida and California concentrate recreational fleet purchasing, with Pinellas County and San Diego marinas specifying electropolished stainless steel for saltwater durability. The US Coast Guard mandates 500-pound load ratings for inspected passenger vessels. Miami-Dade yacht refit yards integrate boarding systems with hydraulic passerelle platforms.
Italy
Italian metalworking heritage sustains premium yacht ladder production for Mediterranean and export markets. The EU F-Gas Regulation compels solvent-free powder coating retooling across Lombardy and Veneto fabrication clusters. Besenzoni leverages regional supply chains to maintain positioning in superyacht boarding systems.
France
Wichard anchors demand for forged stainless steel marine hardware from its Brittany manufacturing base. The EU Marine Equipment Directive shapes CE marking requirements for French exporters serving Northern European fleets. Cannes and Antibes yacht service centers specify integrated boarding solutions for seasonal charter turnover.
Germany
Commercial workboat operators on the North Sea and Baltic coasts prioritize ISO 15085-certified aluminum welding for fleet durability. The EU Green Deal incentivizes low-carbon aluminum sourcing from domestic smelters. Hamburg and Bremen harbor service vessels drive specification toward fixed-mount load-tested configurations.
Australia
Queensland and Western Australia fishing fleets specify telescoping ladders for tidal range accommodation in crab and prawn operations. The country's national marine safety regulator enforces boarding equipment standards for commercial vessels. Perth and Cairns fabrication shops serve regional fleet retrofit demand.
Boat Ladder Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and certification depth. The vendor base stratifies between aluminum volume fabricators, stainless steel specialists, and integrated boarding system providers. Three archetypes dominate: heritage European metalworkers, North American distribution-anchored brands, and Asian scale producers. Competitive moves center on coating process compliance investments and direct-to-marina channel bypass.
Within the heritage metalworking tier, Besenzoni and Wichard exemplify premium positioning through regional craftsmanship associations. TR INOX occupies a specialist position in electropolished stainless steel fabrication. Windline anchors North American presence through extensive dealer network coverage. Jay & Kay Mfg. and J. H. Menge & Company represent domestic fabrication scale serving regional marina procurement.
| Leading Market Players |
|---|
| Jay & Kay Mfg. |
| Wichard |
| J. H. Menge & Company |
| J.F. Brennan Company |
| Baker Sheet Metal Corp. |
| Besenzoni |
| Armstrong Nautical |
| Windline |
| TR INOX |
| Others |
Value Network & Pricing Analysis
LME aluminum cash settlement prices cascade through marine fabrication supply chains into three distinct pricing tiers based on corrosion resistance certification and finishing complexity. Recreational boaters in Florida and California marinas face widening cost spreads between anodized aluminum rungs and electropolished stainless steel systems as alloy volatility and EU F-Gas Regulation compliance costs layer onto finished goods.
Pricing Analysis
Replacement cycle duration anchors value-based pricing ladders in this market. Three-tier pricing structure across premium, standard, and economy levels separates electropolished AISI 316 yacht systems from ISO 15085-certified aluminum commercial units and powder-coated recreational folding ladders. Cost compression in mid-tier aluminum fabrications is intensifying because captive smelter relationships determine raw material access. Charter operators in the Florida Keys demonstrate lowest price sensitivity due to insurance-mandated load ratings, while freshwater lake boaters in the Great Lakes region prioritize economy-tier plastic alternatives.
Supply Chain Analysis
Container freight rates from Lombardy and Veneto fabrication clusters to Miami-Dade yacht refit yards directly influence landed cost competitiveness for European premium suppliers. Primary aluminum sourcing concentrates in China, Russia, and Canada, while electropolished stainless steel tube stock draws from Italian and German specialty mills. Single-source vulnerability persists for ISO 15085-certified welding technicians, particularly in North American fabrication shops serving US Coast Guard-inspected vessel operators. Distribution runs through hierarchical dealer networks anchored by Windline's extensive North American coverage, though direct-to-marina procurement is gaining share among regional specialty fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation has erected a cost-of-compliance barrier that rewards first-mover retooling investments while marginalizing smaller coating operations lacking capital access for solvent-free powder line conversions.
For Market Incumbents: To counter aluminum alloy price volatility compressing margin pools, Besenzoni and heritage European metalworkers should deepen backward integration into low-carbon aluminum sourcing partnerships certified under EU Green Deal frameworks. Channel control through exclusive marina service contracts in Fort Lauderdale and Monaco yacht clusters offers defensive positioning against direct-to-marina disintermediation.
For New Entrants and Emerging Players: Capture underserved demand in telescoping ladder configurations for Pacific Northwest commercial fishing fleets requiring tidal range accommodation. Target Queensland and Western Australia retrofit markets where local fabrication capacity lags fleet renewal cycles. A go-to-market angle emphasizing ISO 15085 certification speed-to-market differentiates against incumbent documentation burdens.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electropolished stainless steel specialists in Italian metalworking clusters where EU regulatory compliance investments have already been sunk. Long-term viability hinges on replacement cycle extension toward twelve-year intervals for premium yacht segments. The signal to watch is marina procurement officer consolidation around bundled boarding system providers, which will accelerate independent fabricator exit opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Powder Coating Retooling | EU F-Gas Regulation compliance secures market access across Lombardy and Veneto fabrication clusters. |
| Low-Carbon Aluminum Sourcing Certification | EU Green Deal alignment enables premium positioning in superyacht boarding system specifications. |
| Direct-to-Marina Distribution Buildout | Bypassing dealer networks captures margin from Florida and California coastal fleet operators. |
| ISO 15085 Welding Capacity Expansion | Certified technician pools address scarcity premiums elevating production costs for automated-light facilities. |
| Telescoping Mechanism R&D Investment | Adjustable-reach configurations serve Pacific Northwest crab and salmon vessel operators with variable boarding heights. |
Research Methodology
Independent corroboration across marina procurement officers, yacht refit yard managers, and commercial fishing fleet operators underwrites the qualitative findings in this study. Primary interviews with ISO 15085-certified welding technicians, aluminum alloy distributors, and marine equipment dealers combined with secondary validation from US Coast Guard inspection protocols, EU Marine Equipment Directive technical files, and customs trade data for marine-grade aluminum imports. Bottom-up triangulation across product type, material specification, and end-use intensity dimensions converged with top-down macroeconomic framing.
Rate-of-change decomposition across the analysis window separates volume drivers from price mix effects in recreational versus commercial segments. The analytical framework models product type, material grade, end-user intensity, and installation permanence dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include marina fleet renewal cycles in Florida and California, EU F-Gas Regulation compliance timelines, and yacht refit seasonality patterns in Mediterranean and South Florida clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum alloy price volatility, ISO 15085 certification backlog durations, and marina procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Europe Marine Communication Systems Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Sailboat Propellers Market
Marine
Marine Beacon Market
Marine
Marine Winch Motors Market
Marine
Boat Trolling Motor Market
Marine
Marine Engine Cooling Systems Market
Marine
Pneumatic Marine Fender Market
Marine
Marine VFD Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Pipes Market
Marine
US Fish Finders Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Chronometers Market
Marine
Boat Hook Market
Marine
Ship/Boat Keel Market