
 Automotive Casting Market | 2026-2036
Automotive Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Casting Market Intelligence
Modular powertrain packaging is repositioning how OEMs source transmission housings and motor enclosures from casting suppliers. Nemak leverages its aluminum die-casting scale to dominate structural EV battery tray production across North American assembly plants. Ryobi Limited sustains competitive intensity through dedicated R&D centers in Japan that specialize in thin-wall magnesium castings for powertrain weight reduction. Rheinmetall Automotive anchors European supply security through in-house sand-casting capacity for commercial-vehicle engine blocks.
Automotive casting encompasses the pouring of molten metal into molds to form precision components with tolerances typically within 0.5 mm for critical engine and transmission parts, serving primarily as the foundational manufacturing process for powertrain and chassis systems. Aluminum castings command the largest share of product-type value as OEMs substitute ferrous materials to meet fleet efficiency targets, while magnesium castings represent the fastest-expanding category due to their unmatched strength-to-weight ratio in seat frames and steering columns. Die-casting technology leads the process mix for high-volume powertrain components, whereas sand-casting retains dominance in prototype runs and heavy-duty engine blocks where geometric complexity exceeds die-casting constraints.
NHTSA Corporate Average Fuel Economy standards, EPA greenhouse-gas emissions rules, and China's MIIT dual-carbon goals collectively mandate lighter vehicle architectures that expand aluminum and magnesium casting penetration. The EU F-Gas Regulation and REACH compliance frameworks additionally restrict certain die-casting release agents and flux chemistries, reshaping supplier qualification requirements across European foundries. Stakeholders must monitor evolving alloy specifications and carbon-border adjustment mechanisms to secure long-term supply contracts without exposure to stranded process investments.
Market Dynamics
Lightweight powertrain architectures are forcing foundries to reconfigure alloy portfolios and process capabilities around aluminum-intensive electric vehicle platforms. This structural shift compresses supplier margins while rewarding scale players with captive OEM relationships.
Growth Catalysts
- EPA greenhouse-gas emissions rules:Fleet efficiency mandates in the United States accelerate aluminum substitution in transmission housings and engine blocks.
- Structural battery enclosures:EV manufacturers specify high-pressure die-cast trays to protect lithium-ion packs while minimizing mass.
- China:MIIT dual-carbon goals push domestic OEMs toward magnesium castings for seat frames and steering columns.
Market Restraints
- Primary aluminum price volatility:LME price swings strain foundry margins and complicate long-term OEM contract pricing.
- EU F-Gas Regulation:Restrictions on certain die-casting release agents force European suppliers to qualify alternative chemistries.
- Geometric complexity ceiling:Die-casting constraints limit thin-wall magnesium adoption in complex motor enclosures.
Strategic Opportunities
- Mexico:Proximity to North American EV assembly plants positions foundries for transmission housing export growth.
- Thin-wall magnesium seat frames:Premium OEMs specify sub-2mm wall sections for occupant safety structures.
- Carbon-border adjustment mechanisms:Low-carbon primary aluminum sourcing becomes a contract differentiator for European battery tray supply.
Industry Challenges
- High-pressure die-casting tool steel shortage:Lead times for H13-grade inserts extend beyond 26 weeks, delaying new program launches.
- REACH compliance documentation:Alloy chemistry traceability requirements consume quality engineering resources across European foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Casting Market |
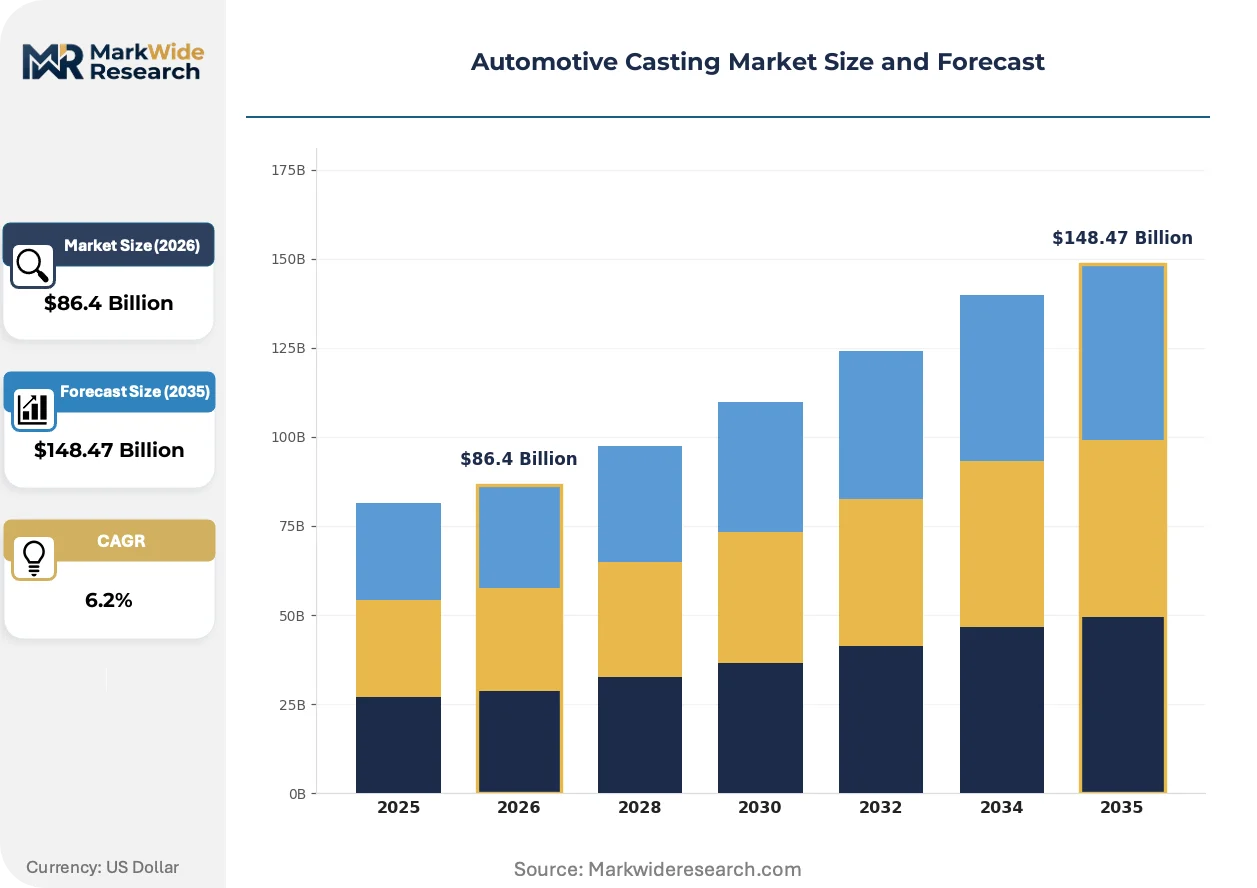
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $148.47 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Castings, Iron Castings, Steel Castings, Magnesium Castings, Copper Castings Technology: Sand Casting, Die Casting, Investment Casting, Centrifugal Casting, Vacuum Casting Application: Engine Components, Transmission Parts, Suspension Components, Brake System Parts, Exhaust Systems End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers, Component Distributors |
| Companies Covered | Nemak, Ryobi Limited, Dynacast, Rheinmetall Automotive, GF Casting Solutions, Endurance Technologies, Pace Industries, Shiloh Industries, Meridian Lightweight Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Casting Market Strategic Shifts & Innovations
Process automation and alloy innovation are compressing development cycles for structural castings while regulatory chemistry restrictions force material science pivots. These forces reshape competitive capability requirements faster than capital replacement cycles.
Large-scale integrated die-casting is unifying multiple stamped and welded chassis components into single aluminum castings. Tesla and Volvo Car have adopted 6,000-ton-plus machines for rear underbody structures. This approach is unifying tiered supplier networks by collapsing stamping, welding, and assembly steps into foundry operations.
REACH authorization lists now restrict certain boron-based grain refiners in European aluminum foundries. Suppliers must reformulate A356 alloys without compromising mechanical properties. German transmission housing producers face the steepest qualification timelines as OEMs demand full material pedigree documentation.
Buyer consolidation around platform-sharing alliances concentrates casting procurement decisions. Stellantis and Hyundai Motor Group now specify common battery tray architectures across multiple brands. Tier-1 suppliers in Germany and Japan report compressed quoting cycles as OEMs synchronize global program launches.
Automotive Casting Market Segmentation
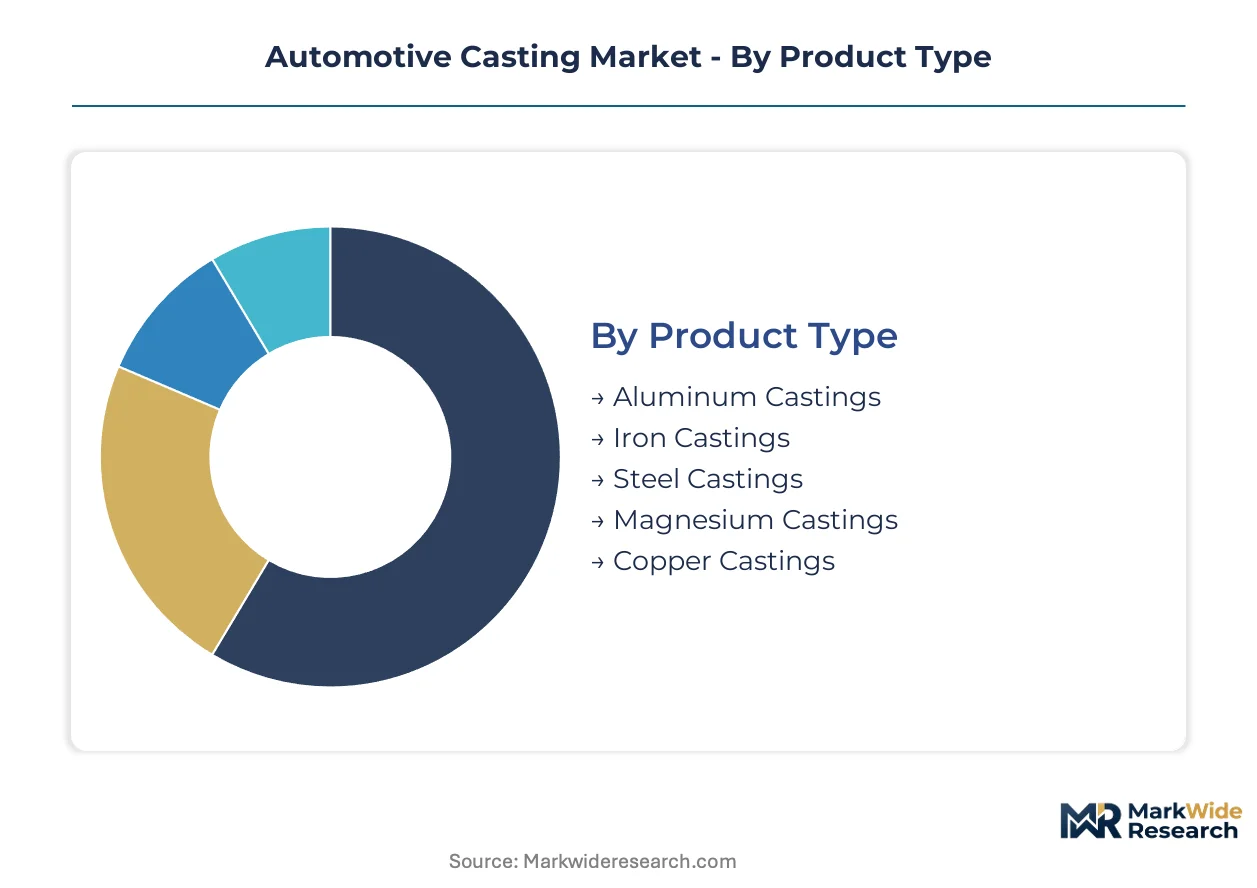
Automotive casting procurement diverges sharply across material systems, process technologies, and supply chain tiers. OEMs weight alloy density against forming constraints differently for ICE powertrains versus EV architectures, fragmenting supplier specialization.
Product Type:
Cost tier separates buyers seeking commodity ferrous castings from those paying premiums for lightweight alloys.
- Aluminum Castings:These alloys deliver density reductions of approximately one-third versus iron while maintaining thermal conductivity for cylinder heads and transmission housings. NHTSA fleet efficiency mandates in the United States accelerate substitution in engine blocks and structural battery trays.
- Magnesium Castings:Unmatched strength-to-weight ratios enable sub-2mm wall sections in seat frames and steering columns. MIIT dual-carbon goals in China push domestic OEM adoption despite higher raw material costs and corrosion protection requirements.
- Iron Castings:Gray and ductile iron retain cost advantages for heavy-duty commercial vehicle engine blocks where mass reduction carries lower regulatory priority.
- Steel Castings:High-strength alloy steels serve suspension knuckles and steering gear housings requiring fatigue resistance beyond aluminum capabilities.
- Copper Castings:Thermal and electrical conductivity specifications drive limited demand for electric motor rotors and high-performance brake calipers.
Aluminum castings lead volumes today; magnesium castings are gaining share fastest.
Technology:
Volume throughput and geometric precision requirements dictate process selection across powertrain versus chassis applications.
- Die Casting:High-pressure systems achieve dimensional tolerances within 0.5 mm for transmission housings and motor enclosures. Large-scale integrated machines exceeding 6,000 tons now unify multiple chassis components into single aluminum castings for EV platforms.
- Sand Casting:Green sand and chemically bonded molds accommodate prototype runs and heavy-duty engine blocks where geometric complexity exceeds die-casting constraints. Rheinmetall Automotive maintains in-house capacity for commercial-vehicle cylinder blocks across European foundries.
- Investment Casting:Lost-wax precision enables turbine blades and complex exhaust manifolds requiring internal passages impossible with other methods.
- Centrifugal Casting:Rotational force distribution produces dense, defect-free cylinders for brake drums and clutch pressure plates.
- Vacuum Casting:Reduced porosity suits thin-wall magnesium components where atmospheric die-casting yields unacceptable defect rates.
Die casting commands the largest revenue base; vacuum casting is expanding most quickly for magnesium applications.
Application:
Powertrain electrification is displacing traditional engine demand while creating new casting categories for battery protection.
- Engine Components:Cylinder heads, blocks, and manifolds face volume pressure as BEV penetration rises. Aluminum substitution in remaining ICE programs sustains foundry utilization.
- Transmission Parts:Multi-speed e-axle housings and reduction gear carriers require die-cast aluminum enclosures with integrated cooling passages. Modular powertrain packaging concentrates procurement decisions at platform level.
- Suspension Components:Control arms and knuckles specify aluminum or steel based on vehicle class and load requirements.
- Brake System Parts:Caliper housings and master cylinders favor cast iron for thermal mass in performance applications.
- Exhaust Systems:Manifold and catalytic converter housings face regulatory pressure from EPA emissions standards while declining in absolute volume.
Transmission parts lead current casting procurement; structural battery enclosures are climbing the fastest as a nascent category.
End User:
Supply chain tier determines technical specification authority and contract duration.
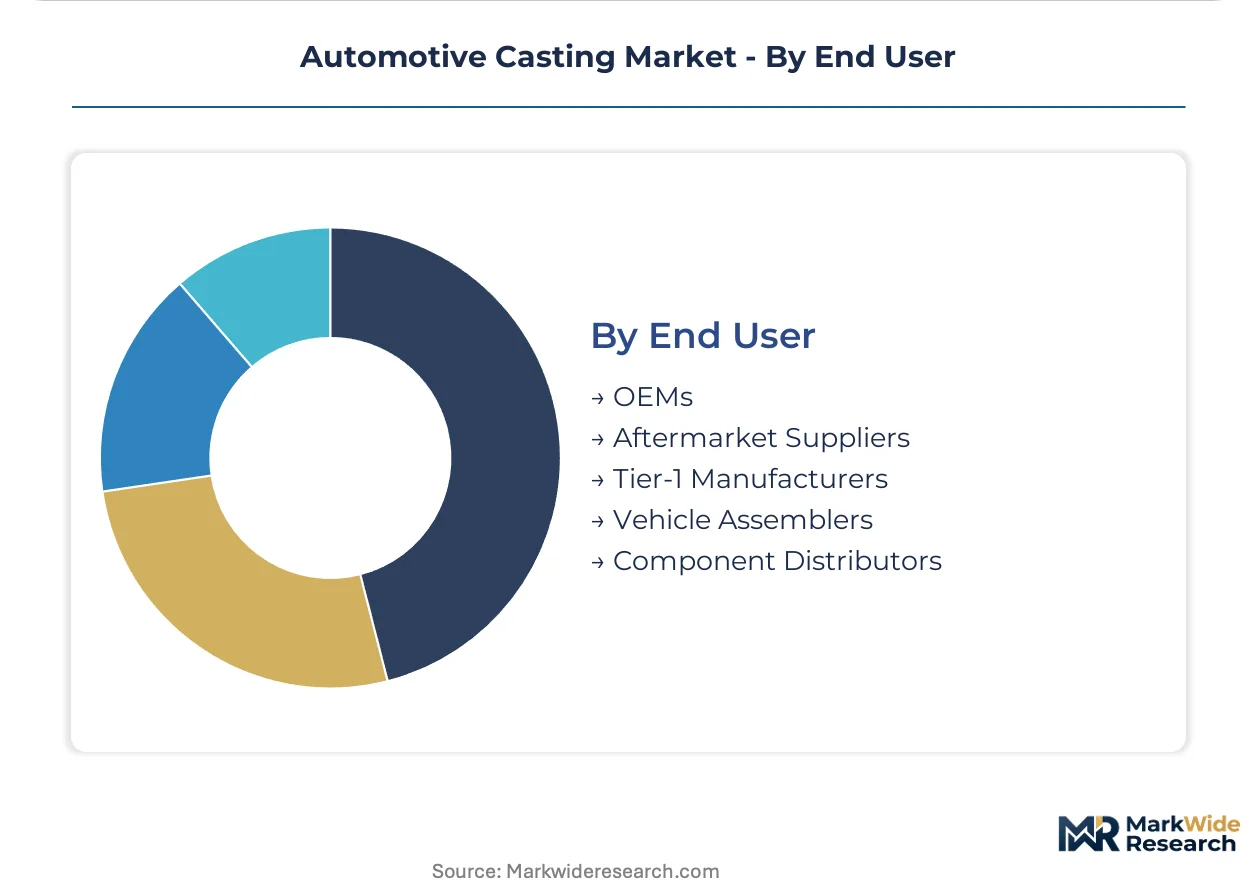
- OEMs:Direct sourcing of structural battery trays and large integrated castings bypasses traditional tier-1 relationships. Tesla and Volvo Car specify 6,000-ton die-casting cells for rear underbody modules.
- Tier-1 Manufacturers:Transmission housing specialists like Nemak aggregate volume across multiple OEM platforms. Stellantis and Hyundai Motor Group now specify common battery tray architectures across brands, compressing quoting cycles.
- Aftermarket Suppliers:Replacement engine blocks and suspension components serve vehicle aging pools with longer lead time tolerance.
- Vehicle Assemblers:Contract manufacturers and emerging EV entrants source complete cast subassemblies rather than individual components.
- Component Distributors:Inventory holding and logistics services bridge foundries with fragmented repair market demand.
Tier-1 manufacturers dominate transaction volumes today; OEM direct sourcing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive die-casting scale during the post-war industrial expansion, establishing process standards that still govern European foundry operations today. Foundry investment now concentrates in Mexico, Germany, and China as these countries anchor regional supply networks for transmission housings and structural battery enclosures.
United States
Domestic EV assembly plants in Michigan, Tennessee, and Texas drive demand for high-pressure die-cast battery trays. NHTSA Corporate Average Fuel Economy standards and EPA greenhouse-gas emissions rules mandate aluminum substitution in powertrain components. Detroit-area foundries supply transmission housings to platform-sharing alliances across the Midwest manufacturing corridor.
Germany
Premium OEMs specify thin-wall magnesium seat frames and integrated rear underbody castings for electric platforms. EU F-Gas Regulation and REACH compliance frameworks restrict certain die-casting release agents and flux chemistries. Bavarian and Baden-Württemberg foundries face compressed qualification timelines as OEMs demand full material pedigree documentation.
China
Domestic EV manufacturers accelerate magnesium casting adoption for steering columns and occupant safety structures. MIIT dual-carbon goals push OEMs toward lightweight architectures that expand aluminum and magnesium penetration. Yangtze River Delta foundries cluster around battery tray production for export to European and North American assembly plants.
Mexico
Proximity to North American EV assembly plants positions foundries for transmission housing export growth. Mexican federal industrial policy supports automotive supplier parks in Nuevo León and the Bajío Region. Querétaro and San Luis Potosí foundries supply die-cast aluminum enclosures to platform-sharing programs across the USMCA trade zone.
Japan
Domestic OEMs source thin-wall magnesium powertrain components for hybrid and battery-electric platforms. METI energy efficiency guidelines reinforce lightweight material adoption across vehicle architectures. Aichi Prefecture foundries specialize in vacuum casting processes for complex motor enclosures requiring sub-2mm wall sections.
Automotive Casting Market Key Industry Players
The competitive structure tilts toward scale-driven aluminum die-casting specialists with captive OEM relationships. Tier-1 suppliers aggregate volume across multiple platforms while integrated OEM foundries bypass traditional procurement channels for structural battery trays. Two strategic archetypes dominate: high-volume die-casting scale players and thin-wall magnesium specialists with dedicated R&D capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as foundries reconfigure alloy portfolios around electric vehicle architectures.
Among North American aluminum die-casting specialists, Nemak and Pace Industries exemplify scale-driven archetypes with platform-level procurement relationships. Rheinmetall Automotive and Ryobi Limited represent contrasting specialization models—European sand-casting capacity for commercial-vehicle engine blocks versus Japanese thin-wall magnesium R&D centers for powertrain weight reduction. GF Casting Solutions occupies a position bridging process technology breadth with geographic diversification across European and Asian supply networks.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Limited |
| Dynacast |
| Rheinmetall Automotive |
| GF Casting Solutions |
| Endurance Technologies |
| Pace Industries |
| Shiloh Industries |
| Meridian Lightweight Technology |
| Others |
Cost & Logistics Intelligence
OEM platform-sharing alliances concentrating procurement decisions at Stellantis and Hyundai Motor Group enforce contract-based long-term offtake pricing for structural battery trays and transmission housings. This buyer consolidation compresses quoting cycles while amplifying volume-scale leverage over tier-1 foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade vacuum-cast magnesium from commodity high-pressure die-cast aluminum and gray iron commercial-vehicle blocks. Price differentiation rests on ISO certification tiers and vertical integration depth in alloy sourcing. Cost compression in standard-tier aluminum transmission housings is intensifying because primary aluminum LME volatility strains foundry margins. Aftermarket distributors exhibit highest price sensitivity due to inventory holding costs, while OEM direct-sourcing programs prioritize performance consistency over unit economics.
Supply Chain Analysis
USMCA domestic-content thresholds and China's MIIT localization mandates are reshaping sourcing patterns for North American and Asian EV assembly plants. Geographic supply concentration centers on Germany, China, and Mexico as anchor points for regional transmission housing and battery tray networks. Raw material dependencies draw from primary aluminum smelters, H13-grade tool steel suppliers, and boron-free grain refiner chemistries. Single-source vulnerability in high-pressure die-casting tool steel creates program launch delays extending beyond half-year lead times. Distribution runs through tier-1 aggregators like Nemak that consolidate volume across multiple OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA Corporate Average Fuel Economy standards and EPA greenhouse-gas emissions rules mandate aluminum-intensive architectures that expand foundry addressable demand.
For Market Incumbents: Acquire captive magnesium vacuum-casting capacity to defend against thin-wall specialists like Ryobi Limited. Consolidate sand-casting assets in Germany to secure commercial-vehicle engine block contracts as Rheinmetall Automotive faces REACH compliance documentation burdens. Backward integration into low-carbon primary aluminum sourcing addresses carbon-border adjustment exposure in European battery tray supply. For New Entrants and Emerging Players: Digital direct-to-OEM channels bypass tier-1 procurement gatekeepers for specialized thin-wall magnesium seat frame programs. White-space targets include Mexican federal industrial policy zones in Nuevo León and Querétaro for transmission housing export growth. Target aftermarket distributors serving aging vehicle pools with longer lead-time tolerance for prototype sand-cast engine blocks. For Investors and Strategic Acquirers: Tier-1 automotive suppliers with platform-level relationships are the most active acquirer in this space, consolidating die-casting scale to serve Stellantis and Hyundai Motor Group shared architectures. Long-term viability hinges on alloy portfolio reconfiguration speed around EV structural enclosures. Monitor high-pressure die-casting tool steel lead time normalization as inflection indicator for new program launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Stellantis and Hyundai Motor Group shared battery tray architectures compress quoting cycles across tier-1 suppliers. |
| Battery Supply Agreement | Structural enclosure procurement concentrates at foundries with 6,000-ton die-casting cell capacity. |
| Geographic Manufacturing Footprint | Mexican supplier parks in Nuevo León anchor USMCA-compliant transmission housing exports. |
| Software-Defined Vehicle Investment | Integrated rear underbody castings collapse traditional stamping and welding tier networks. |
| Charging Infrastructure Partnership | Thermal management casting demand rises with fast-charging battery enclosure cooling requirements. |
Research Approach
Bottom-up vehicle production modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations specialists cross-validate secondary sources including vehicle registration databases, IHS Markit production data, SEC foundry filings, and customs trade records. This triangulation anchors volume estimates against actual supply-side utilization rates.
Input-output matrices map alloy consumption to powertrain architecture shifts across the projection horizon. Segmentation dimensions span propulsion type, vehicle class, content per vehicle, and regional production cluster. CAGRs derive from regression analysis against regulatory milestone timing and OEM platform launch schedules. Forecast inputs incorporate MIIT dual-carbon policy stringency and NHTSA fleet efficiency trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for large-scale integrated die-casting would alter the outlook if geometric complexity ceilings relax faster than projected. Forecasts reflect documented assumptions about primary aluminum price stabilization and REACH authorization list evolution. Stranded process investments from premature ferrous casting obsolescence or boron-refiner chemistry disqualification represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Clock Spring Market