
 Marine Bearings Market | 2026-2036
Marine Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Bearings Market Foresight
The capital-intensity divergence between polymer-formulation specialists and full-system integrators is redrawing competitive boundaries in marine bearings. Trelleborg AB leverages its elastomer-polymer compounding depth to dominate high-performance stern tube and rudder bearing niches. SKF anchors its position through integrated condition-monitoring systems that extend service intervals for deep-sea merchant fleets. Wärtsilä sustains advantage by bundling bearings within complete propulsion packages, capturing shipyard procurement efficiencies.
Marine bearings are precision tribological components engineered to support rotating shafts, rudders, and propulsion machinery under seawater exposure, extreme load cycling, and boundary lubrication regimes; advanced grades employ polytetrafluoroethylene (PTFE)-bronze composites or elastomeric alloys bonded to steel shells to achieve dry-running tolerance and dimensional stability across -40°C to 120°C operating windows. Thrust bearings and composite bearings command the deepest margin pools as vessel power density rises and ship operators abandon oil-lubricated stern tubes for seawater-lubricated polymer alternatives. Ceramic and plastics material segments are gaining fastest in electric propulsion pods and azimuth thrusters where electromagnetic compatibility and corrosion immunity outweigh traditional bronze-steel durability metrics.
IMO MARPOL Annex VI, EU MRV Regulation, and EPA Vessel General Permit collectively mandate lubricant containment and emissions transparency, forcing bearing suppliers to certify seawater-lubricated designs and document lifecycle environmental footprints. The EU Green Deal's Fit for 55 package accelerates fleet decarbonization timelines, tightening material sourcing rules for bearings installed on vessels trading European routes. Stakeholders must monitor classification society readiness to certify novel polymer-ceramic hybrids for ice-class and polar code applications.
Market Dynamics
IMO 2023 amendments to MARPOL Annex VI are forcing commercial shipping operators to abandon oil-lubricated stern tube systems, triggering a wholesale material transition toward seawater-lubricated polymer-composite bearings across deep-sea merchant fleets.
Growth Catalysts
- EU Green Deal Fit for 55:The package accelerates fleet decarbonization timelines, tightening material sourcing rules for bearings installed on vessels trading European routes and expanding addressable demand for certified low-carbon polymer formulations.
- LNG-fueled container vessels:South Korean mega-yards are scaling construction of these vessels, each requiring polymer stern tube bearings compatible with variable-speed electric propulsion and reduced thermal loading profiles.
- Japan naval defense expansion:Maritime Self-Defense Force procurement programs are specifying polymer-composite stern tube bearings for next-generation destroyer classes, validating seawater-lubricated designs for high-reliability military applications.
Market Restraints
- PTFE-bronze composite feedstock volatility:Fluoropolymer resin prices fluctuate with refrigerant chemical markets, compressing margin predictability for bearing formulators dependent on virgin PTFE supply.
- East Asian shipbuilding cluster concentration:Over 70% of newbuild orders flow through South Korean and Chinese yards, creating customer-side bargaining power that pressures bearing suppliers on volume pricing.
- Classification society certification bottlenecks:Novel polymer-ceramic hybrid designs face extended approval timelines from Lloyd's Register and DNV for ice-class and polar code applications, delaying commercialization.
Strategic Opportunities
- Electric propulsion pod azimuth thrusters:Ceramic bearing inserts are penetrating these systems where electromagnetic compatibility and corrosion immunity outweigh traditional bronze-steel durability metrics in Azipod-type installations.
- EPA Vessel General Permit compliance services:US-flag operators require documented lifecycle environmental footprints for bearing replacements, creating attach-rate potential for monitoring and certification service bundles.
- Aftermarket retrofit of existing oil-lubricated stern tubes:German and Japanese commercial fleets hold aging tonnage subject to MARPOL discharge rules, opening conversion demand for drop-in polymer bearing cartridges.
Industry Challenges
- Tribological simulation talent scarcity:Boundary lubrication modeling for seawater-polymer interfaces requires specialized computational fluid dynamics expertise that outpaces marine engineering graduate pipeline output.
- Polymer-to-steel bond qualification timelines:Elastomeric alloy adhesion testing under thermal cycling protocols demands 18-24 month validation periods that compress product development calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Bearings Market |
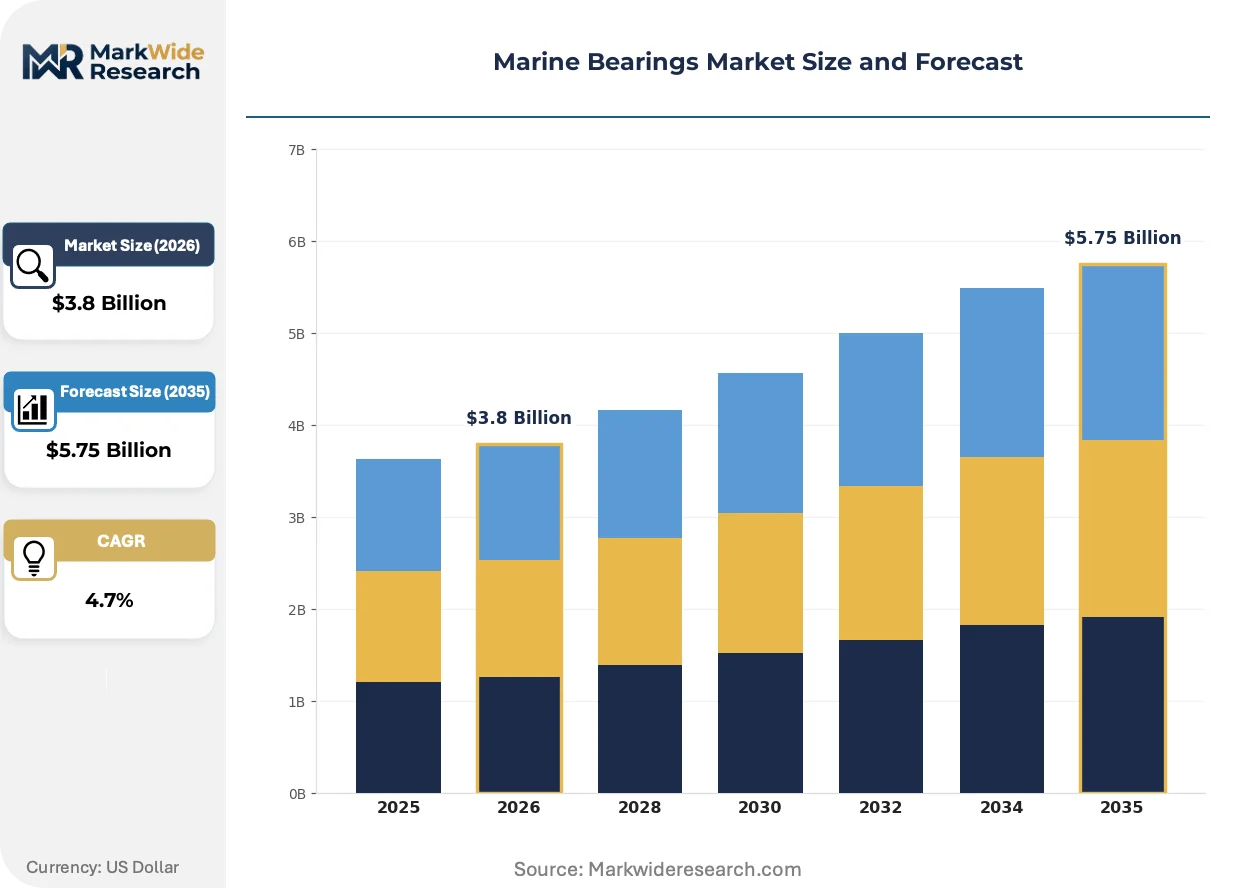
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrust Bearings, Radial Bearings, Composite Bearings, Journal Bearings Material: Bronze, Stainless Steel, Plastics, Ceramics End User: Shipbuilding, Marine Engineering, Offshore Platforms, Fishing Vessels Application: Propulsion Systems, Steering Gear, Auxiliary Equipment, Deck Machinery |
| Companies Covered | Trelleborg AB, Lagersmit B.V., SKF, MAN Energy Solutions SE, NSK Ltd., Wärtsilä, Schaeffler Group, König Maschinen GmbH, Thordon Bearings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Bearings Market Shifts & Advancements
Material science advances and regulatory enforcement are splitting the bearing market into distinct performance tiers, with premium polymer-ceramic hybrids commanding technical specifications while commodity bronze-steel retains cost-sensitive niches.
PTFE-bronze composite stern tube bearing technology is bifurcating the installed base. The material achieves dry-running tolerance and dimensional stability across -40°C to 120°C operating windows. Deep-sea container operators are adopting these bearings at accelerating rates for newbuilds and retrofits. This technology is compressing the addressable market for traditional white-metal oil-lubricated designs while expanding margin pools for formulation specialists.
REACH substance restrictions on persistent organic pollutants are tightening scrutiny of fluoropolymer manufacturing residues. The regulation forces bearing suppliers to certify virgin PTFE sourcing chains and document elimination of perfluorooctanoic acid process residuals. European route operators and their classification intermediaries are responding by mandating supplier environmental product declarations ahead of contract awards.
Shipyard procurement departments are consolidating vendor panels around integrated propulsion package suppliers. The concentration eliminates standalone bearing component bidding for major newbuild programs, forcing independent specialists to penetrate aftermarket channels or develop shipyard-direct technical service relationships. This pattern is most visible in South Korean mega-yard contracting where Wärtsilä and Siemens Energy bundle bearings within turnkey propulsion contracts.
Marine Bearings Market Segmentation
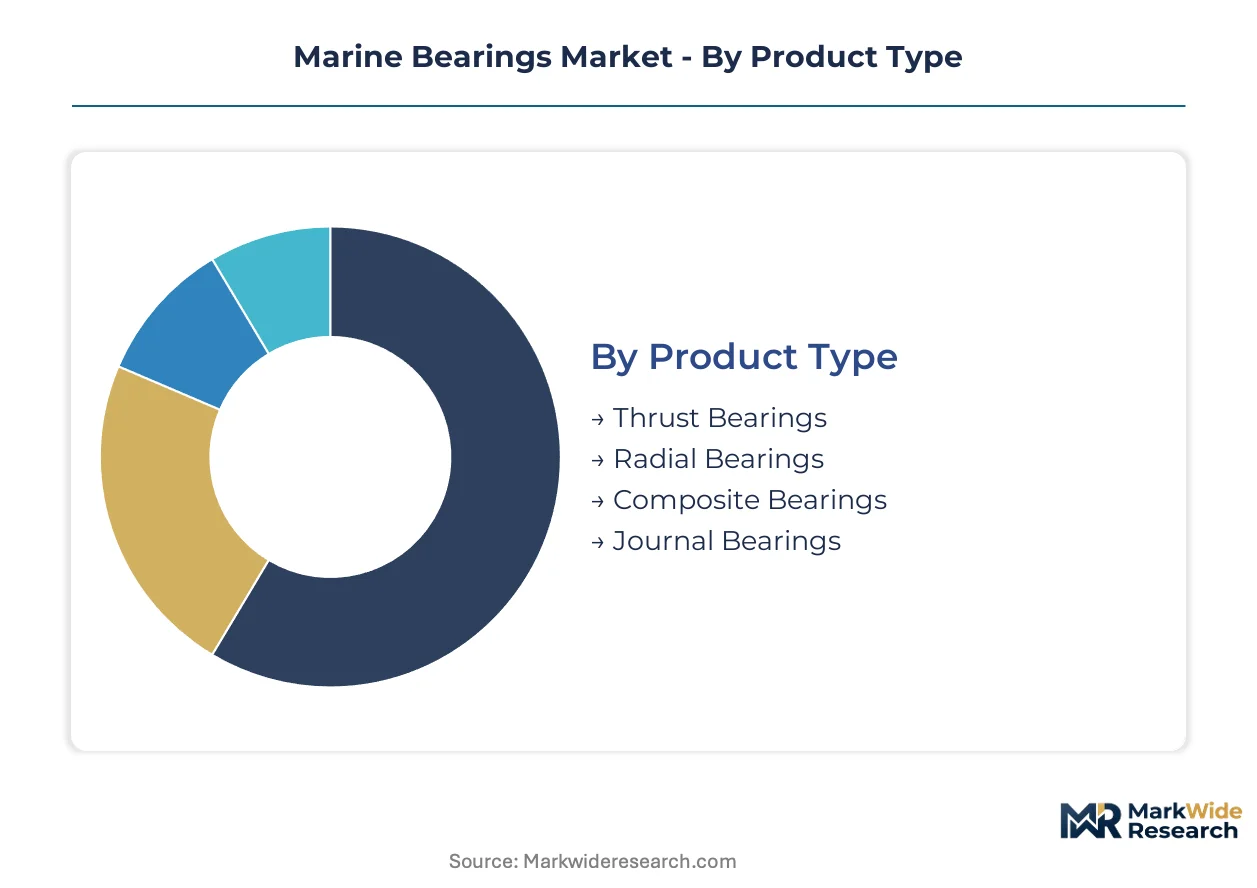
Marine bearings serve distinct tribological regimes across propulsion, steering, and auxiliary systems, with material selection and bearing architecture directly determining service intervals, lubricant compatibility, and regulatory compliance pathways.
Product Type:
Margin pools concentrate in high-load bearing architectures where dry-running tolerance and dimensional stability command premium positioning against commodity alternatives.
- Thrust Bearings:These components manage axial loads from propeller thrust and shaftline dynamics, typically employing PTFE-bronze composites or elastomeric alloys bonded to steel shells. Demand clusters in South Korean mega-yards constructing LNG-fueled container vessels where variable-speed electric propulsion imposes reduced thermal loading profiles. IMO 2023 MARPOL Annex VI amendments accelerate seawater-lubricated polymer adoption, compressing addressable demand for traditional white-metal oil-lubricated designs.
- Composite Bearings:Polymer-ceramic hybrid formulations achieve dimensional stability across -40°C to 120°C operating windows while eliminating lubricant discharge risks. German and Japanese naval defense fleets specify these for next-generation destroyer classes, validating seawater-lubricated designs for high-reliability military applications. REACH substance restrictions on persistent organic pollutants tighten scrutiny of fluoropolymer manufacturing residues, forcing certified virgin PTFE sourcing chains.
- Radial Bearings:Cylindrical and spherical configurations support perpendicular shaft loads in auxiliary machinery and pump drives.
- Journal Bearings:Sleeve-type designs retain cost-sensitive niches in deck machinery and low-speed applications where oil lubrication remains permissible.
The dominant share belongs to Thrust Bearings, while Composite Bearings are expanding most quickly as regulatory enforcement tightens.
Material:
Cost tier stratification separates corrosion-immune advanced ceramics from commodity bronze-steel formulations facing margin compression.
- Plastics:PTFE-bronze composites and engineered polymers dominate seawater-lubricated stern tube retrofits, achieving dry-running tolerance where oil discharge is prohibited. Deep-sea container operators adopt these at accelerating rates for newbuilds and retrofits, with South Korean and Chinese yards driving volume procurement. Fluoropolymer resin prices fluctuate with refrigerant chemical markets, compressing margin predictability for formulators dependent on virgin supply.
- Ceramics:Silicon nitride and zirconia inserts penetrate electric propulsion pods and azimuth thrusters where electromagnetic compatibility and corrosion immunity outweigh traditional bronze-steel durability metrics. Azipod-type installations specify ceramic bearing inserts for their non-conductive properties and thermal stability. Classification society certification bottlenecks from Lloyd's Register and DNV delay commercialization for ice-class and polar code applications.
- Bronze:Traditional tin-bronze alloys retain installed base in legacy oil-lubricated systems and cost-sensitive fishing vessel applications.
- Stainless Steel:Martensitic and duplex grades serve intermediate load conditions where corrosion resistance must balance material cost against polymer alternatives.
Plastics command the deepest margin pools, though Ceramics are gaining share fastest in electric propulsion architectures.
End User:
Application maturity varies sharply, with shipbuilding commanding procurement volume while offshore platforms demand specialized qualification timelines.
- Shipbuilding:Newbuild construction at South Korean mega-yards and Chinese facilities concentrates demand for integrated propulsion packages where Wärtsilä and Siemens Energy bundle bearings within turnkey contracts. This concentration eliminates standalone bearing component bidding for major programs, forcing independent specialists toward aftermarket channels. Over 70% of newbuild orders flow through these East Asian clusters, creating customer-side bargaining power on volume pricing.
- Marine Engineering:Retrofit and maintenance operations serve aging German and Japanese commercial fleets subject to MARPOL discharge rules, opening conversion demand for drop-in polymer bearing cartridges. EPA Vessel General Permit compliance requirements create attach-rate potential for monitoring and certification service bundles among US-flag operators.
- Offshore Platforms:Stationary production facilities require extended service intervals and subsea qualification protocols that extend supplier validation periods.
- Fishing Vessels:Smaller tonnage and cost constraints sustain commodity bronze-steel bearings in this price-sensitive segment.
Shipbuilding captures the dominant share, while Marine Engineering is climbing the fastest as regulatory retrofit cycles accelerate.
Application:
Supply concentration in propulsion system integration is reshaping how bearing suppliers access major procurement decisions.
- Propulsion Systems:Stern tube bearings, shaftline supports, and thrust blocks face the most stringent regulatory pressure under IMO MARPOL Annex VI amendments. Shipyard procurement departments consolidate vendor panels around integrated package suppliers, eliminating standalone component bidding. Polymer-to-steel bond qualification timelines demand 18-24 month validation periods under thermal cycling protocols, compressing product development calendars for formulators.
- Steering Gear:Rudder bearings and tiller mechanisms specify elastomeric polymer composites for their shock-load tolerance and maintenance interval extension. Trelleborg AB leverages elastomer-polymer compounding depth to dominate this niche alongside high-performance stern tube applications.
- Auxiliary Equipment:Pump bearings, generator supports, and HVAC machinery drive steady replacement demand through aftermarket channels.
- Deck Machinery:Winches, cranes, and mooring equipment retain cost-optimized bronze and steel bearing configurations where lubricant containment is mechanically simpler.
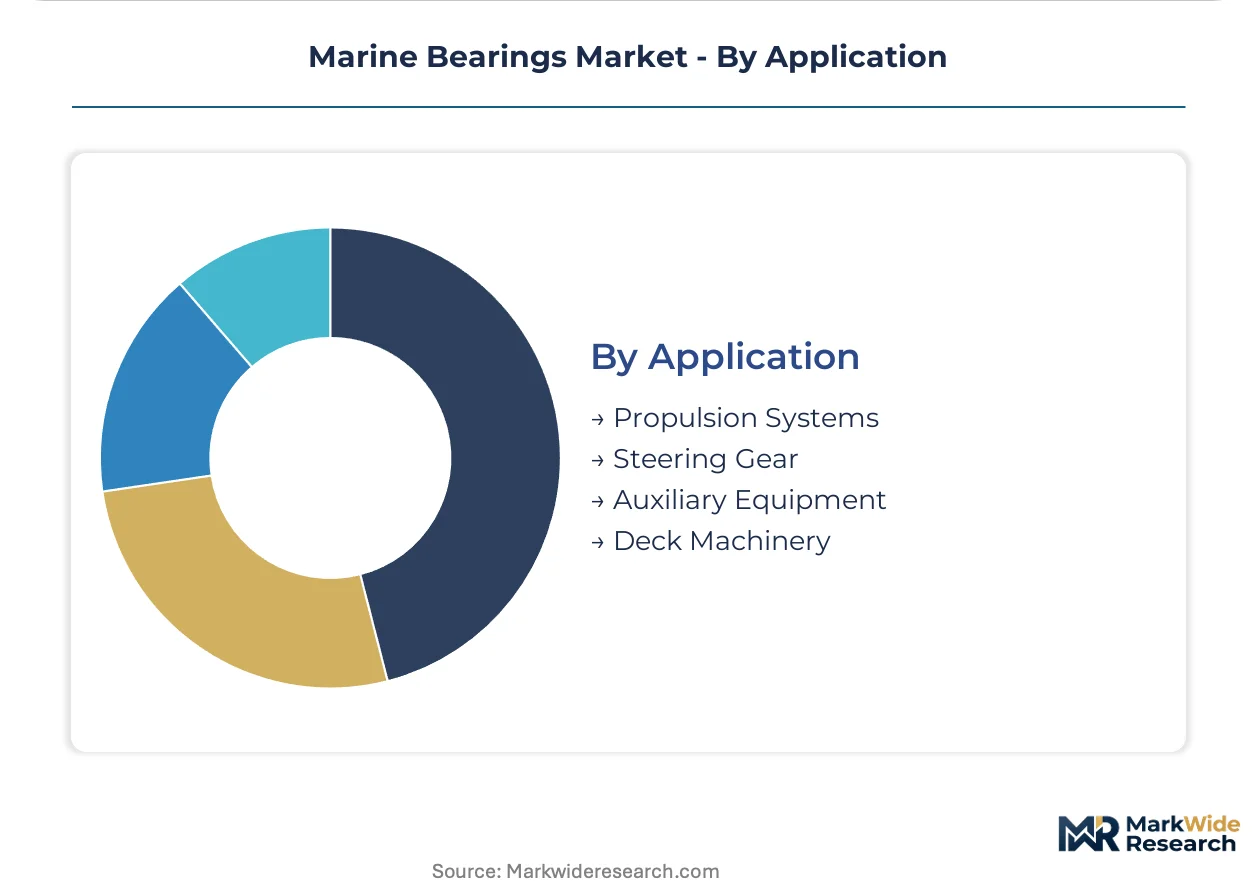
Propulsion Systems hold the dominant share, while Steering Gear is advancing most quickly as rudder bearing specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine bearing consumption patterns diverge sharply by geography: East Asian shipyards prioritize polymer-composite stern tube bearings for newbuild LNG vessels, while European and North American demand concentrates on retrofitting aging fleets with seawater-lubricated alternatives.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive polymer stern tube bearing procurement for LNG-fueled container vessels. Korean Register certification protocols validate seawater-lubricated designs for polar code applications. Ulsan and Geoje shipbuilding clusters absorb over 30% of global high-performance marine bearing output for newbuild programs.
China
State-owned shipyards at Dalian and Shanghai scale construction of dual-fuel bulk carriers requiring compatible bearing architectures. China Classification Society rules on lubricant discharge documentation tighten supplier qualification requirements. Yangtze River Delta manufacturing bases now produce domestically formulated PTFE-bronze composites for captive shipyard consumption.
Germany
Naval defense procurement from Thyssenkrupp Marine Systems specifies polymer-composite stern tube bearings for next-generation submarines. Germanischer Lloyd certification timelines for ice-class polymer-ceramic hybrids extend 18-24 months. Hamburg and Bremen port authorities mandate environmental product declarations for bearing replacements on EU-trading vessels.
Japan
Japan Maritime Self-Defense Force destroyer programs validate seawater-lubricated polymer bearings for military reliability standards. METI subsidizes domestic bearing formulators developing fluoropolymer alternatives with reduced PFOA residuals. Nagasaki and Kure shipyards integrate polymer stern tube systems into indigenous LNG carrier designs.
United States
EPA Vessel General Permit enforcement drives documented lifecycle footprint requirements for bearing retrofits on Great Lakes and coastal fleets. US-flag operators in Louisiana and Texas petrochemical transport sectors convert aging oil-lubricated stern tubes to polymer cartridges. American Bureau of Shipping rules on subsea bearing qualification create aftermarket service attach-rate opportunities.
Marine Bearings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in marine bearings. Full-system integrators bundle bearings within turnkey propulsion contracts, capturing shipyard procurement efficiencies and eliminating standalone component bidding. Polymer-formulation specialists and elastomer-compounding experts occupy distinct niches where material science depth commands premium positioning. Competitive moves center on backward integration into fluoropolymer resin supply and captive certification services that compress approval timelines with classification societies.
Within the integrated propulsion tier, Wärtsilä and MAN Energy Solutions exemplify full-system bundling strategies that lock in bearing volumes through shipyard-direct relationships. SKF anchors the condition-monitoring vector, extending service intervals through integrated sensor systems. Trelleborg AB occupies a position among elastomer-polymer compounding specialists, leveraging rubber-formulation depth for high-performance rudder and stern tube applications.
| Leading Market Players |
|---|
| Trelleborg AB |
| Lagersmit B.V. |
| SKF |
| MAN Energy Solutions SE |
| NSK Ltd. |
| Wärtsilä |
| Schaeffler Group |
| König Maschinen GmbH |
| Thordon Bearings Inc. |
| Others |
Supply & Pricing Matrix
IMO 2023 MARPOL Annex VI certification gates both supplier qualification and price differentiation simultaneously, forcing bearing formulators to absorb 18-24 month validation costs while shipyards consolidate procurement around integrated propulsion packages. This regulatory chokepoint stratifies the market into certified premium tiers and uncertified commodity alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement at South Korean mega-yards, compressing spot market liquidity for standalone bearing suppliers. Price differentiation separates DNV-certified polymer-ceramic hybrids from uncertified bronze-steel alternatives, with certification grade and volume scale driving tier separation. Cost compression in commodity bronze bearings is intensifying because Chinese yards leverage captive PTFE-bronze formulation capabilities. Fishing vessel operators exhibit highest price sensitivity, while naval defense procurement shows lowest sensitivity due to reliability mandates.
Supply Chain Analysis
Fluoropolymer resin production concentrates in China, Japan, and the United States, creating feedstock dependency for PTFE-bronze composite formulators. Virgin PTFE supply draws from refrigerant chemical markets, with elastomeric alloy bonding operations anchored in Germany and Sweden. Single-source vulnerability runs through Chinese virgin fluoropolymer capacity, where environmental enforcement intermittently disrupts resin availability. Distribution runs through shipyard-integrated procurement channels, with Wärtsilä and Siemens Energy capturing bearing volumes within turnkey propulsion contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across IMO, EU MRV, and EPA jurisdictions creates niche opportunities for specialized certification services and regional formulation expertise. The accelerating retrofit cycle in aging German and Japanese commercial fleets opens aftermarket entry points outside consolidated newbuild procurement.
For Market Incumbents: Compound defensive positioning by backward integration into virgin PTFE supply chains and captive Korean Register certification services that compress approval timelines. SKF's condition-monitoring bundling and Trelleborg's elastomer compounding depth illustrate how material-science moats resist margin erosion from Chinese captive production. Prioritize classification society joint-validation programs for ice-class polymer-ceramic hybrids before Lloyd's Register bottlenecks widen. For New Entrants and Emerging Players: Aftermarket environmental compliance documentation for US-flag operators under EPA Vessel General Permit rules represents an under-served service layer where incumbents focus on hardware. German commercial fleet retrofit demand offers the most penetrable geography, with drop-in polymer bearing cartridges replacing aging oil-lubricated stern tubes. Pursue shipyard-direct technical service relationships rather than competing for bundled newbuild contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polymer-formulation specialists holding DNV and Korean Register certifications but lacking integrated propulsion bundling capabilities. Five-to-ten year viability hinges on regulatory enforcement durability rather than commodity cycle exposure. Watch classification society readiness to certify novel polymer-ceramic hybrids for polar code applications as the inflection signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin PTFE Supply | Captive fluoropolymer resin production insulates margin predictability from refrigerant market volatility. |
| Classification Society Joint Certification | Collaborative validation with DNV or Korean Register compresses 18-24 month approval timelines for ice-class bearings. |
| Aftermarket Compliance Service Bundling | EPA Vessel General Permit documentation creates attach-rate potential beyond hardware replacement revenue. |
| Shipyard-Direct Technical Partnership | Hyundai Heavy Industries and Samsung Heavy Industries relationships bypass integrated propulsion bundling constraints. |
| Polymer-Ceramic Hybrid R&D Investment | Silicon nitride and zirconia formulations penetrate Azipod-type electric propulsion pods where electromagnetic compatibility dominates. |
Research Methodology
A spread of perspectives from shipyard procurement directors, marine engineering superintendents, classification society surveyors, and fluoropolymer resin suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, Lloyd's Register certification registries, and SEC filings from listed marine equipment suppliers. Bottom-up vessel orderbook analysis and top-down macro fleet projections were triangulated to anchor volume estimates.
Segmentation dimensions modeled include bearing architecture type, material formulation grade, end-use application maturity, and regional regulatory enforcement intensity across the projection horizon. CAGRs were derived from regression analysis against historical fleet renewal cycles and regulatory compliance deadline clustering. Forecast inputs incorporated shipyard capacity utilization at Ulsan and Geoje clusters, plus fluoropolymer resin price elasticity from refrigerant chemical market correlations.
Underlying assumptions cover sustained IMO MARPOL Annex VI enforcement, stable East Asian shipbuilding cluster concentration, and virgin PTFE supply continuity, with deviation risk concentrated in classification society certification bottlenecks and geopolitical disruption to Chinese resin production. Practitioners should keep alternative scenarios live as EU Green Deal Fit for 55 implementation timelines and polar code ice-class demand evolution reshape qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Controllable Pitch Marine Propeller Market
Marine
Ballast Water Management Market
Marine
Electric Ferry Market
Marine
Electric Boat and Ship Market
Marine
Rescue Boats Market
Marine
Electric Boat Market
Marine
Sea Scooter Market
Marine
Marine Salvage Services Market
Marine
Hydrofoil Market
Marine
Marine Gas Oil Market
Marine
Marine Growth Removal Tool Market
Marine
Buoys and Beacon Market
Marine
Marine Fuel Injector Market
Marine
Tele-Operated Marine Drone Market
Marine
Sliding Fender Market
Marine
Yacht Shell Doors Market