
 Marine VFD Market | 2026-2036
Marine VFD Market Size, Share, and Industry Trends Forecast 2026-2036
Marine VFD Market Analysis
IMO 2023 energy efficiency regulations is recalibrating the cost-of-entry calculus for marine VFD suppliers, forcing compliance investments that favor scaled incumbents. ABB leverages its integrated powertrain portfolio to anchor retrofit contracts across European commercial fleets. Siemens Energy competes through its specialized medium-voltage drive architectures for offshore support vessels. WEG sustains cost leadership in low-voltage propulsion systems across Latin American and Southeast Asian shipyards.
A marine variable frequency drive modulates motor speed and torque by varying input frequency and voltage, typically operating across 380V to 13.8kV ranges depending on vessel power requirements, with pulse width modulation serving as the dominant switching topology for propulsion precision. The device enables fuel optimization, mechanical stress reduction, and emission compliance in maritime propulsion, pumping, and cargo handling systems. Medium voltage VFDs command the dominant share of newbuild propulsion specifications due to rising vessel tonnage and electrification intensity. Direct torque control technology is displacing scalar methods in dynamic positioning thrusters where millisecond-level torque response prevents station-keeping drift. Offshore support vessels represent the fastest-growing end-user category as drillship and construction vessel fleets expand under charterer decarbonization mandates.
The International Maritime Organization enforces EEDI Phase 3 and forthcoming CII rating mechanisms that directly mandate variable speed solutions for engine-load optimization. Classification societies including DNV and Lloyd's Register incorporate VFD performance verification into type-approval protocols for electric propulsion systems. National regulators such as China's MEE and the EPA's marine diesel programs impose emission thresholds that drive converter retrofits on existing tonnage. Stakeholders must monitor the divergence between regional enforcement timelines and the readiness of shipyard electrical infrastructure to absorb higher-voltage drive platforms.
Market Dynamics
Dual carbon mandates across major shipbuilding economies are compressing specification cycles for marine electrical systems, forcing converter manufacturers to accelerate platform development timelines while maintaining classification society certifications.
Growth Catalysts
- IMO EEDI Phase 3:The International Maritime Organization's tightened energy efficiency design index mandates variable speed propulsion for newbuild container ships and bulk carriers, eliminating fixed-speed alternatives from specification sheets.
- Offshore wind installation vessels:Jones Act-compliant construction fleets in the United States and European-flagged jack-up units are specifying medium-voltage drives for precise jacking and positioning operations.
- Direct torque control algorithms:Millisecond-level torque response capabilities in dynamic positioning thrusters prevent station-keeping drift, converting charterer reliability requirements into technical specifications.
Market Restraints
- IGBT and SiC semiconductor supply:Power module lead times from Japanese and German foundries extend converter delivery schedules, constraining shipyard throughput during peak ordering windows.
- Classification society fragmentation:Divergent type-approval protocols between Lloyd's Register, DNV, and Bureau Veritas force redundant testing cycles, inflating certification costs for multi-flag operators.
- Skilled marine electrical technicians:Shortages of personnel qualified for medium-voltage commissioning and fault diagnosis limit retrofit deployment velocity in European and North American ports.
Strategic Opportunities
- Brazilian pre-salt support fleet:Petrobras charter requirements for dynamic positioning class 3 vessels are opening specification windows for integrated powertrain suppliers with local service presence.
- Battery-hybrid retrofit kits:Convergence of lithium-ion energy storage with existing diesel-electric architectures creates upgrade pathways for aging offshore supply vessels facing CII downgrades.
- China MEE port emission controls:The Ministry of Ecology and Environment's shore power mandates at Yangtze River and Pearl Delta ports are stimulating demand for shore connection converters and onboard VFD synchronization systems.
Industry Challenges
- Legacy analog control system integration:Retrofit projects on 1990s-era tonnage require protocol translation layers between modern digital drives and existing automation architectures, extending commissioning timelines.
- Medium-voltage cable routing:Shipyard electrical infrastructure constraints in Southeast Asian facilities limit adoption of 6.6kV and 11kV propulsion systems despite superior efficiency profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine VFD Market |
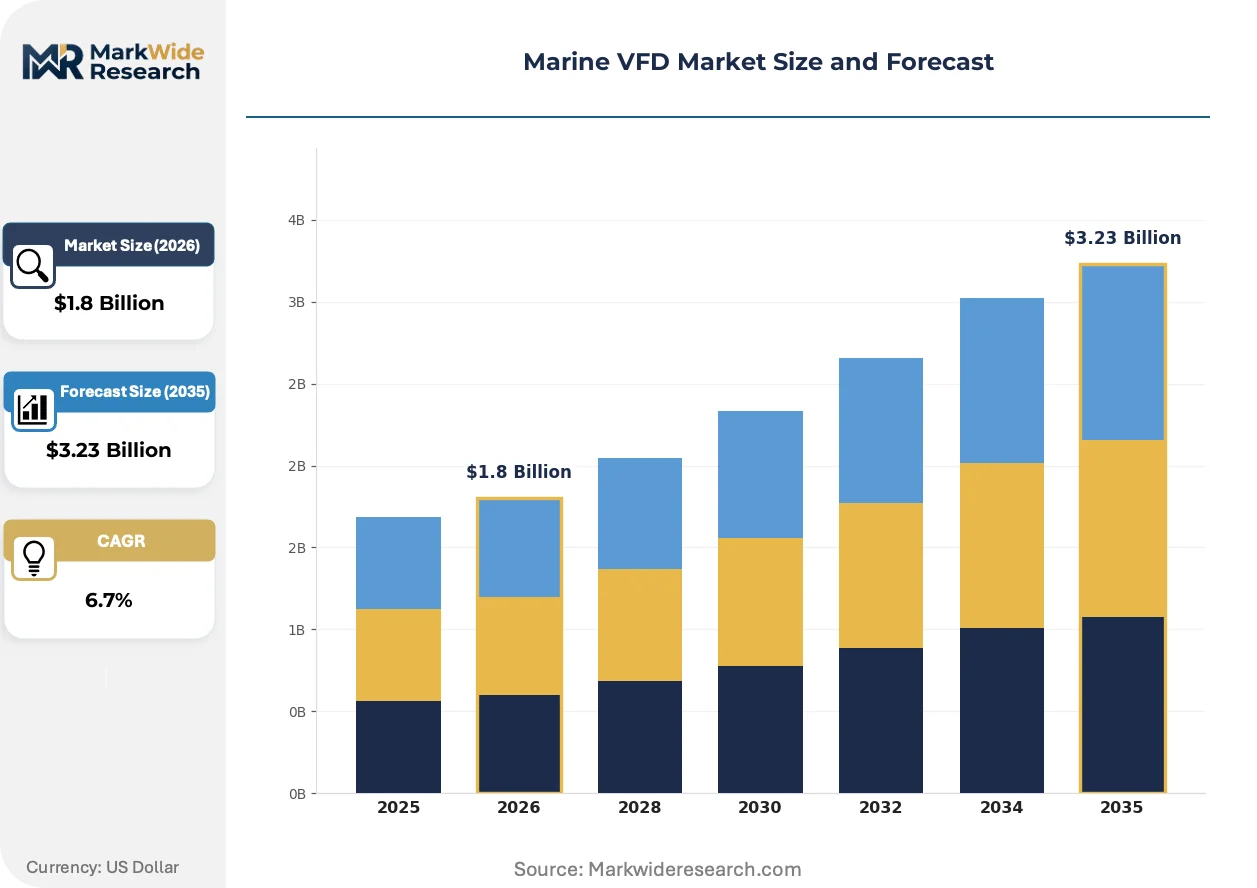
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage VFDs, Medium Voltage VFDs, High Voltage VFDs, Multi-level VFDs End User: Commercial Vessels, Cargo Ships, Passenger Ships, Offshore Support Vessels Technology: Pulse Width Modulation, Direct Torque Control, Vector Control, Sine Wave Control Application: Propulsion Systems, Pump Control, HVAC Systems, Crane Control |
| Companies Covered | Rockwell Automation, WEG, ABB, Yaskawa, Invertek Drives, Siemens Energy, Mitsubishi Electric, Eaton, Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine VFD Market Emerging Trajectories
Silicon carbide power semiconductors and model-predictive control algorithms are compressing converter size-to-power ratios while tightening harmonic distortion limits, reshaping electrical room layouts and specification priorities simultaneously.
Silicon carbide switching devices operate at higher frequencies with reduced thermal losses compared to silicon IGBTs, enabling compact liquid-cooled converter cabinets. Offshore support vessel operators in the North Sea and Gulf of Mexico are specifying SiC-based drives for space-constrained engine rooms. The technology is expanding into cruise ship propulsion applications where reduced weight and volume translate directly to passenger capacity economics.
China's MEE is enforcing GB 15097 emission standards for domestic vessels operating in emission control areas, mandating engine load optimization through variable speed control. Shipyards in Jiangsu province are integrating VFDs into standard propulsion packages for coastal bulk carriers. The regulation is accelerating converter adoption in inland waterway fleets previously exempt from international convention requirements.
Charterers are unbundling propulsion system availability guarantees from vessel day rates, creating separate performance contracting structures. Offshore drilling contractors now specify mean-time-between-failure metrics for electrical drives independent of hull and machinery clauses. This shift is most pronounced in Norwegian and UK North Sea operations where operating expenditure transparency drives supplier selection criteria.
Marine VFD Market Segmentation
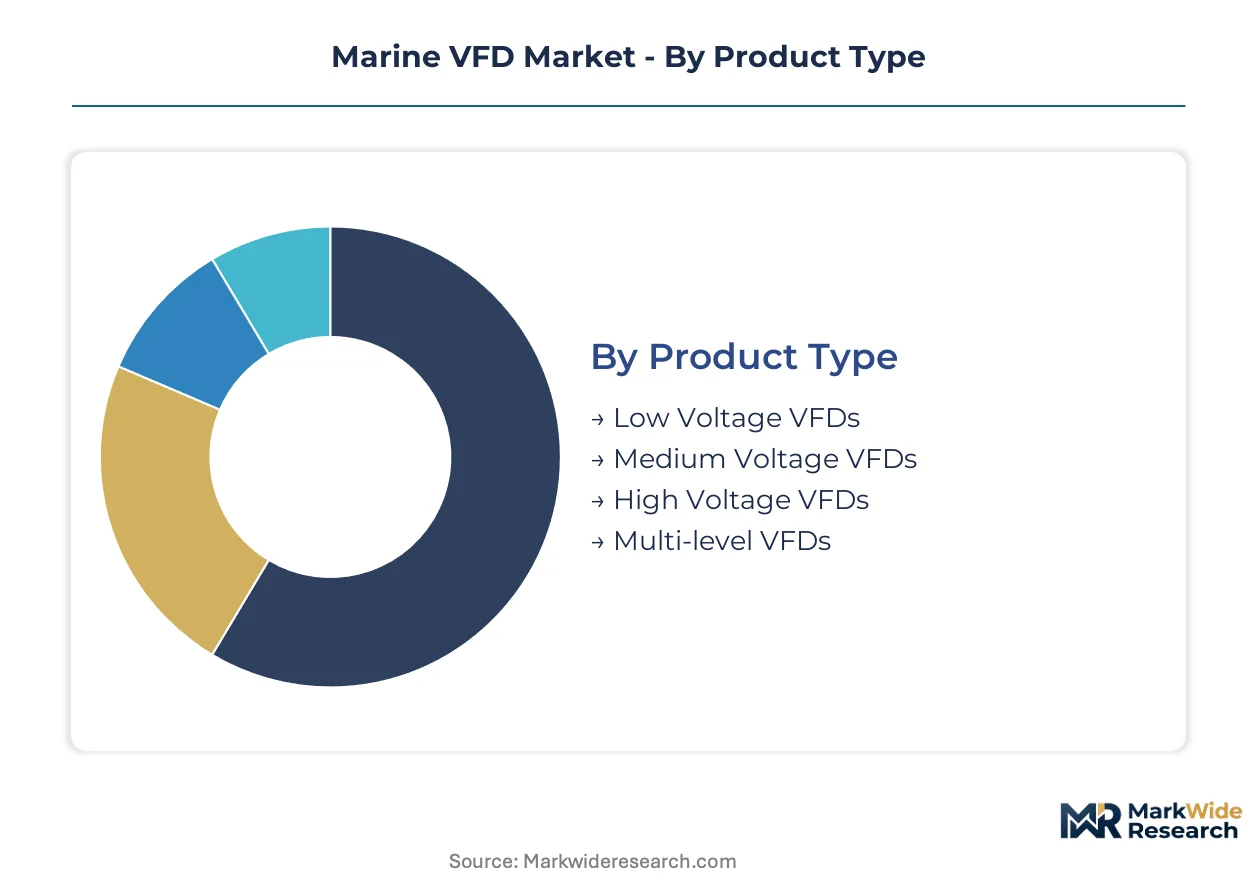
Marine VFD specifications diverge sharply across voltage classes and vessel types, with classification society type-approval requirements fragmenting procurement workflows. Procurement teams must align converter selections with IMO EEDI compliance tiers and flag-state electrical codes.
Product Type:
Certification burden varies by voltage tier: Lloyd's Register and DNV mandate separate testing protocols for medium-voltage versus low-voltage platforms, while high-voltage systems require additional fault-ride-through verification.
- Low Voltage VFDs:Operating between 380V and 690V, these converters employ IGBT switching modules for pump and fan applications on coastal bulk carriers. Demand clusters in China's Jiangsu province shipyards where state-backed consolidation drives specification upgrades for inland waterway fleets.
- Medium Voltage VFDs:Spanning 2.3kV to 13.8kV with multi-level topologies, these systems anchor electric propulsion for container ships and offshore support vessels. Norwegian and UK North Sea charterers specify these for dynamic positioning reliability under unbundled performance contracts.
- High Voltage VFDs:Exceeding 6.6kV for megawatt-class cruise ship propulsion, requiring specialized cable routing and liquid cooling infrastructure.
- Multi-level VFDs:Cascaded H-bridge architectures reducing harmonic distortion for sensitive naval and research vessel applications.
Leading the category by volume: Medium Voltage VFDs. Growing fastest: Multi-level VFDs.
End User:
Charterer decarbonization mandates reshape specification intensity across vessel categories, with offshore contractors unbundling electrical availability guarantees from day-rate structures.
- Commercial Vessels:Tugs and workboats under 5,000 GT specify compact low-voltage drives for harbor maneuvering. Brazilian pre-salt Petrobras charters are opening specification windows for integrated powertrain suppliers with local service presence.
- Cargo Ships:Bulk carriers and tankers face CII rating pressure driving retrofits. China's MEE port emission controls at Yangtze River ports stimulate shore connection converter demand for these fleets.
- Passenger Ships:Cruise vessels prioritize SiC-based compact converters to maximize passenger capacity economics.
- Offshore Support Vessels:Drillships and construction units specify millisecond-level torque response for station-keeping precision.
Commercial Vessels dominate procurement volume. Offshore Support Vessels are expanding most quickly under charterer reliability mandates.
Technology:
Control algorithm selection determines harmonic compliance and torque precision, with direct torque control displacing scalar methods in dynamic positioning thrusters.
- Pulse Width Modulation:Dominant switching topology using carrier frequencies between 2-8kHz for general-purpose pump and HVAC applications across Southeast Asian shipyards.
- Direct Torque Control:Model-predictive algorithms achieving sub-millisecond torque response without encoder feedback. Offshore wind installation vessels in the US Jones Act fleet specify this for jacking system precision.
- Vector Control:Field-oriented architectures for high-performance crane and winch applications requiring full torque at zero speed.
- Sine Wave Control:Filtered output topologies for sensitive naval electronics and research instrumentation.
Pulse Width Modulation leads installed base. Direct Torque Control is gaining share fastest in offshore specifications.
Application:
System integration complexity varies by mechanical coupling, with propulsion drives requiring shaft-line torsional analysis absent in pump control retrofits.
- Propulsion Systems:Azimuth thrusters and podded drives demand coordinated multi-converter control with ride-through capability. European commercial fleets anchor retrofit contract volumes as IMO EEDI Phase 3 eliminates fixed-speed alternatives.
- Pump Control:Ballast and cooling water systems specify simpler scalar control, though battery-hybrid retrofits are creating upgrade pathways for aging offshore supply vessels.
- HVAC Systems:Fan and compressor drives prioritizing energy recovery over torque precision.
- Crane Control:Regenerative braking and anti-sway algorithms for cargo handling productivity.
Propulsion Systems command specification value. Pump Control shows steepest expansion trajectory in hybrid retrofit kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang shipbuilding clusters concentrate converter demand through state-backed yard consolidation and port emission mandates. Norwegian offshore contractors unbundle electrical availability guarantees from day-rate structures. Brazilian pre-salt charter requirements open specification windows for integrated powertrain suppliers.
China
Jiangsu province shipyards specify medium-voltage drives for coastal bulk carriers under MEE port emission controls. The Ministry of Ecology and Environment enforces GB 15097 standards at Yangtze River and Pearl Delta ports. Zhejiang facilities integrate VFDs into standard propulsion packages as inland waterway fleets face new compliance tiers.
Norway
North Sea offshore contractors demand millisecond-level torque response for dynamic positioning reliability. The Norwegian Maritime Authority aligns with IMO EEDI Phase 3 implementation timelines. Stavanger and Bergen clusters anchor specification intensity for drillship and construction vessel fleets.
Brazil
Petrobras charter requirements for DP-class-3 vessels drive integrated powertrain procurement. The national petroleum regulator mandates station-keeping precision standards for pre-salt support fleets. Rio de Janeiro state concentrates service presence requirements for converter suppliers.
United States
Jones Act-compliant offshore wind installation vessels specify medium-voltage drives for jacking operations. The EPA's marine diesel programs impose emission thresholds on existing tonnage. Gulf Coast shipyards face converter delivery constraints during peak ordering windows.
Germany
Commercial fleet retrofits anchor contract volumes as EEDI Phase 3 eliminates fixed-speed alternatives. The Federal Maritime and Hydrographic Agency enforces classification society alignment with EU emission regulations. Hamburg and Bremerhaven clusters drive specification upgrades for container ship propulsion systems.
Marine VFD Market Vendor Landscape
European producers anchor the premium-tier segment; Asian specialists hold cost-leadership positions in standardized platforms. The vendor structure concentrates around integrated powertrain suppliers and component-focused drive manufacturers. Two strategic archetypes dominate: full-system integrators bundling propulsion and control, and pure-play converter specialists optimizing switching topologies. Competitive moves center on classification society certification expansion and localized service network deployment.
Among diversified industrial automation groups, Rockwell Automation and Siemens Energy occupy positions spanning marine and offshore applications. WEG exemplifies the cost-optimized archetype across Latin American and Southeast Asian shipyards. ABB anchors the integrated powertrain tier through retrofit contract penetration in European commercial fleets. These three represent distinct competitive vectors: automation breadth, regional cost leadership, and system integration depth.
| Leading Market Players |
|---|
| Rockwell Automation |
| WEG |
| ABB |
| Yaskawa |
| Invertek Drives |
| Siemens Energy |
| Mitsubishi Electric |
| Eaton |
| Danfoss |
| Others |
Supply Flow & Price Mechanics
European commercial fleet operators and Petrobras charterers concentrate procurement volumes, anchoring project-based contract pricing with heavy after-sales service bundling. Long converter lead times from power semiconductor foundries compress shipyard ordering windows, forcing buyers to absorb premium scheduling costs or accept standard-tier delivery slots.
Pricing Analysis
Premium scheduling for sub-six-month delivery carries surcharges against standard-tier contracts with twelve-month horizons. Pricing stratifies across integrated powertrain packages, standalone converter units, and basic pump-control modules, with differentiation driven by classification society certification tier and localized service network depth. Cost compression in low-voltage coastal bulk carrier specifications intensifies as Chinese state-backed yard consolidation consolidates procurement leverage. Southeast Asian shipyards exhibit highest price sensitivity due to infrastructure constraints limiting medium-voltage adoption, while Norwegian offshore contractors prioritize availability guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German IGBT and SiC power module foundries, where foundry capacity constraints extend converter delivery schedules. Manufacturing draws from China for magnetic components and cooling systems, Germany for precision control electronics, and Japan for power semiconductors. Tariff exposure on semiconductor imports into US Gulf Coast shipyards compounds delivery risk during peak offshore wind vessel ordering windows. Distribution runs through authorized marine electrical distributors with classification society certification capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power semiconductors are displacing silicon IGBT architectures across offshore support vessel specifications, compressing converter size-to-power ratios while tightening harmonic compliance thresholds.
For Market Incumbents: Hedge semiconductor supply exposure through captive allocation agreements with Japanese foundries or backward integration into module packaging. Defend retrofit contract positions in European commercial fleets by embedding shore power synchronization capabilities ahead of China's MEE port mandate expansion. Certification investment in DNV and Lloyd's Register multi-flag protocols preserves pricing power against Asian cost competitors. For New Entrants and Emerging Players: Brazilian pre-salt support vessel operators represent the most penetrable buyer archetype, with Petrobras DP-class-3 charter requirements opening specification windows for suppliers with Rio de Janeiro service presence. Target battery-hybrid retrofit kits for aging offshore supply vessels facing CII downgrades, where incumbent powertrain suppliers lack agile upgrade pathways. Lead with shore connection converter integration as the go-to-market wedge against legacy propulsion specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor converter specialists with stranded classification society certifications in European maritime clusters, where yard consolidation has compressed smaller vendor margins. Long-term viability rests on SiC technology transition completion and offshore wind installation vessel order flow sustainability. Watch US Jones Act jack-up unit contracting velocity as the inflection signal for medium-voltage drive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Transition | Enables compact liquid-cooled cabinets for space-constrained North Sea engine rooms. |
| Classification Society Multi-Flag Certification | Reduces redundant testing cycles for Lloyd's Register, DNV, and Bureau Veritas protocols. |
| Localized Service Network Deployment | Secures Petrobras charter specifications requiring Rio de Janeiro maintenance presence. |
| Battery-Hybrid Retrofit Kit Development | Captures aging offshore supply vessel upgrades facing IMO CII rating pressure. |
| Shore Power Synchronization Integration | Aligns with China's MEE port emission mandates at Yangtze River and Pearl Delta ports. |
Methodological Framework
Classification society technical bulletins, IMO regulatory filings, and customs trade data formed the secondary backbone for vessel specification and converter trade flow analysis. Primary interviews with marine electrical system engineers, shipyard procurement directors, offshore vessel chartering managers, and power semiconductor distribution specialists validated technical adoption timelines and certification requirements. Bottom-up vessel order book analysis triangulated against top-down converter manufacturer revenue segmentation to anchor market sizing across voltage classes and end-use categories.
Bottom-up modeling aggregated individual vessel propulsion specifications by type, tonnage, and electrification intensity, while top-down approaches tracked supplier revenue disclosures and regional production capacity. Segmentation dimensions span voltage tier, vessel category, control technology topology, and application system, with regional regulatory cluster as an additional marine-specific dimension. CAGRs derived from fitted growth curves against historical installation data, incorporating EEDI Phase 3 compliance deadlines and offshore wind fleet expansion trajectories as demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity expansion and shipyard electrical infrastructure upgrade rates. Forecasts reflect documented assumptions on regulatory enforcement timelines and charterer decarbonization mandate intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Turbocharger Market
Marine
Sea Skimmer Market
Marine
Tele-Operated Marine Drone Market
Marine
North Sea Offshore Support Vessels Market
Marine
Shipbuilding Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Electric Ferry Market
Marine
Offshore AUV and ROV Market
Marine
Hydrofoil Market
Marine
Boat Cleat Market
Marine
Marine Glass Market
Marine
Jack-Up Vessels Market
Marine
Marine Dynamic Positioning System Market
Marine
Marine Shackle Market
Marine
Marine Winch Motors Market
Marine
Europe ROV Market