
 Marine Fender Systems Market | 2026-2036
Marine Fender Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fender Systems Market Insights
Modular fender panel configurations is recalibrating buyer choice across port infrastructure projects. Trelleborg Marine Systems leverages integrated fender-to-dolphin design capabilities to anchor large-scale terminal contracts. Yokohama Rubber Company sustains competitive positioning through advanced rubber compounding expertise. Shibata Fender Team specializes in custom-engineered solutions for constrained berth geometries.
Marine fender systems are energy-absorbing structures installed between vessels and berthing facilities, typically manufactured from natural rubber compounds, polyurethane foam cores, or reinforced elastomeric composites rated for reaction forces exceeding 1,000 kN. These systems protect hull integrity and wharf infrastructure by dissipating kinetic energy during vessel contact operations. Rubber fenders dominate installed base volumes across aging port infrastructure, while foam filled fenders capture premium positioning in offshore platform applications where deflection tolerance and saltwater corrosion resistance command higher replacement values. Composite fenders represent the fastest-expanding product configuration as hybrid material formulations reduce maintenance cycles and extend service intervals in high-tidal environments.
ISO 17357 governs high-pressure floating pneumatic fender performance testing, while PIANC guidelines establish berthing velocity and energy absorption benchmarks that shape port authority procurement specifications. The US Army Corps of Engineers mandates fender system compliance with EM 1110-2-1613 for federal navigation projects, restricting market access for uncertified suppliers. Stakeholders must monitor evolving lifecycle cost accounting methodologies as port operators shift capital allocation from initial purchase price toward total cost of ownership frameworks incorporating installation, inspection, and replacement intervals.
Market Dynamics
Port modernization programs across Southeast Asian transshipment hubs are accelerating specification upgrades from conventional rubber fenders to foam-filled composite systems, compressing replacement cycles and reshaping supplier qualification requirements.
Growth Catalysts
- ISO 17357 certification mandates:Port authorities in Vietnam and Indonesia now require high-pressure floating pneumatic fender testing compliance for all new terminal procurements, eliminating uncertified suppliers from bidding pools.
- Offshore platform expansion:Deepwater oil and gas facilities in the South China Sea prioritize foam-filled fenders for deflection tolerance in high-swell conditions, creating premium replacement demand.
- Container terminal automation:Automated berthing systems in Singapore and Port Klang demand fender panels with integrated sensor mounting points for real-time impact monitoring.
Market Restraints
- Natural rubber price volatility:Synthetic polyisoprene substitution remains limited for high-reaction-force applications, exposing manufacturers to commodity input swings.
- Federal procurement restrictions:US Army Corps of Engineers EM 1110-2-1613 compliance requirements block non-domestic suppliers from federal navigation projects.
- Steel-reinforced concrete dolphin inertia:Existing berth infrastructure in legacy ports resists retrofit to lighter composite fender configurations due to structural load-path dependencies.
Strategic Opportunities
- Philippines port privatization wave:Subic Bay and Batangas container terminal concessions specify 25-year lifecycle cost frameworks favoring low-maintenance composite systems over rubber alternatives.
- EU Green Deal procurement criteria:Carbon footprint disclosure requirements for marine infrastructure create first-mover advantage for manufacturers with verified recycled content in foam cores.
- Digital twin integration:Fender-mounted IoT strain sensors combined with predictive maintenance platforms enable performance-based service contracts with terminal operators.
Industry Challenges
- PIANC guideline implementation gaps:Inconsistent berthing velocity assumptions between port engineering consultants and fender suppliers generate specification disputes during tender evaluation.
- Composite repair technician scarcity:Foam-filled fender damage assessment and field repair require specialized elastomeric welding skills absent from conventional marine maintenance workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fender Systems Market |
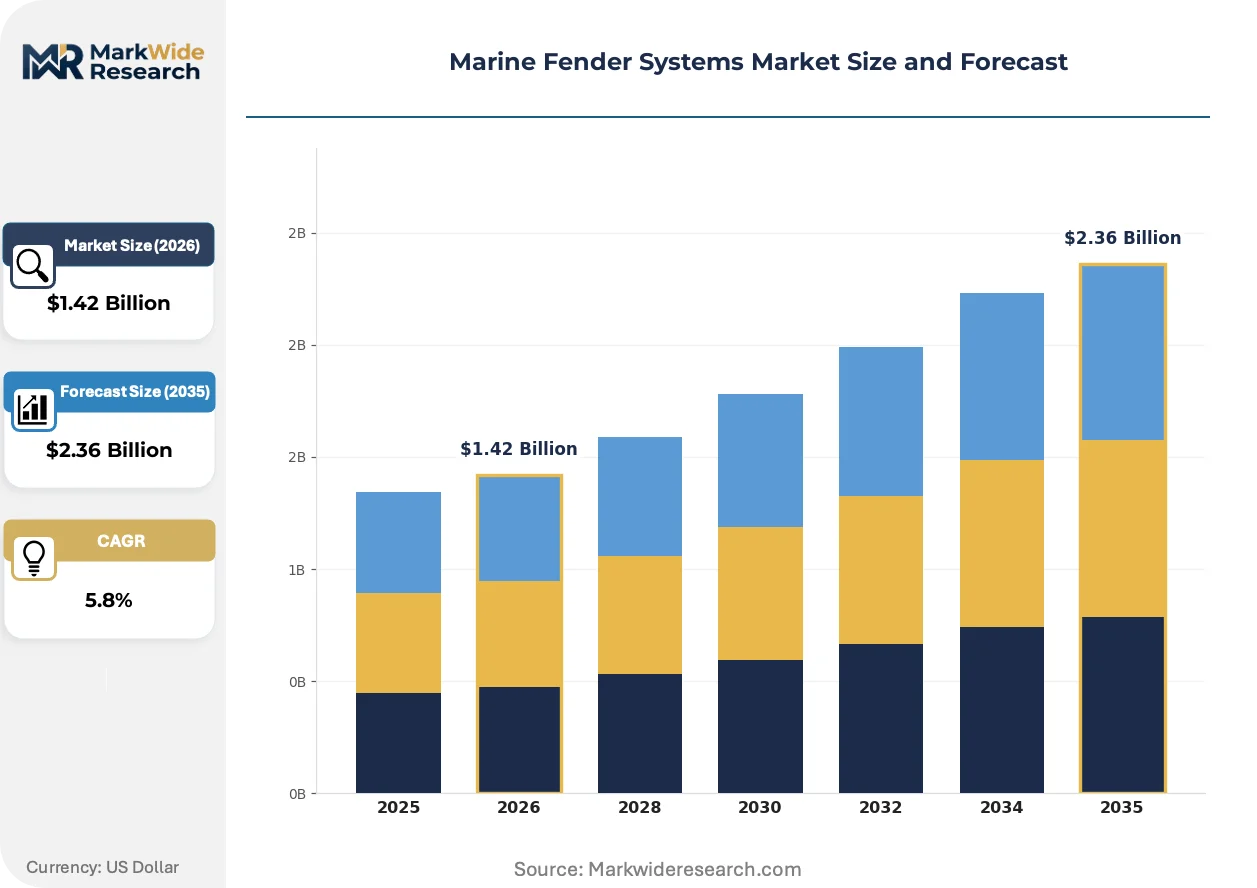
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Fenders, Foam Filled Fenders, Pneumatic Fenders, Composite Fenders, Plastic Fenders Marine Vessel Type: Container Terminals, Bulk Carriers, Tankers, Passenger Terminals, Offshore Platforms Installation Type: Permanent Mount, Floating, Portable, Semi-Permanent End User: Port Authorities, Shipyards, Harbor Operators, Offshore Contractors |
| Companies Covered | Trelleborg Marine Systems, Yokohama Rubber Company, Shibata Fender Team, Bridgestone Corporation, Sumitomo Rubber Industries, Dongjin Industrial, Atlanta Rubber Company, M.I.C. Marine Fender Manufacturing, Marinetech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fender Systems Market Trends and Innovations
Material science advances and regulatory disclosure requirements are converging to redefine competitive advantage around lifecycle performance verification rather than initial capital cost.
Hybrid polyurethane-foam fender cores with embedded fiber-optic strain monitoring is overtaking conventional rubber compounds in new-build container terminals. Singapore's Tuas mega-port specifies these systems for automated vessel berthing, compressing supplier margins on basic rubber alternatives while rewarding integrated sensor-fender packages.
REACH chemical substance registration requirements in Europe now extend to isocyanate precursors in polyurethane foam manufacturing. German and Dutch port authorities incorporate full material disclosure into environmental impact assessments, favoring suppliers with verified supply chain documentation over low-cost competitors.
Terminal operators in Indonesia and Vietnam now unbundle fender supply from installation and 10-year maintenance contracts, forcing manufacturers to compete on unit price while specialized marine contractors capture service revenue. This procurement fragmentation is most visible in Jakarta's Tanjung Priok expansion, where separate lots for fender panels, dolphin construction, and lifecycle inspection compress supplier margins.
Marine Fender Systems Market Segmentation
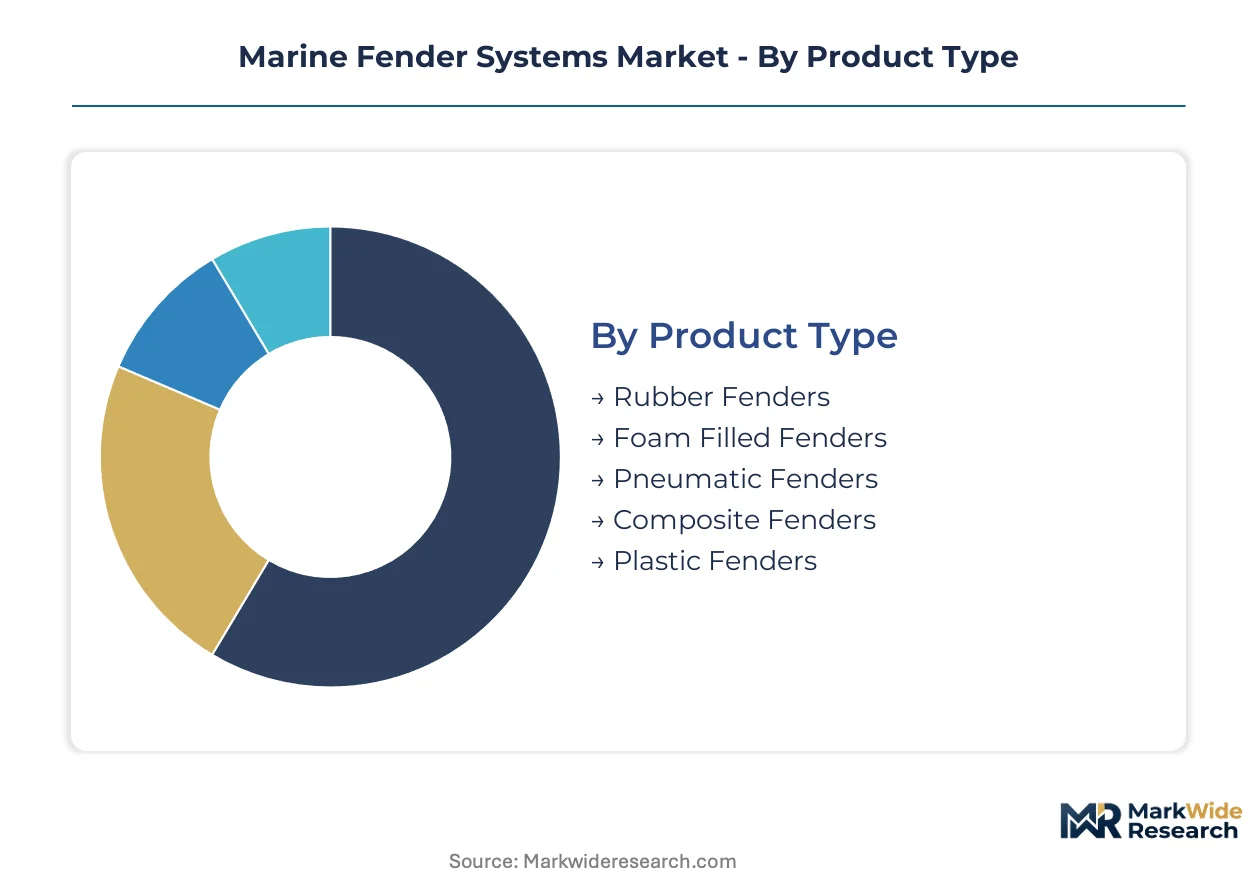
Marine fender procurement patterns diverge sharply across vessel categories and installation contexts. Port authorities weigh lifecycle cost against berthing velocity specifications, while offshore contractors prioritize deflection tolerance in high-swell environments.
Product Type:
Standardization dominates commodity rubber grades, yet customization intensity rises through foam-filled and composite configurations.
- Rubber Fenders:Natural rubber compounds molded into arch, cone, or cell configurations deliver reaction forces exceeding 1,000 kN. Aging port infrastructure in Vietnam and Indonesia sustains replacement demand despite compressed margins from commodity pricing.
- Foam Filled Fenders:Polyurethane foam cores encased in reinforced elastomeric skins provide deflection tolerance for offshore platforms in the South China Sea. Saltwater corrosion resistance commands premium positioning where replacement cycles extend beyond conventional rubber alternatives.
- Pneumatic Fenders:High-pressure floating systems governed by ISO 17357 certification requirements. Yokohama and Shibata dominate qualified supplier pools for pneumatic specifications.
- Composite Fenders:Hybrid material formulations reducing maintenance cycles in high-tidal environments. Singapore's Tuas mega-port specifies integrated sensor mounting points for automated berthing systems.
- Plastic Fenders:Recycled polymer cores meeting EU Green Deal carbon disclosure criteria for European port authorities.
Most installed capacity flows through Rubber Fenders. Expansion is steepest in Composite Fenders.
Marine Vessel Type:
Application scale ranges from high-frequency container terminal operations to intermittent offshore platform supply.
- Container Terminals:Automated berthing systems in Singapore and Port Klang demand fender panels with integrated IoT strain sensors. Real-time impact monitoring compresses supplier margins on basic configurations while rewarding integrated packages.
- Bulk Carriers:High-displacement vessel classes requiring energy absorption rated for extreme reaction forces. Port authorities in Indonesia specify 25-year lifecycle cost frameworks favoring low-maintenance systems.
- Tankers:Specialized fender geometries accommodating bulbous bow profiles and constrained berth clearances.
- Passenger Terminals:Aesthetic and low-noise specifications for cruise ship facilities in Subic Bay and Batangas.
- Offshore Platforms:Foam-filled systems prioritized for deflection tolerance in high-swell conditions across South China Sea deepwater facilities.
Procurement volume concentrates in Container Terminals. Technology upgrade intensity peaks in Offshore Platforms.
Installation Type:
Capital commitment depth varies from permanent dolphin-integrated foundations to rapidly deployable temporary systems.
- Permanent Mount:Steel-reinforced concrete dolphins with embedded fender anchoring systems. Legacy berth infrastructure resists retrofit due to structural load-path dependencies.
- Floating:Mooring-independent positioning for offshore supply vessels and dynamic positioning operations. Pneumatic and foam-filled configurations dominate this category.
- Portable:Rapid-deployment units for emergency repairs and temporary berth expansion in Tanjung Priok.
- Semi-Permanent:Modular configurations allowing seasonal repositioning for multi-use terminals in the Philippines privatization wave.
Revenue concentration sits with Permanent Mount systems. Procurement innovation is accelerating fastest in Semi-Permanent configurations.
End User:
Buyer sophistication spans federal procurement compliance to specialized marine contractor technical specifications.
- Port Authorities:Federal navigation projects in the US mandate EM 1110-2-1613 compliance, restricting market access for uncertified suppliers. Vietnamese and Indonesian authorities now require ISO 17357 certification for all new terminal procurements.
- Shipyards:New-build vessel specifications driving fender-to-hull interface standardization.
- Harbor Operators:Lifecycle cost accounting shifts from initial purchase price toward total cost of ownership frameworks incorporating installation, inspection, and replacement intervals.
- Offshore Contractors:Deepwater oil and gas facilities prioritizing foam-filled fenders for deflection tolerance in high-swell conditions.
Contract value aggregates most heavily with Port Authorities. Specification complexity is climbing fastest among Offshore Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The marine fender systems industry traces its modern scale to Japanese rubber manufacturing clusters that pioneered high-pressure pneumatic fender designs in the 1960s. Port infrastructure expansion across East Asian manufacturing hubs subsequently anchored global procurement patterns. Today, demand concentrates in Southeast Asian transshipment terminals and North American federal navigation projects.
Vietnam
Container terminal operators at Lach Huyen and Cai Mep are expanding fender procurement under port modernization programs. The Vietnam Maritime Administration now mandates ISO 17357 certification for all new terminal procurements, eliminating uncertified suppliers from bidding pools. Ho Chi Minh City and Hai Phong anchor regional transshipment hub development with automated berthing system specifications.
Indonesia
Tanjung Priok expansion and new greenfield terminals in Batam are driving specification upgrades from conventional rubber to foam-filled composite systems. Port authorities specify 25-year lifecycle cost frameworks favoring low-maintenance systems over rubber alternatives. Jakarta and Surabaya concentrate procurement volume as privatization waves reshape terminal concessions.
Singapore
Tuas mega-port development demands fender panels with integrated sensor mounting points for real-time impact monitoring in automated berthing systems. The Maritime and Port Authority enforces stringent performance verification protocols that compress supplier margins on basic configurations. The Tuas industrial zone exemplifies technology upgrade intensity across container terminal automation.
Philippines
Subic Bay and Batangas container terminal concessions under the port privatization wave specify lifecycle cost accounting favoring composite systems. The Philippine Ports Authority incorporates PIANC guideline compliance into tender evaluation criteria. Manila Bay and Batangas anchor procurement concentration as regional transshipment hub status intensifies.
United States
Federal navigation projects through the US Army Corps of Engineers mandate EM 1110-2-1613 compliance, restricting market access for uncertified suppliers. Port authorities in Houston and Long Beach are retrofitting aging berth infrastructure with sensor-integrated fender monitoring. Gulf Coast and Pacific Coast terminals concentrate procurement as container volume resilience persists.
Marine Fender Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and integrated design capabilities. The supplier base stratifies between full-service marine infrastructure contractors and specialized fender fabricators. Three archetypes dominate: rubber compound specialists with legacy port relationships, composite material innovators capturing offshore platform demand, and integrated marine systems providers bundling fender-to-dolphin engineering. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for Southeast Asian terminal modernization contracts.
Within the integrated systems tier, Trelleborg Marine Systems and Yokohama Rubber Company exemplify divergent geographic anchoring strategies. Trelleborg leverages European engineering heritage to capture lifecycle service contracts, while Yokohama draws on Japanese rubber compounding expertise to sustain pneumatic fender qualification pools. Shibata Fender Team occupies a position bridging custom engineering for constrained berth geometries with ISO 17357 certification maintenance. These three represent distinct archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Trelleborg Marine Systems |
| Yokohama Rubber Company |
| Shibata Fender Team |
| Bridgestone Corporation |
| Sumitomo Rubber Industries |
| Dongjin Industrial |
| Atlanta Rubber Company |
| M.I.C. Marine Fender Manufacturing |
| Marinetech Corporation |
| Others |
Pricing and Supply Chain Analysis
Federal navigation procurement programs in the United States anchor pricing power for certified suppliers, compressing margins for uncertified competitors while rewarding EM 1110-2-1613 compliance with premium positioning. Container terminal operators in Southeast Asia unbundle fender supply from installation contracts, forcing manufacturers toward project-based pricing with embedded lifecycle service components.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs marine fender transactions. Premium tiers capture ISO 17357-certified pneumatic systems and sensor-integrated composite panels for automated terminals in Singapore. Standard tiers serve replacement rubber fender demand across aging Vietnamese and Indonesian port infrastructure. Economy tiers address temporary portable units for emergency repairs. Price differentiation hinges on certification grade and after-sales bundling. Cost compression in standard rubber tiers is intensifying because natural rubber price volatility exposes manufacturers to commodity input swings. Port authorities in Indonesia and Vietnam exhibit highest price sensitivity, while offshore contractors in the South China Sea prioritize deflection tolerance over unit cost.
Supply Chain Analysis
Refurbishment flows for foam-filled fender cores create reverse-logistics complexity, with damaged units requiring specialized elastomeric welding skills absent from conventional marine maintenance workforces. Manufacturing concentrates in Japan, Germany, and China, with Japanese suppliers anchoring pneumatic fender qualification pools and German producers leading composite material innovation. Raw material inputs draw from natural rubber plantations in Southeast Asia, polyurethane isocyanate precursors subject to REACH registration, and steel-reinforced concrete for dolphin foundations. Single-source vulnerability sits with specialized foam core formulations. Distribution runs through marine infrastructure contractors and port authority procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in composite fender systems as port operators shift procurement criteria toward 25-year lifecycle cost frameworks that reward reduced maintenance intervals. Sensor-integrated premium tiers capture pricing power in automated terminal specifications.
For Market Incumbents: Lock in certification maintenance advantages by deepening ISO 17357 testing infrastructure and securing exclusive lifecycle service contracts with Vietnamese and Indonesian port authorities. Threats from emerging composite material specialists in China intensify as these players capture offshore platform demand with lower-cost foam-filled alternatives. Capacity addition in Batam and Hai Phong industrial zones anchors regional supply positioning. For New Entrants and Emerging Players: Launch via direct procurement relationships with Philippines port privatization concessions at Subic Bay and Batangas, where 25-year lifecycle frameworks favor new suppliers with verified composite performance data. White-space targets include semi-permanent modular configurations for multi-use terminals and recycled polymer cores meeting EU Green Deal carbon disclosure criteria. Go-to-market angle centers on field repair technician training partnerships that address scarcity in foam-filled fender damage assessment capabilities. For Investors and Strategic Acquirers: Integrated marine infrastructure contractors are the most active acquirer in this space, seeking fender-to-dolphin engineering capabilities to bundle terminal modernization contracts. Long-term viability favors suppliers with hybrid material R&D pipelines and sensor integration competencies. Acquisition target archetype: mid-cap composite specialists with ISO 17357 certification and established relationships with Southeast Asian port authorities. Signal to watch: acceleration of EU Green Deal procurement criteria adoption in German and Dutch port authority tenders.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17357 Certification Investment | Eliminates uncertified competitors from Vietnamese and Indonesian bidding pools. |
| Sensor-Fender Integration Development | Captures Tuas mega-port automated berthing specifications in Singapore. |
| Lifecycle Service Contract Expansion | Shifts revenue from unit sales to recurring inspection and replacement intervals. |
| Composite Material R&D Scale-Up | Reduces maintenance cycles for high-tidal environments in Southeast Asia. |
| Field Repair Technician Training | Addresses scarcity in foam-filled fender damage assessment capabilities. |
Research Methodology
Coverage spans Southeast Asia, North America, and Europe, with primary inputs from each region combined with secondary validation. Primary interviews engaged port authority procurement managers, marine infrastructure contractors, fender system engineering directors, and offshore platform maintenance supervisors. Secondary sources included customs and trade data for rubber and polyurethane imports, PIANC guideline documentation, ISO 17357 certification registries, and SEC filings from listed marine equipment suppliers. Bottom-up vessel berthing frequency data and top-down port infrastructure investment flows were triangulated to anchor market sizing.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. Segmentation dimensions modeled include product type, marine vessel category, installation configuration, and end-user procurement sophistication. CAGRs were derived from regression analysis against port modernization program timelines and offshore platform development pipelines. Industry-specific inputs incorporated berthing velocity specifications from PIANC guidelines and replacement cycle assumptions for rubber versus composite materials.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility and regulatory certification timeline disruptions. Forecasts reflect assumptions regarding port privatization wave progression and automated terminal adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Boat Trolling Motor Market
Marine
Marine Shaft Power Meter Market
Marine
Marine VFD Market
Marine
Marine Diesel Engine Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Swamp Boat Market
Marine
Marine Fasteners Market
Marine
Global Submarine Market
Marine
Jack-Up Vessels Market
Marine
Marine Chronometers Market
Marine
Marine and Marine Management Software Market
Marine
Boat Control Lever Market
Marine
Rescue Boats Market
Marine
Marine Communication Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Strip Market