
 Marine Electronics Market | 2026-2036
Marine Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Electronics Market Intelligence
South Korea's expansion of smart shipyard capacity is tilting the competitive landscape for marine electronics integration. This shift favors suppliers with strong OEM relationships and advanced system-on-chip capabilities. Kongsberg Maritime leverages its deep expertise in integrated bridge systems for complex commercial vessels. Garmin Ltd. dominates the recreational and light commercial segments with its user-friendly GPS and sonar technologies.
Marine electronics encompass the hardware and software systems designed for navigation, communication, and vessel monitoring. These systems often operate on standardized data protocols like NMEA 2000, ensuring interoperability between devices. While commercial shipping applications drive demand for high-specification marine radars and integrated bridge systems, the recreational boating segment represents the fastest-growing application for fish finders and GPS navigation units. Sonar systems and AIS transponders are mature, but critical for safety.
Regulatory frameworks from the International Maritime Organization, particularly SOLAS, mandate specific electronic equipment for safety. In parallel, the FCC in the United States and CE marking requirements in Europe govern radio frequency emissions and product standards for market access. Stakeholders must now decide how to position their product portfolios for the transition toward autonomous vessel operations and predictive maintenance analytics.
Market Dynamics
The concentration of new vessel construction in advanced shipbuilding hubs is the central force shaping the marine electronics market. This dynamic favors suppliers capable of deep integration with yard production schedules and complex digital architecture requirements for smart ships.
Growth Catalysts
- IMO Mandates:New International Maritime Organization regulations for emissions monitoring and enhanced vessel tracking are compelling commercial operators to invest in sophisticated, compliant electronic systems for data collection and reporting.
- Recreational Boating Demand:The leisure and sport fishing segments are driving high-volume sales of user-friendly GPS chartplotters, advanced fish finders, and autopilot systems, seeking features once exclusive to commercial vessels.
- Shipyard Modernization:New construction and retrofitting programs, particularly in South Korean and Chinese shipyards, require the installation of fully integrated bridge, navigation, and communication systems, stimulating large-scale procurement.
Market Restraints
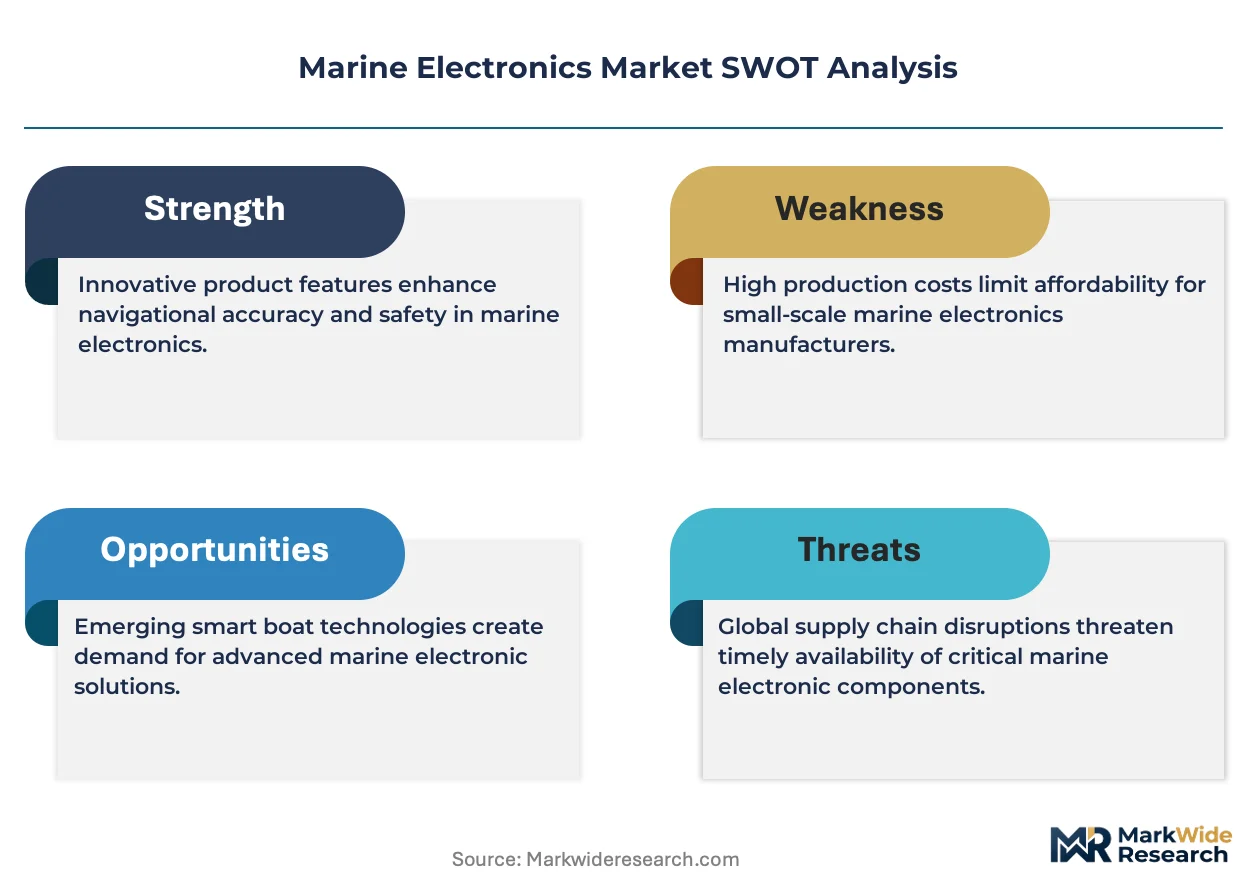
- High Installation Costs:The significant capital outlay and specialized labor required for installing and commissioning integrated bridge systems and advanced sonar arrays can be prohibitive for smaller fleet operators and owners of older vessels.
- Interoperability Hurdles:Despite standards like NMEA 2000, ensuring seamless data exchange between multi-vendor equipment on a single vessel network remains a persistent technical challenge, increasing integration complexity.
- Component Bottlenecks:The marine electronics supply chain is vulnerable to shortages of critical components, such as specialized semiconductors and marine-grade displays, which can lead to production delays and price volatility.
Strategic Opportunities
- Autonomous Vessel Systems:The development of electronics suites for unmanned and autonomous surface vessels represents a significant new market, requiring robust, redundant, and remotely managed navigation and control systems.
- Predictive Maintenance Analytics:Integrating sensor data with AI-driven software platforms offers an opportunity to provide subscription-based services for predictive maintenance, optimizing vessel uptime and reducing operational costs.
- Cybersecurity Solutions:Upcoming regulations mandating cyber risk management on vessels will create demand for new hardware and software solutions, including secure gateways, network monitoring tools, and encrypted communication systems.
Industry Challenges
- Skilled Technician Scarcity:A global shortage of technicians with the combined expertise in electronics, IT networking, and maritime systems is a key bottleneck for installation, service, and maintenance, especially in remote ports.
- Complex Certification Pathways:Navigating the multifaceted and time-consuming certification processes required by bodies like the IMO, FCC, and European authorities for CE marking slows the introduction of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Electronics Market |
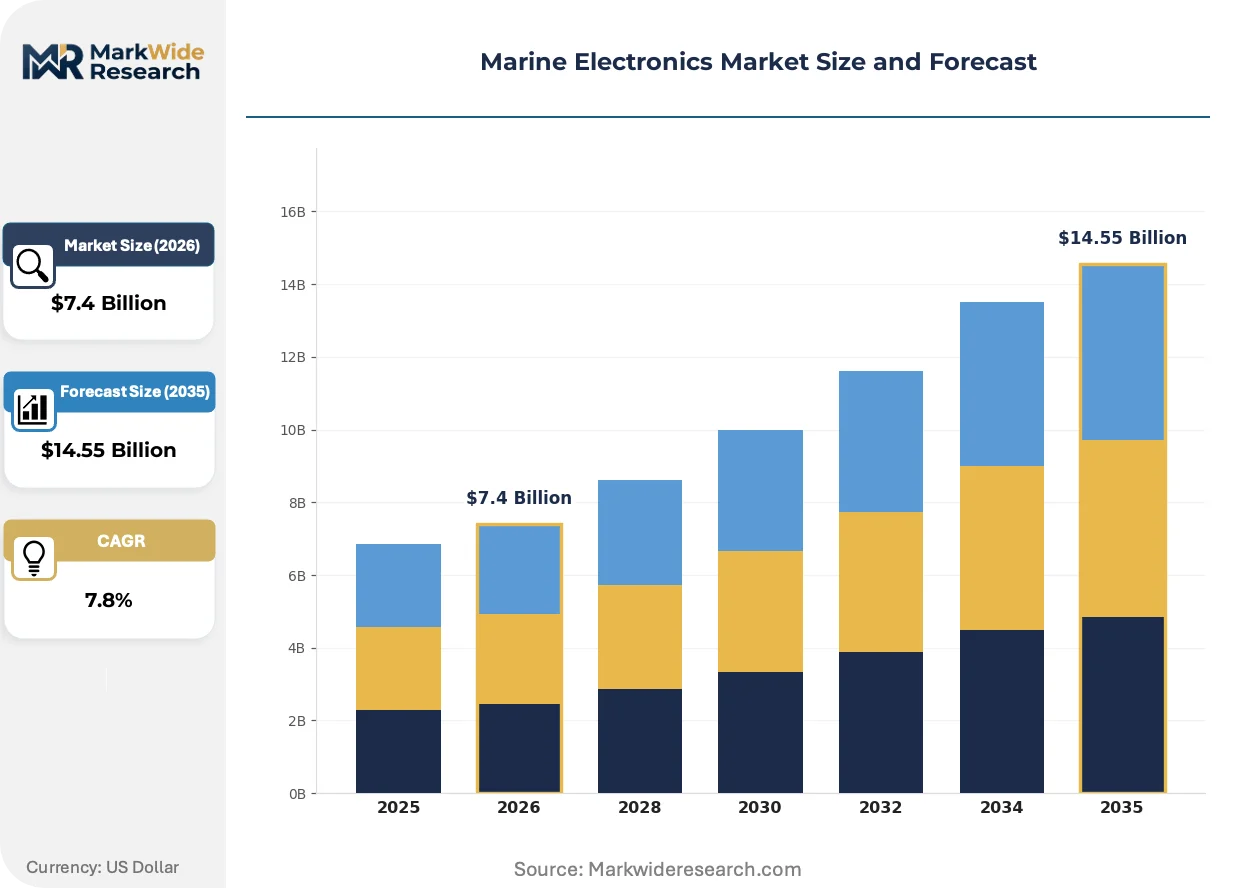
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $14.55 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sonar Systems, Marine Radars, GPS Navigation, Communication Devices, Fish Finders, AIS Transponders Technology: Satellite Communication, Digital Signal Processing, Automatic Identification Systems, Integrated Bridge Systems, Acoustic Monitoring, Electronic Chart Display Application: Commercial Shipping, Recreational Boating, Offshore Exploration, Naval Defense, Environmental Monitoring, Research Vessels End User: Shipbuilders, Offshore Contractors, Maritime Agencies, Fishing Fleet Operators, Survey Companies, Port Authorities |
| Companies Covered | Navico Group, Kongsberg Maritime, Garmin Ltd., Intellian, KVH Industries, Inc., Furuno Electric Co., Ltd., Raymarine, Airmar, Brunswick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Electronics Market Strategic Shifts & Innovations
The evolution from standalone devices to interconnected digital ecosystems defines the current trajectory of the marine electronics market. This shift is driven by a convergence of onboard data processing capabilities, new regulatory pressures, and changing expectations from vessel operators for real-time information.
System-on-Chip (SoC) architectures are a key technological driver, integrating functions like GPS, sonar, and radar processing onto a single component. Commercial and recreational vessel builders are adopting these solutions to reduce the size, cost, and power consumption of helm electronics. The use of powerful SoCs is collapsing the distinction between previously separate hardware boxes, enabling a more unified and software-defined bridge environment.
New regulations, particularly the IMO's resolution on Maritime Cyber Risk Management, are creating a non-negotiable demand for secure electronics. This mandate requires shipowners to incorporate cybersecurity into their vessel safety management systems, making it subject to audit. The integrated bridge and satellite communication segments are most affected, forcing manufacturers to embed security features and provide verifiable, secure software update paths.
A notable behavioral shift is occurring as vessel operators increasingly prioritize access to subscription-based data services over one-time hardware purchases. This trend is disrupting the traditional sales model, favoring suppliers who offer integrated packages including real-time weather data, automatic chart updates, and remote diagnostics. The commercial shipping and superyacht sectors, where operational data provides a clear competitive advantage, are at the forefront of this adoption pattern.
Marine Electronics Market Segmentation
The marine electronics market comprises a complex ecosystem of hardware and software solutions, each tailored to distinct operational requirements and vessel types. Understanding these granular segments allows stakeholders to identify specific demand drivers, technological imperatives, and end-user preferences across the maritime industry.
Product Type:
The diverse use-case spectrum for marine electronics dictates distinct product requirements across various vessel types and operational needs.
- Marine Radars:These systems use radio waves to detect objects, measure range, and determine bearing, crucial for navigation and collision avoidance in all weather conditions. Commercial shipping and naval defense applications drive significant demand for high-specification radar units, particularly in new vessel construction.
- GPS Navigation:Global Positioning System (GPS) units provide precise location data, facilitating route planning, chart plotting, and safe passage through complex waterways. Recreational boating and light commercial segments extensively adopt user-friendly GPS chartplotters, often integrated with multifunction displays.
- Sonar Systems:Sonar systems utilize sound propagation to detect objects underwater, map the seabed, and measure water depth for navigation and scientific purposes.
- Communication Devices:This category includes VHF radios, satellite phones, and GMDSS-compliant equipment, ensuring voice and data exchange for safety and operational efficiency.
- Fish Finders:Specialized sonar devices designed to locate fish schools and underwater structures, primarily used by recreational anglers and small-scale commercial fishing operations.
- AIS Transponders:Automatic Identification System (AIS) transponders broadcast vessel identification, position, course, and speed, enhancing collision avoidance and maritime domain awareness.
The dominant share belongs to Marine Radars, while Fish Finders are closing the gap fastest in terms of unit sales.
Technology:
Specific technological advancements underpin the varied functionalities required by different marine applications, from deep-sea exploration to coastal navigation.
- Integrated Bridge Systems:These advanced systems centralize navigation, communication, and vessel control functions into a unified, ergonomic workstation on complex commercial vessels. New smart ship projects, especially in South Korean shipyards, mandate the installation of highly integrated bridge solutions.
- Satellite Communication:Satellite communication technologies provide global connectivity for voice, data, and internet services, essential for vessels operating beyond terrestrial network range. Offshore exploration platforms and long-haul commercial shipping rely heavily on robust satellite links for operational continuity.
- Digital Signal Processing:This technology enhances the quality and accuracy of sensor data from radar and sonar systems, improving target detection and reducing noise interference.
- Automatic Identification Systems:AIS technology enables automatic tracking and identification of vessels, contributing to maritime safety and traffic management.
- Acoustic Monitoring:Systems for detecting and analyzing underwater sounds are critical for environmental research, defense applications, and specialized survey operations.
- Electronic Chart Display:ECDIS (Electronic Chart Display and Information System) provides digital navigational charts and real-time vessel positioning, enhancing situational awareness and regulatory compliance.
Integrated Bridge Systems represent the highest value proposition, with Satellite Communication technologies expanding most quickly across diverse fleets.
Application:
The diverse operational environments and end-user requirements heavily influence the selection and integration of marine electronics across various applications.
- Commercial Shipping:This segment includes cargo vessels, tankers, and passenger liners operating on global routes, requiring high-specification navigation, communication, and safety equipment. IMO mandates for emissions monitoring and enhanced tracking compel significant investment in advanced electronic systems for commercial fleets.
- Recreational Boating:Encompassing leisure craft, sport fishing boats, and yachts, this segment demands user-friendly and feature-rich GPS chartplotters, fish finders, and autopilot systems. The leisure and sport fishing segments drive high-volume sales of these accessible technologies.
- Offshore Exploration:Specialized vessels and platforms involved in oil & gas, wind farm, and deep-sea mining operations require robust positioning, sonar, and communication systems.
- Naval Defense:Military vessels utilize highly secure and advanced marine electronics for navigation, surveillance, communication, and weapon systems integration.
- Environmental Monitoring:Applications include oceanographic research, climate studies, and marine resource management, employing specialized sensors and data acquisition systems.
- Research Vessels:Scientific research ships utilize advanced acoustic, navigation, and data logging equipment for oceanographic, biological, and geological studies.
Commercial Shipping applications dictate high-specification equipment, while Recreational Boating commands significant volume growth due to broad consumer appeal.
End User:
Procurement patterns for marine electronics vary significantly among end-user categories, reflecting their specific operational models and regulatory compliance needs.
- Shipbuilders:These entities integrate marine electronics into new vessel constructions and perform retrofitting projects for existing ships. New construction activity in South Korean shipyards drives substantial procurement volumes for integrated navigation and communication systems.
- Fishing Fleet Operators:Commercial fishing vessels require specialized sonar, navigation, and communication tools to enhance catch efficiency and ensure crew safety. Fleet modernization programs and regional safety regulations influence purchasing decisions for these operators.
- Offshore Contractors:Companies engaged in offshore construction, energy, and subsea operations purchase specialized positioning, survey, and communication equipment.
- Maritime Agencies:Coast guards, port authorities, and search and rescue organizations procure electronics for surveillance, vessel traffic management, and emergency response.
- Survey Companies:Firms conducting hydrographic, geophysical, and oceanographic surveys invest in high-precision sonar, positioning, and data acquisition systems.
- Port Authorities:These entities utilize marine electronics for vessel traffic services, port security, and environmental monitoring within port limits.
Shipbuilders represent the primary installation point for new systems, with Fishing Fleet Operators driving consistent demand for specialized equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization (IMO) heavily influences marine electronics procurement, setting global standards for safety and environmental compliance. These regulations drive investment in advanced systems across diverse maritime nations. Countries with strong shipbuilding industries and active recreational boating sectors exhibit significant demand.
South Korea
South Korea's robust shipbuilding industry drives demand for integrated bridge systems and advanced navigation solutions. The Ministry of Oceans and Fisheries (MOF) supports smart ship development and maritime safety initiatives. Major shipyards in Busan and Ulsan are centers for integrating sophisticated electronic architectures into new vessels.
United States
The United States recreational boating sector shows strong demand for user-friendly GPS chartplotters and fish finders. The Federal Communications Commission (FCC) regulates marine radio equipment and emissions standards for market access. Coastal regions like Florida and the Pacific Northwest are hubs for recreational marine electronics sales and service.
Germany
Germany's advanced maritime technology sector requires high-specification marine radars and communication devices for commercial vessels. European Union directives, including CE marking requirements, govern product standards for marine electronics sold in the country. Northern German ports and shipyards, such as those in Hamburg, focus on integrating complex systems for specialized vessels.
China
China's expanding new vessel construction programs create substantial procurement volumes for integrated navigation and communication systems. The China Maritime Safety Administration (MSA) enforces regulations for vessel tracking and safety equipment. Shipyards along the Yangtze River Delta and in Dalian are pivotal for installing advanced electronic suites into diverse fleets.
Japan
Japan's established maritime industry demands reliable sonar systems and Electronic Chart Display and Information Systems (ECDIS) for both commercial shipping and fishing fleets. The Japan Coast Guard (JCG) mandates specific electronic equipment for safety and maritime domain awareness. Major port cities like Yokohama and Kobe serve as key distribution and service centers for marine electronics.
Marine Electronics Market Key Industry Players
Value-added integrators and component specialists split the marine electronics market. This tiered structure allows for both highly customized solutions catering to complex commercial vessels and mass-market product offerings for recreational users. Strategic archetypes include large-scale system providers focused on integrated bridge systems and niche technology developers specializing in specific sensor types. Dominant competitive moves involve strategic partnerships for system integration and portfolio diversification into new application areas like autonomous vessel operations.
Within the integrated solutions tier, Kongsberg Maritime exemplifies deep expertise in complex commercial vessel systems, serving the high-end commercial shipping sector. Garmin Ltd. occupies a position as a leading provider of user-friendly GPS and sonar technologies, primarily targeting recreational and light commercial segments with accessible innovations. Furuno Electric Co., Ltd. anchors the market for high-specification marine radars and communication devices, particularly in the Asia-Pacific region, providing essential equipment for navigation and safety across diverse fleets.
| Leading Market Players |
|---|
| Navico Group |
| Kongsberg Maritime |
| Garmin Ltd. |
| Intellian |
| KVH Industries, Inc. |
| Furuno Electric Co., Ltd. |
| Raymarine |
| Airmar |
| Brunswick Corporation |
| Others |
Cost & Logistics Intelligence
The Pacific shipping lanes' fluctuating freight costs influence the sourcing of specialized marine electronics components, shaping supply concentration and downstream price differentiation across the market. This dynamic impacts both high-volume recreational units and complex integrated commercial systems.
Pricing Analysis
Geographic price spreads for marine electronics reflect regional regulatory compliance costs and varying labor rates for installation. Project-based pricing dominates for complex integrated bridge systems, while per-unit transactional models prevail in the recreational segment. Certification level and after-sales service bundling drive significant price differentiation across product tiers. Pricing pressure stems from increased competition in the recreational segment, where consumers are highly price-sensitive compared to commercial shipping operators.
Supply Chain Analysis
Component bottlenecks for specialized semiconductors and marine-grade displays dominate the supply chain risk profile, impacting production schedules globally. Geographic supply concentrates in East Asian nations like South Korea, China, and Japan, which host major electronics manufacturing and shipbuilding hubs. The supply chain relies on a limited number of foundries for advanced System-on-Chip architectures. Distribution runs through a dual model: direct integration with shipbuilders for new vessels and a network of specialized distributors for aftermarket and recreational sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine electronics market presents a significant service-attach opportunity, with subscription-based data services for real-time weather and chart updates expanding faster than core hardware sales. This shift redefines value creation beyond the initial product transaction.
For Market Incumbents: Insulate core integrated bridge system revenues by deepening OEM relationships with major shipyards in South Korea and China. Diversify product portfolios into autonomous vessel control systems, leveraging existing expertise in navigation and communication. Invest in robust cybersecurity features and verifiable software update paths to counter emerging cyber threats. This strategy counters margin pressure from new entrants and evolving regulatory demands.
For New Entrants and Emerging Players: The recreational boating segment in coastal regions of the United States and Europe represents the most penetrable entry point. Focus on user-friendly, cost-effective fish finders and GPS chartplotters with intuitive mobile app integration. Develop modular System-on-Chip solutions offering simplified installation and interoperability with existing NMEA 2000 networks. Target smaller fleet operators with accessible predictive maintenance analytics packages.
For Investors and Strategic Acquirers: Software-defined electronics specialists with strong intellectual property in AI-driven analytics and cybersecurity represent attractive acquisition targets for long-term value creation. The market offers sustained growth over the next decade due to regulatory mandates and autonomous vessel development. Prioritize companies demonstrating verifiable integration capabilities across multi-vendor systems. Watch for increasing consolidation activities among mid-tier hardware providers as a signal of market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen OEM Partnerships | Secures installation volume for integrated bridge systems in South Korean shipyards. |
| Invest in Cybersecurity Solutions | Addresses IMO regulations for maritime cyber risk management across commercial fleets. |
| Develop Modular SoC Architectures | Reduces cost and complexity for recreational boating manufacturers and integrators. |
| Expand Subscription Data Services | Captures recurring revenue from commercial shipping and superyacht operators prioritizing real-time information. |
| Acquire AI/Analytics Startups | Accelerates entry into predictive maintenance and autonomous vessel control systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of IMO reports, FCC filings, and industry association publications. Primary interviews engaged shipyard executives, fleet operators, electronics engineers, and maritime safety authorities globally. This approach triangulates bottom-up market insights with top-down industry trends.
Forecast inputs considered new vessel order books, recreational boating participation rates, and global maritime trade volumes across the analysis window. The analytical framework modeled market evolution by product type, technology, application, end-user, and geographic region. Compound Annual Growth Rates were derived from historical data and projected demand drivers. IMO regulatory changes served as a key forecast input.
Practitioners should monitor supply chain disruptions, geopolitical shifts, and rapid technological advancements for early signals of market revision. Forecasts reflect assumptions documented at the time of analysis. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Electric Outboard Engines Market
Marine
Trim Tabs Market
Marine
Marine VFD Market
Marine
Autonomous Ships Market
Marine
Military Marine Engine Market
Marine
Marine Auxiliary Engine Market
Marine
Yacht Painting and Maintenance Market
Marine
Marine Base Steering Gear Market
Marine
Hydraulic Marine Cranes Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Salvage Services Market
Marine
Fishing Vessel Market
Marine
Boat Cleat Market
Marine
Sea Scooter Market
Marine
Marine Pipes Market
Marine
Europe Marine Communication Systems Market