
 Pneumatic Marine Fender Market | 2026-2036
Pneumatic Marine Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Marine Fender Market Intelligence
The EU's Port Services Regulation, aimed at enhancing transparency and efficiency, is consolidating the supplier base towards manufacturers who can meet stringent performance and documentation criteria. Yokohama Rubber Company leverages its deep material science expertise to produce high-performance fenders for specialized applications like LNG transfers. Trelleborg AB differentiates through its integrated smart fender systems that offer real-time monitoring. JIER Marine Rubber Fender competes on manufacturing scale, primarily serving the expansive port infrastructure projects across Asia.
A pneumatic marine fender is a compressed air-filled bumper designed to absorb kinetic energy during berthing and mooring operations. Its construction typically involves layers of nylon fabric reinforcement within a synthetic rubber body, providing high energy absorption with low reaction force. Ship docking applications constitute the core of the market, driven by constant port traffic and the need to protect aging infrastructure. Demand from shipping companies for ship-to-ship transfers, especially for LNG carriers, is creating new growth avenues in the offshore mooring segment.
Global manufacturing and testing are governed by the ISO 17357 standard, which dictates performance criteria for high-pressure units. National and regional bodies, including the US Coast Guard and China's Maritime Safety Administration, impose further requirements for equipment used in their waters. The critical decision for port authorities and fleet operators is balancing the initial cost of standard-compliant fenders against the long-term operational benefits of investing in advanced, sensor-integrated systems.
Market Dynamics
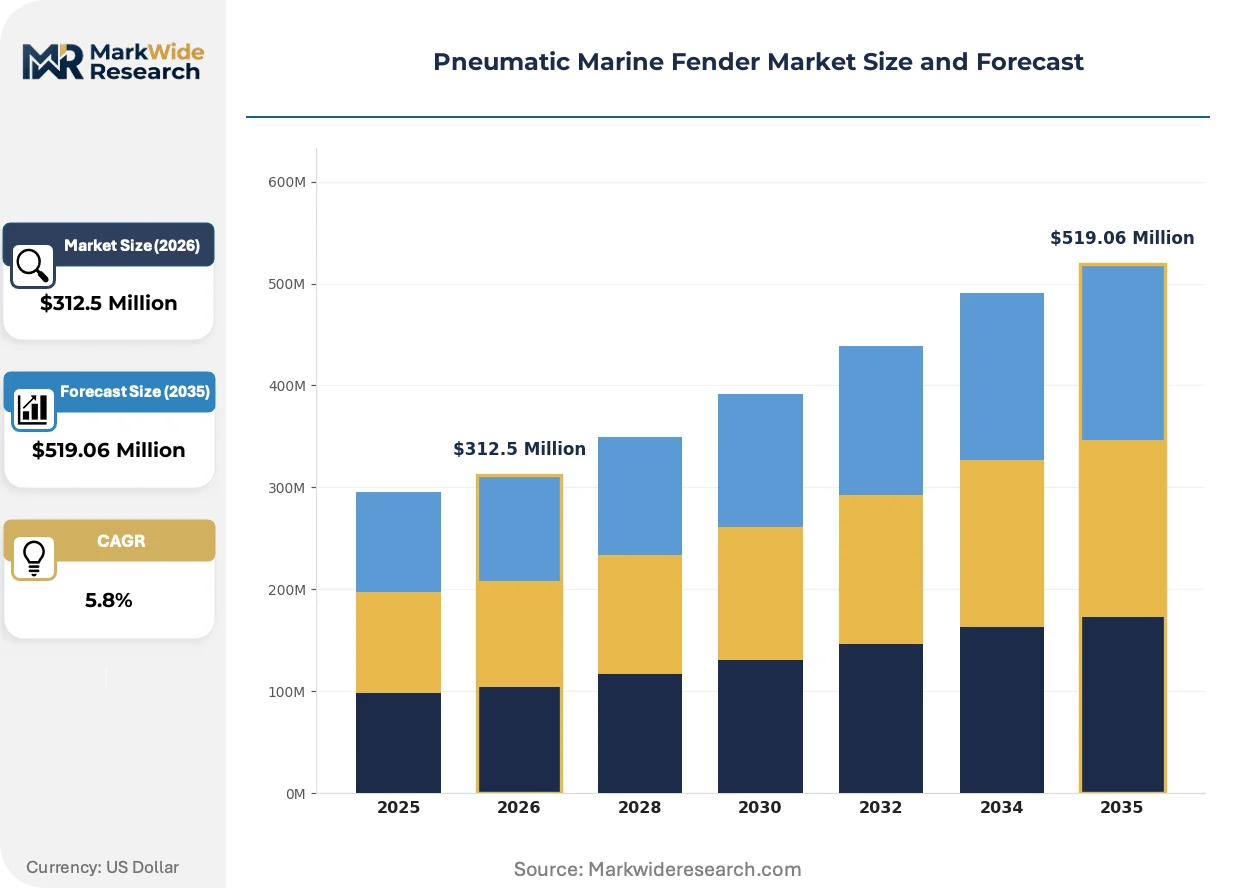
The central dynamic in the pneumatic fender market is the tension between standardized, volume-driven procurement mandated by ISO 17357 and the growing demand for specialized, high-performance systems for applications like LNG ship-to-ship transfers and smart ports.
Growth Catalysts
- Port Infrastructure Expansion:Major investments in new and expanded port facilities, particularly in China, India, and Vietnam, directly drive demand for ship-to-dock fendering systems to equip new berths and protect infrastructure.
- LNG Carrier Fleet Growth:The expanding global fleet of LNG carriers necessitates high-performance pneumatic fenders for ship-to-ship transfers, a segment that demands superior energy absorption and reliability compared to standard docking applications.
- EU Port Services Regulation:This regulation enhances transparency in port services, favoring manufacturers who can provide comprehensive documentation and meet stringent performance criteria, thereby consolidating the market around qualified suppliers.
Market Restraints
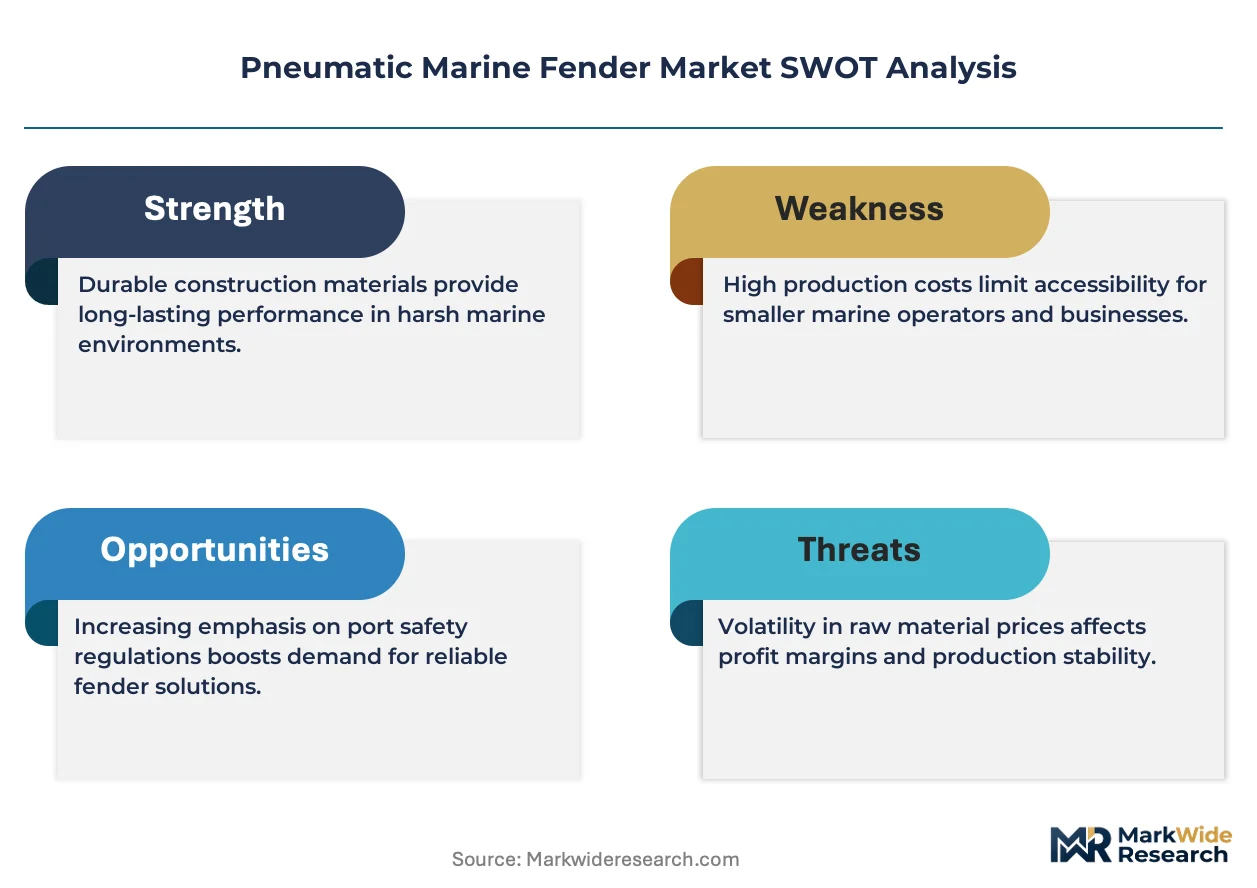
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key raw materials, specifically synthetic rubber and high-tenacity nylon tire cord, which can compress manufacturer margins and affect end-user pricing.
- Substitution from Alternative Fenders:For smaller vessels and less demanding berthing operations, lower-cost alternatives like foam-filled or solid rubber fenders present a persistent substitution threat, limiting pneumatic fender adoption in certain segments.
- Logistical and Installation Costs:The high costs and logistical complexities associated with transporting and installing very large pneumatic fenders can be prohibitive, especially for smaller ports or projects in remote locations.
Strategic Opportunities
- Smart Fender Integration:Embedding IoT sensors for real-time monitoring of internal pressure, impact forces, and location offers a significant opportunity to transition from product sales to data-driven service and maintenance contracts.
- Offshore Wind Energy Sector:The construction and maintenance of offshore wind farms create a new application for specialized fenders designed for crew transfer vessels and service operation vessels berthing in challenging sea states.
- Emerging Market Port Development:Underdeveloped port infrastructure in regions like West Africa and Southeast Asia represents a long-term growth opportunity as these areas modernize their maritime trade facilities and require new fendering systems.
Industry Challenges
- Certification and Compliance Burden:The rigorous testing and documentation required to achieve and maintain ISO 17357 certification is a costly and time-consuming process that can act as a barrier for new entrants and smaller manufacturers.
- Customization versus Standardization:Manufacturers face the challenge of balancing the market's demand for standardized, cost-effective products with the need to engineer custom solutions for unique vessels or complex berthing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Marine Fender Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Type, Twin Type, Solid Type, Cellular Type Application: Ship Docking, Offshore Mooring, Barge Transfer, Harbor Protection Material: Neoprene Rubber, Synthetic Rubber, Polyurethane, Nylon Fabric End User Industry: Port Authorities, Shipyards, Maritime Contractors, Shipping Companies |
| Companies Covered | ShibataFenderTeam, Evergreen Maritime, Yokohama Rubber Company, Anchor Marine, JIER Marine Rubber Fender, Trelleborg AB, Palfinger AG, FenderTec, Sumitomo Rubber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Marine Fender Market Strategic Shifts & Innovations
Material science advancements and digital technology are transforming pneumatic fenders from passive safety equipment into active components of port management systems. This evolution prioritizes operational data and total cost of ownership over initial purchase price, reshaping competitive dynamics.
Smart fender technology incorporates embedded sensors to monitor internal pressure, temperature, and impact forces. Operators of LNG carriers and high-throughput container terminals are the primary adopters, seeking to minimize risk and maximize berth uptime. This technology is integrating fender performance data directly into port operational software, enabling predictive maintenance schedules and optimizing vessel traffic flow.
The global enforcement of the ISO 17357 standard defines quality benchmarks for high-pressure floating pneumatic rubber fenders. This regulation effectively bifurcates the market, creating a clear distinction between suppliers offering certified, high-performance products and those providing non-compliant alternatives. Port authorities, especially in Europe and Japan, increasingly mandate this certification in public tenders, restricting market access for uncertified producers.
Port operators are increasingly adopting a total cost of ownership (TCO) model for procurement decisions. This behavioral shift moves the focus from the lowest initial price to a comprehensive evaluation of a fender's durability, maintenance needs, and operational lifespan. This trend is most pronounced in mature maritime markets like Germany and South Korea, where asset longevity and operational efficiency are critical financial metrics.
Pneumatic Marine Fender Market Segmentation
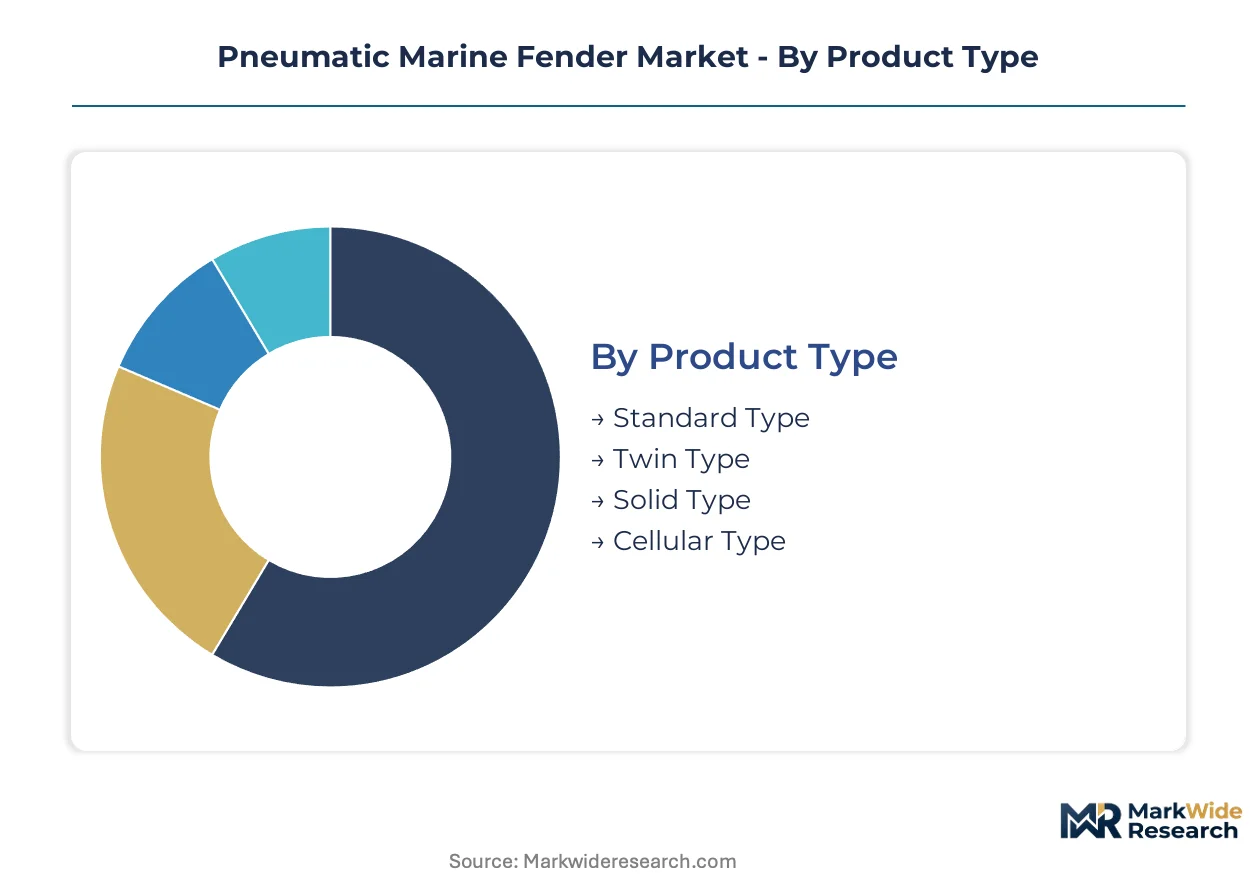
The pneumatic marine fender market segmentation provides a granular view of product variations, application areas, material compositions, and end-user demands. Understanding these distinctions helps stakeholders identify specific growth pockets and tailor solutions for diverse maritime operational requirements. Demand is concentrating in key shipbuilding and port development hubs, particularly in China and South Korea.
Product Type:
The product type segmentation differentiates fenders based on their structural design and how they integrate into varied marine protection systems.
- Standard Type:These high-pressure floating pneumatic rubber fenders conform to ISO 17357, featuring multiple layers of synthetic-tire-cord reinforcement and an inner rubber layer. Ship-to-dock applications in major container ports drive demand for their reliable energy absorption and low reaction force.
- Twin Type:Twin fenders consist of two individual pneumatic fenders connected by a robust chain and tire net, offering enhanced stability and impact distribution. Specialized vessel berthing, such as LNG carriers requiring precise positioning, utilizes these systems for superior protection.
- Solid Type:Solid rubber fenders, though not pneumatic, are included in broader fendering discussions for comparison, offering high durability and abrasion resistance for fixed installations. Smaller vessels and older port infrastructure often employ these as a cost-effective solution.
- Cellular Type:Cellular fenders are a type of compression fender, designed with a hollow cylindrical body to absorb energy efficiently with a low reaction force. They are used in high-traffic berths where consistent performance and long service life are paramount.
Standard Type fenders lead volumes today; Twin Type fenders are gaining share fastest.
Application:
Application segmentation highlights how different operational needs dictate the specific fender configurations required across the maritime industry.
- Ship Docking:This core application involves protecting vessels and port infrastructure during berthing operations, utilizing pneumatic fenders to absorb kinetic energy. Constant port traffic and the need to safeguard aging infrastructure drive consistent demand in established maritime regions.
- Offshore Mooring:Specialized pneumatic fenders facilitate ship-to-ship transfers, particularly for large LNG carriers and oil tankers, minimizing impact forces in open water. The expanding global LNG carrier fleet creates new growth avenues in this high-performance segment.
- Barge Transfer:Pneumatic fenders protect barges and larger vessels during cargo transfers in sheltered waters or offshore, preventing damage from contact. Inland waterways and coastal operations for bulk goods frequently utilize these smaller, more flexible fender solutions.
- Harbor Protection:Permanent installations of pneumatic fenders safeguard critical harbor infrastructure like jetties, quays, and breakwaters from accidental vessel impacts. Port authorities in busy commercial ports deploy these systems to maintain operational continuity and reduce repair costs.
Offshore Mooring applications demonstrate the steepest expansion trajectory.
Material:
Material segmentation reveals the foundational components that impart durability and energy absorption characteristics to pneumatic fenders, influencing performance and lifespan.
- Synthetic Rubber:This forms the primary body of pneumatic fenders, offering excellent elasticity, abrasion resistance, and weatherability crucial for marine environments. Its consistent performance under varying temperatures makes it a preferred choice for ISO 17357 compliant fenders.
- Nylon Fabric:High-tenacity nylon tire cord fabric layers are embedded within the rubber body, providing the critical reinforcement necessary for maintaining the fender's structural integrity under high internal pressure. This material ensures the fender can absorb significant impact energy without bursting.
- Neoprene Rubber:Used in specialized applications requiring enhanced resistance to oil, chemicals, and extreme temperatures, Neoprene rubber offers superior environmental resilience. Certain industrial port operations and offshore platforms may specify this material.
- Polyurethane:Often used as a coating or in solid/foam-filled fender alternatives, polyurethane provides high abrasion resistance and can be customized for various hardness levels. It finds niche applications where specific surface properties are required.
Synthetic Rubber remains the primary material choice due to its balanced properties and cost-effectiveness.
End User Industry:
End user industry segmentation clarifies the diverse stakeholders responsible for procurement and deployment of marine fendering solutions across global waterways.
- Port Authorities:These entities manage and maintain port infrastructure, procuring pneumatic fenders for berths, jetties, and harbor protection to ensure safe vessel operations. Strict compliance with ISO 17357 and local regulations drives their purchasing decisions.
- Shipping Companies:Fleet operators acquire pneumatic fenders for their vessels, primarily for ship-to-ship transfers and safe berthing at various ports worldwide. LNG carrier operators, in particular, prioritize high-performance and reliable fender systems.
- Shipyards:Shipyards integrate fendering systems into new vessel builds and perform maintenance or upgrades on existing fleets, influencing material and design specifications. They often work closely with fender manufacturers for custom solutions.
- Maritime Contractors:These companies undertake port development projects, infrastructure upgrades, and offshore installations, procuring and installing fendering systems as part of larger construction contracts. Their demand is project-based and often driven by tender requirements.
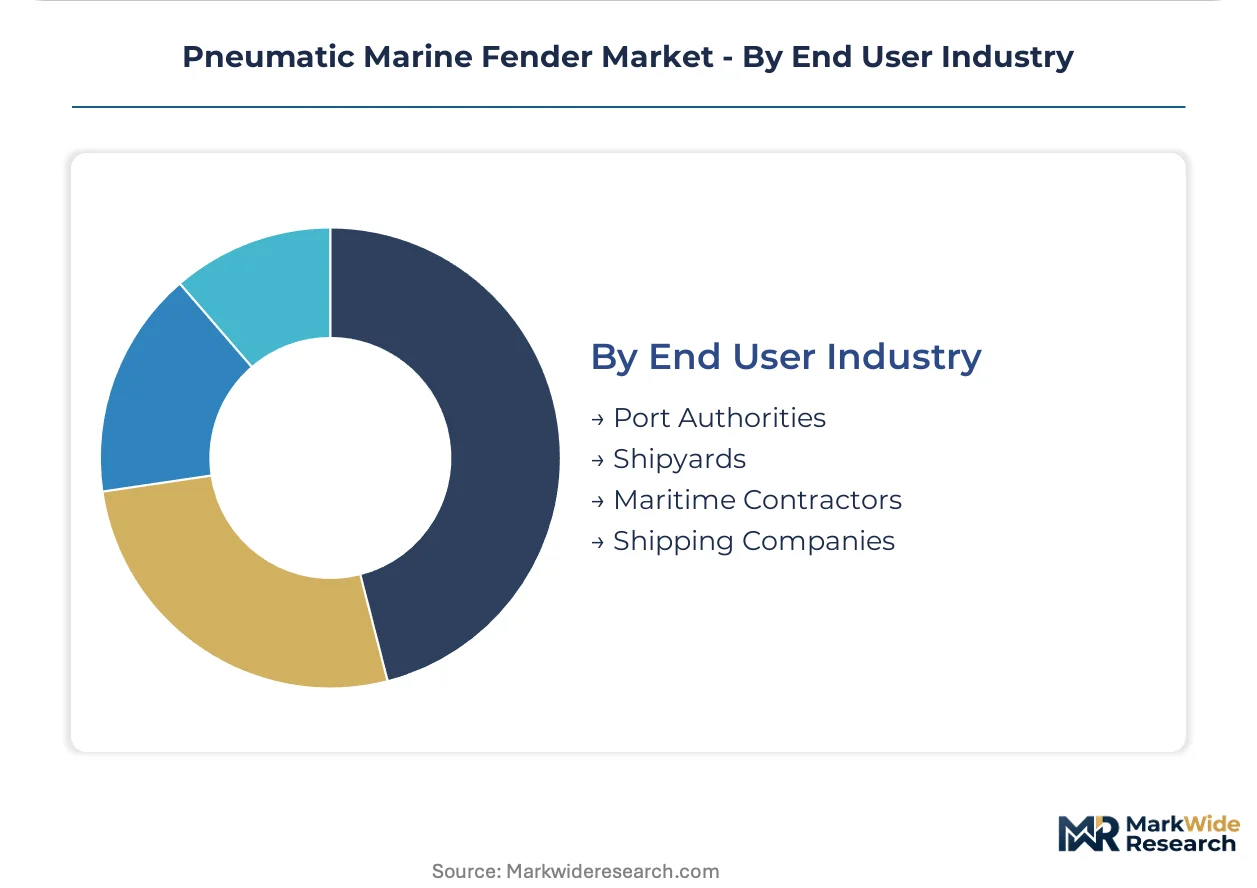
Port Authorities represent the largest procurement segment for permanent installations and infrastructure protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized expertise in marine infrastructure development and shipbuilding across major maritime nations underpins the regional demand for advanced pneumatic marine fenders. This expertise ensures the effective implementation of ISO 17357 standards and the adoption of cutting-edge fendering solutions. Port authorities and shipping companies increasingly rely on regional specialists for complex installations and maintenance.
China
China's extensive port infrastructure expansion and significant shipbuilding activities create substantial demand for pneumatic marine fenders. The Maritime Safety Administration (MSA) enforces stringent requirements for fendering equipment used in Chinese waters. Major port cities like Shanghai and Ningbo-Zhoushan are continuously upgrading facilities, requiring large volumes of standard-compliant fenders.
South Korea
South Korea's robust shipbuilding industry and advanced port operations drive consistent demand for high-performance pneumatic fenders. The Ministry of Oceans and Fisheries (MOF) oversees maritime safety, influencing procurement decisions for fendering systems. Shipyards in Busan and Ulsan integrate specialized fender solutions into new vessel builds, particularly for LNG carriers.
Germany
Germany's focus on operational efficiency and high-throughput container terminals generates demand for durable, sensor-integrated pneumatic fenders. The EU Port Services Regulation influences procurement, favoring manufacturers who meet stringent performance and documentation criteria. Major ports such as Hamburg and Bremerhaven are adopting total cost of ownership models, prioritizing long-term asset longevity.
United States
The United States market sees demand from modernization efforts for aging port infrastructure and new LNG export terminals. The US Coast Guard imposes specific requirements for maritime equipment, including fendering systems, to ensure operational safety. Port complexes in Houston and Los Angeles-Long Beach are investing in advanced fendering for increased traffic and larger vessels.
Pneumatic Marine Fender Market Key Industry Players
The competitive structure tilts toward established global manufacturers with deep material science expertise, forming a tiered market. This market includes global integrated solution providers, specialized application innovators, and regional volume manufacturers. Technology licensing and strategic partnerships are prevalent among players seeking to broaden product portfolios. Continuous portfolio diversification into smart fender systems and customized solutions also defines the competitive landscape.
On the premium-tier vector, Yokohama Rubber Company and Trelleborg AB exemplify innovation in material science and smart fender integration for specialized applications. These entities, with their global operational footprints, represent providers of advanced fendering systems that meet stringent performance criteria. JIER Marine Rubber Fender, a prominent Chinese manufacturer, occupies a strong position in volume-driven segments, particularly serving Asia's expansive port infrastructure projects. This company leverages manufacturing scale to address the significant demand for standard-compliant fenders in key development hubs.
| Leading Market Players |
|---|
| ShibataFenderTeam |
| Evergreen Maritime |
| Yokohama Rubber Company |
| Anchor Marine |
| JIER Marine Rubber Fender |
| Trelleborg AB |
| Palfinger AG |
| FenderTec |
| Sumitomo Rubber Industries |
| Others |
Cost & Logistics Intelligence
Smart fender integration, incorporating real-time monitoring, simultaneously reshapes cost economics by adding value-added services and concentrates supply among manufacturers with advanced R&D capabilities. This shift moves procurement focus beyond initial cost.
Pricing Analysis
Bundled service models, integrating smart fender systems with maintenance contracts, command premium pricing. The market predominantly uses a contract-based long-term offtake model, with price differentiation driven by ISO 17357 certification, brand reputation, and customization for specialized applications. Pricing pressure stems from the volatility of synthetic rubber and nylon fabric raw material costs, impacting manufacturer margins. Smaller ports and barge transfer operators exhibit high price sensitivity, while LNG carrier operators prioritize performance over initial cost.
Supply Chain Analysis
Logistical and installation costs significantly influence the pneumatic fender supply chain, especially for very large units. Supply concentration centers on manufacturing hubs in China and South Korea, which produce the bulk of standard-compliant fenders. The industry draws from key raw material dependencies, specifically synthetic rubber and high-tenacity nylon tire cord, making raw material price volatility a structural risk. Distribution runs through direct sales channels to port authorities and shipping companies, alongside project-based procurement by maritime contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumatic marine fender market presents a geographic-arbitrage opportunity, driven by the cost differential in manufacturing between Asian hubs and the premium placed on ISO 17357 certified products in European markets. This allows for strategic positioning across value tiers.
For Market Incumbents: Deepen material science expertise to innovate high-performance fenders for specialized applications like LNG transfers, countering substitution threats from cheaper alternatives. Secure long-term contracts for synthetic rubber and nylon fabric to mitigate raw material price volatility and stabilize production costs. Expand smart fender integration capabilities, leveraging ISO 17357 certification as a barrier to entry for smaller competitors. This strategy reinforces market leadership against emerging players.
For New Entrants and Emerging Players: Digital procurement platforms offer a direct channel to target smaller ports and barge transfer operators in emerging markets. Focus on providing cost-effective, ISO 17357 standard-compliant fenders for port infrastructure expansion in regions like West Africa. Exploit the underserved offshore wind energy sector by developing specialized fenders for crew transfer vessels. This approach bypasses established distribution networks and addresses specific regional needs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional volume manufacturers in Asia, offering scalable production capacity for standard fenders. The long-term viability of this market hinges on operational efficiency and asset longevity, favoring companies with robust product lifecycles. Target mid-sized firms possessing specialized material science or smart sensor integration technology to gain a competitive edge. A key signal to watch is the increased mandate for smart fender technology in public tenders, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smart Fender R&D | Integrates IoT sensors for real-time monitoring, optimizing port operations and vessel safety. |
| Secure Raw Material Supply | Mitigates price volatility for synthetic rubber and nylon fabric, stabilizing production costs for manufacturers. |
| Expand ISO 17357 Certification | Ensures market access in Europe and Japan, meeting stringent quality benchmarks for port authorities. |
| Target Offshore Wind Sector | Creates new application for specialized fenders, supporting crew transfer vessels in challenging sea states. |
| Develop Regional Partnerships | Leverages local expertise for installation and maintenance, addressing logistical complexities in emerging markets. |
Research Approach
Multiple input streams—primary interviews, regulatory documents, and industry trade publications—were reconciled for this analysis. Insights were gathered from port authorities, shipping company fleet managers, and shipyard procurement specialists. Secondary validation involved reviewing ISO 17357 standards, US Coast Guard regulations, and China Maritime Safety Administration requirements. A rigorous bottom-up and top-down triangulation process ensured data accuracy.
Data streams were rigorously reconciled to construct a comprehensive analytical framework across the analysis window. The model incorporated segmentation by product type, application, material, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected demand, considering factors like port infrastructure investment and LNG carrier fleet growth. This approach provides a robust market outlook.
The model assumes a particular technology adoption path; alternative pathways for smart fender integration would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and geopolitical shifts affecting maritime trade. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Europe Recreational Boating Market
Marine
Marine Stabilizers Market
Marine
Shipbuilding Market
Marine
Deep-V Boat Market
Marine
Ballast Water Management Market
Marine
Jack-Up Vessels Market
Marine
North Sea Offshore Support Vessels Market
Marine
Trim Tabs Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Chartplotter Market
Marine
Marine Glass Market
Marine
Marine Exhaust Systems Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
LNG Bunkering Vessel Market
Marine
Azimuth Thrusters Market