
 Marine Shackle Market | 2026-2036
Marine Shackle Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Shackle Market Foresight
Skilled forging technician shortages across European maritime supply chains is unwinding capacity expansion plans at several specialty manufacturers. Crosby Group LLC leverages its heat-treatment expertise to sustain premium positioning in safety-critical bow shackle grades. Van Beest B.V. anchors its competitive stance through forged alloy steel specialization for heavy-lift offshore applications. Gunnebo Industries AB competes on integrated testing protocols that exceed DNV classification requirements.
A marine shackle is a U-shaped load-bearing connector forged from alloy or carbon steel, typically rated by working load limit and proof-tested to twice that value, designed to join chains, ropes, or lifting slings under tension. Bow shackles with their wider throat clearance dominate marine lifting applications where multi-leg sling angles create side loading, while safety shackles with captive pin mechanisms represent the fastest-growing specification tier as offshore operators mandate drop-prevention compliance. Stainless steel material grades command margin concentration in yacht rigging and coastal weathering environments where galvanized coatings degrade prematurely.
DNV standards for offshore lifting equipment, ISO 2415 specifications for forged shackles, and OSHA maritime safety directives collectively enforce material certification and periodic inspection regimes that shape procurement specifications. The EU Machinery Directive through CE marking mandates traceable load ratings for shackles deployed on European-flagged vessels. Stakeholders must monitor evolving subsea mooring load requirements as floating offshore wind platforms introduce unprecedented shackle diameter and fatigue-resistance specifications.
Market Dynamics
IMO 2023 amendments to the Lifting Appliances and Loose Gear Code are forcing material traceability upgrades across forged marine hardware supply chains, compressing procurement timelines for offshore contractors while elevating specification barriers for smaller forgers.
Growth Catalysts
- Floating Offshore Wind Mooring:Scotland's ScotWind lease rounds and Norway's Utsira Nord project are generating demand for super-diameter shackles rated above 500 tonnes working load limit.
- DNV-ST-N001 Certification Mandates:The standard's 2021 revision requires fatigue-tested alloy steel for all subsea lifting gear, eliminating cast or lower-grade forged alternatives from North Sea procurement lists.
- Decommissioning Surge:The UK's 2024 North Sea Transition Authority timelines for platform removal are accelerating spot-market purchases of high-capacity bow shackles for topside lift campaigns.
Market Restraints
- Scrap Steel Price Volatility:Alloy steel billet costs fluctuate with nickel and molybdenum commodity markets, squeezing forging margins on fixed-price offshore contracts.
- European Forging Capacity Concentration:Heat-treatment and proof-testing facilities cluster in Germany's Ruhr Valley and northern Italy, creating single-point vulnerability for just-in-time delivery to North Sea yards.
- Galvanized Coating Substitution Limits:Hot-dip galvanizing remains standard for carbon steel marine shackles despite inferior salt-spray performance versus stainless, as duplex-grade material costs prohibit mass adoption in commercial shipping.
Strategic Opportunities
- US Gulf of Mexico Brownfield Revival:Shelf infrastructure aging past design life is driving specification upgrades for API RP 2D-compliant shackles in platform maintenance contracts.
- Digital Twin Integration:RFID-embedded shackles with load-history logging are opening recurring-revenue service contracts with offshore vessel operators managing fleet-wide lifting inventories.
- Japan's Offshore Wind Feed-in Tariff:METI's 2040 floating wind targets are creating first-mover advantage for DNV/JIS dual-certified manufacturers establishing local forging partnerships.
Industry Challenges
- Forging Technician Apprenticeship Gaps:Germany's IHK-certified heavy forging programs graduate fewer than 200 specialists annually, below replacement rate for retiring craft workers at marine hardware forges.
- Multi-Standard Certification Overlap:Concurrent DNV, ABS, and Lloyd's Register approval processes add 12-16 weeks to new product qualification timelines for offshore-grade safety shackles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Shackle Market |
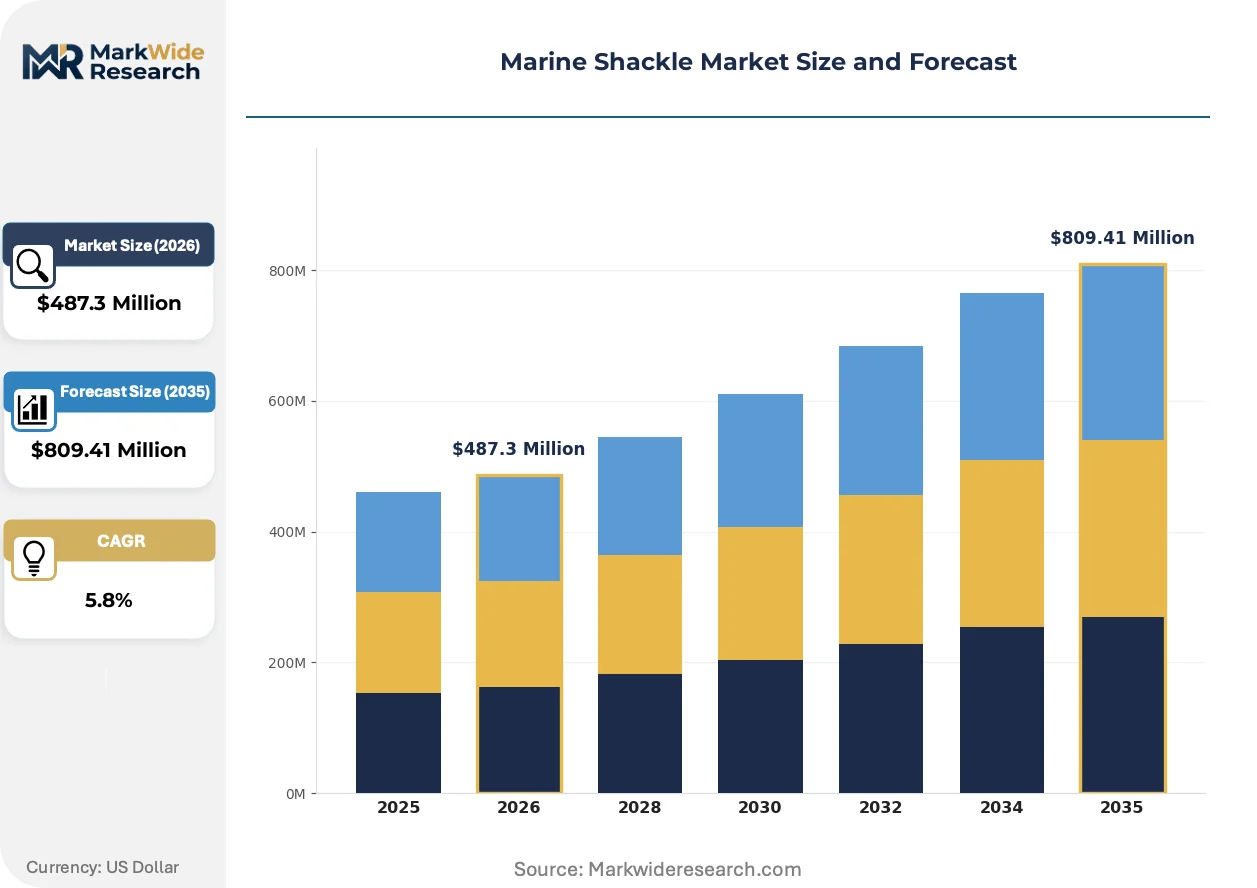
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bow Shackles, Chain Shackles, Safety Shackles, D Shacles Material: Stainless Steel, Galvanized Steel, Alloy Steel, Plastic Application: Marine Lifting, Fastening, Towing, Weathering Conditions End User: Shipping Companies, Marine Services, Individuals, Offshore Operations |
| Companies Covered | Columbus McKinnon Corporation, Crosby Group LLC, Gunnebo Industries AB, Van Beest B.V., Mazzella Companies, James Fisher and Sons plc, Sotra Anchor & Chain AS, Campbell Chain Company, Peerless Industrial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Shackle Market Shifts & Advancements
Marine shackle design is pivoting toward predictive-load monitoring and captive-pin safety architectures as offshore operators eliminate drop-risk exposure and extend inspection intervals on subsea installations.
Additive manufacturing of shackle prototypes is displacing traditional pattern-based sand casting for complex bow geometries in super-alloy grades. Norwegian subsea contractors are piloting topology-optimized designs that reduce weight 15-20% without sacrificing working load ratings. This displacement is compressing lead times for custom mooring connectors from 26 weeks to 14 weeks.
EU Machinery Directive amendments through CE marking now mandate electronic load-rating traceability for shackles deployed on European-flagged offshore vessels. The regulation forces forgers to integrate QR-code stamping or RFID tagging into production workflows. Dutch and Danish port state control inspections are rejecting non-compliant hardware at quayside, redirecting procurement toward pre-certified suppliers.
Charterers are consolidating lifting gear procurement under vessel management agreements rather than project-specific spot buying. This consolidation favors integrated suppliers offering fleet-wide inventory management and inspection services over standalone hardware manufacturers. The shift is most pronounced in Singapore's offshore support vessel cluster, where rigging contractors now specify multi-year framework agreements with embedded recertification schedules.
Marine Shackle Market Segmentation
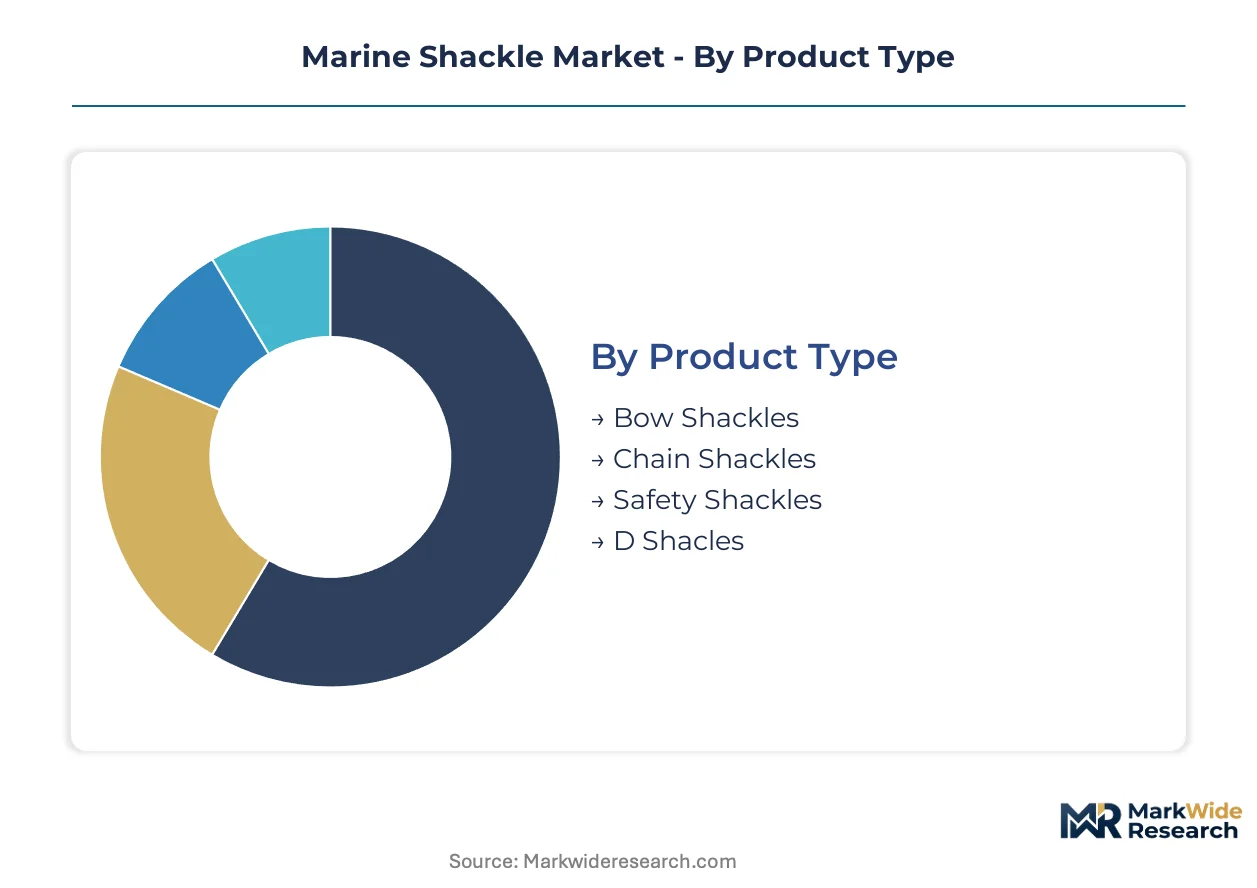
Marine shackle procurement specifications diverge sharply across operating environments, with offshore contractors demanding fatigue-tested alloy grades while commercial shipping prioritizes cost-optimized galvanized alternatives. Segmentation clarity enables suppliers to align heat-treatment capacity and certification investments with actual revenue concentration rather than fragmented spot demand.
Product Type:
Chain shackles face the strongest substitution pressure from synthetic lifting slings in sub-10-tonne applications, forcing forged manufacturers to defend position through super-diameter specialization.
- Bow Shackles:Wider throat geometry accommodates multi-leg sling angles common in offshore topside lifts. Demand concentrates in Norway's North Sea cluster where floating wind mooring projects specify 500-tonne working load limits and DNV fatigue certification.
- Safety Shackles:Captive pin mechanisms eliminate drop-risk exposure, a specification now mandated by major offshore vessel operators under fleet-wide lifting gear protocols. ScotWind lease rounds and Japan's METI floating wind targets are accelerating specification upgrades.
- Chain Shackles:Narrow throat suits linear loading but loses share to bow designs in angled lift applications; retains position in anchor chain connections and fixed-mooring installations.
- D Shackles:Compact profile dominates yacht rigging and coastal fastening where space constraints override load-angle flexibility; stainless grades command premium positioning in salt-spray environments.
Bow shackles retain volume leadership; safety shackles hold the steepest expansion curve.
Material:
Cost tier stratification separates premium alloy grades certified for subsea fatigue from commodity galvanized carbon steel serving commercial shipping maintenance cycles.
- Alloy Steel:Nickel-molybdenum compositions meet DNV-ST-N001 fatigue requirements for subsea lifting gear. Procurement concentrates in offshore contractor frameworks rather than spot purchasing, locking in multi-year volume commitments.
- Stainless Steel:Duplex grades resist crevice corrosion in splash-zone mooring connections where galvanized coatings degrade within 18 months. Premium positioning concentrates in yacht rigging and coastal infrastructure.
- Galvanized Steel:Hot-dip coating remains standard for carbon shackles in commercial shipping despite inferior salt-spray performance; price volatility in zinc and scrap steel squeezes forging margins on fixed-price contracts.
- Plastic:Glass-reinforced polymers substitute in non-load-bearing fastening and temporary rigging where magnetic interference or weight reduction overrides strength requirements.
Galvanized steel retains volume leadership; alloy steel commands the steepest margin expansion.
Application:
Volume concentration in marine lifting applications creates procurement scale effects that fastening and towing segments cannot replicate.
- Marine Lifting:Proof-tested shackles rated at twice working load limit under ISO 2415; offshore platform maintenance and decommissioning campaigns drive specification upgrades in the UK North Sea.
- Weathering Conditions:Coastal infrastructure and yacht rigging demand corrosion-resistant grades with extended inspection intervals; duplex stainless commands premium positioning.
- Towing:Dynamic load cycling requires fatigue-rated bow shackles in harbor towage and offshore vessel escort operations.
- Fastening:Static tension applications in mooring and anchoring tolerate lower-grade materials; price-sensitive procurement dominates.
Marine lifting retains volume leadership; weathering conditions applications are climbing the fastest.
End User:
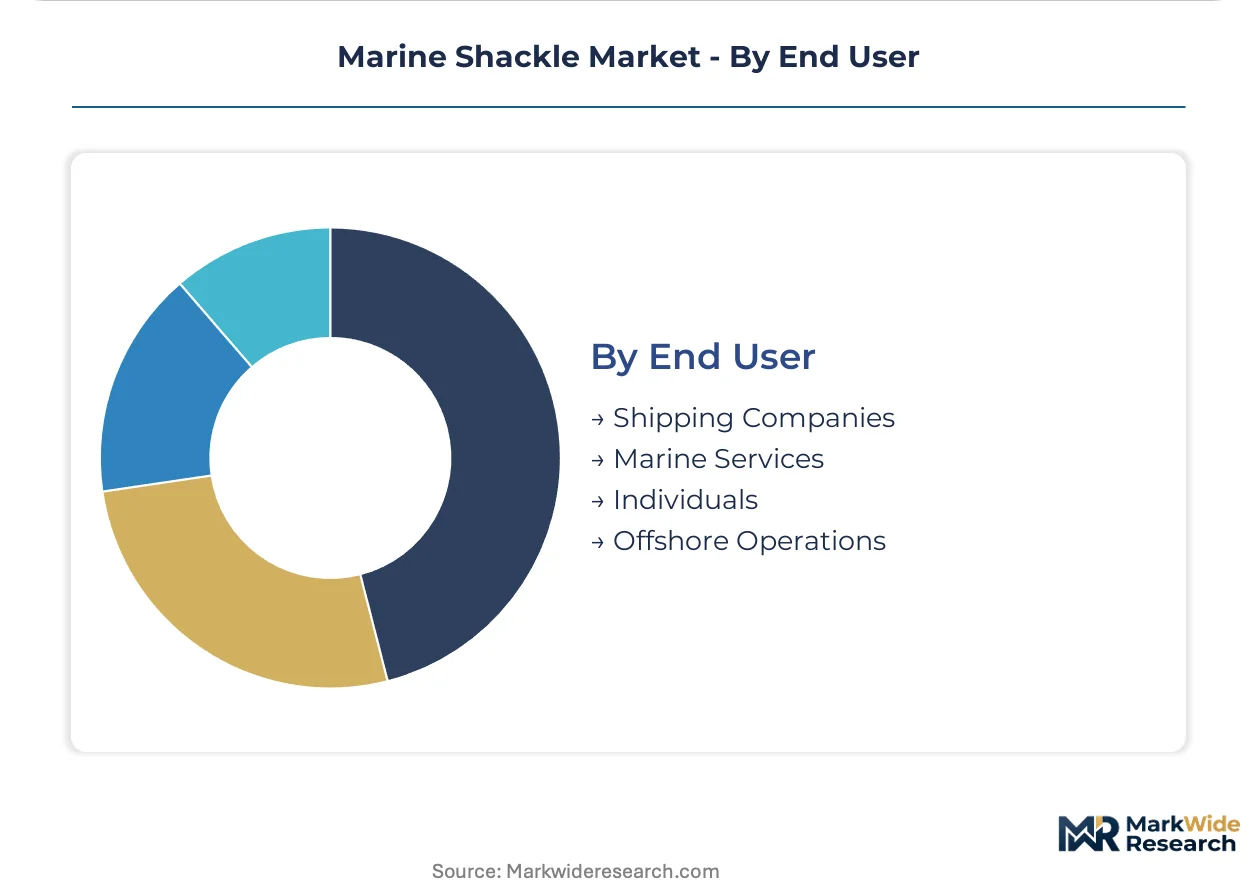
Customer type determines certification burden and procurement modality, with offshore operators imposing traceability requirements that individual buyers bypass.
- Offshore Operations:Floating wind developers and platform decommissioning contractors mandate DNV/ABS dual certification with material traceability to heat-treatment batch. Framework agreements consolidate procurement under vessel management operators.
- Shipping Companies:Fleet-wide lifting gear inventories drive recurring-revenue service contracts for inspection and recertification; Singapore's offshore support vessel cluster leads consolidation.
- Marine Services:Rigging contractors and port operators balance specification compliance with working capital constraints; spot purchasing persists for project-specific campaigns.
- Individuals:Yacht owners and coastal vessel operators prioritize corrosion resistance over load ratings; stainless steel grades dominate despite price premiums.
Shipping companies retain volume leadership; offshore operations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DNV standards anchor Norwegian offshore demand, driving specification upgrades across North Sea supply chains. National regulators and industrial clusters shape procurement patterns in four key geographies.
Norway
Floating offshore wind projects at Utsira Nord and platform decommissioning campaigns generate demand for super-diameter shackles rated above 500 tonnes. DNV-ST-N001 certification mandates eliminate cast alternatives from procurement lists. Stavanger's subsea engineering cluster concentrates specification-setting power for North Sea mooring systems.
United Kingdom
ScotWind lease rounds and North Sea Transition Authority decommissioning timelines accelerate spot-market purchases of high-capacity bow shackles. HSE offshore safety directives enforce traceable load ratings for lifting gear on UK-flagged vessels. Aberdeen's oilfield services hub coordinates topside lift campaigns requiring fatigue-tested alloy grades.
Germany
Offshore wind installation vessels operating from Cuxhaven and Bremerhaven drive demand for DNV-certified safety shackles with captive pin mechanisms. EU Machinery Directive CE marking mandates electronic traceability for shackles on European-flagged ships. The Ruhr Valley's heat-treatment facilities create single-point vulnerability for just-in-time delivery to North Sea yards.
Japan
METI's 2040 floating wind feed-in tariff targets create first-mover opportunities for dual-certified manufacturers. JIS standards for marine lifting equipment require material certification parallel to DNV specifications. Nagoya's heavy forging corridor hosts partnerships targeting domestic offshore wind mooring supply chains.
United States
Gulf of Mexico brownfield revival drives API RP 2D-compliant shackle upgrades for aging platform maintenance. OSHA maritime safety directives enforce periodic inspection regimes for offshore lifting gear. Houston's offshore engineering cluster specifications influence procurement across the Americas shelf.
Marine Shackle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the marine shackle value chain. The market structure consolidates around heat-treatment specialists, integrated testing houses, and forged alloy steel fabricators. Three strategic archetypes dominate: DNV-certified premium specialists, stainless steel corrosion-resistance providers, and galvanized carbon steel volume producers. Competitive moves concentrate on backward integration into alloy steel billet sourcing and captive heat-treatment capacity expansion.
Among European forging specialists, Crosby Group LLC and Van Beest B.V. exemplify the premium-tier positioning anchored in safety-critical bow shackle grades. Gunnebo Industries AB occupies a position within the integrated testing protocol segment, representing the archetype of suppliers exceeding baseline classification requirements. These three companies illustrate how heat-treatment expertise, forged alloy steel specialization, and testing rigor define competitive differentiation in offshore-grade procurement frameworks.
| Leading Market Players |
|---|
| Columbus McKinnon Corporation |
| Crosby Group LLC |
| Gunnebo Industries AB |
| Van Beest B.V. |
| Mazzella Companies |
| James Fisher and Sons plc |
| Sotra Anchor & Chain AS |
| Campbell Chain Company |
| Peerless Industrial Group |
| Others |
Supply & Pricing Matrix
Long-term framework agreements with embedded recertification schedules lock in supply access for offshore operators while stabilizing alloy steel billet costs against nickel and molybdenum volatility. This contract structure concentrates procurement power among vessel management operators in Singapore's offshore support cluster and de-risks heat-treatment capacity investments for European forgers.
Pricing Analysis
Price spreads between DNV-certified alloy grades and commodity galvanized carbon steel widen in Norway's North Sea cluster versus Asian commercial shipping hubs. Three-tier pricing structure across premium fatigue-certified, standard proof-tested, and economy galvanized tiers reflects certification burden and material traceability requirements. Pricing pressure stems from scrap steel volatility squeezing margins on fixed-price offshore contracts. Commercial shipping fleets exhibit highest price sensitivity; floating wind developers accept premium positioning for fatigue-rated super-diameter specifications.
Supply Chain Analysis
Ruhr Valley heat-treatment facilities create single-point vulnerability for just-in-time delivery to North Sea yards. Germany, Italy, and Norway anchor forged alloy steel production; China and India supply lower-grade galvanized alternatives. Nickel-molybdenum alloy billets, zinc for hot-dip coating, and duplex stainless feedstock constitute critical input dependencies. Tariff exposure on specialty steel imports threatens cost structures for non-European buyers. Distribution runs through rigging contractors and vessel management operators rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified forging technician pipelines are drying up faster than replacement rates across European maritime supply chains, constraining capacity expansion regardless of capital availability. Heat-treatment expertise and DNV-accredited testing protocols represent the scarcest capabilities for capturing premium-tier positioning.
For Market Incumbents: Secure captive heat-treatment capacity in Germany's Ruhr Valley or northern Italy before apprenticeship gaps worsen. Deepen backward integration into alloy steel billet sourcing to buffer nickel-molybdenum price volatility. Defend against RFID-embedded shackle disruptors by accelerating digital twin service contract rollouts with offshore vessel operators. For New Entrants and Emerging Players: Lead with JIS-DNV dual certification partnerships in Japan's Nagoya forging corridor to capture METI floating wind procurement. Target US Gulf of Mexico brownfield maintenance contracts where API RP 2D compliance gaps exist among incumbent suppliers. White-space concentration sits in sub-500-tonne safety shackle segments for harbor towage operators seeking captive pin specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated testing and inspection service providers managing fleet-wide lifting inventories. Five-to-ten-year viability favors forgers with in-house heat-treatment and DNV-ABS dual accreditation rather than standalone hardware manufacturers. Watch for ScotWind and Utsira Nord project award announcements as inflection signals for super-diameter shackle demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Billet Sourcing | Insulates forging margins from nickel-molybdenum commodity swings in fixed-price contracts. |
| RFID-Embedded Shackle Production Scale-Up | Opens recurring-revenue service contracts with Singapore vessel management operators. |
| DNV-ABS Dual Certification Investment | Qualifies suppliers for UK North Sea decommissioning and floating wind mooring frameworks. |
| Topology-Optimized Additive Manufacturing Pilot | Compresses custom super-diameter shackle lead times for Norwegian subsea contractors. |
| Japan Local Forging Partnership Establishment | Positions first-movers for METI 2040 floating wind feed-in tariff procurement windows. |
Research Methodology
Initial hypotheses were tested against primary input from forging plant managers, offshore vessel procurement officers, classification society surveyors, and rigging contractor technical directors and refined through secondary validation. DNV-ST-N001 revision documents, IMO Lifting Appliances Code amendments, EU Machinery Directive CE marking guidance, and customs trade data on alloy steel billet flows supplied triangulation anchors. Bottom-up volume builds across product type, material grade, application, and end-user segments were cross-checked against top-down market sizing from heat-treatment capacity utilization rates.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in alloy versus galvanized material tiers. Segmentation dimensions modeled include shackle geometry, certification grade, corrosion resistance specification, operating environment depth, and procurement modality. CAGRs were derived from segment-level growth rate reconciliation against macro offshore wind installation forecasts and North Sea decommissioning timelines. Floating wind mooring load specifications and subsea inspection interval extensions served as industry-specific demand elasticity inputs.
Forecasts assume regulatory continuity in EU Machinery Directive CE marking enforcement and IMO lifting gear certification regimes; material policy shifts would require re-modeling procurement qualification timelines. Alloy steel commodity volatility and apprenticeship program graduation rates constitute primary forecast revision triggers. Practitioners should keep alternative scenarios live as floating wind platform deployment schedules and German IHK certification output evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Hydrofoil Market
Marine
Dynamic Positioning System Market
Marine
Japan Marine Composites Market
Marine
Marine Lighting Market
Marine
Ship Heat Exchanger Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Marine Filter Market
Marine
Submarine Propulsion Systems Market
Marine
Boat Steering Systems Market
Marine
Marine Asset Integrity Services Market
Marine
Marine and Marine Management Software Market
Marine
Marine Turbocharger Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Global Discount-Marine Trenchers Market
Marine
Boat Control Lever Market
Marine
Hybrid Fishing Boats Market