
 North Sea Offshore Support Vessels Market | 2026-2036
North Sea Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Offshore Support Vessels Market Analytics
EU MRV and the FuelEU Maritime initiative is realigning the cost-of-entry calculus for vessel operators serving North Sea energy fields. Solstad Offshore ASA leverages its hybrid-powered fleet to differentiate in charter markets where emission profiles now determine contract eligibility. DOF ASA anchors its position through R&D intensity in subsea construction support. BOURBON Corporation competes across the logistics service tier with standardized vessel specifications that reduce operational variability.
Offshore support vessels are purpose-built marine craft, typically ranging from 50 to 150 meters in length, designed to transport personnel, equipment, and supplies to offshore installations while maintaining dynamic positioning capability in harsh North Sea conditions. Their primary commercial purpose centers on sustaining continuous offshore energy production through logistics, maintenance, and emergency response functions. Platform supply vessels anchor the service type segment with mature demand tied to existing oil and gas infrastructure, while installation services represent the fastest-expanding category as offshore wind construction intensifies. Client type concentration is shifting from oil and gas operators toward renewable energy developers, though decommissioning obligations sustain multi-client vessel utilization across both sectors.
The International Maritime Organization's EEXI and CII frameworks apply directly to North Sea vessel operations, while the EU F-Gas Regulation governs refrigeration and fire suppression systems aboard support fleets. Norway's Petroleum Safety Authority and the UK Maritime and Coastguard Agency enforce complementary safety and environmental standards that shape vessel design specifications and operational certification requirements. Stakeholders must monitor the divergence between national offshore wind lease timetables and shipyard capacity for next-generation low-emission vessel construction.
Market Dynamics
The EU Green Deal is compressing vessel replacement cycles across North Sea energy corridors. Charter eligibility now hinges on verified emission profiles rather than day-rate competitiveness alone, forcing operators to retire conventional tonnage ahead of technical obsolescence.
Growth Catalysts
- Offshore wind installation campaigns:Denmark and the United Kingdom are expanding lease rounds that require specialized jack-up and cable-lay support. Vessel demand from renewable developers now parallels traditional oil and gas logistics.
- FuelEU Maritime mandates:The regulation's well-to-wake emission accounting is disqualifying conventional diesel-electric fleets from EU port calls. Operators with hybrid or methanol-ready vessels capture preferential charter terms.
- Decommissioning liability enforcement:Norway's Petroleum Safety Authority is accelerating platform removal timelines. Plug-and-abandonment operations sustain utilization for heavy-lift and construction support vessels through 2035.
Market Restraints
- Steel price volatility:Hull construction costs fluctuate with European plate steel markets. Shipyard quotations for low-emission newbuilds carry 40-60% premiums over conventional specifications.
- Shipyard capacity concentration:Specialized offshore vessel construction concentrates in Norwegian, Dutch, and Turkish yards. Orderbook saturation delays delivery slots for next-generation tonnage.
- Battery energy density limits:Current lithium-ion configurations cannot sustain dynamic positioning operations beyond 8-12 hours in North Sea wave states. Range anxiety constrains pure-electric designs.
Strategic Opportunities
- Danish offshore wind lease expansion:The Danish Energy Agency's Kriegers Flak and Bornholm clusters require dedicated service operation vessels. First-mover fleets secure decade-long charter coverage.
- Hydrogen fuel cell convergence:Proton exchange membrane systems paired with ammonia cracking are entering pilot phases. Early adopters position for zero-emission certification ahead of 2040 mandates.
- Remote inspection technology integration:Unmanned surface vessels and subsea drones reduce crewed vessel days for routine maintenance. Hybrid mothership designs capture this operational compression.
Industry Challenges
- Marine electrician skill scarcity:High-voltage DC systems and energy storage integration require certifications that exceed traditional marine engineering curricula. Training pipeline gaps extend crew recruitment timelines.
- Class society approval bottlenecks:Novel propulsion configurations face prolonged DNV and Lloyd's Register review cycles. First-of-kind vessel certifications delay revenue service by 6-18 months.
- Legacy contract incompatibility:Existing oil and gas charter agreements lack emission-adjusted rate mechanisms. Renegotiation friction slows fleet reallocation between sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Offshore Support Vessels Market |
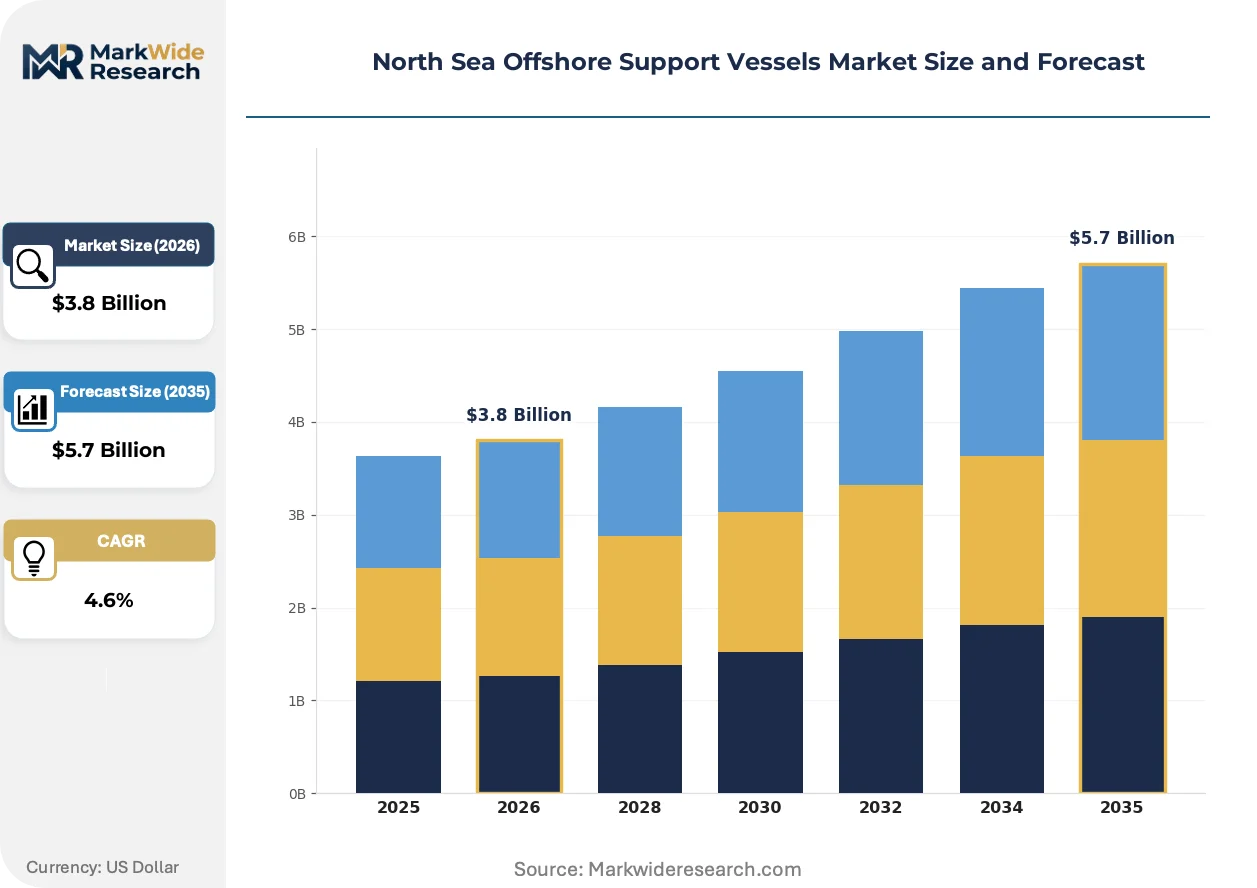
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: AHTS, PSV, ERRV, MPSV Service Type: Logistics, Maintenance, Installation, Emergency Response Client Type: Oil & Gas, Renewable Energy, Marine Research, Construction Deployment Model: Charter, Ownership, Leasing, Management |
| Companies Covered | Solstad Offshore ASA, DOF ASA, BOURBON Corporation, Havila Shipping ASA, Tidewater Inc., Siem Offshore Inc., Maersk Supply Service, Eidesvik Offshore, Gulfmark Offshore Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Offshore Support Vessels Market Evolving Landscape
Propulsion architecture is the primary battleground for competitive differentiation. Vessel operators are engineering out fossil dependency while maintaining station-keeping reliability in force-8 North Sea conditions.
Battery-hybrid propulsion is electrifying platform supply vessel operations. Norwegian operators are retrofitting existing tonnage with 1-2 MWh energy storage modules to enable zero-emission port transits and DP-2 redundancy. The technology is compressing fuel consumption by 15-25% on typical supply runs, though full-electric range remains constrained by deck space for battery banks.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants and fire suppression agents aboard North Sea fleets. Vessel owners must retrofit or replace HFC-based systems with CO2 or fluorinated ketone alternatives before 2030. Offshore wind service vessels with extended port stays face the tightest compliance timelines, driving demand for integrated HVAC and fire safety system overhauls.
Charter contracting is consolidating around performance-guarantee structures. Offshore wind developers in the United Kingdom now tie 30-40% of vessel payments to uptime availability and emission performance metrics rather than day rates alone. This compresses operator margins during weather downtime but rewards technical reliability with contract extensions and fleet expansion rights.
North Sea Offshore Support Vessels Market Segmentation
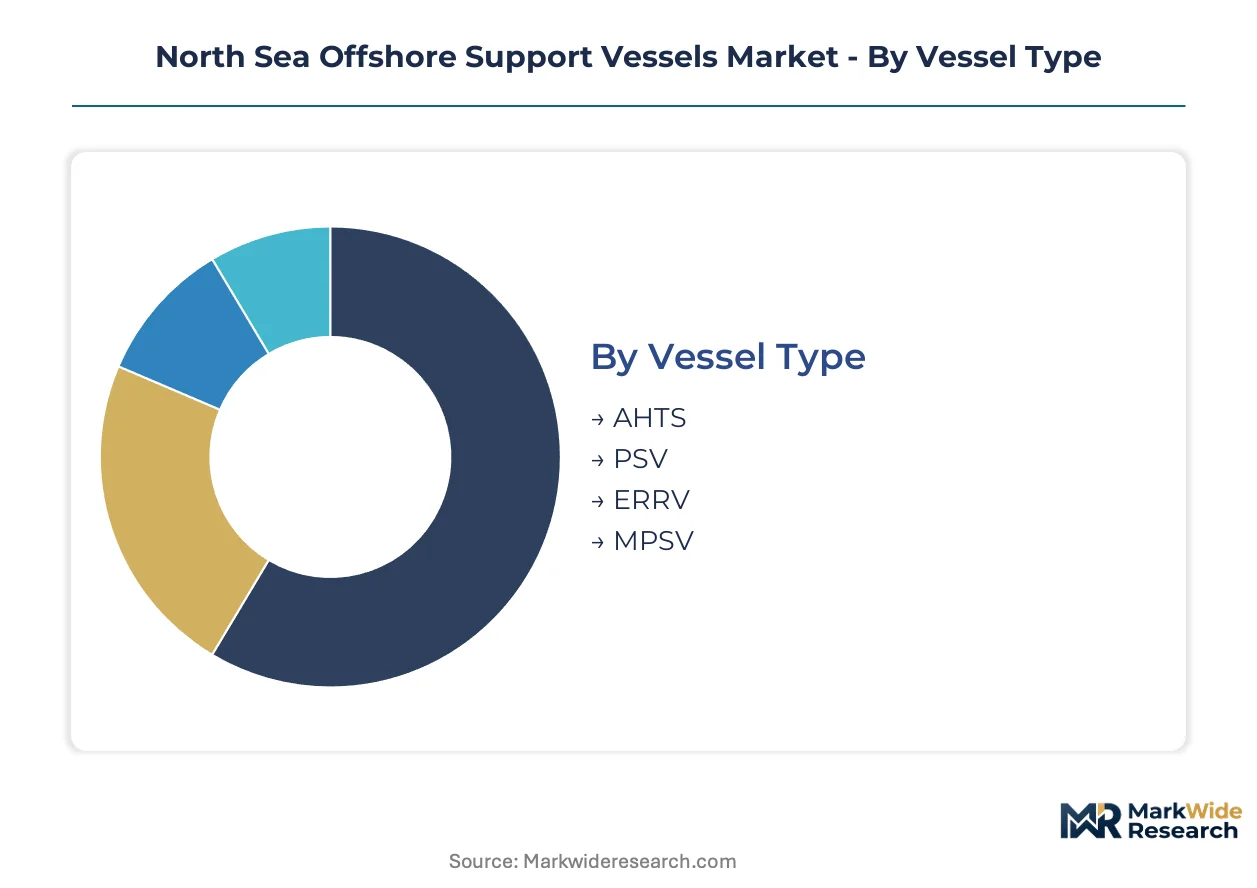
Vessel specification determines charter eligibility under tightening emission frameworks. Each segmentation axis reveals distinct competitive dynamics between legacy oil and gas service models and emerging renewable energy logistics requirements.
Vessel Type:
Hull architecture and propulsion configuration define operational capability in North Sea wave states.
- AHTS (Anchor Handling Tug Supply):Twin-screw propulsion with 100-150 tonne bollard pull ratings enables platform towing and anchor pre-lay operations. Norwegian operators deploy these for subsea construction support in the Barents Sea, though fuel consumption profiles face scrutiny under EU MRV reporting.
- PSV (Platform Supply Vessel):Deck cargo capacity of 1,000-4,000 square meters sustains drilling platform logistics with ROV hangars and liquid mud tanks. United Kingdom North Sea demand concentrates on walk-to-work vessels with motion-compensated gangways for offshore wind technician transfer.
- ERRV (Emergency Response and Rescue Vessel):Standby rescue capacity with fire-fighting Class 1 certification protects manned installations.
- MPSV (Multi-Purpose Support Vessel):Heavy-lift cranes exceeding 250 tonnes combined with subsea moonpools serve decommissioning campaigns.
Mature deployment sits with PSV tonnage serving existing oil and gas infrastructure. Newer deployment is concentrated in MPSV configurations purpose-built for offshore wind foundation installation.
Service Type:
Revenue stability varies sharply between contracted maintenance schedules and project-based installation campaigns.
- Logistics:Routine cargo runs from Aberdeen, Esbjerg, and Stavanger supply bases sustain platform operations with 95%+ schedule reliability requirements.
- Maintenance:Scheduled shutdown support and subsea inspection contracts generate recurring revenue streams. Danish offshore wind clusters drive demand for service operation vessels with integrated workboat and accommodation functions.
- Installation:Jack-up vessel positioning and cable-lay support for offshore wind arrays operate on 12-18 month project cycles with high day-rate volatility.
- Emergency Response:Regulatory-mandated standby coverage for manned platforms operates on fixed standby tariffs with limited upside.
Revenue predictability clusters around Maintenance contracts with multi-year visibility. Installation services capture the steepest expansion trajectory as offshore wind construction accelerates.
Client Type:
Procurement sophistication diverges between established oil majors and renewable developers building fleet relationships.
- Oil & Gas:Integrated operators like Equinor and Shell charter on 3-5 year frameworks with emission-adjusted rate mechanisms.
- Renewable Energy:Ørsted and RWE specify hybrid-propulsion vessels for construction and O&M phases, often requiring 10-15 year charter commitments.
- Marine Research:Oceanographic institutes deploy modified support vessels for seabed survey and environmental monitoring.
- Construction:EPC contractors sub-charter specialist vessels for decommissioning and civil marine projects on spot-market terms.
Contract duration extends longest with Renewable Energy developers securing fleet availability. Spot-market exposure concentrates with Construction clients on project-specific tenders.
Deployment Model:
Capital structure preferences reflect balance sheet capacity and risk tolerance across operator tiers.
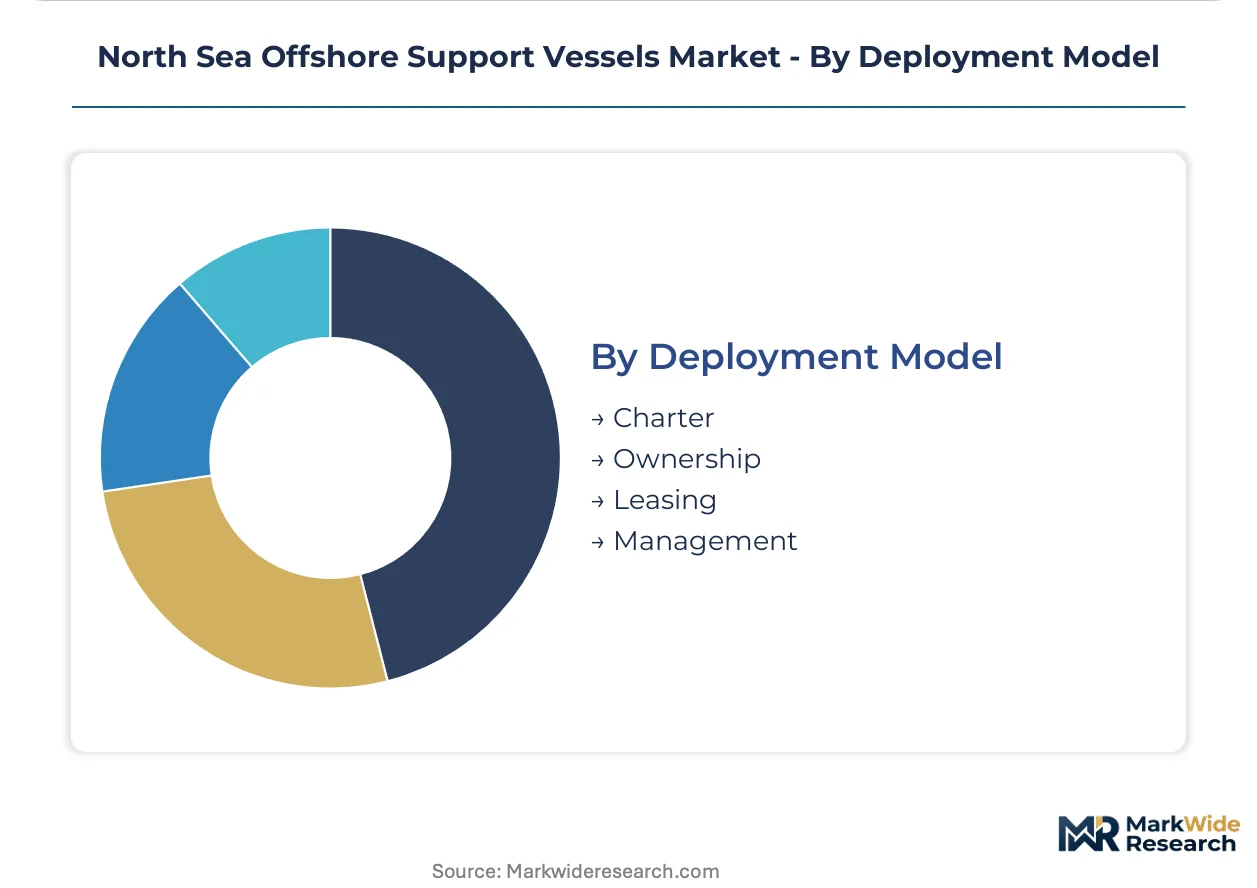
- Charter:Vessel operators retain ownership while energy companies assume operational risk through time-charter or bareboat arrangements.
- Ownership:Major energy companies directly own specialist tonnage for strategic fleet control, particularly for emergency response assets.
- Leasing:Sale-and-leaseback structures free operator capital for newbuild programs while lessors assume residual value risk.
- Management:Third-party technical managers handle crewing, maintenance, and regulatory compliance for vessel owners lacking operational infrastructure.
Capital efficiency favors Charter structures for renewable developers avoiding fleet ownership. Ownership models persist for Oil & Gas majors with integrated logistics requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind lease expansions and decommissioning obligations concentrate vessel demand across five North Sea littoral states. Each national regulatory framework reshapes fleet specifications and charter eligibility.
Norway
Equinor's floating offshore wind projects and Barents Sea field developments sustain demand for heavy-lift construction support. The Petroleum Safety Authority enforces accelerated platform removal timelines that sustain plug-and-abandonment vessel utilization. Stavanger and Bergen anchor subsea service clusters where operators retrofit hybrid propulsion into existing anchor handling tonnage.
United Kingdom
The Crown Estate's leasing rounds for floating wind in the Celtic Sea and Scottish waters require specialized jack-up support. The Maritime and Coastguard Agency implements IMO EEXI and CII frameworks that disqualify conventional diesel-electric fleets from port calls. Aberdeen maintains its logistics hub status while Great Yarmouth expands as an offshore wind construction staging base.
Denmark
The Danish Energy Agency's Kriegers Flak and Bornholm energy island projects drive demand for cable-lay and service operation vessels. FuelEU Maritime mandates apply directly to vessels operating from Esbjerg and Copenhagen. The Port of Esbjerg concentrates turbine component handling and vessel mobilization for Baltic Sea arrays.
Netherlands
Hollandse Kust wind zones and IJmuiden Ver developments require dedicated installation support tonnage. The Dutch Human Environment and Transport Inspectorate enforces emission reporting under EU MRV regulations. Rotterdam and IJmuiden serve as primary marshalling ports where vessel operators secure decade-long charter coverage with renewable developers.
Germany
North Sea offshore wind repowering and Baltic Sea new-build campaigns sustain demand for multi-purpose support vessels. The Federal Maritime and Hydrographic Agency coordinates safety standards with neighboring littoral states. Cuxhaven and Wilhelmshaven host turbine manufacturing facilities that generate dedicated vessel requirements for component transport and installation.
North Sea Offshore Support Vessels Market Competitive Landscape
Norwegian operators anchor the premium tier with specialized subsea and construction support capabilities; Dutch and UK specialists hold regional logistics positions through standardized platform supply tonnage. Market structure consolidates around three strategic archetypes: integrated offshore service groups with diversified vessel portfolios, pure-play renewable energy specialists with hybrid-propulsion fleets, and construction-focused operators targeting decommissioning campaigns. Competitive moves concentrate on fleet renewal programs and charter contract restructuring to embed emission-adjusted rate mechanisms.
Within the integrated service tier, Solstad Offshore ASA and DOF ASA occupy positions exemplifying hybrid-powered fleet differentiation and subsea construction R&D intensity. BOURBON Corporation represents the standardized logistics archetype with vessel specifications designed to reduce operational variability across charter markets.
| Leading Market Players |
|---|
| Solstad Offshore ASA |
| DOF ASA |
| BOURBON Corporation |
| Havila Shipping ASA |
| Tidewater Inc. |
| Siem Offshore Inc. |
| Maersk Supply Service |
| Eidesvik Offshore |
| Gulfmark Offshore Inc |
| Others |
Value Network & Pricing Analysis
European plate steel prices feed directly into newbuild vessel quotations, with Norwegian and Dutch shipyards passing through 40-60% premiums for low-emission specifications to offshore wind developers and oil majors chartering under EU MRV frameworks.
Pricing Analysis
Short-lead-time premiums dominate charter contracting as Danish and UK offshore wind lease expansions compress mobilization windows. Vessel operators command rate escalations for hybrid-propulsion tonnage available within 90-day windows, while spot-market conventional diesel-electric fleets trade at discounts reflecting FuelEU Maritime disqualification risk. Price differentiation hinges on emission certification tier and dynamic positioning redundancy class. Charter payments now tie 30-40% to uptime availability metrics rather than flat day rates, squeezing margins during North Sea weather downtime. Renewable energy developers exhibit lowest price sensitivity, prioritizing decade-long fleet availability over rate negotiation.
Supply Chain Analysis
Specialized hull steel draws from Swedish and German mills, with propulsion system integration anchored in Norwegian and Finnish engineering clusters. Battery energy storage modules rest on South Korean and Chinese cell manufacturers, while azimuth thruster assemblies source from German and Dutch marine equipment specialists. Single-source vulnerability concentrates in proton exchange membrane fuel cell stacks, where European suppliers remain pre-commercial. Distribution runs through Stavanger, Aberdeen, and Esbjerg logistics hubs serving North Sea energy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North Sea Offshore Support Vessels Market is fundamentally a cost-of-compliance story. FuelEU Maritime's well-to-wake emission accounting erects a barrier-to-entry moat that rewards early hybrid-propulsion adopters while stranding conventional tonnage.
For Market Incumbents: Anchor fleet renewal programs around methanol-ready and hydrogen fuel cell pilot vessels to preempt 2040 zero-emission mandates. Secure long-term charter coverage with Ørsted and RWE before shipyard orderbook saturation extends delivery slots. Vertical integration into battery system maintenance capabilities offsets marine electrician skill scarcity threatening crew recruitment timelines. For New Entrants and Emerging Players: Begin with service operation vessel niches in Danish Kriegers Flak and Bornholm clusters where first-mover fleets capture decade-long contracts. Target decommissioning-heavy Norwegian segments where plug-and-abandonment operations sustain utilization through accelerated platform removal timelines. Pursue sale-and-leaseback structures with Nordic maritime lessors to bypass capital intensity barriers. For Investors and Strategic Acquirers: Danish Energy Agency lease round announcements are the leading indicator that vessel demand inflection is materializing. Position for 5-10 year holding periods as fleet replacement cycles compress under EU Green Deal timelines. Acquisition targets should display hybrid-propulsion orderbook exposure and existing relationships with UK or Danish offshore wind developers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | Battery-hybrid installations enable zero-emission port transits under FuelEU Maritime compliance frameworks. |
| Methanol-Ready Newbuild Investment | Dual-fuel engines position fleets for 2040 zero-emission certification ahead of regulatory mandates. |
| Subsea Construction R&D Partnership | Collaboration with Norwegian subsea clusters anchors premium positioning in decommissioning campaigns. |
| Long-Term Charter Restructuring | Emission-adjusted rate mechanisms align operator incentives with offshore wind developer ESG requirements. |
| Remote Inspection Technology Integration | Unmanned surface vessels reduce crewed vessel days for routine maintenance in harsh North Sea conditions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with vessel operators, offshore wind project developers, shipyard procurement managers, and maritime classification society surveyors. Norwegian Petroleum Safety Authority decommissioning schedules, UK Maritime and Coastguard Agency certification databases, and EU MRV emission reports provided operational validation. Bottom-up vessel deployment counts triangulated against top-down charter market value estimates.
Granularity-level modeling distinguished vessel type, service category, client segment, and deployment structure across the projection horizon. Platform supply vessel, anchor handling tug supply, and multi-purpose support vessel categories were modeled separately with distinct utilization assumptions. Installation, maintenance, logistics, and emergency response service types carried differentiated day-rate and contract duration parameters. CAGRs were derived from charter rate trajectories, fleet replacement schedules, and offshore wind capacity build-out pipelines.
Underlying measurement precision varies by segment; platform supply vessel estimates carry tighter precision given mature oil and gas infrastructure visibility, while hydrogen fuel cell vessel projections reflect pre-commercial uncertainty. Forecasts embed assumptions around EU Green Deal implementation pace, shipyard delivery slot availability, and battery energy density improvement curves. A small set of named triggers warrants ongoing watch: Norwegian platform removal timeline acceleration, Danish lease round award announcements, and DNV/Lloyd's Register certification backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fender Market
Marine
Marine Electronics Market
Marine
Boat Trolling Motor Market
Marine
Marine Shaft Power Meter Market
Marine
Boat Cleat Market
Marine
Marine Fasteners Market
Marine
Swamp Boat Market
Marine
Dynamic Positioning System Market
Marine
Marine Chartplotter Market
Marine
US Fish Finders Market
Marine
Marine Spreader Lights Market
Marine
Europe Recreational Boating Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Ship Searchlight Market
Marine
Mooring Ropes Market
Marine
Ship Rudders Market