
 Automotive Fuel Nozzle Market | 2026-2036
Automotive Fuel Nozzle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Nozzle Market Analytics
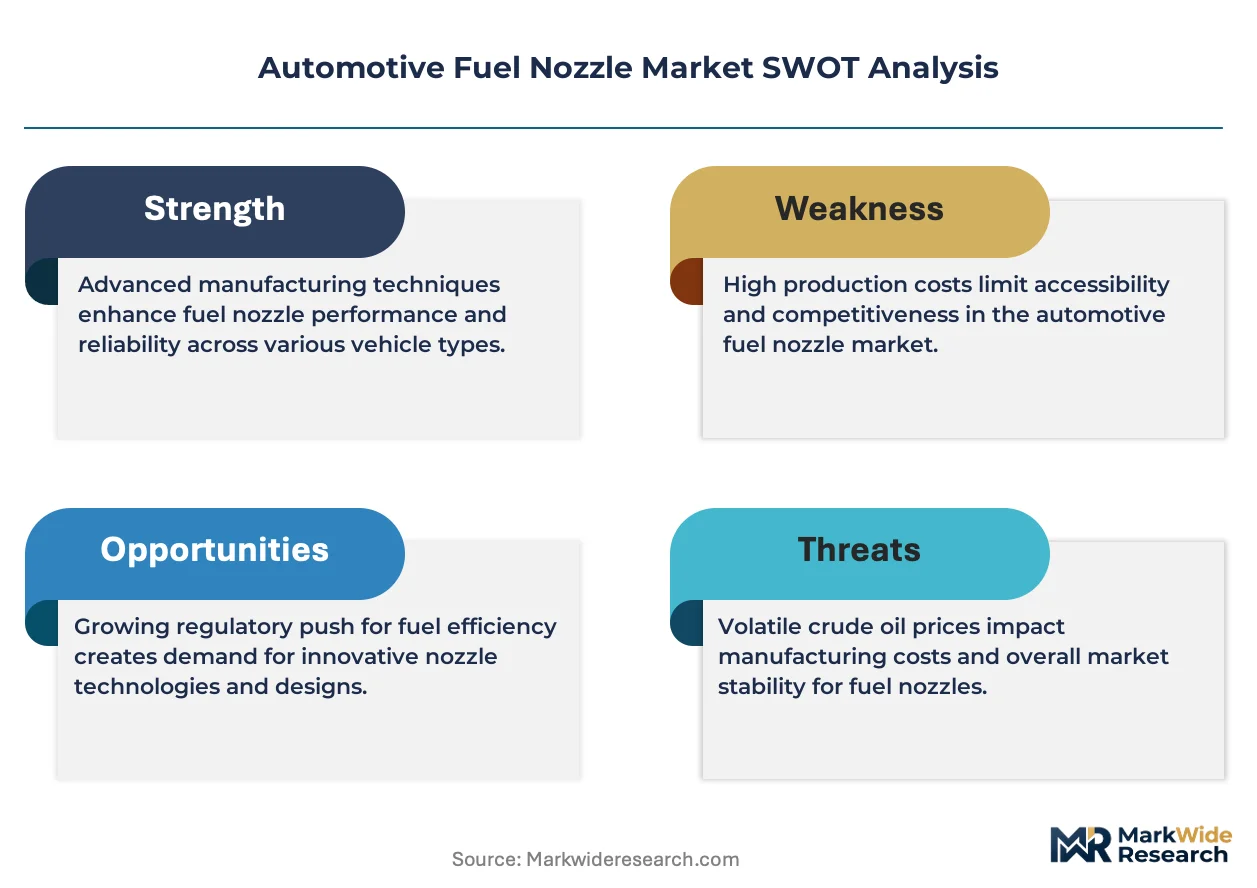
China is tilting toward higher-precision fuel nozzle manufacturing as domestic automotive production scales. Robert Bosch GmbH leverages its injection systems heritage to anchor European supply relationships. Denso Corporation sustains Japanese OEM channel control through integrated sensor-nozzle architectures. Continental AG competes on electronic control module compatibility across multiple nozzle platforms.
An automotive fuel nozzle is a precision-engineered dispensing device, typically constructed from aluminum alloys or stainless steel with fluorocarbon seals, designed to deliver measured fuel volumes into vehicle tanks while minimizing vapor emissions and static discharge risks. Its primary commercial purpose centers on safe, compliant, and efficient refueling operations across retail, fleet, and industrial settings. Smart nozzles with sensor integration command premium positioning as fuel retailers pursue automated transaction accuracy and leak detection capabilities. Conventional mechanical nozzles still dominate volume in emerging markets where cost sensitivity and simpler infrastructure prevail. Dual fuels nozzles represent a narrower but expanding niche serving bi-fuel vehicle parc growth.
EPA vapor recovery regulations and California Air Resources Board certification requirements shape nozzle design mandates in the United States, while China's SAMR enforces GB standards on refueling equipment safety and metrology. The EU F-Gas Regulation and REACH compliance obligations add material selection constraints for suppliers serving European fuel retailers. Stakeholders must monitor how electrification timelines alter refueling infrastructure investment priorities and nozzle replacement cycles.
Market Dynamics
Retrofit cycles at existing fuel retail networks are compressing replacement timelines as EPA Tier 3 sulfur standards and California Air Resources Board vapor recovery rules force hardware upgrades across aging infrastructure.
Growth Catalysts
- Emissions tracking mandates:Commercial fleet operators face regulatory pressure to document fuel consumption and vapor capture, pulling smart nozzle systems into procurement specifications.
- GB standards enforcement:China's SAMR has tightened refueling equipment safety and metrology rules, accelerating domestic manufacturing upgrades toward higher-precision nozzle output.
- Bi-fuel vehicle parc expansion:Dual-fuel nozzle architectures are capturing incremental demand as compressed natural gas and liquefied petroleum gas vehicle populations grow in select markets.
Market Restraints
- Aluminum alloy price volatility:Primary metal input costs swing with energy and smelter capacity constraints, squeezing margin stability for precision casting operations.
- Fluorocarbon seal supply concentration:Specialized elastomer production clusters in East Asia create vulnerability to logistics disruption and export control friction.
- Electrification substitution threat:Battery electric vehicle penetration is eroding addressable nozzle demand at rates that vary sharply by national policy commitment and charging infrastructure buildout.
Strategic Opportunities
- Sensor-nozzle convergence:Integrated flow measurement and leak detection architectures open premium positioning as fuel retailers automate transaction accuracy.
- Fleet telematics integration:Smart nozzle data streams can feed directly into commercial operator fuel management platforms, creating recurring service revenue models.
- EU F-Gas Regulation compliance services:Material selection consulting and REACH documentation support represent adjacent revenue for suppliers with European fuel retailer relationships.
Industry Challenges
- Cross-platform electronic control module compatibility:Nozzle suppliers must engineer for multiple dispenser communication protocols, fragmenting development resource allocation.
- Certification timeline compression:California Air Resources Board and EPA approval cycles for new vapor recovery configurations extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Nozzle Market |
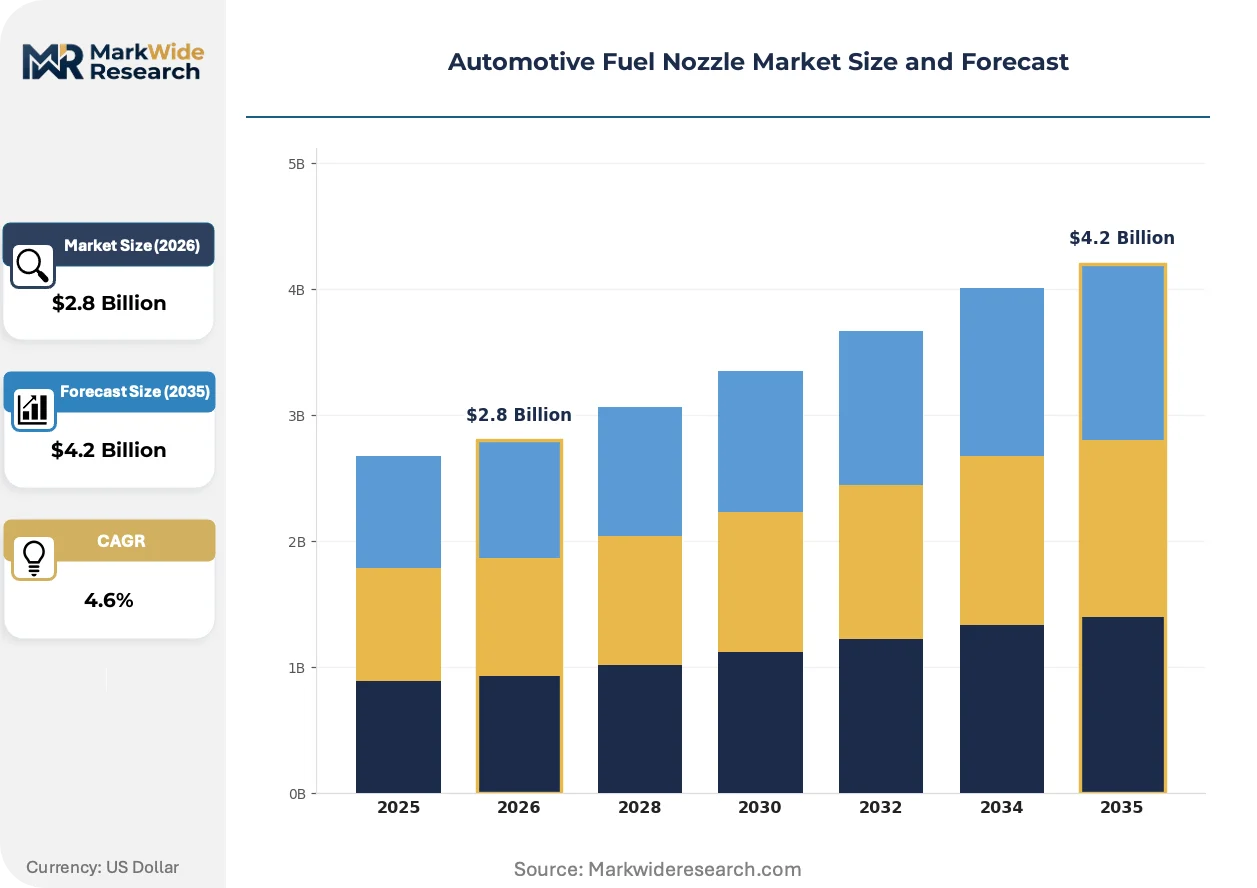
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Nozzles, Smart Nozzles, Automatic Shut-off Nozzles, Dual Fuels Nozzles End User: Fuel Retailers, Commercial Fleets, Fuel Distributors, Automotive Manufacturers Deployment: Onshore Installation, Mobile Services, Stationary Solutions, Industrial Applications Technology: Mechanical Technology, Electronic Control, Sensor Integration, Digital Displays |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Delphi Technologies, Keihin Corporation, Magneti Marelli, Infineon Technologies AG, Hitachi Astemo, Stanadyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Nozzle Market Evolving Landscape
Active sensor integration and automated fuel management systems are redefining nozzle value propositions beyond mechanical dispensing, while regulatory material bans and electrification timelines force portfolio repositioning.
Ultrasonic flow measurement embedded directly into nozzle spouts is rendering obsolete traditional mechanical meter-dependent architectures. Major fuel retailers in North America and Western Europe are piloting these systems at high-throughput sites. The shift is compressing supplier margins on legacy mechanical platforms while opening service-contract revenue streams.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are forcing fluorocarbon seal material substitutions across European-bound product lines. Suppliers serving EU fuel retailers must requalify elastomer compounds under tightened environmental safety thresholds. German and French retail networks are already specifying next-generation seal materials in procurement tenders.
Fuel retailers are unbundling after-sales service from hardware procurement, contracting maintenance and calibration separately through specialized field service providers. This disintermediation is disrupting traditional nozzle supplier channel control in mature markets. The pattern is most advanced in the United States, where independent service organizations now capture significant share of nozzle lifecycle revenue.
Automotive Fuel Nozzle Market Segmentation
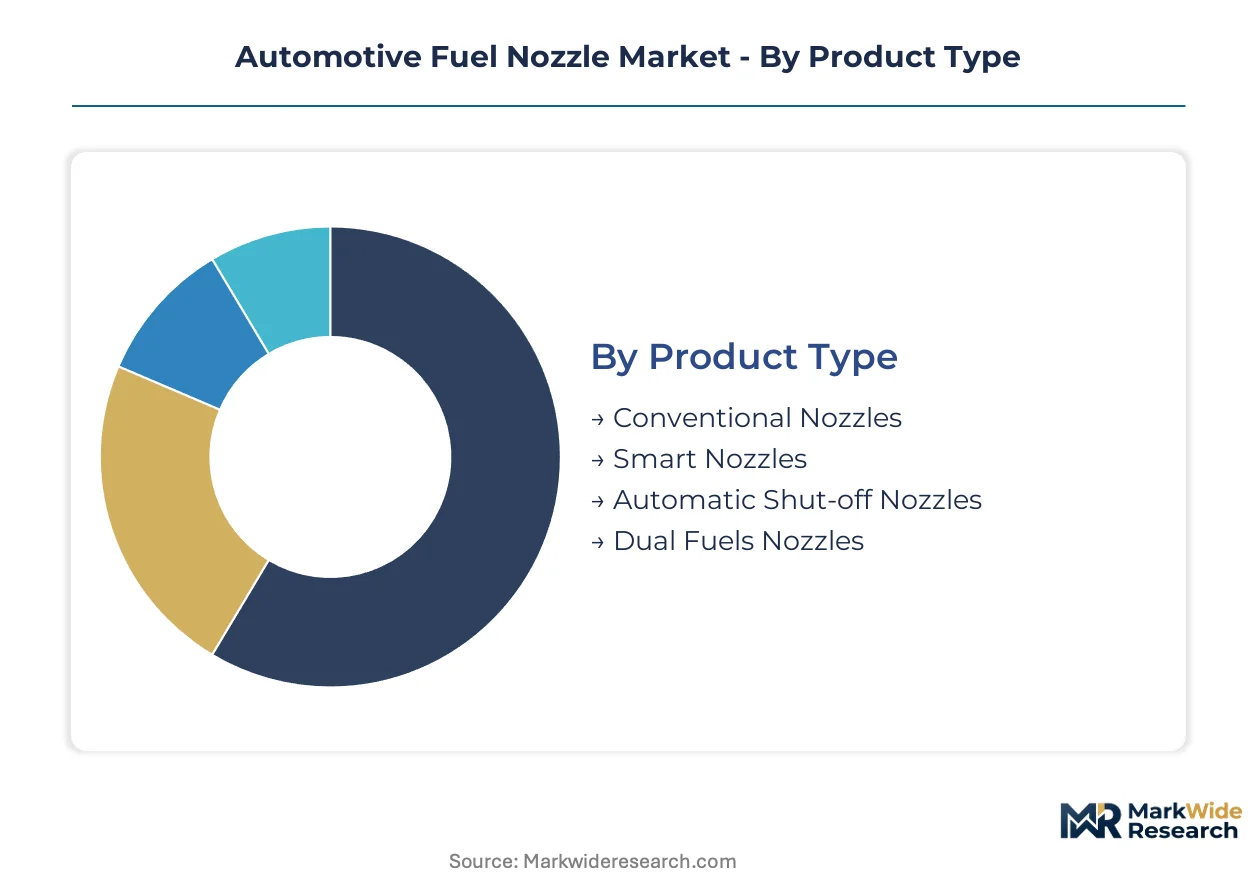
Segmentation in the automotive fuel nozzle market reveals divergent service intensity requirements across hardware categories. Procurement patterns vary sharply between high-frequency retail deployments and specialized fleet installations.
Product Type:
After-sales service intensity varies dramatically by nozzle architecture, with sensor-embedded systems demanding continuous calibration support versus mechanical platforms requiring only periodic seal replacement.
- Conventional Nozzles:Aluminum alloy construction with fluorocarbon seals and spring-loaded shut-off mechanisms. Demand concentrates at independent fuel retailers across emerging markets where capital constraints limit smart infrastructure investment; these operators prioritize replacement part availability over predictive maintenance capabilities.
- Smart Nozzles:Integrated flow sensors, leak detection circuits, and automated transaction interfaces define this architecture. Fleet operators in the United States specify these systems to satisfy EPA emissions tracking mandates; recurring firmware updates and sensor recalibration create ongoing service revenue streams.
- Automatic Shut-off Nozzles:Mechanical vacuum-sensing or electronic float mechanisms prevent overfill incidents.
- Dual Fuels Nozzles:Dual-port designs accommodate gasoline and compressed natural gas dispensing.
Conventional nozzles hold the largest share; momentum sits with smart nozzles.
End User:
Customer type dictates procurement scale and technical specification complexity, with national fuel retail chains operating on multi-year replacement cycles distinct from fleet operator spot purchasing.
- Fuel Retailers:High-throughput networks require CARB-certified vapor recovery configurations and SAMR-compliant metrology for Chinese installations. United States retail chains are unbundling hardware procurement from field service contracts, shifting lifecycle revenue to independent service organizations.
- Commercial Fleets:Centralized fueling depots with telematics integration requirements. These operators in California and Texas specify smart nozzle data streams feeding directly into fuel management platforms; integration complexity limits supplier switching.
- Fuel Distributors:Bulk transfer operations with high-cycle durability specifications.
- Automotive Manufacturers:OEM fuel system testing and prototype validation applications.
Fuel retailers dominate procurement volumes; commercial fleets are expanding most quickly.
Deployment:
Physical installation context determines durability specifications and regulatory compliance obligations, with permanent retail infrastructure facing distinct certification requirements from temporary field deployments.
- Onshore Installation:Fixed retail fueling positions with underground storage tank connections. Installations across the United States must satisfy EPA spill containment and CARB vapor recovery regulations; concrete island mounting specifications vary by state environmental agency requirements.
- Mobile Services:Truck-mounted or trailer-based fueling for construction and agricultural equipment. These deployments in Texas and Alberta prioritize ruggedized housing designs; vibration resistance and quick-connect portability command specification priority.
- Stationary Solutions:Fleet depot installations with dedicated island configurations.
- Industrial Applications:Marine, mining, and rail fueling with specialized flow rate requirements.
Onshore installation captures the greatest installed base; mobile services are gaining share fastest.
Technology:
Technology tier stratification reflects the transition from purely mechanical dispensing toward electronically controlled fuel management architectures.
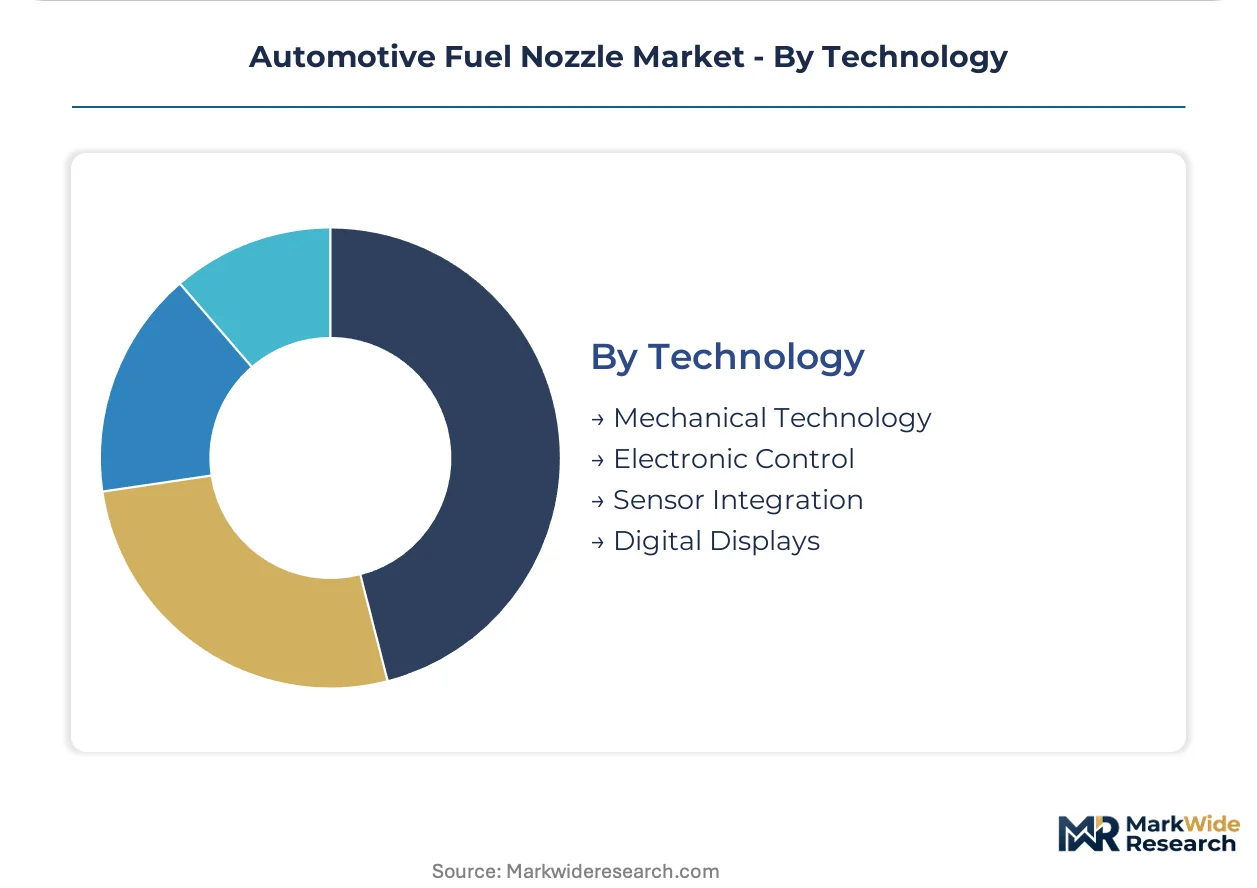
- Mechanical Technology:Spring-loaded shut-off valves and vacuum-assisted vapor recovery without electronic components. These systems retain dominance at retail networks in India and Southeast Asia where humidity and dust exposure challenge electronic reliability; simplicity supports field repairability.
- Electronic Control:Microprocessor-managed flow regulation with programmable shut-off thresholds. European fuel retailers under EU F-Gas Regulation pressure specify these platforms for precise vapor capture measurement; firmware customization enables dispenser protocol compatibility.
- Sensor Integration:Ultrasonic flow measurement and real-time leak detection embedded at the spout.
- Digital Displays:Transaction feedback interfaces integrated into nozzle handle assemblies.
Mechanical technology retains the largest installed base; electronic control shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 sulfur standards and California Air Resources Board vapor recovery mandates are compressing replacement timelines across United States fuel retail networks. Procurement concentrates in markets where regulatory enforcement intersects with aging infrastructure retrofit cycles.
United States
Fleet operators in California and Texas specify smart nozzle systems to satisfy EPA emissions tracking documentation requirements. CARB certification cycles for new vapor recovery configurations extend product launch windows for suppliers serving West Coast retail chains. Houston-Galveston refining corridor operators are accelerating depot equipment upgrades ahead of 2027 compliance deadlines.
China
Domestic automotive production scaling is pulling demand toward higher-precision nozzle manufacturing capabilities. SAMR enforcement of GB standards on refueling equipment safety and metrology is forcing manufacturing upgrades across Yangtze River Delta fabricators. Shanghai-based precision casting operations are expanding capacity to serve state-owned fuel retail network retrofit programs.
Germany
EU F-Gas Regulation phase-down schedules and REACH compliance obligations are constraining material selections for European-bound product lines. ECHA substance restrictions are forcing fluorocarbon seal requalification across Baden-Württemberg component suppliers. Munich and Stuttgart retail networks are specifying next-generation elastomer compounds in procurement tenders.
Japan
Integrated sensor-nozzle architectures dominate OEM channel relationships as domestic manufacturers pursue telematics compatibility. METI industrial standards on refueling equipment precision are tightening tolerances for Nagoya-area production facilities. Kanto region fleet operators are piloting ultrasonic flow measurement systems at high-throughput commercial depots.
India
Cost sensitivity at independent fuel retailers preserves demand for conventional mechanical nozzle platforms. BIS certification requirements on refueling equipment safety are gradually tightening import specifications for Mumbai and Delhi distribution networks. Gujarat-based manufacturing clusters are scaling aluminum alloy casting capacity to serve domestic replacement part demand.
Automotive Fuel Nozzle Market Competitive Landscape
Full-system integrators and component specialists split the market into distinct competitive spheres. Tier-1 automotive suppliers leverage dispenser protocol relationships to control premium positioning, while regional fabricators compete on replacement part availability and field service density. Strategic archetypes include sensor-embedded platform developers, conventional mechanical specialists, and dual-fuel configuration engineers. Capacity expansion and certification timeline acceleration represent the dominant competitive moves as suppliers compress product development cycles.
Within the full-system integrator tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes anchored by injection systems heritage and OEM channel control respectively. Continental AG occupies a position emphasizing electronic control module compatibility across multiple dispenser platforms. These three entities represent the scale-driven end of supplier stratification, with their geographic footprints and corporate structures reflecting deep entrenchment in European and Japanese automotive supply networks.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Delphi Technologies |
| Keihin Corporation |
| Magneti Marelli |
| Infineon Technologies AG |
| Hitachi Astemo |
| Stanadyne |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion drives freight cost volatility that amplifies price spreads between precision-cast smart nozzles and conventional mechanical alternatives, concentrating margin pressure on aluminum alloy-dependent fabricators while rewarding suppliers with captive fluorocarbon seal production.
Pricing Analysis
Price spreads between North American and Asia-Pacific procurement markets widen during raw material cost spikes. Three-tier pricing structure across smart sensor-embedded, electronic control, and mechanical platforms reflects certification grade differentiation and after-sales service bundling. Cost compression in conventional nozzle tiers is intensifying because Indian and Southeast Asian retailers prioritize replacement part availability over predictive maintenance capabilities. Fleet operators in California and Texas exhibit lowest price sensitivity due to EPA emissions tracking compliance requirements.
Supply Chain Analysis
Export control friction around fluorocarbon polymer processing equipment constrains seal material flows from East Asian production clusters. Precision casting capacity concentrates in China, Germany, and Japan, while specialized elastomer compounding draws from South Korea and Japan. Raw material dependencies span aluminum alloy ingots, fluorocarbon resins, and microprocessor components. Single-source vulnerability in fluorocarbon seal supply creates disruption exposure. Distribution runs through OEM channel partnerships for smart nozzle platforms and independent aftermarket distributors for conventional replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fuel nozzle market is entering a cyclical recovery phase as EPA Tier 3 and CARB-mandated retrofit cycles compress replacement timelines across aging United States retail infrastructure.
For Market Incumbents: Entrench sensor-nozzle platform control by accelerating ultrasonic flow measurement certification timelines ahead of 2027 compliance deadlines. Deepen backward integration into fluorocarbon seal compounding to neutralize East Asian supply concentration risks. Lock in multi-year fleet telematics integration contracts with California and Texas operators to raise switching costs. For New Entrants and Emerging Players: Pursue white-space opportunities in mobile fueling services for construction and agricultural equipment across Texas and Alberta, where vibration-resistant ruggedized housing designs command specification priority. Target India's independent fuel retailer segment with conventional mechanical nozzle platforms optimized for humidity and dust exposure. Establish field service density partnerships with regional distributors rather than competing head-to-head against incumbent OEM channel relationships. For Investors and Strategic Acquirers: Sensor-embedded platform developers with CARB certification track records represent the most defensible acquisition archetype for long-term viability through the electrification transition window. Monitor battery electric vehicle penetration rates in California and Texas as the critical inflection signal for nozzle demand erosion velocity. Evaluate targets on firmware customization capabilities and dispenser protocol compatibility breadth rather than mechanical casting scale.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Nozzle Platform Certification | CARB approval cycles for ultrasonic flow measurement systems open premium positioning at West Coast retail chains. |
| Fluorocarbon Seal Backward Integration | Captive elastomer compounding neutralizes East Asian supply concentration and REACH requalification risks. |
| Fleet Telematics Data Integration | Smart nozzle data streams feeding fuel management platforms create recurring service revenue at California depots. |
| Mobile Fueling Ruggedization | Vibration-resistant housing designs capture construction and agricultural equipment demand in Alberta and Texas. |
| EU F-Gas Compliance Services | Material selection consulting and REACH documentation support adjacent revenue from German and French retailers. |
Research Methodology
Operator-level perspectives from fuel retail procurement directors, fleet maintenance managers, and aftermarket distribution channel heads anchored the qualitative base. Secondary validation drew from EPA enforcement action records, CARB certification databases, SAMR GB standards documentation, and customs trade flow data. Bottom-up unit demand estimates triangulated against top-down fuel retail infrastructure investment tracking.
Scenario-bracketing around electrification penetration rates and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include nozzle architecture tier, end-user procurement scale, deployment context, and technology integration level. CAGRs derived from replacement cycle compression analysis and bi-fuel vehicle parc expansion trajectories. Industry-specific inputs encompassed aluminum alloy price volatility indices and fluorocarbon seal supply lead time fluctuations.
Sensitivities concentrate around battery electric vehicle adoption acceleration, EPA enforcement intensity variations, and East Asian export control escalation. Forecasts reflect documented assumptions on retrofit cycle timing and fleet telematics integration rates. Material shifts in CARB certification timelines or SAMR enforcement patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Speed Bump Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Vehicle Jump Starter Market