
 LNG Bunkering Vessel Market | 2026-2036
LNG Bunkering Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Bunkering Vessel Market Insights
A shift from single-source chartering toward multi-source vessel pooling is realigning procurement strategies across major LNG suppliers. Shell PLC leverages its integrated trading arm to secure long-term charter contracts directly with Asian shipyards. TotalEnergies SE anchors its Atlantic basin presence through dedicated bunker vessel deployments at Rotterdam and Marseille. Korea Gas Corporation competes by controlling domestic newbuild slots and extending engineering partnerships to mid-scale owners.
An LNG bunkering vessel is a specialized marine craft designed to store and transfer liquefied natural gas at temperatures below minus 162 degrees Celsius to fuel-powered ships, employing insulated cargo tanks and cryogenic pumping systems for safe cargo containment. Self-propelled bunker vessels dominate current orderbooks due to operational flexibility in congested port environments. Ship-to-ship transfer leads delivery-method adoption as terminal infrastructure matures at major hub ports. Small-scale and medium-scale size categories attract disproportionate investment where channel depths restrict larger designs.
The International Maritime Organization enforces sulphur-content limits under MARPOL Annex VI, while the EU Green Deal and F-Gas Regulation tighten emissions benchmarks for maritime fuels in European waters. The US Coast Guard and China's Maritime Safety Administration administer port-state control inspections that determine vessel eligibility for coastal LNG delivery. Stakeholders must monitor flag-state equivalency certificates and local pilotage rules as these will determine which vessel designs achieve operational clearance at emerging bunkering locations.
Market Dynamics
Container shipping lines face MARPOL Annex VI sulphur enforcement while South Korean shipyards concentrate cryogenic cargo-handling system production, creating a supply-demand asymmetry that favors early fleet commitment.
Growth Catalysts
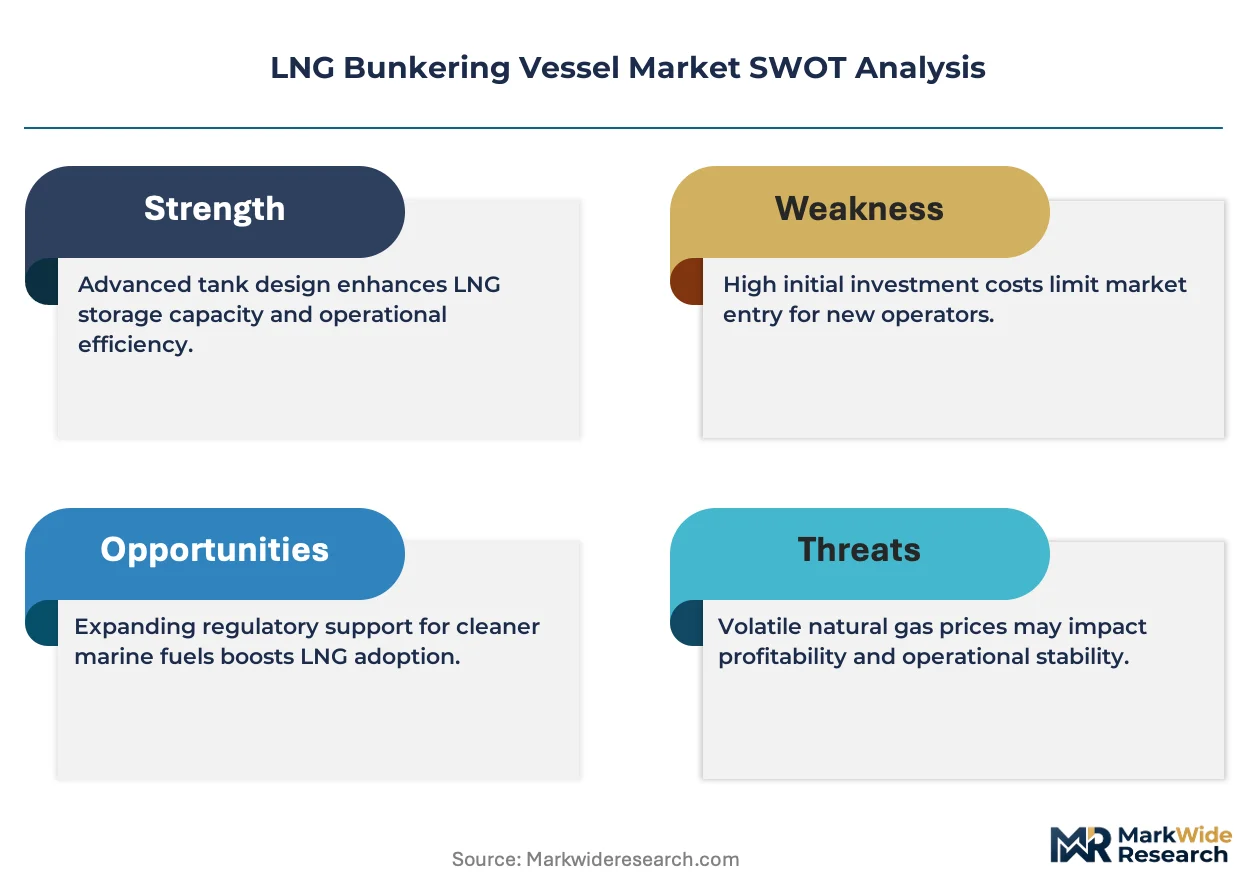
- IMO 2020 Sulphur Regulations:The International Maritime Organization's sulphur-content limits under MARPOL Annex VI compel container shipping lines to convert existing fleets and order LNG-fuelled newbuilds, generating sustained vessel demand.
- EU Green Deal Emissions Benchmarks:The European Union's tightening maritime fuel standards under the F-Gas Regulation and broader decarbonization framework accelerate bunker infrastructure deployment at Rotterdam, Marseille, and other Atlantic ports.
- Cryogenic Pumping System Advances:Insulated cargo tank technology operating below minus 162 degrees Celsius enables safer ship-to-ship transfers, expanding operational windows in congested hub environments.
Market Restraints
- Stainless Steel and Nickel Alloy Input Volatility:Cryogenic tank construction depends on specialized alloys whose price swings directly compress fabrication margins for mid-scale vessel owners.
- South Korean Yard Concentration:Newbuild slots for cryogenic cargo-handling systems cluster at Hyundai Heavy Industries and Samsung Heavy Industries, creating queue risk for non-integrated buyers.
- Channel Depth Limitations:Small-scale and medium-scale vessel categories dominate where port infrastructure cannot accommodate larger designs, fragmenting economies of scale.
Strategic Opportunities
- China Maritime Safety Administration Expansion:Coastal LNG delivery eligibility under China's port-state control inspections opens dedicated bunkering corridors at Shanghai, Shenzhen, and Ningbo-Zhoushan.
- Self-Propelled Vessel Operational Flexibility:Congested Asian hub ports favor designs eliminating tug dependence, creating differentiation for owners with integrated propulsion engineering.
- Multi-Source Chartering Models:Pooling arrangements displace single-source contracts, allowing trading houses to arbitrage spot LNG pricing against long-term vessel commitments.
Industry Challenges
- Cryogenic Systems Engineering Talent Scarcity:Specialized expertise in minus 162 degrees Celsius containment and pumping system integration concentrates at South Korean and Japanese engineering firms, constraining owner expansion.
- Flag-State Equivalency Certificate Delays:Emerging bunkering locations in Southeast Asia and the Middle East lack harmonized vessel design approvals, extending clearance timelines for new operational zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Bunkering Vessel Market |
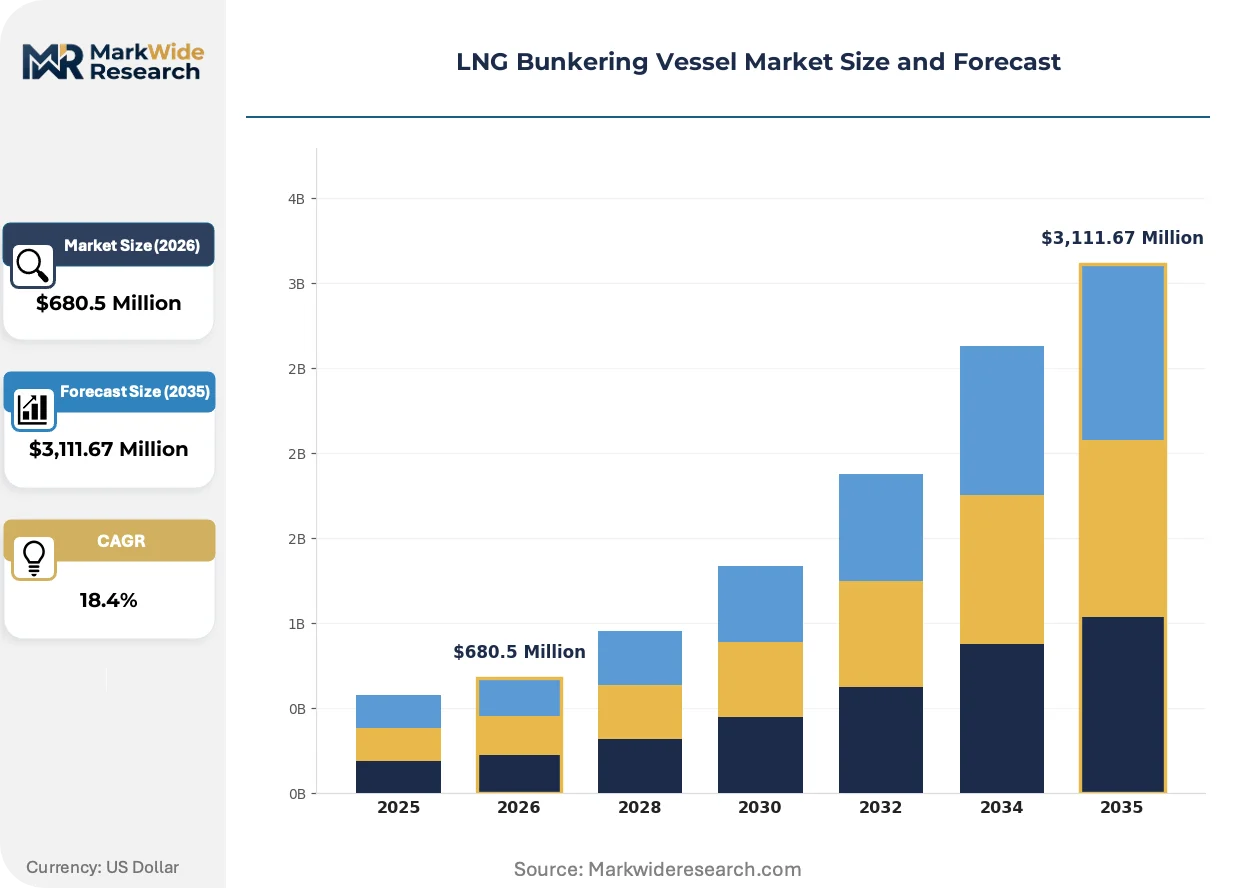
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $3,111.67 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Articulated Tug Barge, Shuttle Tanker, Self-Propelled Bunker Vessel, LNG Carrier Application: Shipping Ports, Offshore Operations, Maritime Logistics, Fleet Support Size: Small Scale, Medium Scale, Large Scale, Mega Scale Delivery Method: Pipeline Supply, Ship-to-Ship Transfer, Truck-to-Ship Transfer, Barge Delivery |
| Companies Covered | Shell PLC, TotalEnergies SE, ENGIE SA, Gasum Oy, Korea Gas Corporation, Bomin Linde LNG, Harvey Gulf International Marine, ENN Energy Holdings Limited, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Bunkering Vessel Market Trends and Innovations
Vessel design evolution and regulatory harmonization are compressing deployment timelines while procurement models fragment across integrated trading houses and independent owners.
Membrane tank technology is integrating Type C independent pressure vessel designs into medium-scale bunker vessels, replacing traditional prismatic configurations. European operators at Rotterdam and Marseille adopt these systems to reduce boil-off rates during extended port stays. The technology is integrating operational flexibility that allows simultaneous cargo and bunker operations, compressing turnaround times at multi-use terminals.
The EU F-Gas Regulation and MARPOL Annex VI amendments tighten methane slip monitoring requirements for dual-fuel engines. Shipyards must now certify cryogenic fuel systems under combined pressure-vessel and emissions protocols, extending design validation cycles. Container shipping lines operating Atlantic basin routes face the steepest compliance ramps, accelerating dedicated bunker vessel deployments at hub ports to ensure fuel availability.
Charter contracting now fragments between long-term integrated trading arrangements and spot-market pooling. Shell PLC and TotalEnergies SE anchor opposite models—direct Asian yard relationships versus dedicated regional vessel fleets—forcing mid-scale owners to select alignment strategies. This bifurcation concentrates most visibly in the Singapore-Jakarta corridor, where fuel demand density supports both contract structures simultaneously.
LNG Bunkering Vessel Market Segmentation
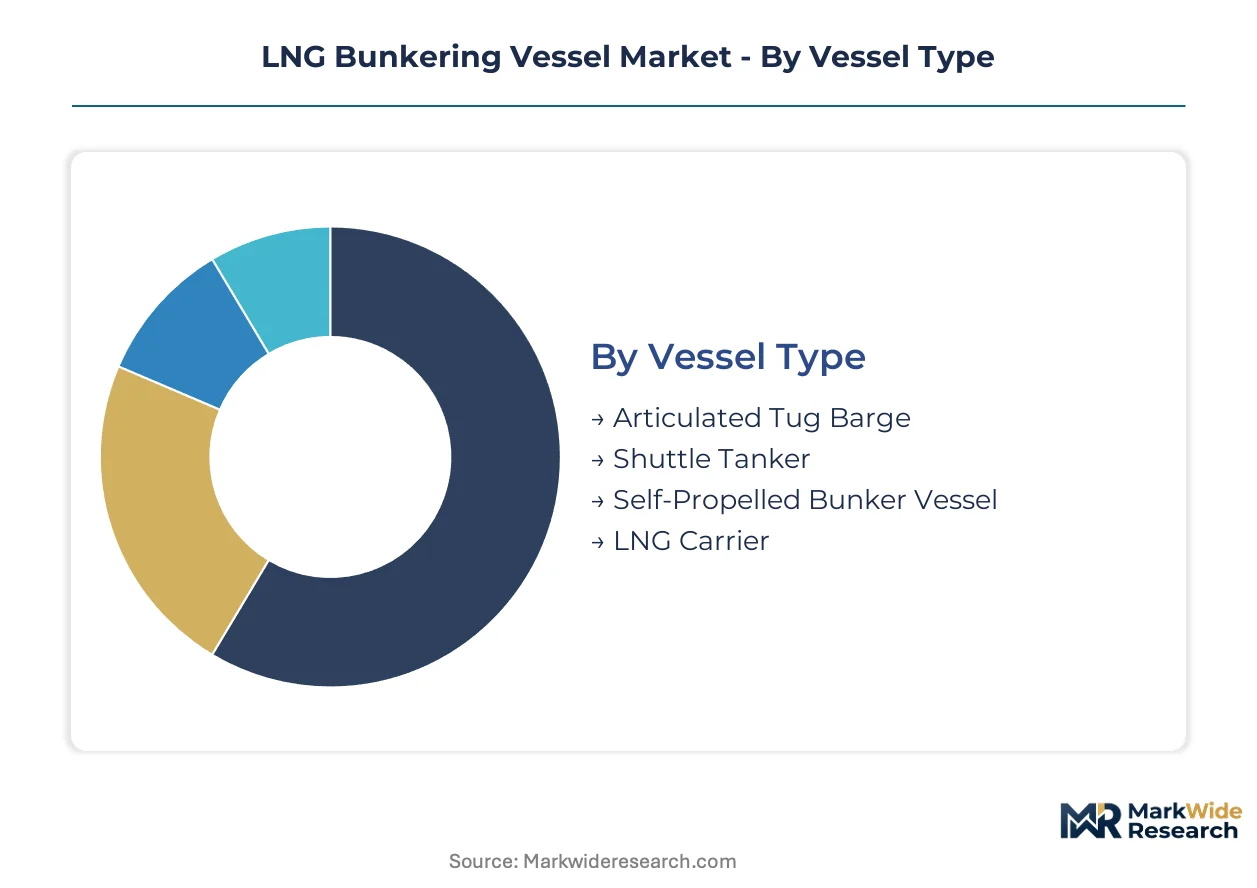
Procurement patterns in LNG bunkering diverge sharply by operational environment and cargo-handling architecture. Vessel specifications determine charter rates, yard queue priority, and regulatory compliance pathways across hub ports and offshore corridors.
Vessel Type:
Propulsion configuration and cargo containment technology define operational envelopes and capital intensity tiers.
- Self-Propelled Bunker Vessel:Integrated diesel-electric or dual-fuel propulsion eliminates tug dependence in congested Asian hub ports. Hyundai Heavy Industries and Samsung Heavy Industries concentrate orderbook slots for cryogenic cargo-handling systems on this hull form, creating queue premiums for non-integrated buyers.
- Articulated Tug Barge:A coupled ATB system pairs a dedicated tug with a non-propelled barge carrying Type C independent pressure vessels. Lower capital outlays attract mid-scale owners targeting secondary ports where channel depths restrict larger designs.
- Shuttle Tanker:Adapted hulls from offshore oil service fleets repurpose dynamic positioning systems for LNG transfer operations.
- LNG Carrier:Full-size carriers occasionally divert to bunkering duty at mega-scale hub ports with dedicated jetties.
Self-propelled designs lead on scale; articulated tug barge configurations lead on momentum in emerging Southeast Asian corridors.
Application:
End-use concentration shapes deployment density and fuel specification requirements.
- Shipping Ports:Dedicated bunker operations at Rotterdam, Singapore, and Shanghai require vessels certified for simultaneous cargo and fuel transfers. Membrane tank technology with Type C independent pressure vessel integration reduces boil-off rates during extended port stays, compressing turnaround times at multi-use terminals.
- Offshore Operations:Dynamic positioning and weather-restricted transfer protocols dominate specification sheets for supply vessels serving drilling rigs and FPSO units. Harsh environment class notations from classification societies extend design validation cycles.
- Maritime Logistics:Tramp trade and short-sea shipping routes demand flexible scheduling and rapid mobilization between ports.
- Fleet Support:Container shipping lines with committed LNG-fuelled tonnage anchor long-term charter contracts for dedicated vessel pools.
Shipping ports anchor current deployment volumes; offshore operations are expanding most quickly under North Sea and Gulf of Mexico production schedules.
Size:
Channel depth constraints and cargo economics fragment optimal hull dimensions across geographies.
- Small Scale:Vessels under 5,000 cubic meters navigate restricted waterways at secondary Japanese and Mediterranean ports. Shallow draft requirements limit cargo tank configuration options to prismatic or small-diameter Type C pressure vessels.
- Medium Scale:The 10,000-20,000 cubic meter bracket balances economies of scale with port accessibility across the Singapore-Jakarta corridor. European operators at Rotterdam and Marseille favor this envelope for membrane tank technology adoption.
- Large Scale:Hub-to-hub shuttle operations between major LNG terminals exploit full cargo containment volumes.
- Mega Scale:Converted carriers and purpose-built units serve only the largest integrated bunkering hubs with dedicated infrastructure.
Medium scale dominates orderbook value; small scale gains share fastest in archipelagic Southeast Asian markets.
Delivery Method:
Transfer interface technology determines vessel design certification and operational clearance protocols.
- Ship-to-Ship Transfer:Cryogenic hose and manifold systems operating at minus 162 degrees Celsius require specialized crew certification under MARPOL Annex VI amendments. This method leads adoption as terminal infrastructure matures at Rotterdam, Singapore, and Shanghai.
- Truck-to-Ship Transfer:Mobile LNG supply chains serve vessels at anchor or alongside without dedicated bunker vessel presence. Limited cargo volumes restrict application to short-sea ferries and coastal feeders.
- Pipeline Supply:Fixed berth connections at major LNG export terminals enable highest-volume transfers.
- Barge Delivery:Non-propelled units towed to point of demand serve intermittent demand pockets.
Ship-to-ship transfer leads on scale; truck-to-ship transfer leads on momentum in fragmented coastal markets lacking dedicated vessel infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing LNG bunkering vessel deployment toward jurisdictions with streamlined port-state control and harmonized emissions protocols. South Korean yards exploit this compliance-cost gap by concentrating cryogenic system production for buyers seeking faster certification cycles.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global cryogenic cargo-handling system fabrication, commanding queue premiums for newbuild slots. The Korea Maritime Safety Administration enforces stringent containment standards under domestic implementing rules for MARPOL Annex VI. Ulsan and Geoje industrial clusters concentrate membrane tank engineering talent and nickel-alloy welding capacity for export markets.
Singapore
The Maritime and Port Authority of Singapore licenses bunkering operators under a dedicated regulatory framework that accelerates vessel deployment timelines. Port infrastructure investments at Jurong Island and Tuas support simultaneous cargo and fuel transfer operations. The Singapore-Jakarta corridor attracts medium-scale self-propelled vessel orders from trading houses arbitraging spot LNG pricing.
Netherlands
Rotterdam's status as Europe's largest bunkering hub drives dedicated vessel deployments under EU F-Gas Regulation methane-slip monitoring requirements. The Human Environment and Transport Inspectorate coordinates with classification societies on cryogenic system certification. The Port of Rotterdam Authority mandates shore-power compatibility for new bunker vessel charters, filtering design specifications.
China
The Maritime Safety Administration administers coastal LNG delivery eligibility through port-state control inspections at Shanghai, Shenzhen, and Ningbo-Zhoushan. China's dual carbon goals accelerate domestic newbuild programs for medium-scale vessels serving Yangtze River Delta container terminals. Jiangsu and Zhejiang province shipyards compete for cryogenic tank fabrication contracts previously concentrated in South Korea.
United States
The US Coast Guard's liquefied gas carrier regulations govern bunker vessel eligibility for coastal and inland waterway operations. Harvey Gulf International Marine anchors Gulf of Mexico deployment through dedicated offshore supply vessel conversions. Texas and Louisiana port authorities develop LNG bunkering infrastructure to capture container shipping line traffic from expanded Panama Canal routes.
LNG Bunkering Vessel Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated trading-house partnerships and regional pooling arrangements. Market structure consolidates around three archetypes: integrated oil majors with captive vessel fleets, national gas utilities controlling domestic newbuild slots, and independent marine operators specializing in hub-port deployment. Competitive positioning depends on yard queue access and long-term charter contract tenure. Dominant moves include backward integration into cryogenic system engineering and geographic expansion through dedicated regional vessel pools.
Among integrated oil majors, Shell PLC and TotalEnergies SE exemplify divergent strategic archetypes—direct Asian yard relationships versus Atlantic basin dedicated fleet deployment. Korea Gas Corporation occupies a position within the national utility tier, leveraging domestic newbuild slot control to extend engineering partnerships. These three entities represent the competitive spectrum: trading-house integration, regional hub anchoring, and state-backed capacity coordination.
| Leading Market Players |
|---|
| Shell PLC |
| TotalEnergies SE |
| ENGIE SA |
| Gasum Oy |
| Korea Gas Corporation |
| Bomin Linde LNG |
| Harvey Gulf International Marine |
| ENN Energy Holdings Limited |
| Chevron Corporation |
| Others |
Pricing and Supply Chain Analysis
Specialized nickel-alloy welders concentrated in South Korea's Ulsan-Geoje industrial corridor command wage premiums that compress fabrication margins for mid-scale vessel owners while widening spreads between premium integrated contracts and economy-tier spot charters. Labor-cost differentials between Korean yard clusters and emerging Chinese competitors at Jiangsu and Zhejiang provinces are forcing charter rate stratification that rewards early slot commitments.
Pricing Analysis
Direct-to-OEM charter contracting eliminates intermediary margin layers for integrated trading houses like Shell PLC and TotalEnergies SE, while independent owners absorb distributor markups through shipbroker networks. Pricing stratifies across premium, standard, and economy tiers based on cryogenic system certification grade and charter contract duration. Cost compression in the standard tier is intensifying because stainless steel and nickel alloy input volatility directly transfers to fabrication quotes. Container shipping lines with committed LNG-fuelled tonnage exhibit lowest price sensitivity; tramp trade operators in fragmented Southeast Asian corridors face acute margin pressure.
Supply Chain Analysis
Classification society certification for minus 162 degrees Celsius containment systems gates entry to South Korean, Japanese, and select European engineering firms with established membrane tank validation protocols. Cryogenic cargo-handling system fabrication draws from specialized nickel alloy feedstock, high-vacuum insulation panel production, and precision cryogenic pump manufacturing concentrated in South Korea and Japan. Single-source vulnerability concentrates at Hyundai Heavy Industries and Samsung Heavy Industries for newbuild slots with integrated cargo systems. Distribution runs through integrated trading house charter desks, independent vessel pools, and national gas utility direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LNG bunkering vessel market functions as a regulatory compounder where MARPOL Annex VI sulphur enforcement generates inelastic demand for compliant fuel infrastructure regardless of spot LNG price volatility.
For Market Incumbents: Deploy backward integration into cryogenic system engineering to capture margin pools currently flowing to South Korean yard subcontractors. Shell PLC and TotalEnergies SE should lock multi-year charter extensions with Asian shipyards before queue premiums escalate further. The emerging threat of Chinese yard competition at Jiangsu and Zhejiang provinces demands accelerated certification investment to maintain technical differentiation. For New Entrants and Emerging Players: EU F-Gas Regulation in the Netherlands opens a window for medium-scale self-propelled vessel deployment at Rotterdam under methane-slip monitoring compliance. The Singapore-Jakarta corridor presents the most penetrable geography where fuel demand density supports spot-market pooling models against integrated trading house contracts. A go-to-market angle anchored in articulated tug barge configurations for secondary Southeast Asian ports bypasses queue competition at Korean yards. For Investors and Strategic Acquirers: Valuations sit cheapest among independent marine operators with hub-port deployment expertise but lacking integrated trading house charter backing. Long-term viability hinges on vessel pool scale sufficient to arbitrage spot LNG pricing against long-term commitments. The signal to watch is Maritime Safety Administration coastal delivery eligibility expansion at Shanghai, Shenzhen, and Ningbo-Zhoushan as inflection indicator for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Engineering | Captures margin pools from South Korean yard subcontractors and reduces queue dependence. |
| Multi-Source Charter Pooling Arrangement | Enables trading houses to arbitrage spot LNG pricing against long-term vessel commitments. |
| Membrane Tank Technology Certification | Reduces boil-off rates at Rotterdam and Marseille under EU F-Gas Regulation compliance. |
| Articulated Tug Barge Fleet Deployment | Targets secondary Southeast Asian ports where channel depths restrict larger self-propelled designs. |
| China Maritime Safety Administration Alignment | Secures coastal LNG delivery eligibility at Shanghai, Shenzhen, and Ningbo-Zhoushan corridors. |
Research Methodology
Bottom-up vessel deployment modeling reconciled against top-down cryogenic system production tracking forms the analytical core of this study. Primary interviews with shipyard procurement directors, LNG trading house chartering managers, classification society surveyors, and port authority infrastructure planners combined with secondary validation from Lloyd's Register vessel databases, IMO MARPOL implementation circulars, and EU F-Gas Regulation compliance filings. Triangulation across stakeholder inputs and trade data ensures segmentation integrity across vessel type, application, size, and delivery method dimensions.
Input-output matrices map newbuild slot allocation at Hyundai Heavy Industries and Samsung Heavy Industries against charter contract tenures held by integrated oil majors and national gas utilities. Segmentation modeling spans propulsion configuration, cargo containment technology, operational environment, and regional regulatory cluster across the projection horizon. CAGRs derive from vessel orderbook analysis reconciled against container shipping line LNG-fuelled newbuild commitments and port infrastructure investment pipelines at Rotterdam, Singapore, and Shanghai.
Forecast precision tightens around the base case; tail outcomes carry wider variance under flag-state equivalency certificate delays at emerging Southeast Asian bunkering locations. Model outputs reflect assumptions on MARPOL Annex VI enforcement trajectory and stainless steel alloy price stability. A model refresh is warranted upon material change in China Maritime Safety Administration coastal delivery eligibility rulings or South Korean yard queue dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
North America Naval Vessels Market
Marine
Marine Strip Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Global Discount-Marine Trenchers Market
Marine
Sliding Fender Market
Marine
Marine Chronometers Market
Marine
Deep-V Boat Market
Marine
Sailboat Propellers Market
Marine
Azimuth Thrusters Market
Marine
Buoys and Beacon Market
Marine
Hybrid Fishing Boats Market
Marine
Sea Skimmer Market
Marine
Marine Winch Motors Market
Marine
Integrated Bridge System for Ships Market
Marine
Marine Exhaust Systems Market
Marine
Offshore AUV and ROV Market