
 Recreational Vessel Battery Market | 2026-2036
Recreational Vessel Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Vessel Battery Market Analytics
Modular battery pack configurations is broadening buyer choice across recreational vessel segments. Clarios leverages its automotive-scale manufacturing footprint to supply standardized lithium-ion modules that reduce installation complexity for boat builders. Corvus Energy anchors the high-capacity segment with marine-specific architectures that sustain thermal performance in salt-air environments. Saft Batteries competes through nickel-cobalt-aluminum formulations that dominate extended-range sailing applications.
Recreational vessel batteries are electrochemical energy storage systems engineered for cyclic deep-discharge operation in marine environments, typically featuring IP67 sealing, vibration-resistant terminal designs, and operating voltage ranges from 12V to 800V depending on propulsion architecture. Their primary purpose is to supply sustained power for electric or hybrid propulsion, house loads, and navigation electronics aboard leisure craft. Lithium-ion chemistry commands the premium tier due to energy density advantages and declining cell costs, while AGM retains substantial share in retrofit installations where charging infrastructure remains limited. Sailboats represent a concentrated demand pocket where weight reduction directly impacts performance, drawing higher-margin product configurations than motorboat segments where space constraints are less severe.
The EU Green Deal and F-Gas Regulation are tightening marine emissions standards and compelling OEMs to certify electric propulsion systems for inland and coastal waterways. The US Coast Guard and ABYC standards govern battery compartment ventilation and thermal runaway containment, shaping product design requirements for North American suppliers. Stakeholders must monitor how IEC 62619 certification timelines and evolving marina charging standards interact to determine which chemistry-platform combinations achieve scalable deployment.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing diesel propulsion timelines across Mediterranean charter fleets, forcing rapid lithium chemistry transitions before 2030 compliance deadlines.
Growth Catalysts
- Marina electrification infrastructure:French and Italian port authorities are installing high-amperage shore power systems that enable overnight charging for electric yachts, eliminating range anxiety for coastal cruising routes.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases used in marine HVAC and refrigeration systems are pushing OEMs toward all-electric auxiliary systems that require larger battery banks.
- Sailboat weight-performance sensitivity:Competitive racing circuits and bluewater cruising segments prioritize lithium-ion packs that reduce ballast displacement and improve hull speed metrics.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings from South American brine operations compress margin predictability for pack assemblers serving mid-tier boat builders.
- Cell supply concentration:Cylindrical format production clusters in East Asian manufacturing hubs create single-source vulnerability for European marine system integrators.
- Thermal runaway containment standards:ABYC E-13 battery compartment requirements mandate expensive fire suppression and ventilation engineering that extends certification timelines.
Strategic Opportunities
- Retrofit aftermarket penetration:Aging AGM installations in coastal US and Australian trailerable boat fleets present conversion revenue as charging infrastructure spreads beyond premium marinas.
- Second-life automotive cell reuse:Repurposed electric vehicle battery modules from passenger car retirement streams offer cost-competitive entry points for house load applications in liveaboard sailboats.
- EU Green Deal vessel modernization subsidies:Member state decarbonization funds covering 30-40% of electric repower costs are accelerating procurement decisions among commercial charter operators.
Industry Challenges
- IEC 62619 certification bottlenecks:Marine-specific lithium safety testing queue times at notified bodies extend product launch windows by 8-14 months.
- Marine electrical technician scarcity:Specialized training for high-voltage DC system installation and diagnostics lags behind fleet electrification pace in Nordic and Baltic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Vessel Battery Market |
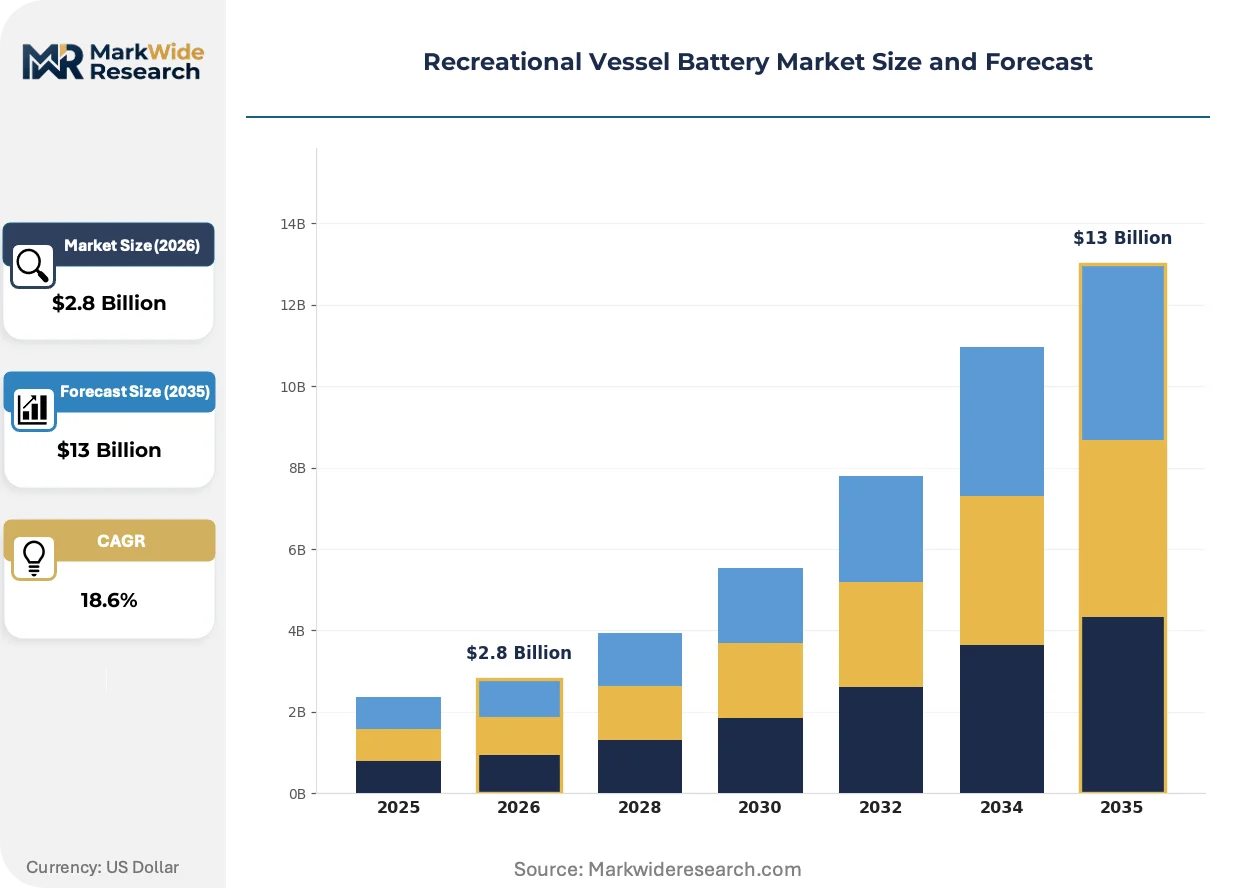
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, AGM, Gel, Lead Acid Application: Sailboats, Motorboats, Personal Watercraft, Yachts End User: Recreational Boaters, Commercial Operators, Marine Enthusiasts, Fleet Managers Capacity: 100Ah, 200Ah, 300Ah, 400Ah |
| Companies Covered | Clarios, Saft Batteries, Corvus Energy, Echandia, Akasol AG, EST-Floattech, Craftsman Marine, Exide Technologies, Victron Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Vessel Battery Market Evolving Landscape
Electrification is fragmenting traditional propulsion supply chains as battery pack architecture becomes the central design variable for new hull development programs.
Lithium iron phosphate chemistry is consolidating dominance in recreational marine applications due to thermal stability advantages in enclosed engine compartments. Production yacht builders in the 40-60 foot segment are specifying LFP as standard equipment to simplify insurance underwriting and reduce battery management system complexity. This chemistry choice is consolidating supplier relationships around cell manufacturers with marine-certified form factors, compressing the vendor landscape for nickel-cobalt-aluminum alternatives.
The EU Green Deal's vessel emissions standards are mandating zero-emission operation in designated inland waterways and coastal zones by 2030. Marine OEMs must certify electric propulsion systems under harmonized technical specifications to access these regulated corridors. French canal networks and Dutch inland shipping routes are experiencing the earliest enforcement, driving demand for modular battery configurations that enable range extension through hot-swappable packs.
Buyer preference is rotating toward integrated energy system procurement where propulsion, house loads, and solar generation are specified as unified architectures. Independent boat builders and custom yards are displacing component-by-component sourcing in favor of turnkey marine energy partnerships with battery system houses. This bundling behavior concentrates most visibly in Scandinavian cruising yacht segments where off-grid autonomy ranks as a primary purchase criterion.
Recreational Vessel Battery Market Segmentation
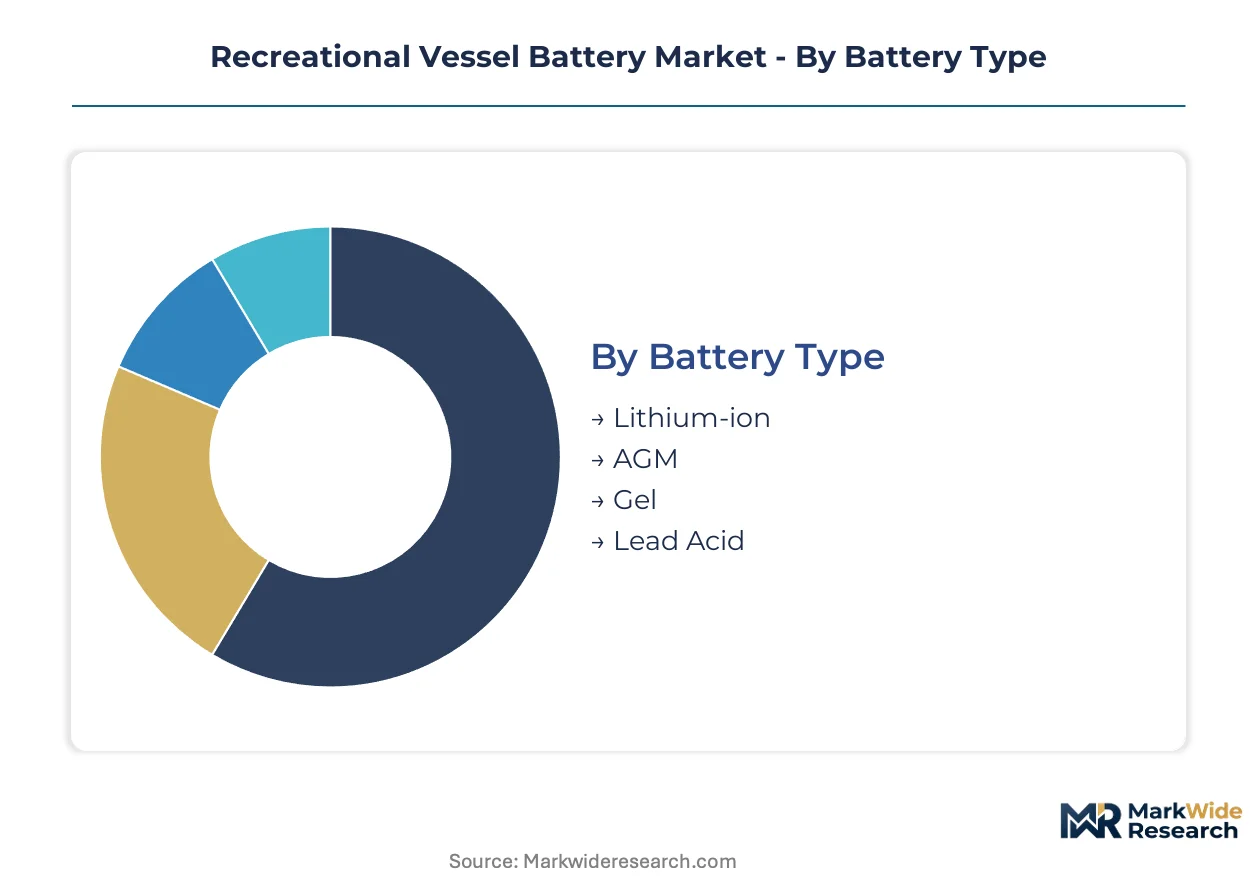
Battery procurement patterns diverge sharply across vessel architectures and operator profiles, with chemistry selection and capacity sizing tightly coupled to hull design constraints and electrification roadmaps. Understanding these segment boundaries enables suppliers to align thermal management specifications and certification investments with actual deployment environments.
Battery Type:
Standardization pressures dominate at the cell level while pack-level customization proliferates to accommodate varying hull geometries and ventilation constraints.
- Lithium-ion:Lithium iron phosphate formulations deliver thermal stability in enclosed engine compartments, with nickel-cobalt-aluminum variants reserved for extended-range sailing applications where energy density outweighs cost sensitivity. Demand concentrates in Mediterranean charter fleets facing EU Green Deal compliance deadlines for zero-emission operation.
- AGM:Absorbed glass mat construction tolerates partial state-of-charge cycling common in trailerable boats with limited shore power access. Retrofit demand persists in US coastal markets where charging infrastructure lags behind premium marina networks.
- Gel:Electrolyte immobilization suits deep-discharge house load applications in liveaboard sailboats requiring maintenance-free operation during extended anchoring.
- Lead Acid:Flooded and sealed variants retain cost-driven niches in entry-level personal watercraft and legacy fleet replacements where weight and cycle life tradeoffs are acceptable.
Leading the category by volume: AGM. Growing fastest: Lithium-ion.
Application:
Propulsion architecture dictates voltage tier and thermal management requirements, fragmenting supplier relationships across hull categories.
- Sailboats:Weight-performance sensitivity drives lithium-ion penetration in racing circuits and bluewater cruising segments, where ballast displacement reductions directly improve hull speed metrics. French and Italian riviera marinas with electrified infrastructure anchor premium demand.
- Motorboats:Space constraints are less severe than sailing counterparts, enabling larger AGM configurations in recreational cruising segments where installation cost dominates specification decisions.
- Personal Watercraft:Compact form factors and splash-resistant sealing requirements favor sealed lead-acid and small-format lithium packs in jet ski and tender applications.
- Yachts:Integrated energy system procurement bundles propulsion, house loads, and solar generation into unified architectures, concentrating purchasing power with turnkey marine energy partners in Scandinavian cruising segments.
Highest margin concentration: Sailboats. Steepest expansion trajectory: Yachts.
End User:
Procurement sophistication varies across operator sophistication, from component-by-component sourcing to integrated fleet electrification programs.
- Recreational Boaters:Individual owners prioritize upfront cost and warranty terms, with lithium conversion decisions contingent on local marina charging availability.
- Commercial Operators:Charter fleets in Dutch inland shipping routes and French canal networks drive modular battery demand for hot-swappable range extension under regulatory compliance timelines.
- Marine Enthusiasts:Racing circuit participants and technical liveaboard communities specify high-performance lithium configurations with advanced battery management systems for off-grid autonomy.
- Fleet Managers:Centralized procurement for rental and tour operations leverages volume scale to negotiate cell supply agreements directly with East Asian cylindrical format manufacturers.
Dominant volume share: Recreational Boaters. Accelerating procurement sophistication: Commercial Operators.
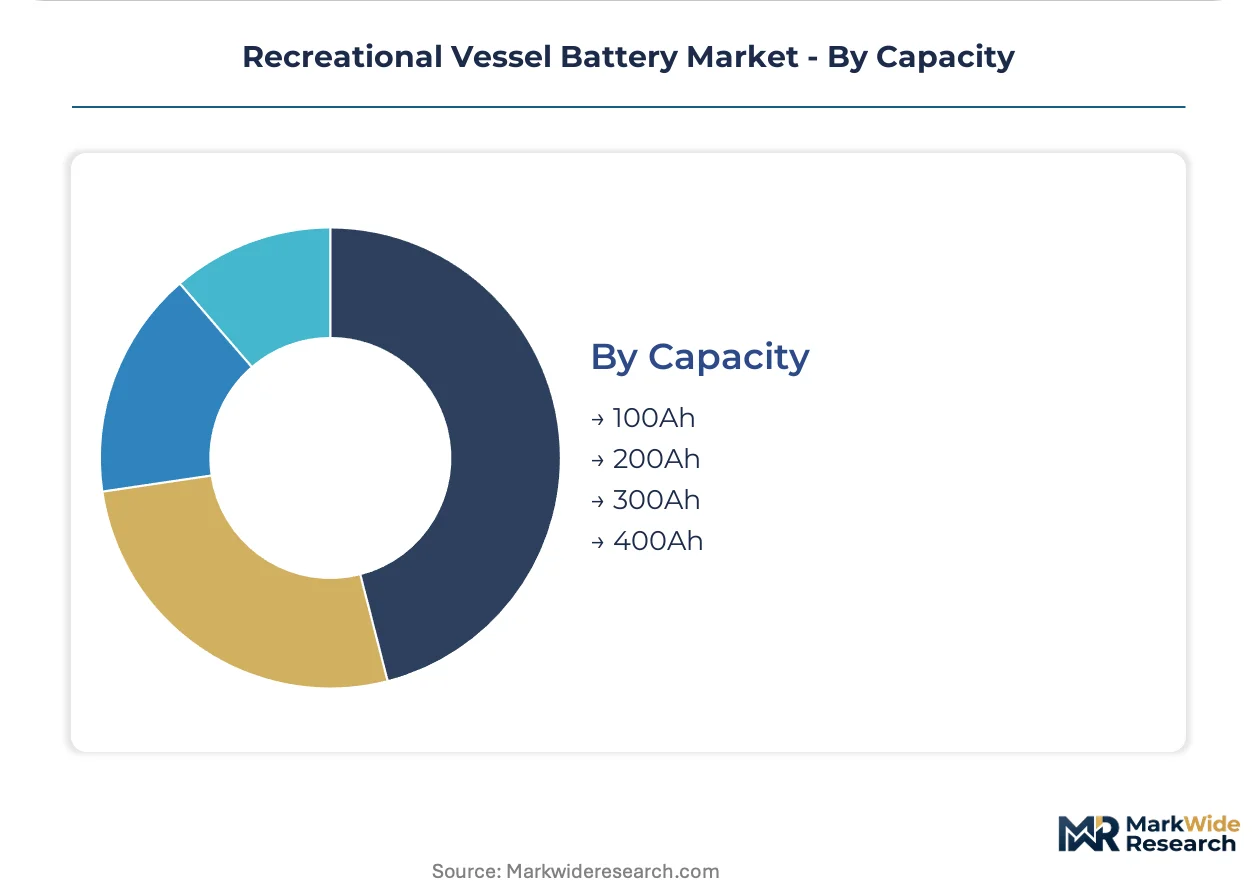
Capacity:
Energy storage scaling follows a nonlinear path where 100Ah increments unlock distinct use case categories rather than linear range extension.
- 100Ah:Standard house load foundation for trailerable boats and day cruisers, frequently deployed in parallel configurations to achieve target system voltage without complex series balancing.
- 200Ah:Coastal cruising threshold enabling overnight anchoring with refrigeration and navigation electronics, the entry point for lithium iron phosphate standardization in production yacht builder programs.
- 300Ah:Extended autonomy segment for liveaboard sailboats and electric auxiliary propulsion in inland waterways, where EU Green Deal subsidies cover substantial repower costs.
- 400Ah:High-capacity tier for hybrid propulsion architectures and all-electric yacht specifications, requiring marine-specific thermal management and ABYC E-13 compartment certification.
Installed base concentration: 100Ah and 200Ah. Gaining share fastest: 300Ah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in East Asian cell production hubs while consumption gravitates toward Mediterranean marina networks and Nordic electrification corridors. Battery pack assembly follows vessel builder proximity to reduce logistics complexity for high-weight components.
United States
Coastal trailerable boat fleets drive AGM retrofit demand from Florida to the Pacific Northwest as marina electrification spreads beyond premium destinations. ABYC E-13 standards govern battery compartment ventilation and thermal runaway containment for domestic suppliers. The Chesapeake Bay and Great Lakes sailing communities anchor lithium conversion activity where shore power infrastructure enables overnight charging.
France
Canal networks and Riviera charter fleets compress diesel propulsion timelines under EU Green Deal enforcement. ANSM maritime safety protocols intersect with F-Gas Regulation phase-down requirements for vessel HVAC systems. Marseille and Nice port authorities are installing high-amperage shore power to service electric yacht demand from Italian and Spanish cruising routes.
Italy
Production yacht builders in the 40-60 foot segment specify lithium iron phosphate as standard equipment to simplify insurance underwriting. ECHA chemical safety registrations shape cell import documentation for Adriatic and Tyrrhenian boat builders. The Ligurian coast and Venetian lagoon anchor premium demand where electrified marina infrastructure enables coastal cruising without range anxiety.
Germany
Inland shipping routes through the Rhine-Main-Danube corridor drive modular battery demand for hot-swappable range extension. KBA vessel certification requirements align with EU harmonized technical specifications for zero-emission operation. Bavarian and Baden-Württemberg custom yards are displacing component sourcing in favor of turnkey marine energy partnerships.
Australia
Trailerable boat fleets across Queensland and New South Wales present conversion revenue as charging infrastructure extends beyond Sydney Harbour. The country's national maritime safety regulator governs lithium installation standards for coastal cruising vessels. Perth and Melbourne sailing clubs anchor technical liveaboard communities specifying high-performance configurations for off-grid autonomy.
Recreational Vessel Battery Market Competitive Landscape
The competitive structure tilts toward automotive-scale manufacturers repurposing cell formats for marine applications. Pack-level specialists compete on thermal management architecture and salt-air corrosion resistance. Two strategic archetypes dominate: standardized module suppliers leveraging passenger car production volumes, and marine-native system houses engineering vessel-specific integration. Capacity expansion and strategic partnerships represent the dominant competitive moves as certification timelines compress procurement windows.
Among automotive-heritage suppliers, Clarios and Exide Technologies occupy positions as volume-driven module providers. Marine-specialist archetypes exemplified by Corvus Energy and Saft Batteries anchor the high-capacity and extended-range segments respectively. Akasol AG sits within the European system integration tier serving production yacht builder programs. Echandia and EST-Floattech represent Nordic engineering houses bundling propulsion, house loads, and solar generation into unified architectures.
| Leading Market Players |
|---|
| Clarios |
| Saft Batteries |
| Corvus Energy |
| Echandia |
| Akasol AG |
| EST-Floattech |
| Craftsman Marine |
| Exide Technologies |
| Victron Energy |
| Others |
Value Network & Pricing Analysis
Captive cell production in East Asian manufacturing hubs anchors both supply security and pricing leverage for marine battery assemblers, compressing margin flexibility for European pack integrators dependent on cylindrical format imports. This integration pattern concentrates cost control with automotive-scale producers while forcing marine specialists to compete on thermal management engineering rather than cell economics.
Pricing Analysis
Margin tightening in the mid-tier production yacht segment reflects lithium carbonate volatility from South American brine operations and IEC 62619 certification queue delays. Three-tier pricing structure across premium, standard, and economy levels separates marine-native system houses with ABYC E-13 compliance from automotive-heritage module suppliers and AGM retrofit providers. Cost-down pressure on standard lithium iron phosphate packs accelerates because French and Italian charter fleets face EU Green Deal compliance deadlines. Commercial operators exhibit lowest price sensitivity due to subsidy coverage, while individual recreational boaters in US coastal markets remain most cost-conscious.
Supply Chain Analysis
Lithium carbonate and nickel-cobalt-aluminum cathode precursors rest on South American mining operations and East Asian refining capacity, with cylindrical cell production clustering in China, South Korea, and Japan. Marine-specific battery management systems and thermal runaway containment hardware draw from German and Nordic engineering houses. Single-source vulnerability concentrates in East Asian cell format supply, exposing European system integrators to logistics chokepoints through Red Sea routing. Distribution runs through vessel builder proximity networks, with pack assembly co-locating to French, Italian, and German production yacht facilities to reduce high-weight component transport costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around marine-certified thermal management capabilities, with IEC 62619 certification timelines forcing weaker pack assemblers into acquisition or exit.
For Market Incumbents: Acquire marine-specific battery management system engineering teams to deepen thermal runaway containment expertise before ABYC E-13 standards tighten further. Secure captive cell supply agreements with East Asian cylindrical format producers to defend against lithium carbonate price swings compressing pack assembler margins. Vertical integration into salt-air corrosion-resistant enclosure manufacturing reduces dependency on third-party marine hardware suppliers. For New Entrants and Emerging Players: Launch via second-life automotive cell repurposing for liveaboard sailboat house load applications, targeting the US Chesapeake Bay and Australian trailerable boat retrofit segments where charging infrastructure lags behind premium marinas. Target modular hot-swappable configurations for Dutch inland shipping routes and French canal networks under EU Green Deal vessel modernization subsidies. Bundle solar generation and propulsion control into turnkey marine energy partnerships to displace component-by-component sourcing in Scandinavian custom yards. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive-scale battery manufacturers seeking marine market entry through thermal management capability. Long-term viability favors marine-native system houses with IEC 62619 certification traction and Scandinavian turnkey energy partnerships over pure cell traders. Watch IEC 62619 notified body capacity expansion as the inflection signal for certification timeline compression enabling faster product launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Marine-Specific Thermal Management Acquisition | ABYC E-13 compliance expertise differentiates pack assemblers from automotive module suppliers entering marine segments. |
| Second-Life Automotive Cell Repurposing Program | Retired passenger car battery streams offer cost-competitive entry points for house load applications in liveaboard sailboats. |
| Turnkey Marine Energy Partnership Formation | Unified propulsion, house load, and solar architectures concentrate purchasing power with Scandinavian cruising yacht builders. |
| East Asian Cell Supply Agreement Negotiation | Cylindrical format production commitments secure input cost predictability against South American lithium carbonate volatility. |
| EU Green Deal Subsidy Access Structuring | French and Dutch member state decarbonization funds covering substantial electric repower costs accelerate charter fleet procurement decisions. |
Research Methodology
Independent corroboration across marine battery system integrators, production yacht builder procurement leads, and marina infrastructure operators underwrites the qualitative findings. Primary interviews with thermal management engineers, ABYC certification specialists, and EU maritime safety regulators combined with secondary validation from IEC technical committee documentation, ECHA chemical safety registrations, and French ANSM maritime protocols. Customs data on lithium cell imports, vessel production statistics from Italian and German builder associations, and marina electrification investment disclosures from French and Italian port authorities enabled bottom-up and top-down triangulation.
Rate-of-change decomposition across battery chemistry transitions, propulsion architecture shifts, and regulatory compliance timelines structured the analytical framework. Segmentation dimensions modeled include vessel architecture, operator profile, capacity tier, and regional marina infrastructure maturity. CAGRs were derived from installed base replacement cycles, fleet electrification roadmaps, and subsidy program uptake curves. Forecast inputs incorporated EU F-Gas Regulation phase-down enforcement schedules and lithium iron phosphate chemistry adoption curves in the 40-60 foot production yacht segment.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for lithium-ion dominance in extended-range sailing applications. Forecasts reflect assumptions on IEC 62619 certification queue resolution, marina charging infrastructure deployment pace, and lithium carbonate supply stabilization from South American brine expansion. A small set of triggers—thermal runaway containment standard revisions, East Asian cell export restrictions, and EU Green Deal subsidy program extensions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Strip Market
Marine
Marine Turbocharger Market
Marine
Pneumatic Marine Fender Market
Marine
Marine Fin Stabilizer Market
Marine
Boat Steering Systems Market
Marine
Marine Filter Market
Marine
Ship Rudders Market
Marine
Marine and Marine Management Software Market
Marine
Hydrofoil Market
Marine
Europe Recreational Boating Market
Marine
Marine Stabilizers Market
Marine
Marine Electronics Market
Marine
Boat Trolling Motor Market
Marine
Hybrid Fishing Boats Market
Marine
Hydrogen Ships Market
Marine
Marine Shackle Market