
 India Passenger Vehicles Lubricants Market | 2026-2036
India Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
India Passenger Vehicles Lubricants Market Foresight
Maharashtra is reconfiguring lubricant distribution networks through its Mumbai-Pune industrial corridor and Nagpur logistics hub. Indian Oil Corporation Limited leverages its Koyali and Panipat refinery complexes to sustain pan-India feedstock security for passenger vehicle lubricants. Bharat Petroleum Corporation Limited anchors western India through its Mumbai refinery output and proprietary MAK lubricant brand. Gulf Oil International competes on two-wheeler and passenger car motor oil specialization through its Chennai blending facility and franchise service station partnerships.
India passenger vehicles lubricants comprise refined base oils blended with additive packages to manage engine friction, thermal stability, and exhaust after-treatment compatibility in gasoline and diesel powertrains. These formulations typically incorporate Group II or Group III base stocks with detergents, dispersants, anti-wear agents, and viscosity index improvers to meet SAE J300 and API SP/ILSAC GF-6 performance thresholds. Synthetic oil commands expanding share as turbocharged direct-injection engines proliferate and drain intervals extend under OEM service protocols. Viscosity grade 5W-30 dominates volume throughput owing to its cold-start protection and fuel economy credentials across compact and mid-size passenger vehicles. Distribution through auto parts stores and service stations retains structural importance for brand trust and technical specification verification at point of sale.
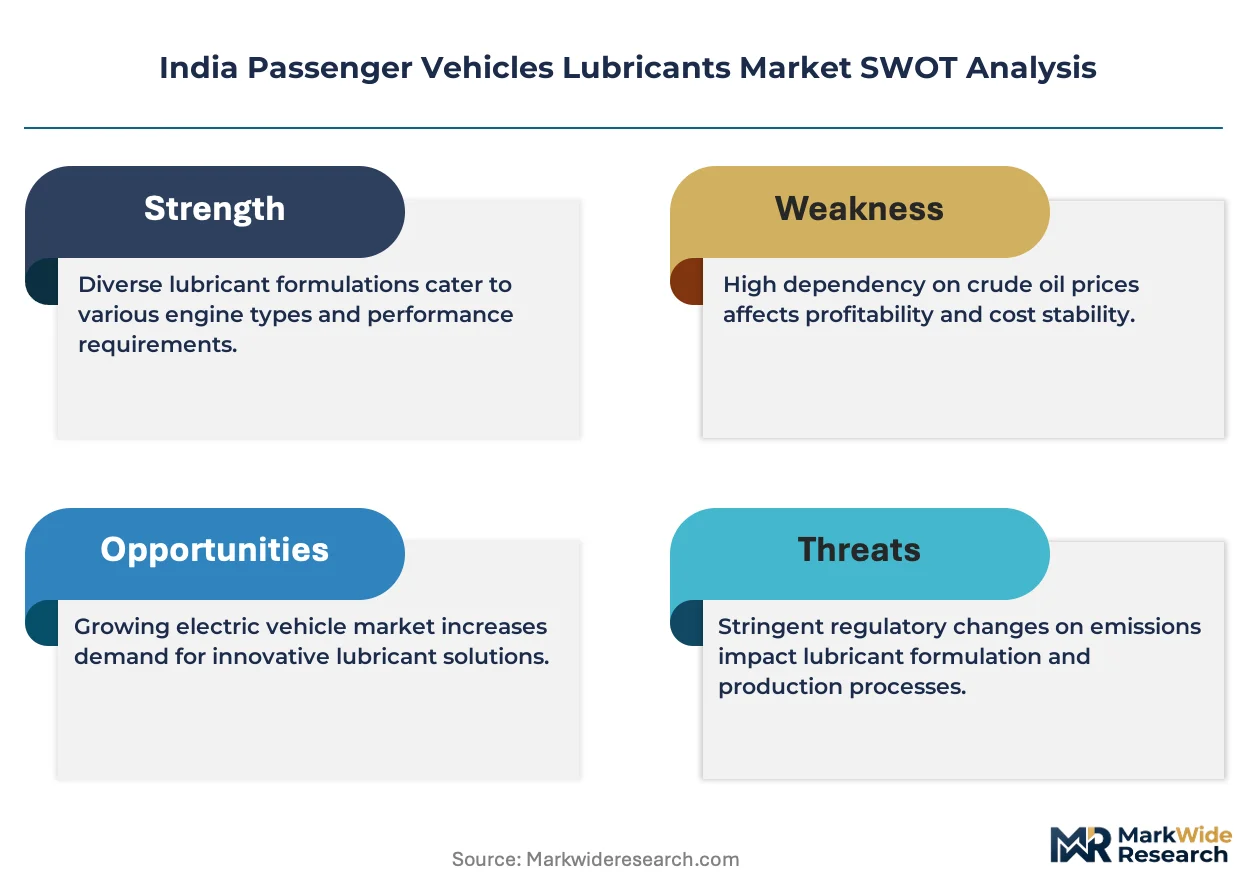
BIS certification mandates, CDSCO oversight of additive chemical safety, and CEA energy efficiency labeling collectively shape product formulation and market access protocols for lubricant manufacturers operating in India. The PLI scheme for automotive components indirectly stimulates lubricant demand by accelerating domestic vehicle production capacity. Stakeholders must monitor how BIS evolves viscosity grade labeling requirements and whether state-level EV adoption policies redirect lubricant R&D investment toward hybrid-compatible and reduced-volume formulations.
Market Dynamics
Bharat Stage VI emission norms are compressing lubricant formulation cycles as OEMs demand extended drain intervals and after-treatment compatibility from their supply base. This regulatory pressure is restructuring procurement relationships between refiners, additive suppliers, and automotive service networks.
Growth Catalysts
- Turbocharged Gasoline Direct Injection (TGDI) penetration:Engine downsizing trends force adoption of API SP/ILSAC GF-6 compliant formulations with enhanced LSPI protection. Passenger vehicle OEMs now specify synthetic 5W-30 as factory-fill standard.
- PLI scheme for automotive components:Domestic vehicle production capacity expansion under this incentive framework generates captive lubricant demand from assembly plant filling stations and dealer networks.
- Maharashtra-Gujarat freight corridor density:Fleet operators along the Mumbai-Pune industrial belt and Ahmedabad-Vadodara highway cluster are consolidating synthetic oil procurement through direct refinery agreements.
Market Restraints
- Group II/III base oil import dependency:Domestic refining capacity for high-viscosity-index base stocks remains concentrated at Indian Oil's Koyali and Panipat complexes, exposing blenders to feedstock cost volatility.
- Additive package supply concentration:Key detergent and dispersant chemistries rely on imports from US and European specialty chemical suppliers, creating tariff and currency exposure.
- BIS certification timeline friction:Bureau of Indian Standards approval processes for new viscosity grades and additive systems extend product launch cycles by 12-18 months versus regional competitors.
Strategic Opportunities
- Hybrid powertrain lubricant white space:Start-stop systems and belt-driven integrated starter-generators require dedicated formulations with enhanced oxidation stability for frequent thermal cycling.
- E-commerce direct-to-garage channels:Independent workshops in Tier-II cities are bypassing traditional auto parts distributors through platform-based procurement of certified lubricants.
- CEA energy efficiency labeling expansion:Anticipated mandatory fuel economy certification for lubricants would create premium tier differentiation based on verifiable test data rather than brand equity alone.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in tribology and additive synergy optimization remains concentrated at IIT Bombay and ICT Mumbai, limiting R&D scaling for mid-tier blenders.
- Drain interval extension compression:OEM service protocols now specify 15,000-20,000 kilometer intervals for synthetic formulations, reducing per-vehicle lubricant consumption volume over ownership lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Passenger Vehicles Lubricants Market |
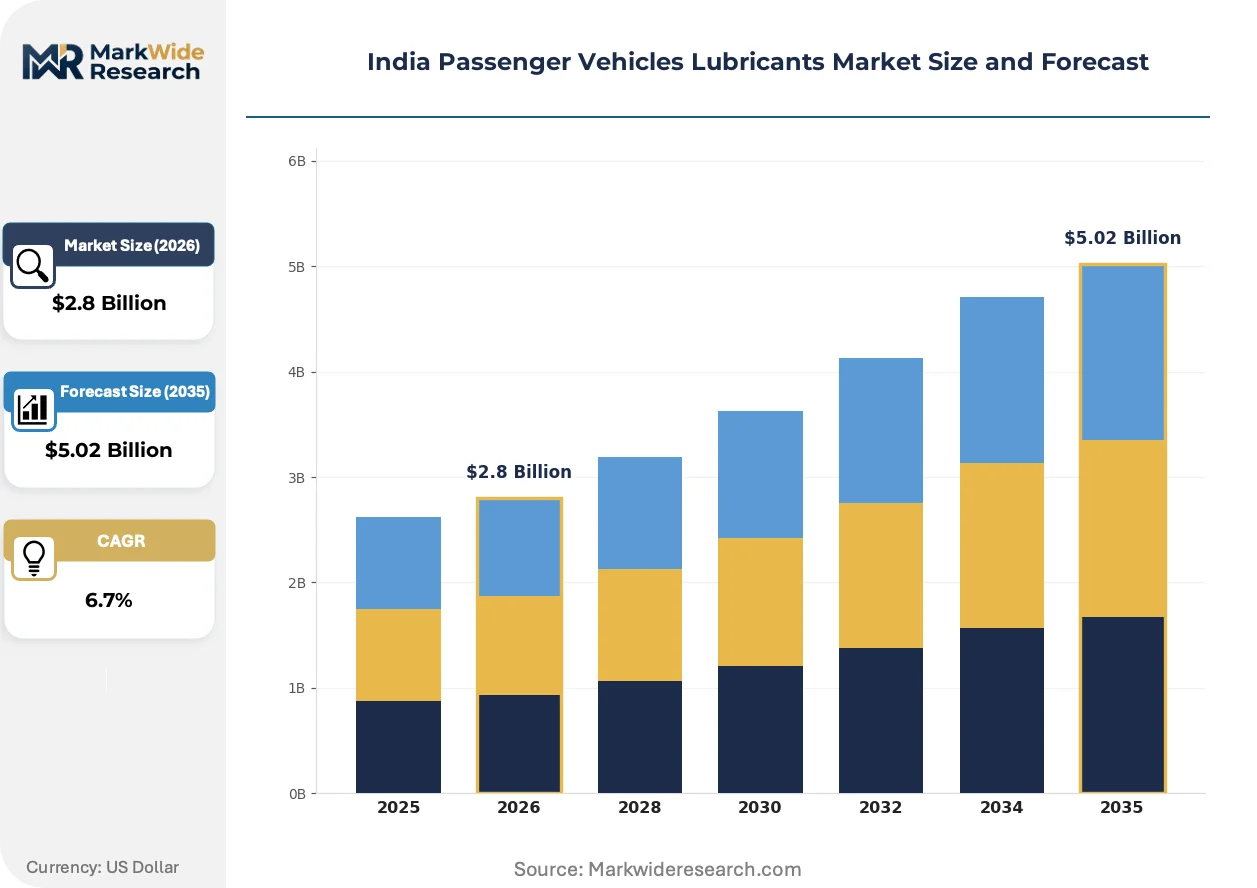
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lubricant Type: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Lubricants Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Barrels, Drums, Packets, Cans Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Wholesalers |
| Companies Covered | Indian Oil Corporation Limited, Bharat Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, BP PLC (Castrol), Royal Dutch Shell Plc, Gulf Oil International, ExxonMobil Corporation, Valvoline Inc., Idemitsu Kosan Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry is pivoting toward lower viscosity grades and hybrid-compatible additive systems as powertrain electrification fragments traditional engine lubricant demand. This shift is compressing the addressable market for conventional mineral oils while opening specialized application segments.
Polyalkylene glycol (PAG) and ester-based synthetic base stocks are penetrating high-performance passenger vehicle segments where thermal stability under turbocharger operating temperatures determines engine durability. German and Japanese OEMs operating in India have accelerated factory-fill specifications toward 0W-20 and 5W-20 grades, rendering obsolete the 10W-40 and 15W-40 mineral formulations that dominated the market through 2020.
BIS is revising IS 13656 viscosity grade labeling requirements to align with SAE J300 updates, forcing reformulation of products carrying outdated certification marks. Lubricant manufacturers must resubmit test data for cold-cranking simulator and high-temperature high-shear viscosity parameters, with Maharashtra-based blenders facing the steepest compliance burden given their volume concentration.
Fleet operators are consolidating procurement through annual volume contracts with direct refinery lifting rather than spot purchases through distributor networks. This behavioral shift is most visible in Gujarat's Surat-Vadodara industrial belt, where logistics companies are negotiating delivered-price agreements that bypass traditional auto parts retail markups and technical service bundling.
India Passenger Vehicles Lubricants Market Segmentation
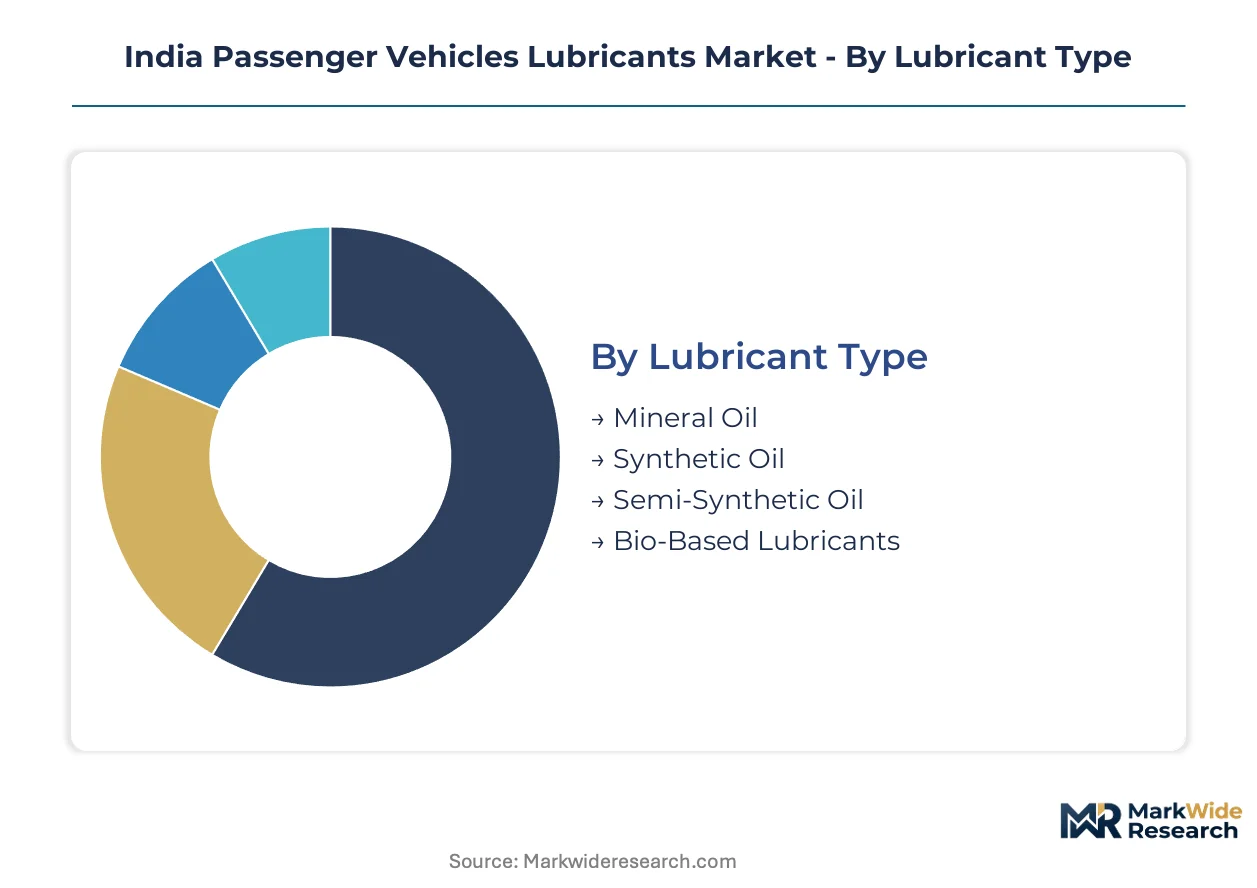
Segmentation in India's passenger vehicle lubricants market reveals how formulation chemistry, viscosity engineering, and channel economics fragment procurement decisions across OEM factory-fill programs, fleet operator contracts, and retail replacement cycles. Understanding these divides exposes where margin pools concentrate and where regulatory pressure reshapes product portfolios fastest.
Lubricant Type:
Passenger vehicle powertrains impose distinct thermal and mechanical stresses that segment lubricant demand across base oil refinement levels and additive sophistication.
- Synthetic Oil:Group III and PAO base stocks blended with advanced detergent-dispersant packages deliver oxidation stability for turbocharged direct-injection engines. Factory-fill specifications from Maruti Suzuki and Hyundai Motor India now mandate synthetic 5W-30 for new passenger vehicles, compressing mineral oil's addressable market.
- Mineral Oil:Group I and Group II base stocks dominate aftermarket replacement in Tier-III towns and rural Maharashtra where price sensitivity outweighs drain interval extension benefits. BIS certification costs and additive import tariffs squeeze blender margins at this tier.
- Semi-Synthetic Oil:Blended formulations occupy the transition segment for vehicles exiting warranty coverage, balancing cost against modest performance upgrade.
- Bio-Based Lubricants:Ester and vegetable oil derivatives target niche sustainability mandates from corporate fleet operators in Gujarat's industrial corridors.
The dominant share belongs to Synthetic Oil, while Bio-Based Lubricants is closing the gap fastest.
Viscosity Grade:
SAE J300 specifications stratify demand according to cold-start protection requirements and fuel economy optimization across India's climatic zones.
- 5W-30:The workhorse grade balances cold-cranking viscosity for northern Indian winters with high-temperature shear stability for highway cruising. Mumbai-Pune fleet operators specify this grade exclusively for mixed-duty gasoline passenger vehicles under BS VI emission compliance.
- 0W-20:Ultra-low viscosity formulations reduce hydrodynamic friction for hybrid powertrains and downsized turbocharged engines. Japanese OEM technical service bulletins now recommend this grade for start-stop equipped vehicles in Ahmedabad and Chennai urban cycles.
- 10W-40:Legacy grade retains volume in older passenger vehicle parc and commercial taxi segments where extended drain intervals matter less than upfront lubricant cost.
- 15W-50:High-viscosity reserve for performance applications and high-mileage engines operating in Rajasthan and Gujarat desert conditions.
5W-30 commands the volume base, though 0W-20 is expanding most quickly as OEM service protocols proliferate.
Packaging Type:
Packaging economics align with procurement scale and inventory turnover velocity across the value chain from refinery blending facilities to service bay dispensing.
- Drums:200-liter steel and polymer drums dominate fleet operator direct procurement through annual volume contracts with Indian Oil and Bharat Petroleum refinery complexes.
- Cans:One-liter and four-liter retail formats sustain auto parts store shelf presence and service station impulse replacement purchases.
- Barrels:Intermediate bulk packaging serves regional distributor consolidation points and large independent workshop chains.
- Packets:Single-use sachets address emergency top-up demand and rural market price-point accessibility.
Drums capture the fleet procurement channel, while Cans retain structural importance in retail brand building.
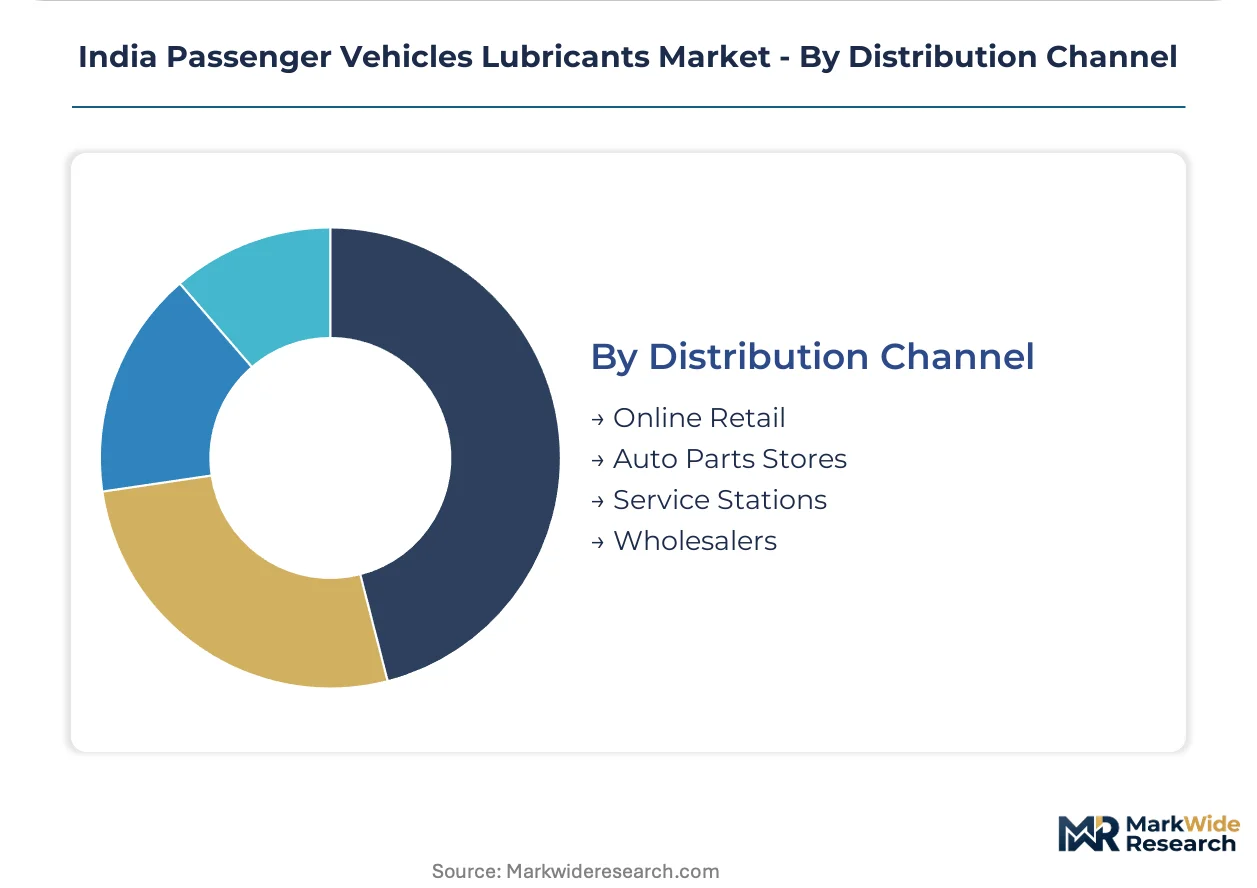
Distribution Channel:
Channel selection determines technical specification verification, price transparency, and inventory carrying cost allocation between manufacturers and end-users.
- Auto Parts Stores:Authorized distributors and independent retailers provide specification cross-referencing and brand trust verification at point of sale. Maharashtra's Nagpur and Nashik automotive clusters sustain dense network coverage.
- Service Stations:Indian Oil SERVO and BPCL MAK branded outlets bundle lubricant sales with technical service, capturing warranty-compliant replacement demand.
- Online Retail:Platform-based procurement bypasses distributor markups for independent garages in Tier-II cities, though counterfeit risk constrains premium synthetic adoption.
- Wholesalers:Regional aggregators manage inventory pooling for fragmented rural demand and small fleet operators.
Auto Parts Stores hold the volume concentration, yet Online Retail is gaining share fastest among digitally native workshop operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates and state-level industrial policies concentrate lubricant demand in India's western and southern manufacturing belts. Maharashtra and Gujarat host the densest automotive service networks and refinery infrastructure.
Maharashtra
Mumbai-Pune industrial corridor fleet operators specify synthetic 5W-30 through direct refinery agreements with Indian Oil's Koyali complex. The state's automotive service density supports 15,000-20,000 kilometer drain interval protocols under BS VI compliance. Nagpur logistics hub consolidates procurement for central India distribution.
Gujarat
Ahmedabad-Vadodara highway cluster generates concentrated demand from commercial fleet operators negotiating annual volume contracts. The state's petroleum refining infrastructure anchors western India feedstock security. Surat-based logistics companies bypass retail markups through delivered-price refinery agreements.
Karnataka
Bengaluru's technology corridor drives hybrid powertrain lubricant specification as start-stop vehicle penetration accelerates. The state's automotive R&D ecosystem attracts formulation chemistry talent from ICT Mumbai. Tier-II city workshops adopt platform-based procurement for certified synthetic products.
Tamil Nadu
Chennai blending facilities serve OEM factory-fill programs for Japanese and Korean passenger vehicle manufacturers. The state's manufacturing belt requires API SP/ILSAC GF-6 compliant formulations for turbocharged direct-injection engines. Gulf Oil International leverages local production for two-wheeler and passenger car motor oil specialization.
Delhi-NCR
National Capital Region fleet operators face the strictest BS VI enforcement, compressing formulation cycles for after-treatment compatibility. The region's air quality regulations accelerate synthetic oil adoption for extended drain intervals. Gurugram automotive clusters demand 0W-20 grades for hybrid urban cycle operation.
India Passenger Vehicles Lubricants Market Competitive Landscape
State-owned refiners and multinational lubricant specialists split the market along feedstock security versus formulation technology vectors. Indian Oil, Bharat Petroleum, and Hindustan Petroleum leverage captive refinery output for pan-India distribution scale. Shell, Castrol, and Gulf Oil compete through OEM factory-fill relationships and service station branding. Competitive moves concentrate on direct fleet procurement contracts and hybrid-compatible product line extensions.
Among state-owned refiners, Indian Oil Corporation Limited, Bharat Petroleum Corporation Limited, and Hindustan Petroleum Corporation Limited exemplify the integrated archetype controlling upstream base oil production through Koyali, Panipat, and Mumbai refinery complexes. Within the multinational specialist tier, BP PLC (Castrol) and Royal Dutch Shell Plc occupy positions anchored by global formulation technology transfer and OEM technical service partnerships. Gulf Oil International represents the regional specialist model through Chennai-based blending and franchise service station density.
| Leading Market Players |
|---|
| Indian Oil Corporation Limited |
| Bharat Petroleum Corporation Limited |
| Hindustan Petroleum Corporation Limited |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| Gulf Oil International |
| ExxonMobil Corporation |
| Valvoline Inc. |
| Idemitsu Kosan Co. Ltd |
| Others |
Supply & Pricing Matrix
Group II/III base oil import dependency determines both the premium-to-economy pricing spread across synthetic and mineral formulations and the geographic clustering of blending capacity around Indian Oil's Koyali and Panipat refinery complexes. This feedstock concentration forces blenders to absorb currency volatility into margin structures while fleet operators exploit direct refinery agreements to compress distributor markups.
Pricing Analysis
Maharashtra-Gujarat price spreads for synthetic 5W-30 exceed those in Tamil Nadu due to freight cost differentials from Koyali refinery output. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels reflects certification grade and volume scale differentiation. Cost compression in mineral oil tiers is intensifying because BIS certification timelines extend product launch cycles. Independent workshops in Tier-II cities exhibit highest price sensitivity, while OEM factory-fill programs demonstrate lowest sensitivity due to technical specification lock-in.
Supply Chain Analysis
Tariff exposure between India and US/European specialty chemical suppliers dominates supply chain risk for detergent and dispersant additive packages. Domestic refining capacity draws from Koyali, Panipat, and Mumbai complexes for base stock security, while additive chemistries rest on imports from Lubrizol, Infineum, and Afton facilities. Single-source vulnerability concentrates in high-viscosity-index Group III base oil production. Distribution runs through refinery-direct fleet contracts, auto parts store networks, and emerging platform-based procurement channels for independent garages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's passenger vehicle lubricants market sits at an early-cycle expansion story as BS VI emission compliance and turbocharged direct-injection engine penetration accelerate synthetic formulation adoption beyond current refinery capacity planning.
For Market Incumbents: Pre-empt hybrid powertrain lubricant specification shifts by dedicating R&D capacity to start-stop system formulations with enhanced oxidation stability. Indian Oil and Bharat Petroleum should secure backward integration into additive package blending through technology licensing with Lubrizol or Infineum to reduce tariff exposure. Channel control through exclusive fleet procurement contracts along the Mumbai-Pune corridor defends margin position against platform-based disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Karnataka's Bengaluru technology corridor where hybrid vehicle penetration outpaces national averages and formulation chemistry talent concentrates at ICT Mumbai satellite operations. Target Tier-II city independent workshops through e-commerce direct-to-garage channels with certified synthetic products that bypass traditional distributor networks. White space exists in bio-based lubricants for corporate fleet sustainability mandates in Gujarat's industrial corridors. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors blenders with captive refinery feedstock or proprietary additive technology. Long-term viability over a 5-10 year window hinges on hybrid-compatible product line depth and OEM factory-fill relationship durability. Acquisition targets should demonstrate BIS certification pipeline strength and direct fleet contract books. The signal to watch is state-level EV adoption policy acceleration that redirects lubricant R&D investment toward reduced-volume hybrid formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Reduces tariff exposure on US and European specialty chemical imports for domestic blenders. |
| Hybrid Powertrain Formulation Development | Captures start-stop system lubricant demand as Maruti Suzuki and Hyundai expand hybrid portfolios. |
| Direct Fleet Procurement Contracts | Bypasses auto parts retail markups through annual volume agreements with Maharashtra-Gujarat logistics operators. |
| E-Commerce Platform Partnership | Enables Tier-II city workshop access to certified synthetic products with counterfeit verification protocols. |
| BIS Certification Pipeline Investment | Compresses 12-18 month approval timelines for new viscosity grades under evolving IS 13656 standards. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant formulation chemists, refinery operations managers, fleet procurement heads, automotive service network operators, and BIS certification specialists; and secondary validation through customs import records for Group II/III base oils, BIS certification registries, OEM technical service bulletins, and petroleum ministry production statistics. Bottom-up triangulation across refinery output volumes, additive import tonnage, and vehicle parc lubricant consumption rates anchored demand estimates.
Forecast inputs incorporated lubricant type segmentation by base oil refinement level, viscosity grade stratification per SAE J300 specifications, packaging format economics, and distribution channel evolution across the projection horizon. Modeled dimensions spanned synthetic-mineral formulation mix, regional production cluster capacity utilization, and OEM factory-fill specification trajectories. CAGRs derived from regression analysis of base oil demand against vehicle production and parc expansion, with BS VI compliance timelines and PLI scheme automotive component incentives as structural demand accelerants.
Sensitivities concentrate around BIS certification timeline revisions, Group II/III base oil import tariff fluctuations, and state-level EV adoption policy acceleration that could compress addressable engine lubricant volumes. Forecasts reflect assumptions on synthetic penetration rates, drain interval extension protocols, and hybrid powertrain market share trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Europe Automotive Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Global Automotive Gears Market
Automotive Components
United States Automotive Pneumatic Actuators Market