
 Singapore Container Transshipment Market | 2026-2036
Singapore Container Transshipment Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Container Transshipment Market Insights
ISO 28000 supply chain security certification is unwinding the competitive landscape for terminal operators and shipping lines serving Singapore. PSA International Pte Ltd leverages its automated Pasir Panjang Terminal complex to sustain throughput leadership across Southeast Asian lanes. Mediterranean Shipping Company (MSC) anchors its intra-Asia network around Singapore's connectivity, while Pacific International Lines (PIL) specializes in regional feeder services linking secondary ports to the main hub.
Singapore Container Transshipment encompasses the transfer of containerized cargo between vessels at port facilities without customs clearance for import, typically involving gantry cranes with 65-ton lifting capacity and automated guided vehicles moving boxes at 6 meters per second across 600-meter quay lengths. The terminal type dimension reveals automated terminals capturing premium pricing through labor efficiency gains, while conventional terminals retain volume share in breakbulk-adjacent operations. Container size segmentation shows 40ft boxes dominating throughput volumes, though high cube variants are gaining share in electronics and pharmaceutical cargo flows where vertical space utilization reduces per-unit shipping costs.
The Maritime and Port Authority of Singapore enforces port facility security codes aligned with the International Ship and Port Facility Security Code, while the International Maritime Organization's carbon intensity indicators shape vessel eligibility for hub calls. Singapore's Green Port Programme incentivizes low-emission berth operations, directly influencing terminal equipment procurement cycles and shore power infrastructure deployment. Stakeholders must monitor how the next revision of IMO greenhouse gas strategy affects vessel deployment patterns and whether Singapore's carbon tax expansion alters the cost calculus for carriers routing through the Strait of Malacca.
Market Dynamics
The Maritime and Port Authority of Singapore's digital port clearance mandates are compressing terminal operating windows and forcing synchronized investments in automated stacking cranes and vessel traffic management systems across the harbor complex.
Growth Catalysts
- Intra-Asia Electronics Manufacturing:Vietnam and Thailand-based semiconductor fabricators are routing precision components through Singapore's bonded facilities to exploit duty deferral and consolidated cross-docking.
- IMO Carbon Intensity Indicators:The International Maritime Organization's vessel efficiency ratings are filtering eligible tonnage toward hub ports with shore power infrastructure, advantaging Singapore's electrified berths.
- Automated Guided Vehicle Deployment:Terminal operators are deploying 6-meter-per-second AGV fleets to compress inter-yard transit times and reduce labor dependency during peak vessel windows.
Market Restraints
- Land Scarcity Premium:Singapore's limited back-up acreage constrains yard expansion, forcing densification investments that raise per-TEU infrastructure amortization costs.
- Bunker Fuel Price Volatility:Vessel operators face margin compression from Singapore's high-low sulfur fuel oil spreads, reducing discretionary calls at the hub during arbitrage windows.
- Strait of Malacca Congestion:Piracy incidents and navigational bottlenecks near the Indonesian archipelago inject schedule unreliability into feeder connections from secondary Southeast Asian ports.
Strategic Opportunities
- Green Port Programme Incentives:Singapore's emission-linked berth fee discounts reward LNG dual-fuel vessel deployments, creating preferential queue access for compliant carriers.
- Pharmaceutical Cold Chain:Temperature-controlled transshipment for biologics remains underdeveloped relative to electronics volumes, offering margin expansion through specialized reefer handling.
- Digital Trade Corridors:Blockchain-enabled cargo documentation between Singapore and Dubai is reducing letter-of-credit processing friction for Middle East-Asia container flows.
Industry Challenges
- Cyber-Physical System Integration:Terminal operators struggle to harmonize legacy terminal operating systems with new IoT sensor networks across multi-phase automation rollouts.
- Specialized Crane Technician Shortage:The shallow talent pool for 65-ton gantry crane maintenance is extending mean-time-to-repair during critical vessel operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Container Transshipment Market |
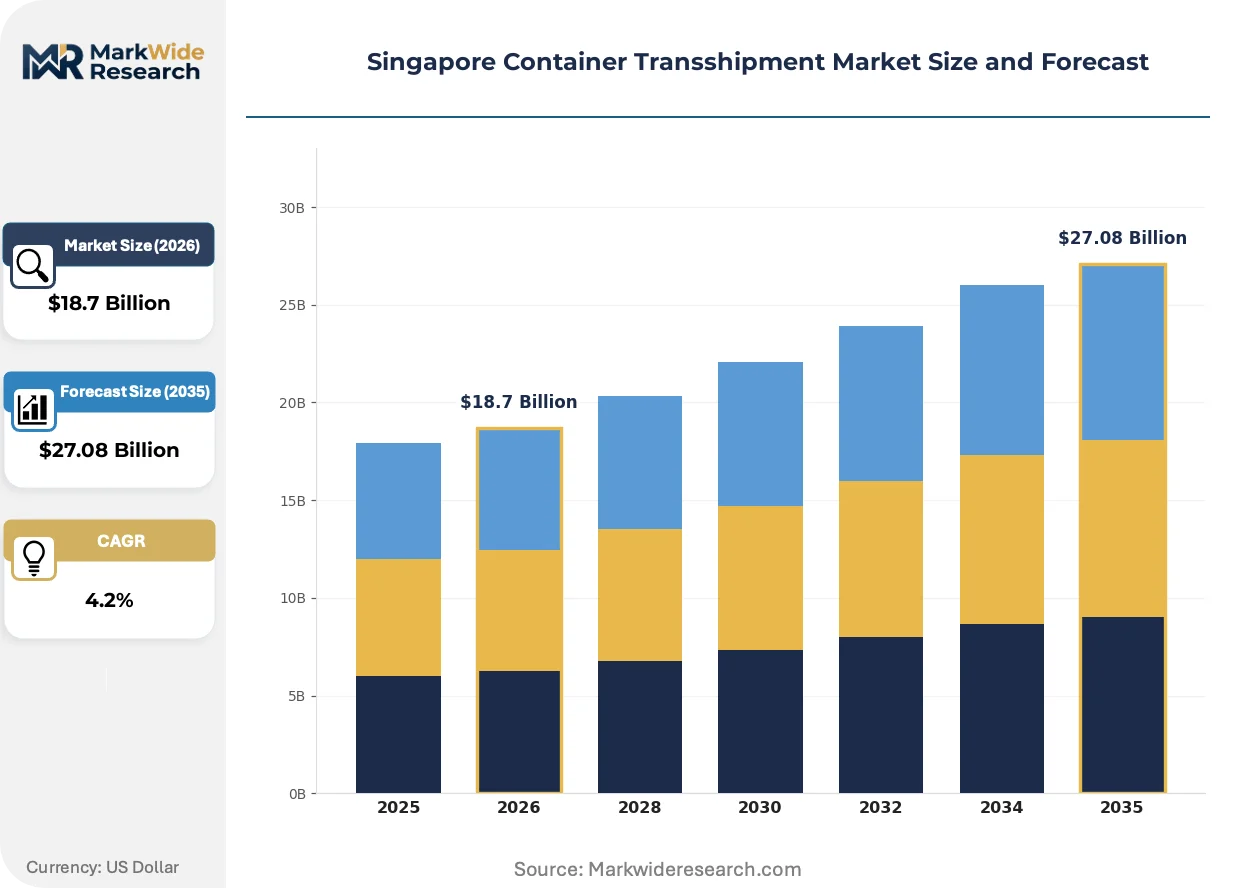
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading, Unloading, Storage, Inland Transportation Terminal Type: Automated Terminals, Conventional Terminals, Multi-Purpose Terminals, Dedicated Container Terminals Shipping Line: Maersk, MSC, COSCO, Hapag-Lloyd Container Size: 20ft, 40ft, 45ft, High Cube |
| Companies Covered | PSA International Pte Ltd, Maersk Line, Mediterranean Shipping Company (MSC), CMA CGM, Pacific International Lines (PIL), Evergreen Marine Corporation, Hapag-Lloyd, Ocean Network Express, Jurong Port Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Container Transshipment Market Trends and Innovations
Digital twin simulation and predictive berth allocation algorithms are compressing vessel turnaround windows and reshaping how terminal operators prioritize capital deployment across Singapore's harbor complex.
Autonomous quay cranes with integrated optical recognition systems are displacing manually operated ship-to-shore equipment at Pasir Panjang Terminal. PSA International is deploying these units to sustain throughput during labor-constrained night shifts. The technology is displacing conventional crane-operator staffing models and enabling 24-hour vessel operations without shift-change productivity losses.
Singapore's Green Port Programme mandates are tightening eligibility criteria for preferential berth assignments based on verified emission reductions. Carriers with installed shore power connections receive priority window allocations during peak demand periods. The policy is compressing deployment timelines for LNG-ready vessel orders among intra-Asia feeder operators.
Electronics manufacturers in Vietnam and Thailand are consolidating procurement of logistics services through Singapore-based freight forwarders rather than direct carrier contracts. This concentration is displacing fragmented port-to-port purchasing and shifting pricing power toward integrated supply chain managers with bonded warehouse control in the hub port.
Singapore Container Transshipment Market Segmentation
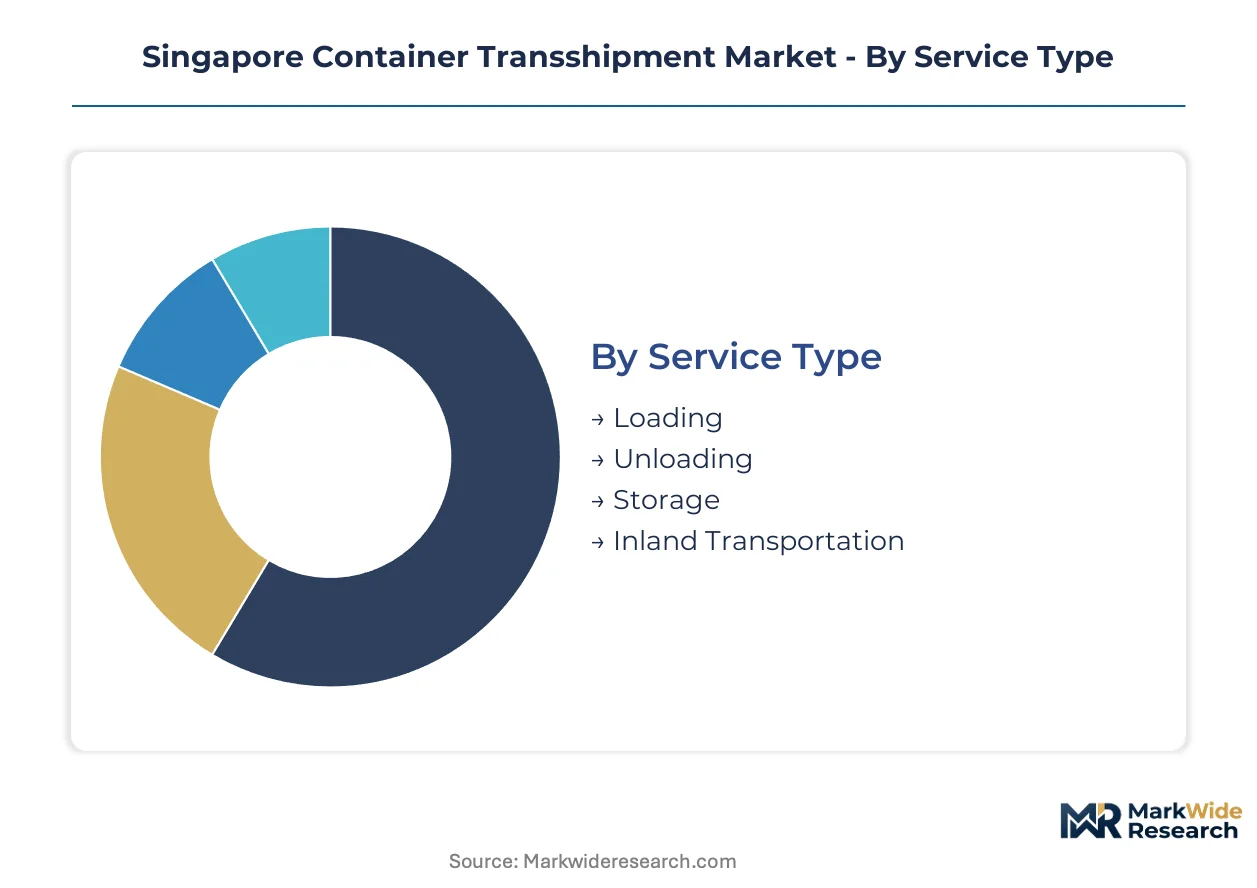
Segmentation in Singapore's container transshipment market reveals how cargo flows concentrate through specific terminal configurations and service arrangements. Each dimension shapes infrastructure investment priorities and carrier routing decisions across the harbor complex.
Service Type:
Loading and unloading services flow through vessel-to-yard channels, while storage and inland transportation segments route through bonded warehouse and intermodal corridors respectively.
- Loading:Gantry cranes with 65-ton lifting capacity transfer containers from yard stacks to vessel holds. Precision timing matters for semiconductor shippers in Vietnam and Thailand who face narrow delivery windows for just-in-time manufacturing.
- Unloading:Reverse cargo movement from vessel to yard requires synchronized berth allocation. The Maritime and Port Authority of Singapore's digital clearance mandates compress these windows, forcing terminal operators to deploy predictive algorithms.
- Storage:Bonded yard facilities defer customs duties for transshipment cargo. Electronics manufacturers exploit these arrangements for consolidated cross-docking of precision components.
- Inland Transportation:Truck and rail connections extend the port's reach into Johor and the Malaysian manufacturing corridor. PSA International coordinates these movements through integrated terminal operating systems.
Loading dominates revenue contribution. Unloading is where automation investment concentrates.
Terminal Type:
Cost tiers separate automated terminals commanding premium handling fees from conventional facilities serving breakbulk-adjacent operations with lower infrastructure amortization.
- Automated Terminals:Pasir Panjang Terminal deploys autonomous quay cranes and 6-meter-per-second AGV fleets. Labor efficiency gains justify capital intensity for carriers with high-frequency intra-Asia calls.
- Conventional Terminals:Manually operated gantry cranes retain volume share in cargo mixes requiring flexibility for non-standard box sizes. These facilities absorb overflow during peak vessel windows at automated complexes.
- Multi-Purpose Terminals:Hybrid configurations handle containerized and breakbulk cargo through shared infrastructure. Singapore's land scarcity premium forces densification of these mixed-use facilities.
- Dedicated Container Terminals:Single-purpose facilities optimize throughput for pure box traffic. Mediterranean Shipping Company anchors dedicated berth arrangements at these sites for network reliability.
Automated terminals lead margin extraction. Dedicated container terminals are climbing the fastest in throughput share.
Shipping Line:
Customer type segmentation splits between global integrators with owned terminal assets and regional specialists relying on common-user facilities.
- Maersk:Danish carrier with dedicated terminal investments and integrated logistics subsidiaries. Electronics procurement consolidation through Singapore-based freight forwarders strengthens its hub presence.
- MSC:Swiss-Italian line anchoring intra-Asia network connectivity around Singapore's port. Shore power infrastructure investments align with Green Port Programme incentive structures.
- COSCO:Chinese state-owned carrier leveraging Belt and Road corridor integration. Middle East-Asia flows through Singapore connect to COSCO's Dubai terminal network.
- Hapag-Lloyd:German container line with alliance partnerships determining terminal access priorities. Carbon intensity ratings shape its vessel eligibility for preferential berth assignments.
MSC dominates intra-Asia feeder deployment. Maersk is where integrated logistics expansion concentrates.
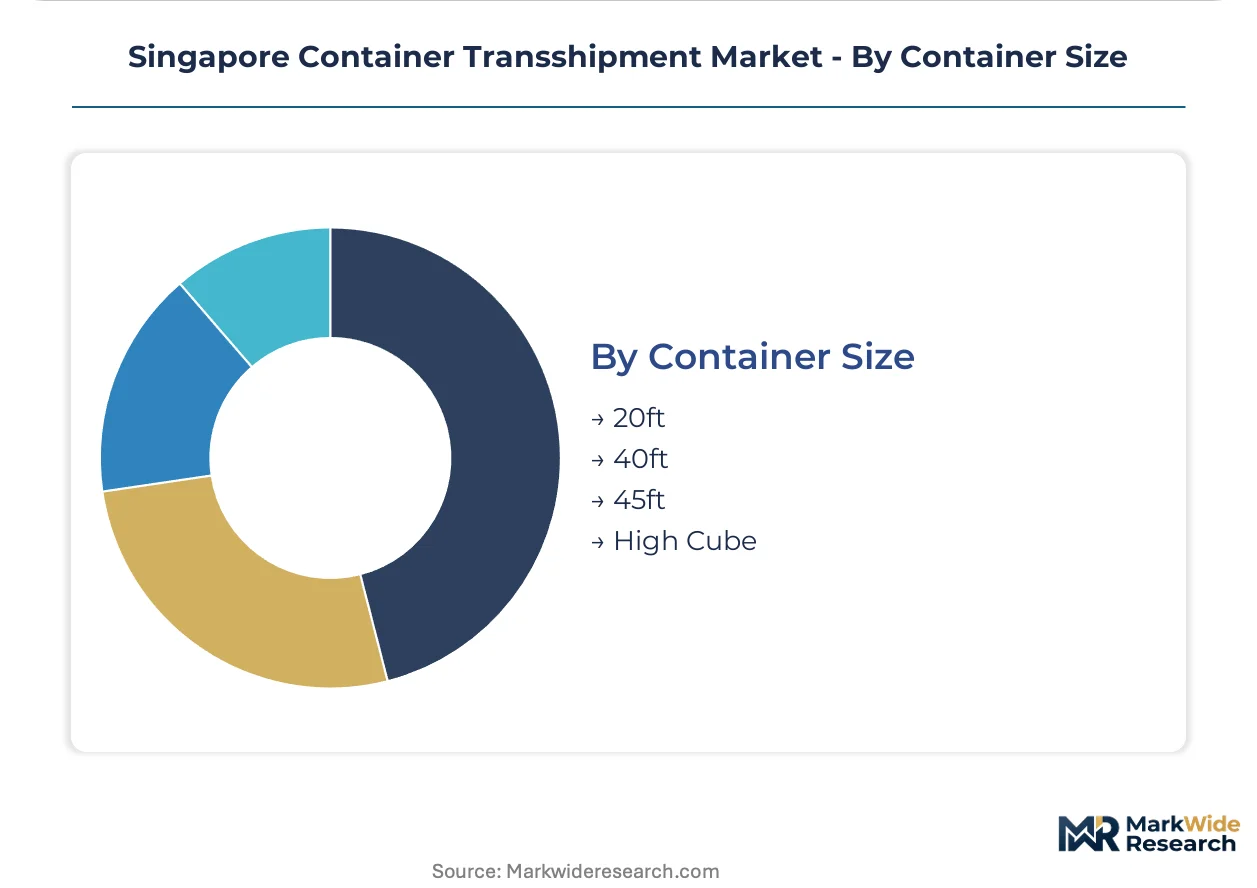
Container Size:
Volume concentration varies by box dimension, with 40ft units absorbing the majority of electronics and manufacturing cargo flows.
- 20ft:Standard twenty-foot equivalent units serve dense commodity shipments and regional feeder connections. Indonesian archipelago routes favor this dimension for port draft constraints.
- 40ft:Forty-foot containers handle the bulk of Vietnam and Thailand semiconductor fabricator shipments. Vertical space utilization in these units reduces per-unit shipping costs for high-value electronics.
- 45ft:Extended length boxes accommodate lightweight volumetric cargo. European apparel re-exports through Singapore exploit this dimensional efficiency.
- High Cube:Taller variants gain share in pharmaceutical and electronics flows where additional vertical clearance enables optimized stowage. Temperature-controlled biologics increasingly specify this format.
40ft containers dominate throughput volumes. High Cube is where margin expansion concentrates for specialized cargo handlers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Green Port Programme incentives are reshaping carrier routing decisions across Southeast Asian waters, compressing deployment timelines for emission-compliant vessel fleets throughout the region.
Vietnam
Semiconductor fabricators in Ho Chi Minh City and Hanoi are consolidating precision component flows through Singapore's bonded facilities. Vietnam's Ministry of Transport port modernization directives accelerate deep-water terminal investments at Cai Mep-Thi Vai. The northern Red River Delta electronics corridor feeds growing transshipment demand through Singapore's hub.
Thailand
Automotive and electronics manufacturers in the Eastern Economic Corridor exploit Singapore's duty deferral mechanisms for just-in-time supply chains. Thailand's Board of Investment tax incentives for logistics infrastructure align with feeder service expansion to Singapore. Laem Chabang Port's capacity constraints push overflow cargo toward Singapore's automated terminals.
Indonesia
Archipelago port draft limitations favor 20ft container movements through Singapore's transshipment complex. Indonesia's Maritime Investment Coordinating Board prioritizes feeder connectivity upgrades linking Batam and Belawan to Singapore. The Java Sea manufacturing belt concentrates electronics assembly flows requiring Singapore's cold chain and bonded storage capabilities.
Malaysia
Johor's manufacturing corridor integrates with Singapore's port through truck and rail intermodal connections. Malaysia's Port Klang expansion competes for transshipment volume while complementary feeder services reinforce Singapore's hub position. The Iskandar Malaysia special economic zone generates cross-border cargo flows handled through PSA International's integrated systems.
Singapore Container Transshipment Market Competitive Landscape
Player mix skews toward state-linked terminal operators and alliance-anchored shipping lines with dedicated berth arrangements. Two strategic archetypes dominate: vertically integrated port-to-door logistics providers and regional feeder specialists optimizing intra-Asia connectivity. Competitive moves concentrate on automation capital deployment and shore power infrastructure partnerships securing preferential queue access under Singapore's emission-linked incentive structures.
Within the terminal operator tier, PSA International Pte Ltd and Jurong Port Pte Ltd represent contrasting automation strategies at Singapore's harbor complex. Among shipping line participants, Mediterranean Shipping Company and Pacific International Lines occupy distinct positions in hub-and-spoke network architecture. Maersk Line exemplifies the integrated logistics archetype consolidating freight forwarder relationships.
| Leading Market Players |
|---|
| PSA International Pte Ltd |
| Maersk Line |
| Mediterranean Shipping Company (MSC) |
| CMA CGM |
| Pacific International Lines (PIL) |
| Evergreen Marine Corporation |
| Hapag-Lloyd |
| Ocean Network Express |
| Jurong Port Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term berth concession agreements lock in both terminal capacity access and handling fee visibility for carriers anchoring intra-Asia networks through Singapore. These arrangements insulate Mediterranean Shipping Company and Pacific International Lines from spot-market volatility while committing them to minimum throughput guarantees that amortize PSA International's automation investments across the Pasir Panjang complex.
Pricing Analysis
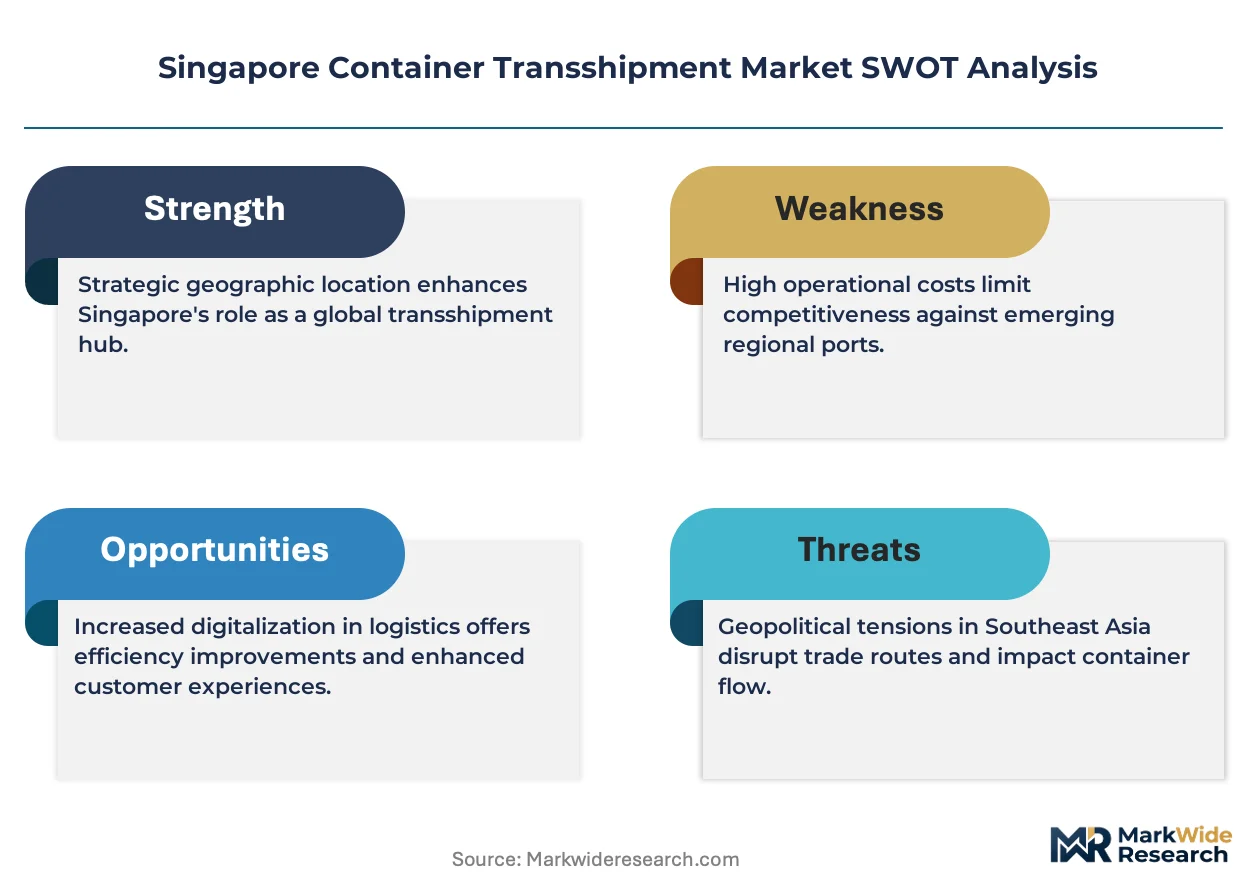
Certification level (ISO 28000 supply chain security) creates the primary spread between premium automated terminals and conventional facilities. Three-tier pricing structure across Green Port Programme compliant, standard, and non-compliant berth tiers concentrates margin extraction at electrified terminals with shore power infrastructure. Pricing pressure stems from bunker fuel price volatility compressing carrier margins and reducing discretionary hub calls during arbitrage windows. Regional feeder operators exhibit highest price sensitivity due to thin margins on secondary port connections, while integrated logistics providers with bonded warehouse control absorb premium handling fees for just-in-time electronics flows.
Supply Chain Analysis
Just-in-time inventory strategies dominate semiconductor and automotive component flows, compressing dwell times at Singapore's bonded facilities and demanding predictive berth allocation algorithms. Manufacturing concentration in Vietnam, Thailand, and Indonesia feeds container aggregation through Singapore's hub, with precision components from Ho Chi Minh City fabricators and Eastern Economic Corridor assembly plants drawing from this corridor. Single-source vulnerability concentrates in the Strait of Malacca chokepoint, where piracy incidents and navigational bottlenecks inject schedule unreliability. Distribution runs through PSA International's integrated terminal operating systems coordinating truck and rail intermodal connections into Johor and the Malaysian manufacturing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's container transshipment market is cycling through a recovery phase driven by intra-Asia electronics manufacturing expansion and terminal automation investments compressing vessel turnaround windows.
For Market Incumbents: Consolidate throughput leadership by deepening automation deployment at Pasir Panjang Terminal and securing dedicated berth arrangements with alliance-anchored carriers. The shallow talent pool for 65-ton gantry crane maintenance poses operational risk during critical vessel windows; vertical integration into specialized technician training programs mitigates mean-time-to-repair exposure. Shore power infrastructure partnerships secure preferential queue access under Singapore's emission-linked incentive structures. For New Entrants and Emerging Players: Lead with pharmaceutical cold chain specialization targeting temperature-controlled biologics transshipment, a segment underdeveloped relative to electronics volumes. The high cube container format for biologics offers margin expansion through specialized reefer handling at conventional terminals absorbing automated complex overflow. Blockchain-enabled cargo documentation partnerships with Dubai-based terminals reduce letter-of-credit processing friction for Middle East-Asia flows. For Investors and Strategic Acquirers: Capital is best deployed toward terminal operators with Green Port Programme compliance and integrated logistics capabilities spanning bonded warehouse control. The five-to-ten year viability window favors assets with shore power infrastructure and LNG dual-fuel vessel accommodation. Watch for IMO greenhouse gas strategy revisions as the inflection indicator that would re-rate vessel eligibility for preferential berth assignments and trigger infrastructure recapitalization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Expansion | Autonomous quay cranes at Pasir Panjang compress vessel turnaround windows and sustain 24-hour operations. |
| Shore Power Infrastructure Partnership | Electrified berths secure preferential queue access under Singapore's emission-linked fee discount structures. |
| Pharmaceutical Cold Chain Development | Specialized reefer handling for biologics captures margin expansion in underdeveloped temperature-controlled segments. |
| Digital Trade Corridor Integration | Blockchain documentation with Dubai terminals reduces processing friction for Middle East-Asia container flows. |
| Feeder Service Network Densification | Regional connections from Batam and Belawan reinforce Singapore's hub position against Port Klang competition. |
Research Methodology
A spread of perspectives from terminal operations executives, carrier network planners, freight forwarder procurement leads, and Maritime and Port Authority of Singapore regulatory specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, MPA port statistics, IMO regulatory filings, and SEC disclosures from listed shipping lines. Bottom-up throughput modeling and top-down regional trade flow analysis triangulated volume and value estimates.
Segmentation dimensions modeled include terminal type (automated, conventional, multi-purpose, dedicated), service type (loading, unloading, storage, inland transportation), shipping line category (global integrator, regional specialist), and container size format across the projection horizon. CAGRs were derived from historical throughput trends, vessel deployment patterns, and electronics manufacturing capacity expansion in Vietnam and Thailand. Forecast inputs incorporated Green Port Programme incentive structures and IMO carbon intensity indicator thresholds.
Forecasts assume regulatory continuity in Singapore's port facility security codes and Maritime and Port Authority of Singapore digital clearance mandates; material policy shifts would require re-modeling of terminal automation deployment timelines. Revision becomes warranted when IMO greenhouse gas strategy revisions cross thresholds that alter vessel eligibility for hub calls or when Singapore's carbon tax expansion materially changes routing calculus for Strait of Malacca transits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sliding Fender Market
Marine
Global Maritime Information Market
Marine
Yacht Painting and Maintenance Market
Marine
Fishing Vessel Market
Marine
Marine Navigation System Market
Marine
Flap Rudder Market
Marine
Tele-Operated Marine Drone Market
Marine
Marine Engines Market
Marine
Yacht Shell Doors Market
Marine
Marine AIS Monitoring System Market
Marine
Boat Trolling Motor Market
Marine
Marine Pipes Market
Marine
Marine Lighting Market
Marine
Marine Growth Removal Tool Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Marine Interiors Market