
 Marine Stabilizers Market | 2026-2036
Marine Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Stabilizers Market Insights
Italian and Dutch specialty producers is pivoting toward compact electric gyroscopic systems for the superyacht segment. Seakeeper leverages its vacuum-sealed flywheel architecture to dominate recreational installations. Quantum Marine Stabilizers sustains its position in the megayacht category through custom hydraulic fin arrays. SKF Group anchors the European supply chain with precision bearing technology that reduces gyroscopic friction losses.
Marine stabilizers are anti-roll devices that counteract vessel pitching and rolling through hydrodynamic fins, spinning flywheels, or interceptors generating corrective lift forces, with modern units achieving roll reduction exceeding 90% at speeds below 6 knots. Their primary purpose is to ensure crew safety, equipment integrity, and passenger comfort across variable sea states. Gyroscopic stabilizers now capture the fastest expansion within the product type dimension as electric motor advances shrink unit footprint and weight. Hydraulic technology still occupies the largest installed base in cargo ships and naval vessels where power density requirements exceed electric alternatives. The application split favors passenger ships for premium pricing, though offshore service vessels represent the emerging volume frontier as wind farm support boats multiply.
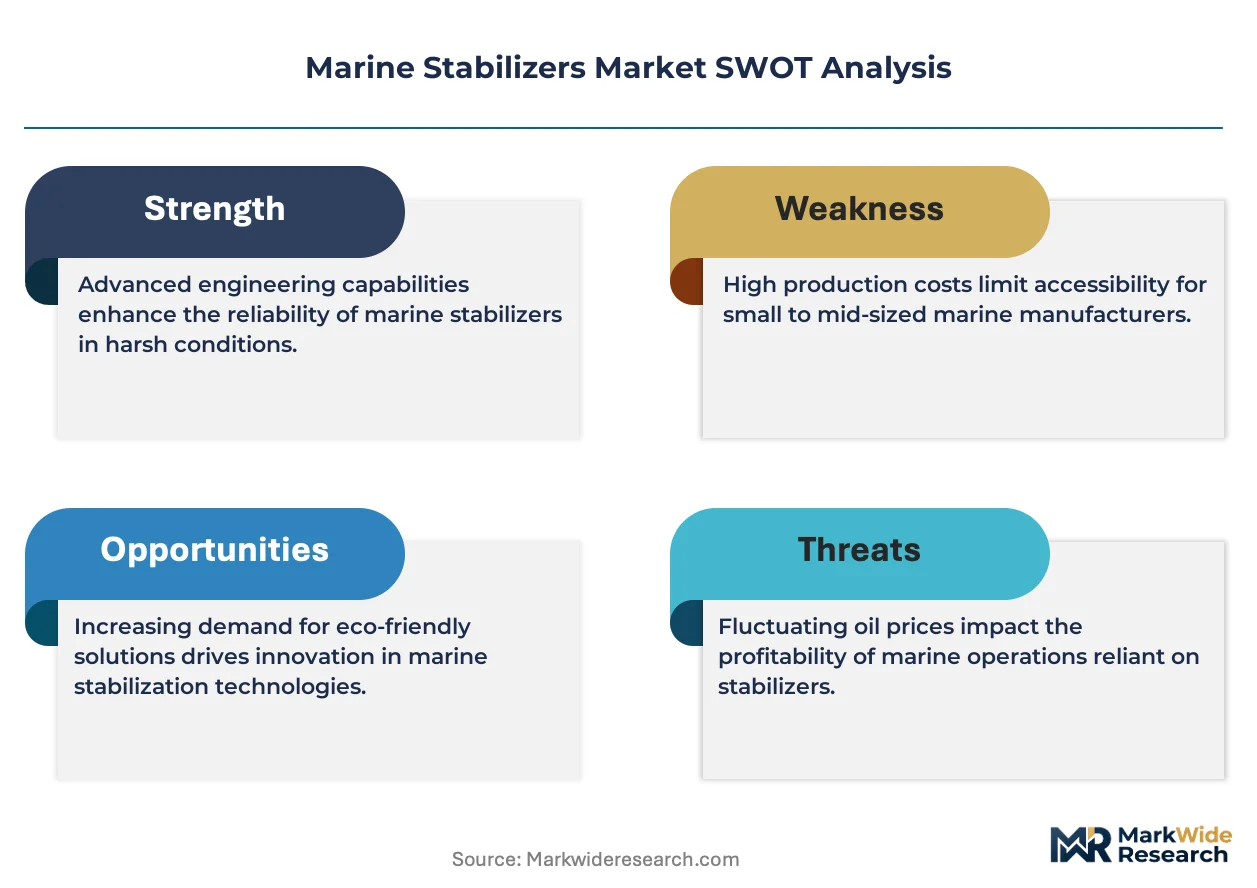
IMO stability criteria, the EU MRV framework, and classification society rules from Lloyd's Register and DNV shape product certification pathways and retrofit eligibility across European and Asian fleets. The US Coast Guard enforces separate intact stability standards for domestic passenger vessels that limit certain interceptor configurations in shallow-draft operations. Stakeholders must monitor the divergence between electric and hydraulic technology cost curves while tracking offshore wind vessel specifications that will determine next-generation stabilizer form factors.
Market Dynamics
The transition from hydraulic to electric gyroscopic architectures is compressing installation footprints while expanding addressable vessel categories, forcing incumbent suppliers to reconfigure manufacturing lines around compact flywheel assemblies.
Growth Catalysts
- IMO Stability Mandates:Tighter roll-motion limits for passenger vessels under the International Maritime Organization's intact stability criteria are mandating stabilizer retrofits across existing fleets.
- Offshore Wind Expansion:Norwegian and UK wind farm support vessels require zero-speed stabilization for turbine technician transfers, opening volume demand previously served by anchor-dependent operations.
- Electric Motor Advances:Permanent magnet synchronous motor improvements are shrinking gyroscopic unit weight by half, enabling installation on 40-foot yachts previously excluded from active stabilization.
Market Restraints
- Copper and Rare Earth Volatility:Neodymium magnet and copper winding costs fluctuate with Chinese export quotas, squeezing electric gyroscope margins against fixed-price shipyard contracts.
- Hydraulic Supply Concentration:Precision hydraulic actuator production clusters in German and Japanese machine shops, creating single-source vulnerability for fin-stabilizer arrays.
- Technical Ceiling at Ultra-Low Speeds:Gyroscopic precession effectiveness degrades below 3 knots, leaving interceptors as the only viable option for stationary mooring stabilization.
Strategic Opportunities
- Italian Superyacht Refit Market:Viareggio and Ancona shipyards are expanding dry-dock capacity for 50-meter-plus vessel upgrades, creating aftermarket installation demand.
- EU Green Deal Vessel Incentives:Battery-electric harbor craft qualify for retrofit subsidies when paired with electric stabilizers, bundling propulsion and anti-roll upgrades.
- Digital Twin Convergence:Real-time sea state modeling fused with gyroscopic precession control is enabling predictive roll cancellation before wave encounter.
Industry Challenges
- Marine Hydrodynamics Talent Scarcity:Computational fluid dynamics specialists with vessel motion expertise command premium salaries, constraining R&D headcount at mid-tier suppliers.
- Classification Society Certification Lag:Lloyd's Register and DNV type-approval timelines for novel interceptor geometries extend 18-24 months, delaying product launches.
- Legacy Hydraulic Integration:Retrofitting electric gyros onto vessels with existing fin-based hydraulic systems requires custom mechanical isolation, complicating yard scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Stabilizers Market |
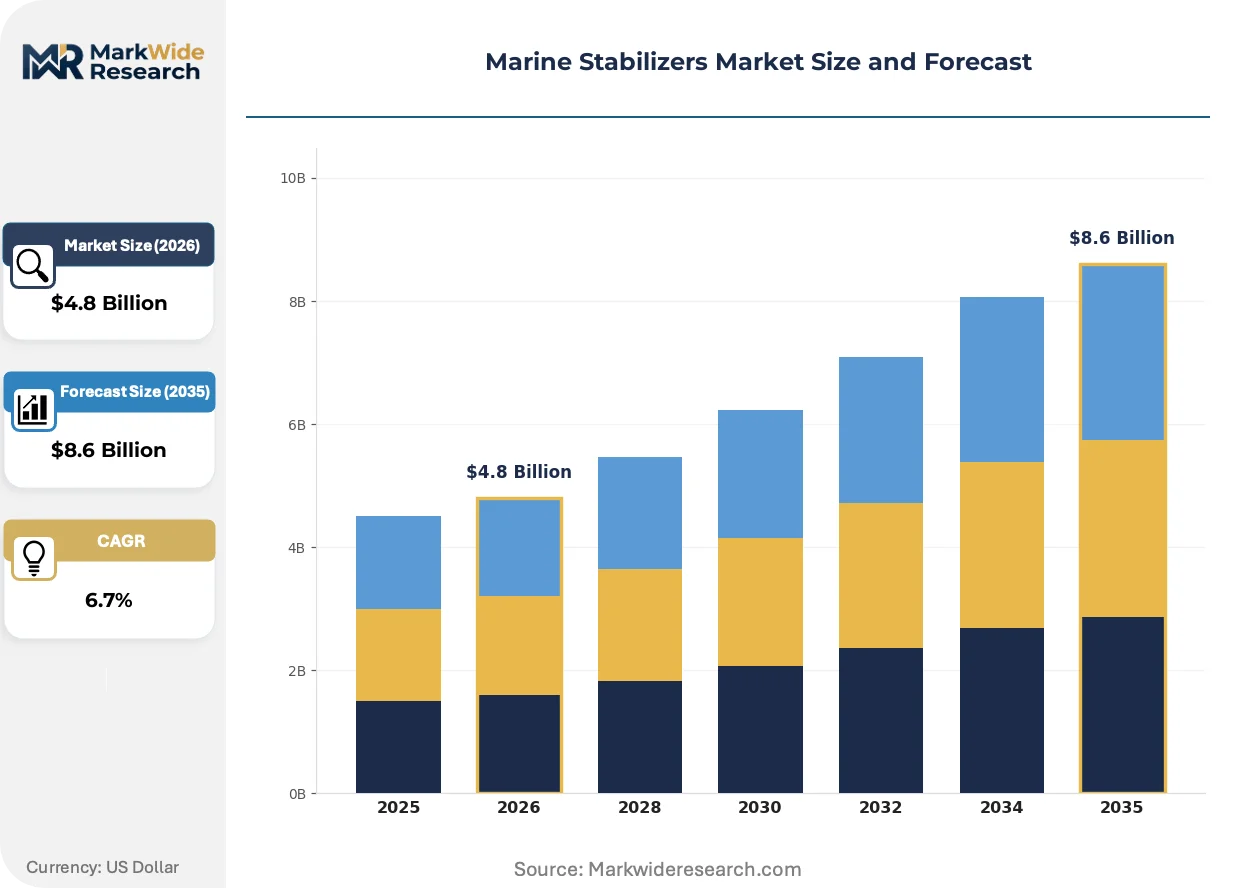
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fin Stabilizers, Gyroscopic Stabilizers, Active Rotary Stabilizers, Interceptor Stabilizers Technology: Hydraulic, Electric, Pneumatic, Electro-Hydraulic Application: Passenger Ships, Cargo Ships, Naval Vessels, Offshore Service Vessels End User: Shipbuilders, Marine Operators, Government Defense, Offshore Exploration Companies |
| Companies Covered | Seakeeper, Quantum Marine Stabilizers, Naiad Dynamics, Sleipner, Fincantieri, SKF Group, Imtra, WESMAR Marine Electronics, Kongsberg Maritime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Stabilizers Market Trends and Innovations
Active stabilization technology is bifurcating into compact electric units for recreational craft and high-power hydraulic arrays for commercial vessels, with software-defined control systems bridging both categories.
Permanent magnet flywheel technology is integrating vacuum-sealed enclosures with active magnetic bearings to eliminate mechanical wear. Superyacht builders in the Netherlands are specifying these units for 30-60 meter newbuilds where space constraints previously precluded stabilization. The structural consequence is that electric architectures are integrating into vessel design earlier, compressing the traditional retrofit-dominant revenue model.
The EU's F-Gas Regulation is phasing out hydrofluorocarbon refrigerants used in hydraulic power unit cooling, forcing suppliers to adopt CO2-based or water-glycol heat exchange systems. This industrial consequence raises system complexity for fin-stabilizer installations. Cargo vessel operators in the Mediterranean are responding by accelerating electric gyroscope evaluations to preempt compliance-driven hydraulic obsolescence.
Shipyard procurement departments are consolidating vendor relationships around integrated motion-control packages rather than discrete stabilizer purchases. The equipment supplier channel is being disrupted by turnkey seakeeping solution providers. This consolidation is most visible in German and Dutch newbuild yards, where single-source accountability for ride quality is replacing multi-vessel subsystem bidding.
Marine Stabilizers Market Segmentation
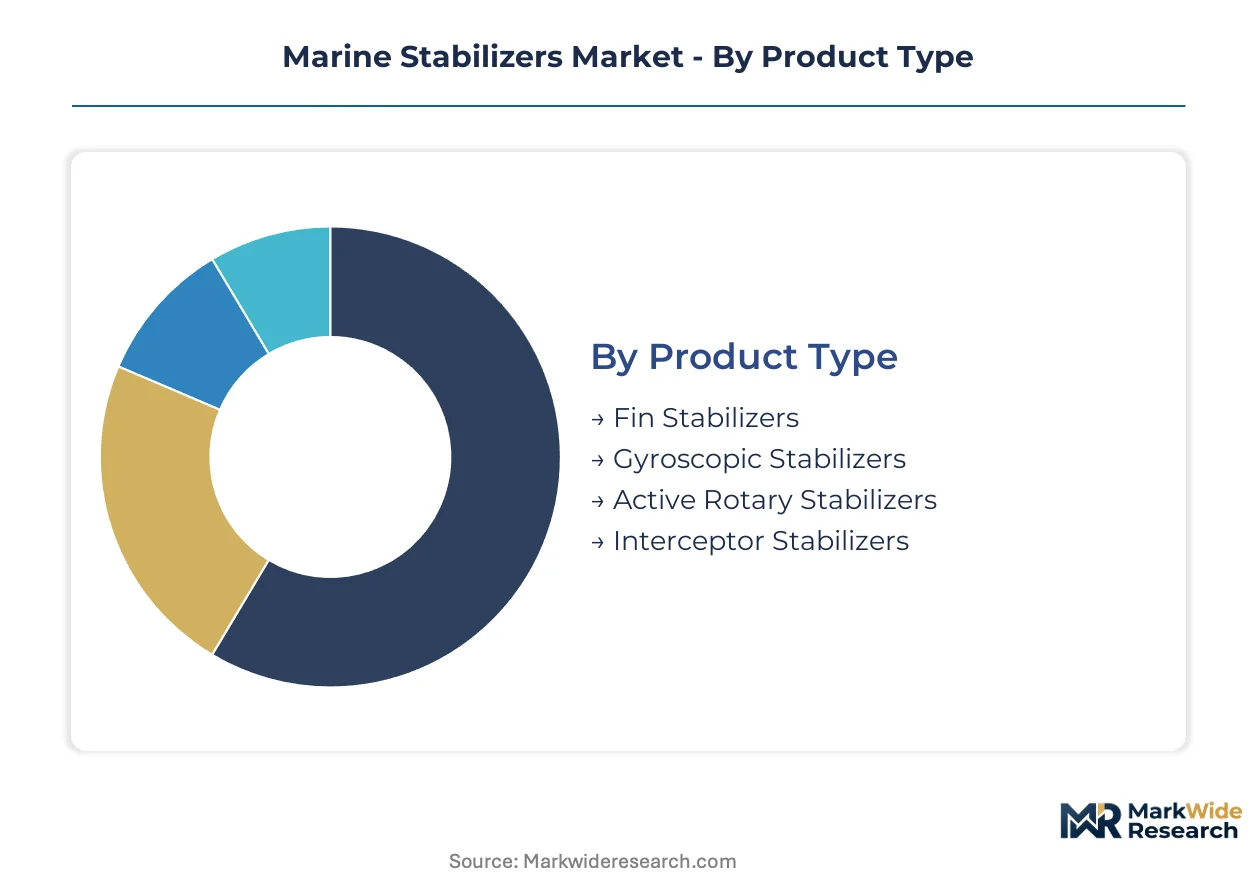
Marine stabilizer procurement decisions split across vessel architecture constraints, power system compatibility, and regulatory certification pathways. Buyers evaluate roll-reduction performance against installation footprint, maintenance intervals, and yard integration complexity.
Product Type:
Shipyards select stabilizer architecture based on vessel displacement, operating speed envelope, and available machinery space below deck.
- Fin Stabilizers:Hydrodynamic wing surfaces extend from the hull bilge to generate corrective lift forces against rolling motion. Italian and Greek ferry operators specify these units for high-speed passenger routes where continuous forward motion sustains hydrodynamic efficiency.
- Gyroscopic Stabilizers:Vacuum-sealed flywheel assemblies mounted on gimbals exploit angular momentum precession to counteract vessel roll. Dutch superyacht builders are expanding specifications for compact electric variants as permanent magnet motor advances shrink unit footprint below 500 kilograms.
- Active Rotary Stabilizers:Rotating cylinders exploit the Magnus effect to generate variable lift forces without external appendages. Offshore wind farm support vessels in Norwegian waters deploy these units for zero-speed stabilization during turbine technician transfers.
- Interceptor Stabilizers:Vertically actuated blades at the stern intercept water flow to trim vessel attitude. Shallow-draft harbor craft in Mediterranean ports favor interceptors where fin clearance constraints prohibit retractable wing installations.
Volume sits with fin stabilizers; growth tilts toward gyroscopic units.
Technology:
Power transmission architecture determines maintenance burden, energy consumption, and compatibility with vessel electrical infrastructure.
- Hydraulic:Pressurized oil circuits drive actuator pistons with power density exceeding electric alternatives for high-load fin arrays. German and Japanese machine shops concentrate precision hydraulic component production, creating supply chain vulnerability for large commercial installations.
- Electric:Permanent magnet synchronous motors eliminate fluid leakage risk and reduce machinery room ventilation requirements. EU F-Gas Regulation compliance is accelerating electric adoption as hydrofluorocarbon refrigerant phaseout raises cooling system complexity for hydraulic power units.
- Pneumatic:Compressed air systems provide rapid response for interceptor blade positioning in lightweight applications. Limited to small craft where accumulator weight penalties remain acceptable.
- Electro-Hydraulic:Hybrid architectures combine electric motor precision with hydraulic force multiplication for megayacht fin arrays exceeding 15 square meters surface area.
Installed base favors hydraulic systems; electric architectures are climbing the fastest.
Application:
Operating profile and passenger exposure determine stabilizer performance specifications and certification stringency.
- Passenger Ships:IMO intact stability criteria mandate roll-motion limits that drive premium stabilizer specifications. Mediterranean cruise operators and Baltic ferry lines represent concentrated demand for redundant fin-gyro hybrid installations.
- Cargo Ships:Container vessel operators prioritize fuel efficiency over ride quality, limiting stabilizer penetration to refrigerated cargo routes where roll-induced spoilage risk justifies capital expenditure.
- Naval Vessels:Stealth requirements and shock survivability specifications constrain stabilizer selection. National defense procurement programs in France and the UK specify hardened electro-hydraulic arrays with acoustic signature management.
- Offshore Service Vessels:Wind farm support and platform supply operations require zero-speed stabilization for personnel transfer safety. Norwegian North Sea operators are expanding fleet specifications as offshore wind installation activity intensifies.
Revenue concentration rests with passenger ships; offshore service vessels are expanding most quickly.
End User:
Procurement authority and technical integration responsibility vary across vessel lifecycle stages.
- Shipbuilders:New construction specifications embed stabilizer selection within hull structural design. Dutch and Italian superyacht yards are consolidating vendor relationships around integrated motion-control packages.
- Marine Operators:Fleet managers drive retrofit demand as IMO stability mandates tighten roll-motion limits for in-service passenger vessels. Greek ferry operators are accelerating dry-dock upgrade schedules.
- Government Defense:Naval procurement programs impose survivability and signature requirements that constrain commercial technology adoption. National security classification limits vendor pool eligibility.
- Offshore Exploration Companies:Charter specifications for wind farm support vessels increasingly mandate active stabilization for technician transfer operations. UK and Norwegian offshore contractors are rewriting vessel hire agreements.
Contract volume flows through shipbuilders; retrofit activity is tilting toward marine operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing in China anchors raw material supply for electric gyroscope motors, while precision hydraulic actuator manufacturing concentrates in German and Japanese machine shops. Shipyard clusters in Italy, the Netherlands, Norway, and Greece drive finished system demand across recreational and commercial vessel segments.
Italy
Viareggio and Ancona superyacht builders are expanding dry-dock capacity for 50-meter-plus vessel upgrades, creating aftermarket installation demand. The EU F-Gas Regulation phases out hydrofluorocarbon refrigerants in hydraulic power unit cooling, accelerating electric gyroscope evaluations. Lombardy-based precision engineering firms supply bearing systems to Dutch and German stabilizer assemblers.
Netherlands
Dutch shipyards in Flevoland and South Holland specify compact electric gyroscopic units for 30-60 meter newbuilds where space constraints previously excluded stabilization. The EU Green Deal vessel incentives bundle battery-electric harbor craft retrofits with electric stabilizer installations. Rotterdam maritime equipment distributors consolidate vendor relationships around integrated motion-control packages.
Norway
North Sea wind farm support vessel operators require zero-speed stabilization for turbine technician transfers, opening volume demand previously served by anchor-dependent operations. The Norwegian Maritime Authority enforces stricter roll-motion limits for offshore personnel transfer vessels. Bergen and Stavanger shipyards are expanding fleet specifications as offshore wind installation activity intensifies.
Germany
German machine shops in Bavaria and Baden-Württemberg concentrate precision hydraulic actuator production, creating single-source vulnerability for fin-stabilizer arrays. The EU F-Gas Regulation raises cooling system complexity for hydraulic power units, prompting cargo vessel operators to accelerate electric alternatives. Hamburg shipyard procurement departments consolidate around turnkey seakeeping solution providers.
United States
The US Coast Guard enforces separate intact stability standards for domestic passenger vessels that limit certain interceptor configurations in shallow-draft operations. Florida and Pacific Northwest recreational boat builders specify compact gyroscopic units as permanent magnet motor advances shrink installation footprints. American shipyards face copper and rare earth magnet cost volatility tied to Chinese export quotas.
Marine Stabilizers Market Competitive Landscape
Global majors compete with regional champions across technology architecture, with vacuum-sealed flywheel specialists vying against hydraulic fin array fabricators for shipyard specification slots. The vendor base organizes around three strategic archetypes: compact electric gyroscope innovators, high-power hydraulic array builders, and integrated motion-control turnkey providers. Incumbent suppliers reconfigure manufacturing lines around compact flywheel assemblies while defending installed base relationships in cargo and naval segments. Competitive moves concentrate on manufacturing footprint compression and shipyard procurement consolidation.
Among US-based stabilization technology developers, Seakeeper occupies a position exemplifying compact electric gyroscope specialization for recreational craft. Quantum Marine Stabilizers represents the custom hydraulic array archetype serving megayacht specifications. SKF Group anchors the European supply chain tier through precision bearing technology that reduces gyroscopic friction losses. These three entities illustrate the technology bifurcation between electric compactness and hydraulic power density that defines current competitive positioning.
| Leading Market Players |
|---|
| Seakeeper |
| Quantum Marine Stabilizers |
| Naiad Dynamics |
| Sleipner |
| Fincantieri |
| SKF Group |
| Imtra |
| WESMAR Marine Electronics |
| Kongsberg Maritime |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation phaseout of hydrofluorocarbon refrigerants gates qualified supply for hydraulic stabilizer cooling systems, reserving premium-tier pricing access to vendors with CO2-based or water-glycol heat exchange certifications. Shipyards purchasing electric gyroscopic units command lower total cost of ownership quotes while hydraulic array buyers absorb compliance-driven engineering surcharges.
Pricing Analysis
Warranty and service bundling separates premium-tier quotations from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in the hydraulic segment is intensifying because EU refrigerant compliance raises cooling system complexity. Offshore wind vessel operators exhibit lowest price sensitivity due to zero-speed stabilization mandates, while Mediterranean harbor craft buyers prioritize capital expenditure minimization.
Supply Chain Analysis
Reverse-logistics flows for gyroscopic flywheel refurbishment center on Dutch and German service hubs, with worn bearing assemblies returning to Lombardy precision engineering firms for remanufacturing. Neodymium magnet processing concentrates in China, while precision hydraulic actuator production clusters in German and Japanese machine shops. Copper winding and rare earth magnet costs fluctuate with Chinese export quotas, creating single-source vulnerability for electric gyroscope motors. Distribution runs through Rotterdam maritime equipment distributors and Italian superyacht yard procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine stabilizers occupy a technology-transition phase as compact electric gyroscopic architectures displace hydraulic fin arrays across recreational and light-commercial vessel categories. Permanent magnet synchronous motor advances are compressing unit footprints below thresholds that previously excluded active stabilization.
For Market Incumbents: Anticipate margin compression in hydraulic fin-stabilizer arrays as EU F-Gas Regulation compliance costs accumulate. Prioritize backward integration into permanent magnet motor supply through captive sourcing agreements with Chinese rare earth processors. Defend installed base relationships in cargo and naval segments by accelerating electro-hydraulic hybrid certifications with Lloyd's Register and DNV.
For New Entrants and Emerging Players: Capture white-space demand in Norwegian offshore wind support vessels requiring zero-speed stabilization specifications. Target Italian superyacht refit yards in Viareggio and Ancona expanding dry-dock capacity for 50-meter-plus vessel upgrades. Pursue software-defined control system partnerships with Dutch shipyards consolidating vendor relationships around integrated motion-control packages.
For Investors and Strategic Acquirers: DNV type-approval timeline compression for novel interceptor geometries is the leading indicator that regulatory bottlenecks are easing for innovative architectures. Long-term viability favors turnkey seakeeping solution providers over discrete component vendors. Monitor Lloyd's Register certification queue lengths for electric gyroscopic units as inflection signal for manufacturing capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Shrinks gyroscopic unit footprint below 500 kilograms for 30-60 meter newbuild specifications. |
| CO2-Based Cooling System Transition | Secures EU F-Gas Regulation compliance for hydraulic power unit installations in German yards. |
| Digital Twin Control Convergence | Enables predictive roll cancellation through real-time sea state modeling fused with gyroscopic precession. |
| Zero-Speed Stabilization Certification | Unlocks Norwegian and UK offshore wind farm support vessel specifications for turbine technician transfers. |
| Turnkey Motion-Control Packaging | Consolidates shipyard procurement relationships around single-source accountability for ride quality. |
Research Methodology
Document review covered Lloyd's Register and DNV classification society rulebooks, IMO intact stability criteria amendments, EU F-Gas Regulation compliance guidance, and SEC filings from listed marine equipment suppliers, complemented by interviews with shipyard procurement directors, naval architects, stabilizer system engineers, and offshore vessel fleet managers. Secondary validation drew from customs trade data on bearing and magnet imports, shipyard order books, and offshore wind vessel charter specifications. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Installed base and newbuild penetration models produced volume and value trajectories across the projection horizon, with segmentation by product type, technology architecture, application category, and end-user procurement authority. CAGRs derived from regression analysis against vessel order flow, regulatory mandate implementation schedules, and technology substitution curves. Forecast inputs incorporated permanent magnet motor cost decline rates, hydraulic cooling system compliance cost inflation, and offshore wind installation activity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese rare earth export policy shifts, Lloyd's Register certification timeline variability, and offshore wind vessel specification evolution. Practitioners should monitor DNV type-approval queue lengths, EU Green Deal vessel incentive program allocations, and superyacht dry-dock capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Airbags Market
Marine
Tele-Operated Marine Drone Market
Marine
Europe Marine Communication Systems Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Fasteners Market
Marine
Marine and Marine Management Software Market
Marine
Marine Asset Integrity Services Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Ship/Boat Keel Market
Marine
Trim Tabs Market
Marine
Fishing Vessel Market
Marine
Asia-Pacific Electric Boat Market
Marine
India Boat Davits Market
Marine
Marine Chartplotter Market
Marine
Electric Outboard Engines Market
Marine
Sea Scooter Market