
 Synchronous Timing Belts Market | 2026-2036
Synchronous Timing Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Synchronous Timing Belts Market Analytics
China is reconfiguring its synchronous timing belt supply base through dedicated industrial zones in Jiangsu and Zhejiang provinces. Gates Corporation leverages captive rubber compounding facilities to sustain margin control across Asia-Pacific distribution. Continental AG anchors European OEM supply through specialized polyurethane formulations for electric vehicle camshaft drives. Tsubakimoto Chain Co competes in precision robotics applications with reinforced neoprene constructions for cleanroom environments.
Synchronous timing belts are toothed power transmission components manufactured from chloroprene rubber or thermoplastic polyurethane with embedded fiberglass or steel tensile cords, engineered to maintain precise phase relationships between crankshaft and camshaft or servo motor and load. Their primary purpose is eliminating slip in applications requiring exact positional accuracy across automotive engine timing, industrial positioning systems, and automated material handling. Closed loop belt configurations dominate automotive original equipment due to integrated tensioner compatibility and service life predictability, while open loop variants capture industrial retrofit demand where custom center distances prevail. Polyurethane materials command premium positioning in robotics and semiconductor automation for chemical resistance and low particulate generation, whereas neoprene formulations retain volume leadership in HVAC and general industrial machinery for cost-performance balance.
EPA tailpipe emissions rules and NHTSA fuel economy standards mandate friction reduction technologies that favor belt-driven accessory systems over traditional chain architectures in US vehicle programs. EMA and REACH frameworks in Europe enforce substance restrictions on chloroprene additives and require full material disclosure for aftermarket replacement belts entering EU distribution channels. ISO 1813 and JIS K 6323 establish tensile strength and tooth shear benchmarks that differentiate qualified suppliers from commodity traders in cross-border procurement. Stakeholders must monitor evolving electric vehicle platform architectures to determine whether integrated motor-transaxle designs eliminate traditional timing belt positions or create new e-axle reduction belt applications.
Market Dynamics
Electric vehicle platform architectures are eliminating traditional engine timing positions while simultaneously creating new e-axle reduction belt applications, forcing suppliers to pivot polyurethane formulation capabilities toward integrated motor-transaxle systems.
Growth Catalysts
- EPA Fuel Economy Standards:NHTSA Corporate Average Fuel Economy mandates drive friction-reduction requirements that favor belt-driven accessory architectures over chain drives in US vehicle programs.
- Robotics Manufacturing Clusters:China's Jiangsu and Zhejiang industrial zones concentrate precision automation demand requiring neoprene belts with reinforced tensile cords for cleanroom positioning systems.
- Thermoplastic Polyurethane Chemistry:Low-particulate generation properties enable semiconductor and pharmaceutical automation applications where chemical resistance and contamination control are non-negotiable.
Market Restraints
- Chloroprene Additive Restrictions:REACH substance restrictions on neoprene compounding chemicals create compliance friction for aftermarket belts entering EU distribution channels.
- Steel Cord Volatility:Embedded steel tensile element costs fluctuate with metallurgical commodity markets, compressing margin predictability for volume automotive contracts.
- Integrated E-Axle Designs:Electric vehicle motor-transaxle integration threatens to eliminate discrete timing belt positions entirely in next-generation platform architectures.
Strategic Opportunities
- Industrial Retrofit Channels:Open-loop belt configurations for custom center-distance machinery in Germany's automation corridor capture replacement demand outside OEM supply agreements.
- EU F-Gas Regulation Tailwinds:HVAC system efficiency mandates favor synchronous belt-driven compressor architectures over direct-drive alternatives in European climate equipment.
- 5G Infrastructure Deployment:Automated material handling systems for telecom equipment manufacturing create new precision positioning belt applications in Chinese and South Korean production facilities.
Industry Challenges
- ISO 1813 Certification Timelines:Tensile strength and tooth shear testing protocols create extended qualification periods that delay supplier entry into cross-border procurement channels.
- Legacy Chain Architecture Integration:Automotive engineering teams face reconfiguration complexity when retrofitting belt-driven systems into existing powertrain tooling and assembly line investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synchronous Timing Belts Market |
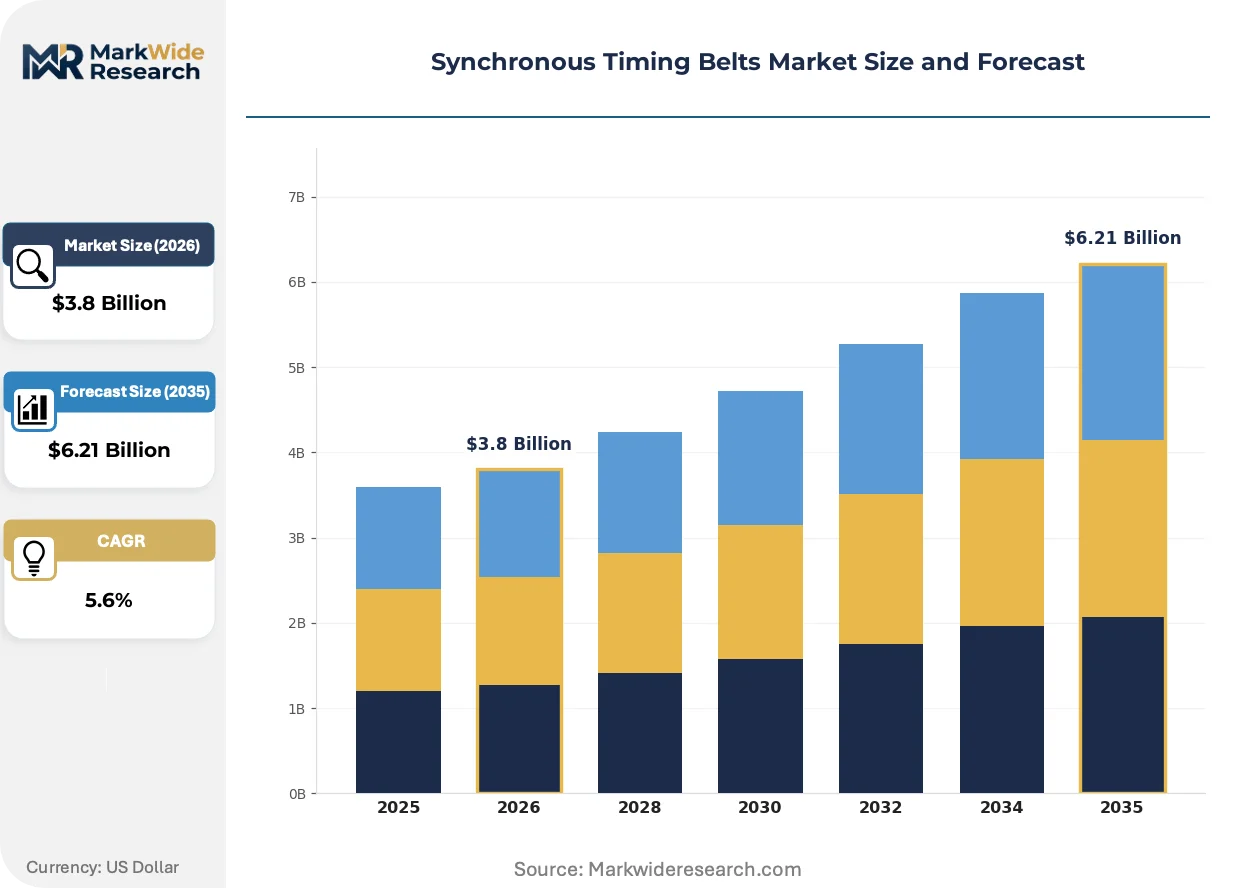
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Loop, Closed Loop, Synchronous Belt, Variable Speed Belt Material: Polyurethane, Neoprene, Nylon, Rubber End User: Automotive, Industrial Machinery, Robotics, HVAC Application: Conveyor Systems, Printing Machines, Textile Machinery, Packaging Equipment |
| Companies Covered | Dayco Products, Megadyne Group, Gates Corporation, Mitsuboshi Belting, Optibelt GmbH, Continental AG, Tsubakimoto Chain Co, Habasit, Bando Chemical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchronous Timing Belts Market Evolving Landscape
Digital twin simulation and predictive maintenance integration are compressing belt replacement cycles and reshaping how industrial buyers evaluate total cost of ownership across automotive and automation applications.
Carbon fiber tensile cord reinforcement is virtualizing traditional fiberglass-reinforced belt constructions in high-precision robotics applications. Semiconductor equipment manufacturers in Taiwan and South Korea specify carbon fiber for reduced elongation under dynamic load. This material shift is virtualizing the performance gap between standard industrial belts and precision-engineered alternatives, compressing mid-tier supplier margins.
EU F-Gas Regulation phase-down schedules mandate refrigerant containment improvements that favor synchronous belt-driven HVAC compressor architectures. Equipment OEMs in Germany and Italy redesign scroll compressor systems to eliminate shaft seal leakage points. The regulation most affects rooftop unit manufacturers serving commercial building retrofit markets across France and Spain.
Automotive service channel consolidation concentrates aftermarket belt procurement decisions into fewer national distributor networks. Independent repair shops in the United States increasingly source through consolidated parts platforms rather than traditional jobber relationships. This pattern is most visible in California and Texas where fleet maintenance contracts drive volume purchasing through centralized procurement systems.
Synchronous Timing Belts Market Segmentation
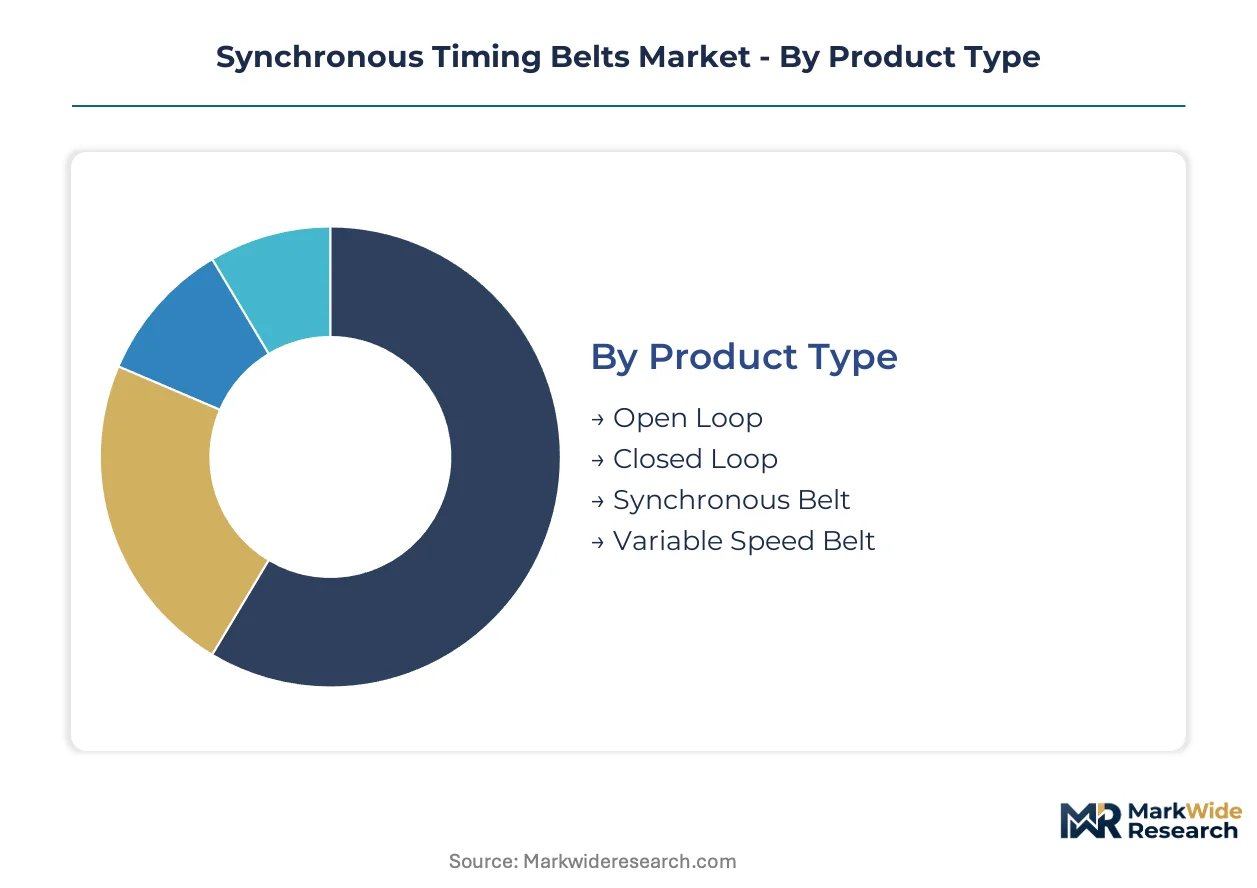
Synchronous timing belt demand fragments across precision requirements, chemical exposure profiles, and duty cycle intensities that resist one-size-fits-all specification. Each segment category reflects distinct procurement criteria that separate captive OEM supply from aftermarket replacement channels.
Product Type:
Use-case spectrum spans static engine timing installations through reconfigurable industrial retrofits where center distances vary by machine vintage.
- Closed Loop:Factory-terminated endless configurations integrate tensioner systems for predictable service intervals in automotive camshaft drives. EPA fuel economy mandates favor these architectures for friction reduction in US vehicle programs. Established volume favors closed loop; emerging adoption favors open loop.
- Open Loop:Cut-to-length variants enable custom center distances in Germany's industrial automation corridor where legacy machinery requires field-fitted replacement. Procurement concentrates through distributor networks serving retrofit contractors outside OEM supply agreements.
- Synchronous Belt:Standard toothed configurations serve general industrial positioning with fiberglass tensile cord reinforcement. ISO 1813 certification differentiates qualified suppliers from commodity traders in cross-border procurement.
- Variable Speed Belt:Cogged designs accommodate sheave-adjustable ratios in agricultural equipment and material handling systems where fixed ratios prove uneconomical.
Established volume favors closed loop; emerging adoption favors open loop.
Material:
Cost tier separation runs from commodity neoprene formulations through premium polyurethane chemistry demanded by contamination-sensitive environments.
- Polyurethane:Thermoplastic construction generates minimal particulate in semiconductor cleanrooms across Taiwan and South Korea. REACH substance disclosure requirements favor these formulations for EU pharmaceutical automation where chloroprene additives face restriction. Carbon fiber reinforcement variants are displacing fiberglass in precision robotics.
- Neoprene:Chloroprene rubber dominates HVAC compressor drives and general industrial machinery for cost-performance balance. China's Jiangsu and Zhejiang manufacturing clusters specify neoprene with steel tensile cords for automated material handling.
- Nylon:Reinforced facing materials reduce tooth wear in high-cycle packaging equipment where abrasive dust loads accelerate belt degradation.
- Rubber:General-purpose formulations serve price-sensitive conveyor applications in emerging manufacturing economies where duty cycles permit shorter replacement intervals.
Volume leadership resides with neoprene; polyurethane climbs the fastest on precision automation demand.
End User:
Customer type segmentation separates specification-driven OEM procurement from maintenance-driven aftermarket replacement with diverging margin structures.
- Automotive:Powertrain timing systems face platform architecture disruption as electric vehicle motor-transaxle integration eliminates traditional camshaft positions. NHTSA Corporate Average Fuel Economy standards sustain belt-driven accessory demand in hybrid architectures.
- Industrial Machinery:Factory automation in China's robotics manufacturing hubs specifies reinforced constructions for cleanroom positioning systems with 24-hour duty cycles.
- Robotics:Six-axis articulated arms and Cartesian gantries demand low-elongation carbon fiber reinforcement for repeatability in Taiwanese semiconductor equipment.
- HVAC:EU F-Gas Regulation phase-down schedules favor synchronous belt-driven scroll compressors with reduced shaft seal leakage points in German and Italian rooftop unit manufacturing.
Automotive retains volume concentration; robotics gains share fastest on precision manufacturing expansion.
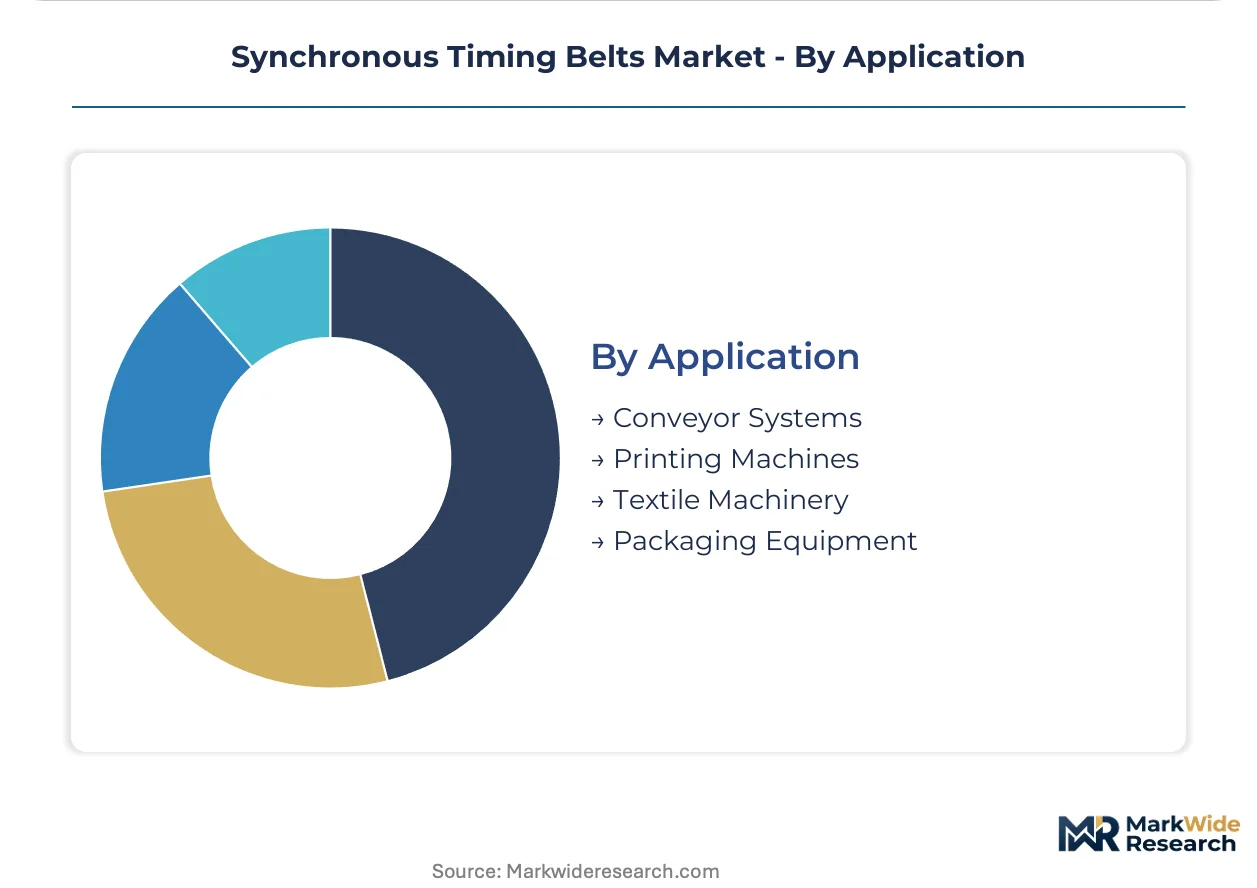
Application:
Application segmentation tracks machinery duty cycles and contamination exposure that determine belt construction specifications and replacement frequency.
- Conveyor Systems:Long-center-distance bulk material handling in automated warehouses specifies heavy-duty constructions with steel tensile cords for load capacity.
- Printing Machines:Registration accuracy demands in web offset and digital presses favor polyurethane with minimal stretch characteristics for color-to-color alignment.
- Textile Machinery:High-speed spindles and loom drives in South Korean production facilities require oil-resistant neoprene formulations for lubricant exposure tolerance.
- Packaging Equipment:Intermittent motion cam drives and continuous flow wrappers specify reinforced tooth profiles for shock loading in food and beverage automation lines.
Conveyor systems anchor replacement volume; packaging equipment shows steepest expansion trajectory on e-commerce fulfillment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubber compounding capacity concentrates in Germany's industrial belt and China's eastern manufacturing corridor, with polyurethane formulation expertise clustering around Taiwanese semiconductor equipment suppliers. This geographic specialization shapes procurement patterns across automotive, robotics, and HVAC end markets.
Germany
EPA-aligned NHTSA fuel economy standards drive belt-driven accessory architectures in US-bound vehicle exports from Bavarian powertrain plants. EU F-Gas Regulation phase-down mandates favor synchronous belt-driven HVAC compressors in rooftop unit manufacturing across Baden-Württemberg. Stuttgart's automation corridor concentrates precision polyurethane demand for electric vehicle camshaft drives.
China
Jiangsu and Zhejiang industrial zones specify neoprene belts with steel tensile cords for 24-hour cleanroom robotics manufacturing. GB standards enforcement differentiates qualified suppliers from commodity traders in cross-border procurement. Suzhou's semiconductor equipment cluster demands low-particulate polyurethane formulations for contamination-sensitive automation.
United States
NHTSA Corporate Average Fuel Economy mandates sustain belt-driven hybrid powertrain demand across Michigan and Ohio automotive corridors. EPA tailpipe emissions rules favor friction-reduction technologies in accessory drive systems. California's fleet maintenance consolidation drives centralized aftermarket procurement through distributor networks.
Japan
JIS K 6323 tensile strength benchmarks enforce quality differentiation in precision robotics applications for Tokyo and Osaka manufacturing hubs. METI industrial automation incentives accelerate carbon fiber reinforced belt adoption in six-axis articulated arm production. Nagoya's automotive belt suppliers pivot polyurethane capabilities toward integrated motor-transaxle architectures.
South Korea
MFDS pharmaceutical automation standards favor thermoplastic polyurethane belts with minimal particulate generation in Seoul-area cleanroom facilities. 5G infrastructure deployment creates precision positioning belt demand in Busan-Ulsan telecom equipment manufacturing. Daegu-Gyeongbuk textile machinery clusters specify oil-resistant neoprene for high-speed spindle applications.
Synchronous Timing Belts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying formulated materials and tensioner subassemblies. The vendor base separates into three archetypes: captive rubber compounders controlling margin through backward integration, precision polyurethane formulators serving contamination-sensitive automation, and volume neoprene producers competing on cost-performance balance. Consolidation pressures concentrate among automotive OEM supply agreements, while fragmentation persists in industrial retrofit channels. Strategic moves center on geographic expansion into China's robotics manufacturing clusters and portfolio diversification toward e-axle reduction belt applications.
Among Japanese belt manufacturers, Mitsuboshi Belting and Tsubakimoto Chain Co occupy positions within the precision automation tier, exemplifying carbon fiber reinforcement capabilities for semiconductor equipment. Continental AG anchors European OEM supply through specialized polyurethane formulations. These three represent distinct competitive positioning: Mitsuboshi Belting exemplifies scale-driven automotive volume, Tsubakimoto Chain Co sits within the precision robotics specialization, and Continental AG represents the integrated platform supplier archetype serving electric vehicle powertrain transitions.
| Leading Market Players |
|---|
| Dayco Products |
| Megadyne Group |
| Gates Corporation |
| Mitsuboshi Belting |
| Optibelt GmbH |
| Continental AG |
| Tsubakimoto Chain Co |
| Habasit |
| Bando Chemical Industries |
| Others |
Value Network & Pricing Analysis
Germany's captive polyurethane formulation facilities anchor margin capture for precision automotive and robotics tiers, concentrating pricing power among compounders with backward-integrated rubber processing capabilities. This upstream concentration funnels value toward suppliers serving EPA-aligned NHTSA fuel economy mandates and EU F-Gas Regulation compliance tiers, while commodity neoprene producers compete on cost-performance balance in HVAC and general industrial channels.
Pricing Analysis
EPA fuel economy standards and EU REACH substance restrictions dictate the pricing tier structure across synchronous timing belt procurement. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber-reinforced polyurethane for semiconductor cleanrooms from fiberglass-cord neoprene for HVAC compressors and commodity rubber for conveyor applications. Cost compression in standard-tier neoprene formulations is intensifying because steel cord volatility feeds directly into volume automotive contract margins. Fleet maintenance consolidators in California and Texas exhibit highest price sensitivity through centralized distributor procurement, while semiconductor equipment OEMs in Taiwan and South Korea show lowest sensitivity for contamination-specified polyurethane grades.
Supply Chain Analysis
Chloroprene rubber feedstock draws from Germany's industrial belt and China's eastern manufacturing corridor, with thermoplastic polyurethane resin anchored in Taiwanese semiconductor equipment supplier networks. Raw material dependencies center on metallurgical-grade steel for tensile cords, fiberglass yarn for standard reinforcement, and carbon fiber tow for precision robotics applications. Single-source vulnerability concentrates in carbon fiber supply for semiconductor-grade belts, where qualified alternative sources remain limited. Distribution runs through national distributor networks serving automotive aftermarket channels in the United States and specialized industrial retrofit contractors in Germany's automation corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform economics are eliminating discrete timing positions while creating e-axle reduction belt applications, representing an interoperability inflection that rewards suppliers with integrated motor-transaxle formulation capabilities.
For Market Incumbents: Harden polyurethane formulation capabilities for integrated e-axle architectures before electric vehicle platform standardization locks in supplier relationships. Deepen backward integration into captive rubber compounding to defend margin position against steel cord commodity volatility. Prioritize ISO 1813 certification maintenance to sustain cross-border procurement qualification as REACH substance restrictions tighten on chloroprene additives.
For New Entrants and Emerging Players: Establish a beachhead in Germany's industrial automation corridor open-loop retrofit channel, where custom center-distance machinery escapes captive OEM supply agreements. Target carbon fiber-reinforced polyurethane for Taiwanese semiconductor equipment manufacturers facing qualified supplier shortages. Lead with digital twin-enabled predictive maintenance bundling to differentiate against incumbent pure-component pricing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision polyurethane formulators serving contamination-sensitive automation in South Korea and Taiwan. Five-to-ten year viability hinges on electric vehicle platform architecture stabilization determining whether e-axle integration creates new belt positions or eliminates traditional timing applications entirely. Monitor JIS K 6323 and GB standards enforcement timelines as inflection indicators for supplier qualification barriers tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Gates Corporation's captive facilities in Asia-Pacific sustain margin control against commodity chloroprene price swings. |
| Carbon Fiber Reinforcement Scale-Up | Taiwanese semiconductor equipment OEMs specify reduced-elongation belts for six-axis robotic repeatability requirements. |
| E-Axle Reduction Belt Development | Continental AG anchors European OEM supply through polyurethane formulations for integrated motor-transaxle systems. |
| Cleanroom Certification Investment | MFDS pharmaceutical automation standards in Seoul-area facilities favor low-particulate thermoplastic polyurethane constructions. |
| Industrial Retrofit Channel Expansion | Open-loop belt configurations capture replacement demand outside OEM agreements in Germany's automation corridor. |
Research Methodology
The analysis maps closed-loop automotive timing systems, open-loop industrial retrofits, and variable-speed agricultural applications, each validated through procurement directors at Tier 1 automotive suppliers, maintenance engineers at German automation OEMs, and distribution channel managers serving HVAC equipment manufacturers. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed belt manufacturers, customs trade data for rubber and steel cord imports, EPA fuel economy compliance reports, and REACH substance registration databases. Bottom-up demand modeling across end-use segments triangulates against top-down market sizing from production volume data.
Assumption sets held electric vehicle platform architecture evolution and regulatory enforcement timelines fixed at baseline trajectories while varying steel cord commodity price bands and carbon fiber supply availability scenarios across the projection horizon. Segmentation dimensions modeled include product type configuration, material chemistry tier, end-user industry vertical, and regional production cluster concentration. CAGRs derive from elasticity-adjusted demand curves incorporating duty cycle intensity and replacement frequency differentials by application, with EPA tailpipe emissions rule stringency and EU F-Gas Regulation phase-down schedules as primary industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, industrial capital expenditure cycles, or steel metallurgical commodity indices would shift the trajectory. Forecasts reflect documented assumptions about electric vehicle platform standardization timing and regulatory enforcement consistency. Cross-checking against IHS Markit vehicle production databases and Cefic chemical industry output benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Power Liftgate Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Automotive Ignition Coil Market