
 US Tanker Truck Market | 2026-2036
US Tanker Truck Market Size, Share, and Industry Trends Forecast 2026-2036
US Tanker Truck Market Insights
Single-source fleet procurement is rebalancing toward multi-source contracting across the US tanker truck sector. Kenan Advantage Group leverages its national terminal network to sustain bulk liquid coverage. Quality Carriers anchors chemical transport through specialized tank specifications. Trimac Transportation competes on dedicated contract carriage for industrial shippers.
A tanker truck is a motor vehicle designed with cylindrical or elliptical tanks mounted to its chassis, constructed from aluminum, stainless steel, or carbon steel with capacities ranging from 1,000 to 11,600 gallons, engineered to transport liquids, gases, or dry bulk commodities under pressure or atmospheric conditions. Its primary commercial purpose is to move petroleum, chemicals, food-grade liquids, and waste materials from production facilities to distribution terminals or end-use locations. Petroleum tankers dominate product-type revenue given steady refinery throughput volumes. Chemical tankers command premium positioning due to specialized cleaning protocols and hazmat compliance requirements. Large and extra-large size categories concentrate fleet investment where route density and payload optimization improve per-mile economics.
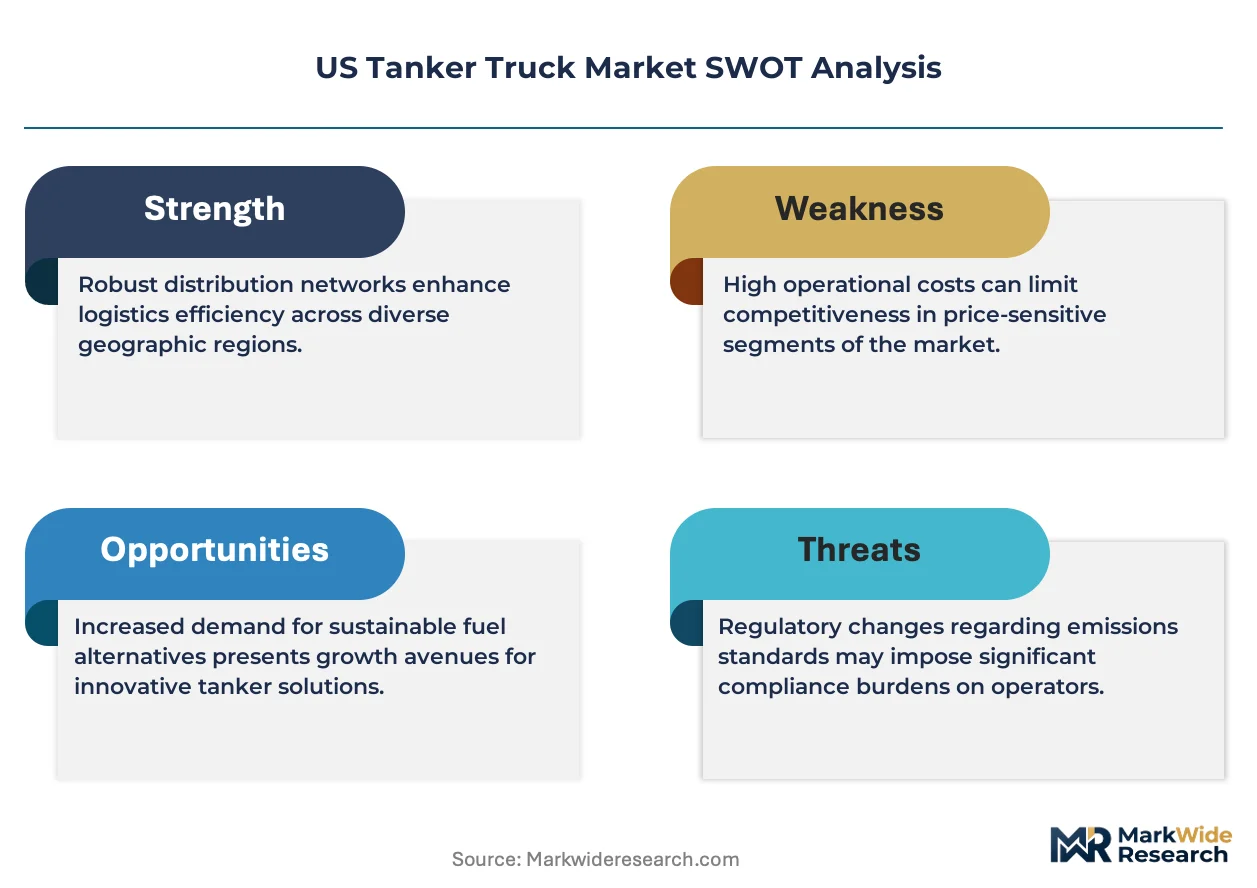
Federal Motor Carrier Safety Administration hours-of-service rules and DOT hazmat regulations shape driver availability and tank certification costs across interstate operations. EPA greenhouse gas standards for heavy-duty vehicles push fleet operators toward alternative fuel powertrains and aerodynamic tank designs. NHTSA vehicle safety mandates influence rollover protection and braking system investments. Stakeholders must weigh equipment replacement cycles against evolving compliance thresholds and fuel-type transition pathways.
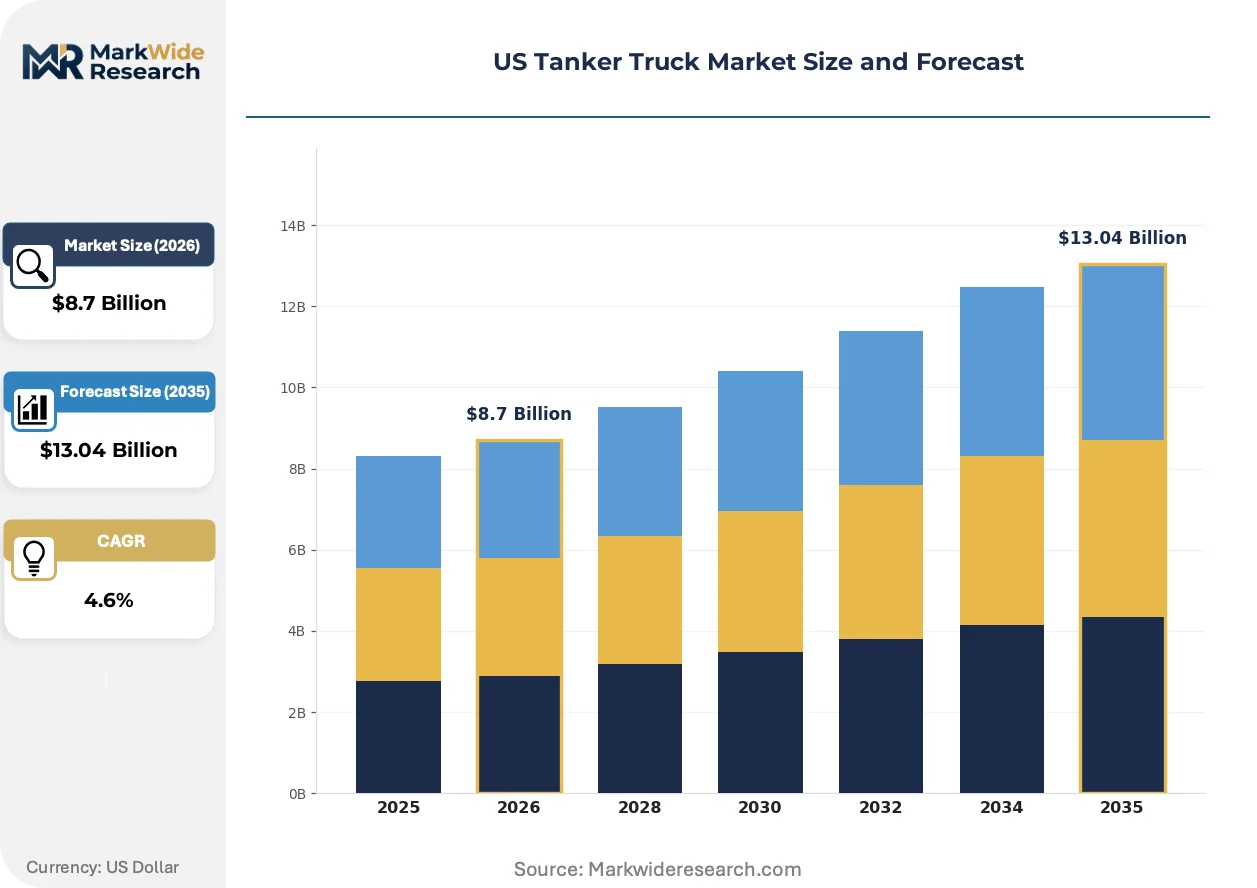
Market Dynamics
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are compressing fleet replacement cycles while simultaneously forcing capital reallocation toward alternative fuel powertrains and aerodynamic tank configurations across the US tanker truck sector.
Growth Catalysts
- Petrochemical corridor expansion:Texas Gulf Coast ethylene crackers and derivative plants are generating contracted tanker demand for feedstock and finished chemical transport. Midstream operators are securing dedicated fleet capacity along the Houston Ship Channel.
- Farm-to-terminal fuel logistics:Midwest agricultural fuel distribution networks require seasonal surge capacity for ethanol blending and diesel delivery to rural co-ops. Terminal operators are expanding storage-linked hauling contracts.
- DOT hazmat specialization premiums:Chemical manufacturing fleets pay elevated rates for tankers meeting MC 407 specification and CGA pressure vessel standards. Specialized cleaning protocols create switching costs that lock in carrier relationships.
Market Restraints
- Aluminum and stainless steel input volatility:Tank fabrication costs swing with commodity exchange pricing for 304-grade stainless and marine aluminum alloys. Fleet operators delay new builds during raw material spikes.
- Driver pool concentration risk:FMCSA hours-of-service rules and hazmat endorsement requirements restrict eligible labor supply to specific metropolitan training centers. Rural routes face persistent capacity gaps.
- Compressed natural gas infrastructure gaps:CNG-powered tanker adoption stalls outside California and Texas corridor networks due to sparse refueling station density. ROI calculations assume subsidized station buildouts that lag deployment schedules.
Strategic Opportunities
- California LCFS credit monetization:Fleet operators running renewable natural gas or battery-electric tankers generate tradable Low Carbon Fuel Standard credits. Early movers capture credit price premiums before compliance obligation saturation.
- Food-grade liquid specialization:Dairy processors and edible oil refiners seek segregated tank fleets with kosher and organic certifications. This segment commands rate premiums above petroleum baseline economics.
- Telematics and predictive maintenance convergence:IoT tank monitoring systems combined with AI-driven component failure prediction reduce unplanned downtime. Integrated platforms differentiate regional carriers against asset-heavy incumbents.
Industry Challenges
- Hazmat endorsement training pipeline:TSA security threat assessments and CDL tank vehicle certification create 6-12 week onboarding delays. Fleet managers compete for instructors at limited commercial driving academies.
- Legacy dispatch system integration:Tank-level sensors and automated billing platforms require API connectivity with decades-old transportation management software. Mid-size carriers face IT contractor scarcity for custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tanker Truck Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Chemical, Petroleum, Liquid Waste End User: Food & Beverage, Oil & Gas, Agriculture, Chemical Manufacturing Size: Small, Medium, Large, Extra Large Fuel Type: Diesel, Gasoline, Alternative Fuels, Biofuels |
| Companies Covered | Kenan Advantage Group, Quality Carriers, Trimac Transportation, Foodliner/Quest Liner, Heniff Transportation Systems, Martin Transport, Groendyke Transport, Superior Bulk Logistics, Eagle Transport, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tanker Truck Market Trends and Innovations
Digital freight matching platforms and automated tank cleaning systems are compressing asset utilization cycles while simultaneously elevating service expectations across the US tanker truck market.
Composite tank technology utilizing carbon fiber reinforced polymer liners with aluminum exoskeletons is unifying payload maximization with corrosion resistance for chemical transport. Specialty chemical shippers in the Gulf Coast region are piloting these configurations for high-purity solvent delivery. This unifying architecture is enabling 15% weight reduction against conventional stainless builds while maintaining DOT 407 compliance, compressing total cost of ownership calculations for dedicated contract carriage.
NHTSA's updated rear underride guard standards and automatic emergency braking mandates for heavy commercial vehicles are accelerating collision avoidance system adoption. Fleet safety departments must retrofit existing tractors or accelerate replacement schedules to meet compliance deadlines. Chemical tanker segments face the steepest cost impact given tractor-trailer integration complexity and extended vehicle lifecycles in hazmat service.
Shippers are consolidating spot market exposure into multi-year dedicated capacity agreements with guaranteed volume floors. Food-grade and chemical verticals are displacing transactional broker relationships with direct carrier contracts bearing performance SLAs. This restructuring is most visible across Midwest agricultural fuel networks where co-op buying groups negotiate collective hauling arrangements.
US Tanker Truck Market Segmentation
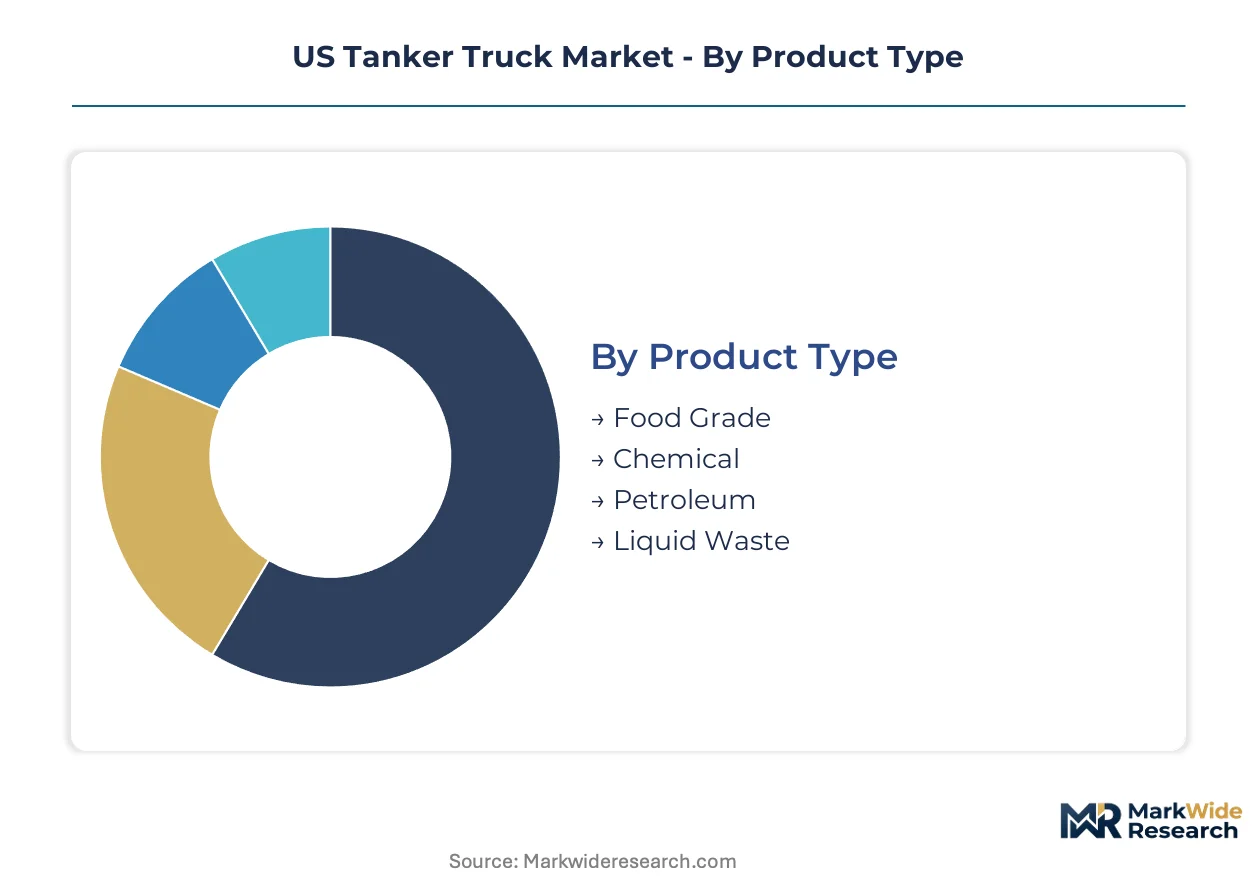
US tanker truck segmentation reveals distinct equipment specifications and compliance requirements that reshape procurement patterns across four critical dimensions. Fleet operators prioritize tank material compatibility and capacity optimization when matching assets to specific liquid cargo categories and regional route densities.
Product Type:
Buyer decisions pivot on cargo compatibility requirements and cleaning protocol complexity, with hazmat certification tiers driving contract rate differentials.
- Petroleum:Aluminum and carbon steel tank construction dominates refinery-to-terminal movements. Demand clusters along Texas Gulf Coast petrochemical corridors where midstream operators secure dedicated capacity for gasoline, diesel, and jet fuel distribution. Steady throughput volumes sustain this segment's revenue concentration despite EPA emissions compliance pressures on tractor replacement cycles.
- Chemical:Stainless steel MC 407 specification tanks with specialized linings handle corrosive solvents and industrial feedstocks. Gulf Coast ethylene crackers and derivative plants generate contracted demand where CGA pressure vessel standards and dedicated cleaning protocols create carrier switching costs. Premium rate structures reflect hazmat endorsement scarcity and tank certification maintenance.
- Food Grade:Segregated kosher and organic-certified fleets serve dairy processors and edible oil refiners with stainless steel construction and sanitized loading protocols.
- Liquid Waste:Vacuum-equipped tankers with corrosion-resistant linings transport industrial effluent and municipal sludge under EPA discharge regulations.
Petroleum leads on scale; chemical leads on momentum.
End User:
Volume concentration and seasonality patterns determine fleet deployment strategies, with agricultural networks requiring surge capacity that chemical manufacturing cannot match.
- Oil & Gas:Integrated majors and independent refiners contract dedicated capacity for crude gathering and finished product delivery. Pipeline terminal connections in Houston and Corpus Christi anchor route density optimization for large-capacity tankers.
- Chemical Manufacturing:Specialty chemical producers demand spec-compliant fleets with documented chain-of-custody protocols. Gulf Coast petrochemical complexes prioritize carriers with terminal infrastructure and rapid tank turnaround capabilities.
- Agriculture:Midwest ethanol blending operations and rural co-op diesel distribution require seasonal surge capacity with flexible dispatch scheduling.
- Food & Beverage:Edible oil refiners and dairy processors seek temperature-controlled transport with allergen segregation certifications.
Oil & gas dominates absolute volume; agriculture shows the steepest expansion trajectory during planting and harvest windows.
Size:
Payload economics and route infrastructure constraints dictate capacity selection, with bridge formula compliance and terminal turnaround times shaping optimal configurations.
- Large:7,000-9,000 gallon configurations balance weight distribution with terminal unloading efficiency. Interstate corridors and high-volume petrochemical routes favor this category where per-mile economics improve with payload maximization.
- Extra Large:9,000-11,600 gallon tanks exploit route density on dedicated contract lanes with minimal deadhead. Long-haul chemical transport and refined product movements between major hubs deploy these assets where weight restrictions permit.
- Medium:4,000-7,000 gallon capacity serves regional distribution and urban delivery constraints.
- Small:1,000-4,000 gallon tanks access confined terminals and last-mile fuel delivery to remote agricultural cooperatives.
Extra large captures margin expansion; large defends volume leadership.
Fuel Type:
Total cost of ownership calculations increasingly incorporate regulatory credit values and infrastructure availability rather than fuel price alone.
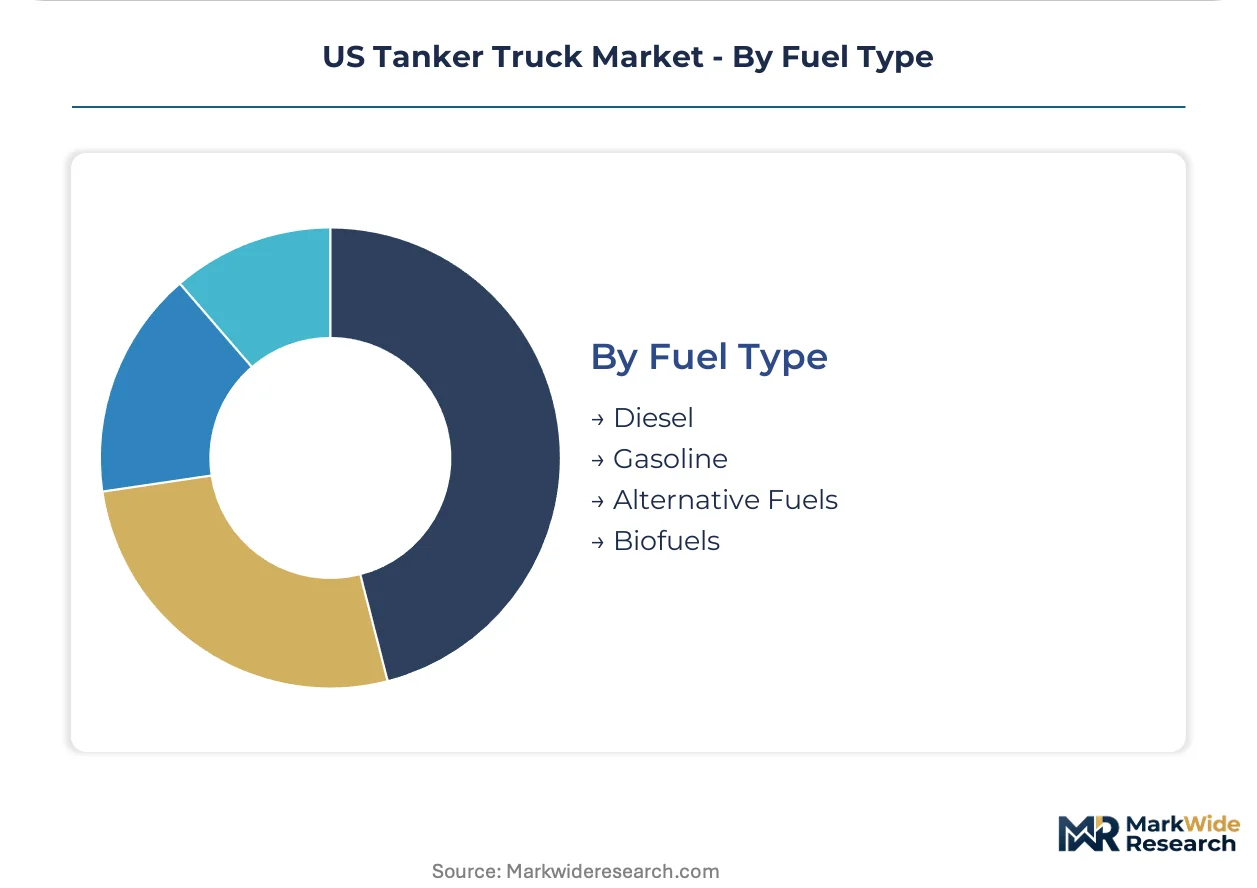
- Diesel:Proven powertrain reliability sustains fleet dominance despite EPA Phase 3 greenhouse gas standards compressing replacement cycles. Established service networks and driver familiarity maintain procurement preference where alternative fuel infrastructure remains sparse.
- Alternative Fuels:Compressed natural gas and renewable natural gas powertrains generate California LCFS credit monetization opportunities. Corridor deployment concentrates in Texas and California networks where station density supports route planning.
- Biofuels:Biodiesel blends and renewable diesel offer drop-in compliance with existing engine platforms.
- Gasoline:Light-duty and medium-duty tanker applications in urban delivery routes.
Diesel retains installed base dominance; alternative fuels gain share fastest in credit-eligible corridor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast petrochemical corridor anchors national tanker truck demand through ethylene cracker expansions and derivative plant construction. EPA Phase 3 greenhouse gas standards and DOT hazmat enforcement vary across state jurisdictions, reshaping fleet deployment patterns.
Texas Gulf Coast
Houston Ship Channel terminal complexes and Corpus Christi crude export facilities drive contracted capacity demand for petroleum and chemical transport. TCEQ air quality regulations and EPA regional office enforcement shape emissions compliance investments. Port of Houston petrochemical clusters anchor dedicated fleet agreements with midstream operators securing feedstock logistics.
Midwest Agricultural Belt
Iowa and Illinois ethanol blending terminals and rural co-op diesel distribution networks require seasonal surge capacity during planting and harvest windows. FMCSA hours-of-service enforcement across interstate corridors limits driver availability for agricultural fuel logistics. Chicago-area terminal operators negotiate collective hauling arrangements with co-op buying groups.
California Central Valley
CARB Low Carbon Fuel Standard credit markets incentivize renewable natural gas and battery-electric tanker deployments for food-grade liquid transport. Central Valley dairy processors and edible oil refiners seek segregated kosher-certified fleets. Fresno and Modesto processing clusters anchor temperature-controlled distribution contracts.
Pennsylvania-Ohio-West Virginia
Appalachian shale gas liquids and NGL fractionation plants generate demand for pressurized tanker capacity along the Ohio River corridor. Pennsylvania DEP spill prevention regulations and Ohio EPA transport permits shape hazmat routing protocols. Pittsburgh-area petrochemical renaissance projects anchor midstream infrastructure investments.
Louisiana Gulf Coast
Baton Rouge and Lake Charles refinery complexes sustain large-capacity tanker demand for refined product distribution to Mississippi River barge terminals. LDEQ environmental compliance requirements and Coast Guard tank vessel inspection protocols elevate carrier certification standards. Mississippi River chemical corridor activity concentrates fleet investment in dedicated contract carriage.
US Tanker Truck Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized chemical and food-grade certifications. The market structure concentrates around asset-heavy incumbents with terminal infrastructure advantages and regional specialists with flexible dispatch capabilities. Three archetypes dominate: national network operators with integrated terminal assets, chemical specialists with MC 407 specification fleets, and agricultural fuel distributors with seasonal surge capacity. Competitive dynamics center on dedicated contract carriage agreements and multi-year capacity commitments displacing spot market exposure.
Among national-scale carriers, Kenan Advantage Group exemplifies network-density positioning through terminal infrastructure coverage. Quality Carriers and Trimac Transportation occupy specialized tiers within chemical and industrial contract carriage segments. These three entities represent distinct strategic archetypes: integrated bulk liquid coverage, hazmat specification leadership, and dedicated industrial shipper relationships respectively.
| Leading Market Players |
|---|
| Kenan Advantage Group |
| Quality Carriers |
| Trimac Transportation |
| Foodliner/Quest Liner |
| Heniff Transportation Systems |
| Martin Transport |
| Groendyke Transport |
| Superior Bulk Logistics |
| Eagle Transport |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange aluminum and 304-grade stainless steel price indices cascade through tank fabrication costs into three-tier pricing structures across premium, standard, and economy levels. Fleet operators pass commodity volatility to chemical shippers through fuel surcharges and tank certification fees while agricultural fuel distributors absorb margin compression during planting season surges.
Pricing Analysis
Input-cost pass-through dominates contract negotiations, with 304-grade stainless and marine aluminum alloy fluctuations feeding directly into MC 407 specification tank premiums. Price differentiation hinges on hazmat certification tiers and dedicated cleaning protocol investments, separating chemical specialists from petroleum haulers. Pricing pressure stems from EPA Phase 3 compliance costs compressing tractor replacement cycles. Agricultural co-ops exhibit highest price sensitivity during ethanol blending windows, while Gulf Coast petrochemical majors accept premium rates for chain-of-custody documentation.
Supply Chain Analysis
Reverse-logistics flows for tank refurbishment and pressure vessel recertification anchor aftermarket value pools in Ohio and Pennsylvania fabrication centers. Primary tank manufacturing concentrates in Ohio, Texas, and Wisconsin where specialty welding labor pools support MC 407 and DOT 407 compliance. Raw material sourcing draws from domestic aluminum smelters and imported stainless steel coils. Single-source vulnerability sits with specialized valve and pumping equipment from German and Japanese suppliers. Distribution runs through terminal-integrated carriers with dedicated contract carriage agreements displacing spot market exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where chemical manufacturing demand shifts toward kosher-certified and organic-segregated tank specifications. Premium fleet investments now outperform commodity petroleum haulers on contract duration and rate stability.
For Market Incumbents: Anticipate EPA Phase 3 tractor replacement deadlines compressing asset utilization cycles. Defend position by accelerating terminal infrastructure deployment along Texas Gulf Coast ethylene corridor expansions. Secure backward integration into tank refurbishment capabilities to capture aftermarket revenue streams. Invest in automated tank cleaning systems to reduce turnaround times and lock in chemical shipper relationships. For New Entrants and Emerging Players: The premium-to-economy price-point gap in food-grade liquid transport offers white-space entry. Target California Central Valley dairy processors seeking segregated kosher and organic-certified capacity. Pursue Midwest agricultural fuel distributors with seasonal surge flexibility as the most penetrable segment. Lead with telematics-enabled predictive maintenance platforms to differentiate against asset-heavy incumbents on service reliability metrics. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding MC 407 chemical certification and flexible dispatch capabilities. Long-term viability favors carriers with terminal-integrated networks over pure asset-light brokers. Monitor California LCFS credit price trajectories as inflection indicators for renewable natural gas tanker deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Expansion | Houston Ship Channel terminal networks capture dedicated contract carriage agreements with ethylene cracker operators. |
| MC 407 Certification Investment | Specialized tank specifications create switching costs that lock in chemical manufacturing relationships. |
| Renewable Natural Gas Fleet Conversion | California LCFS credit monetization improves total cost of ownership in Central Valley food-grade corridors. |
| Telematics Platform Integration | IoT tank monitoring and AI-driven maintenance prediction reduce unplanned downtime for regional carriers. |
| Automated Tank Cleaning Deployment | Rapid turnaround capabilities differentiate service offerings for Gulf Coast petrochemical shippers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet operations directors at national tanker carriers, procurement leads at Gulf Coast petrochemical complexes, terminal managers along the Houston Ship Channel, FMCSA enforcement officers, and EPA regional compliance specialists. Secondary validation drew from DOT hazmat incident databases, FMCSA carrier safety measurement system data, EPA greenhouse gas compliance filings, and American Trucking Associations fleet statistics. Bottom-up equipment deployment models triangulated against top-down petrochemical throughput projections.
Historical reference periods anchored volume and value forecasts across the analysis window. The analytical framework modeled segmentation dimensions including tank material specification, cargo category, fleet size tier, powertrain fuel type, and regional corridor density. CAGRs derived from equipment replacement cycle analysis and contracted capacity growth trajectories. Industry-specific inputs incorporated EPA Phase 3 compliance cost curves and California LCFS credit market pricing dynamics.
Caveats apply where aluminum and stainless steel commodity volatility, FMCSA hours-of-service enforcement shifts, or CNG infrastructure buildout delays could materially shift the outlook. Practitioners should monitor EPA Phase 3 implementation timing and renewable natural gas station deployment schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Flatbed Truck Market