
 Marine Fin Stabilizer Market | 2026-2036
Marine Fin Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fin Stabilizer Market Analysis
Superyacht construction is broadening as a share of marine fin stabilizer procurement, displacing some commercial vessel retrofit activity. Quantum Marine Stabilizers leverages its Florida-based engineering base to dominate North American luxury yacht fit-outs. SKF Group anchors European supply through its bearing and motion control integration. Wärtsilä Corporation extends its propulsion portfolio into stabilizer systems for large commercial hulls.
Marine fin stabilizers are hydrodynamic appendages mounted bilaterally on a hull to generate counter-rolling moments through active angle adjustment or passive flow dynamics, typically constructed from high-strength nickel-aluminum bronze or composite matrices to resist cavitation and biofouling in continuous seawater immersion. Active fin systems lead technology segmentation due to real-time sensor feedback and hydraulic actuation precision, while hybrid configurations represent the fastest-growing category as builders seek fuel efficiency gains from reduced power draw. New build installation dominates volume, though retrofit demand for integrated systems strengthens as aging fleets face IMO stability compliance deadlines.
The International Maritime Organization stability criteria and EU MDR framework shape product certification timelines and material traceability requirements for European yards. The US Coast Guard enforces supplemental rules for passenger vessel roll reduction that filter down to stabilizer specification sheets. Stakeholders must monitor pending amendments to ISO 12217 stability standards and assess whether control system software will face cybersecurity disclosure mandates.
Market Dynamics
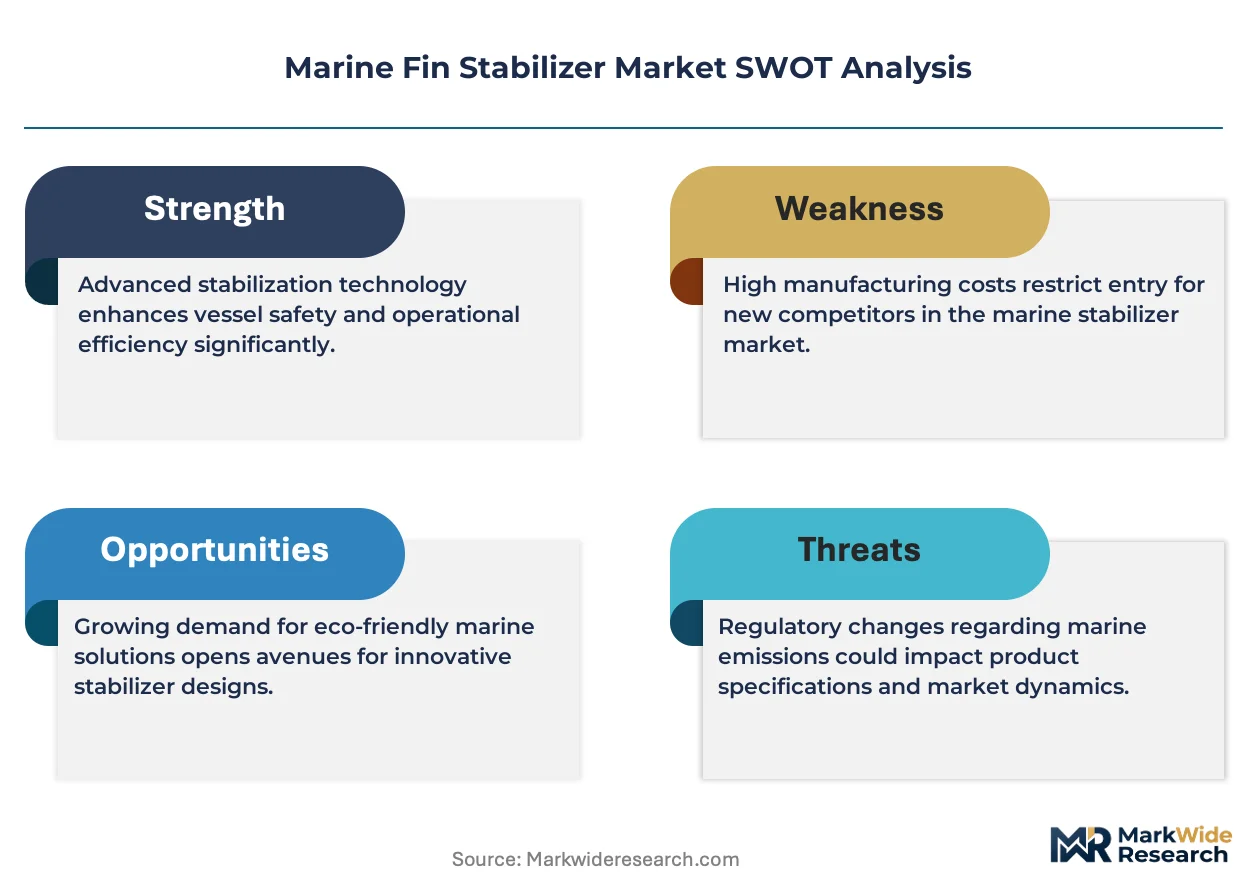
Active fin stabilization systems are compressing passive alternatives as IMO stability mandates tighten and superyacht builders demand real-time roll compensation. Hydraulic actuation precision now determines competitive positioning in premium hull fit-outs.
Growth Catalysts
- EU MDR Certification Pressure:European yards must demonstrate material traceability for motion control equipment, accelerating replacement cycles for non-compliant legacy systems.
- Superyacht Hull Expansion:Italian builders in Viareggio and Livorno are specifying integrated active fin packages for vessels exceeding 80 meters LOA.
- Seawater-Resistant Alloys:Nickel-aluminum bronze formulations with enhanced cavitation resistance are extending service intervals in continuous immersion environments.
Market Restraints
- Hydraulic Fluid Cost Volatility:Specialized marine-grade hydraulic oils face input price pressure from base stock supply constraints.
- Actuator Supply Concentration:Precision servo-hydraulic actuator manufacturing clusters in Germany and Japan create single-source vulnerability for smaller stabilizer OEMs.
- IMO Compliance Timeline Compression:Retrofit deadlines for aging passenger fleets strain shipyard capacity and compress installation windows.
Strategic Opportunities
- Brazilian Offshore Support Vessels:ANVISA-aligned safety protocols for crew welfare are creating specification pull for motion reduction systems in PSV and AHTS newbuilds.
- Hybrid Electric-Hydraulic Convergence:Battery-buffered actuation architectures are opening fuel efficiency positioning against conventional all-hydraulic designs.
- Direct Yard Integration Channel:Bypassing traditional marine equipment distributors through embedded engineering teams at Fincantieri and Lürssen accelerates specification capture.
Industry Challenges
- Marine Hydrodynamics Talent Scarcity:Computational fluid dynamics specialists with hull-appendage interaction expertise command premium compensation and extended recruitment cycles.
- ISO 12217 Certification Lag:Pending amendments to stability standard software disclosure requirements create product roadmap uncertainty for control system developers.
- Legacy Vessel Integration Complexity:Retrofitting active fins into hulls designed for passive stabilization requires structural reinforcement and tank reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fin Stabilizer Market |
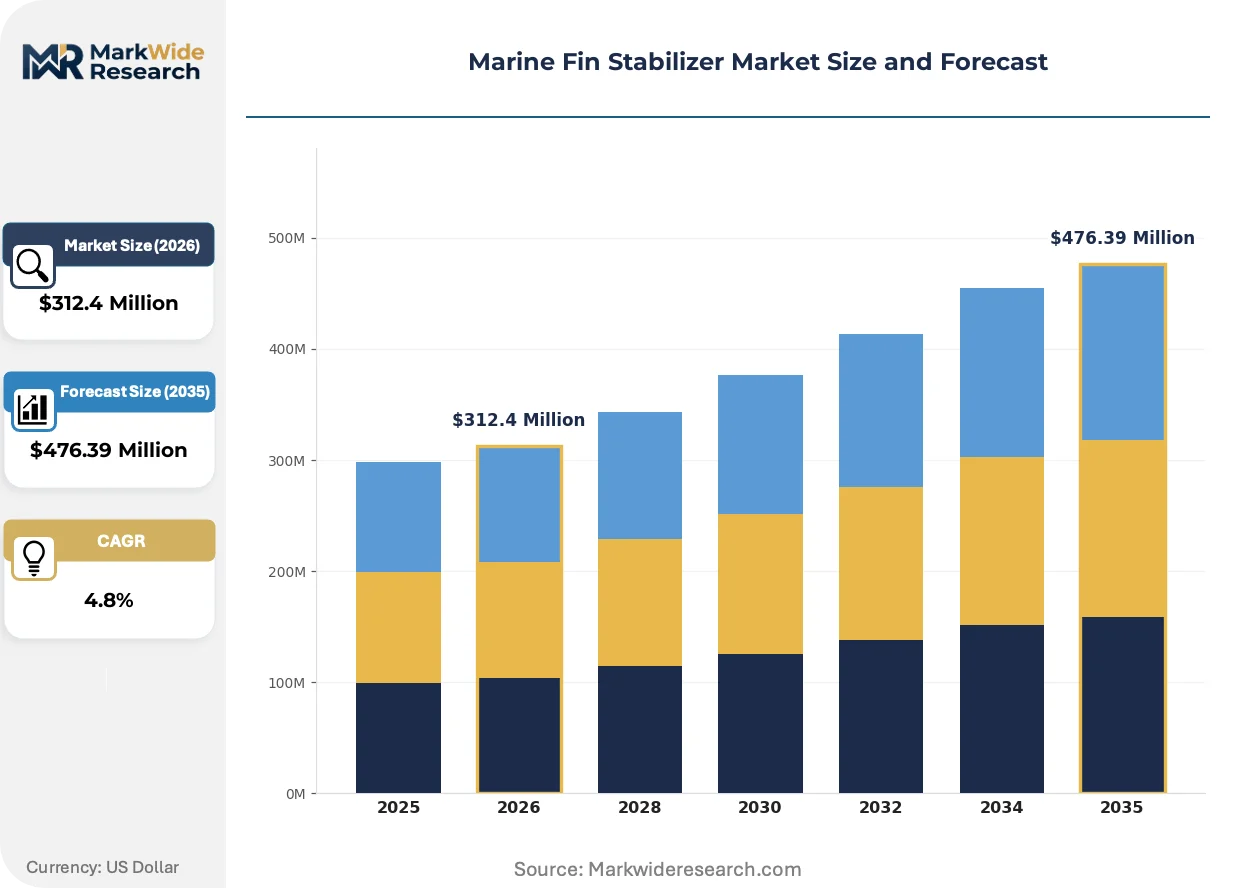
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active fins, Passive fins, Hybrid systems, Control systems End User: Commercial vessels, Luxury yachts, Research vessels, Naval ships Installation Type: Retrofit, New build, Integrated systems, Modular systems Size: Small vessels, Medium vessels, Large vessels, Superyachts |
| Companies Covered | Quantum Marine Stabilizers, ABT-TRAC, SKF Group, KoopNautic Holland, VEEM Ltd., Naiad Dynamics, CMC Marine S.r.l., Humphree AB, Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fin Stabilizer Market Emerging Trajectories
Real-time sensor fusion and predictive roll algorithms are redefining performance benchmarks. Builders now specify stabilizer systems as integrated vessel control nodes rather than standalone appendages.
Composite matrix fin construction is consolidating around carbon-fiber-reinforced epoxy formulations with embedded nickel-copper alloy leading edges. Feadship and Amels are specifying these hybrid structures for 100-meter-plus deliveries to reduce topside weight and lower center of gravity. The shift is consolidating procurement around aerospace-qualified composite suppliers with marine corrosion expertise.
EU MDR technical documentation requirements are forcing control system architecture redesigns. Software version traceability and cybersecurity risk assessments now accompany physical hardware certification for European-flagged vessels. Commercial ferry operators in Greece and Denmark are prioritizing MDR-compliant suppliers in tender evaluations, compressing vendor qualification timelines.
Buyer engineering teams are embedding stabilizer specification earlier in hull design cycles. Naval architects at Italian and Dutch superyacht studios now model fin envelope clearances in initial tank testing rather than post-hoc accommodation. This front-loading is most pronounced in 60-to-90-meter custom builds where LOA constraints demand integrated appendage optimization.
Marine Fin Stabilizer Market Segmentation
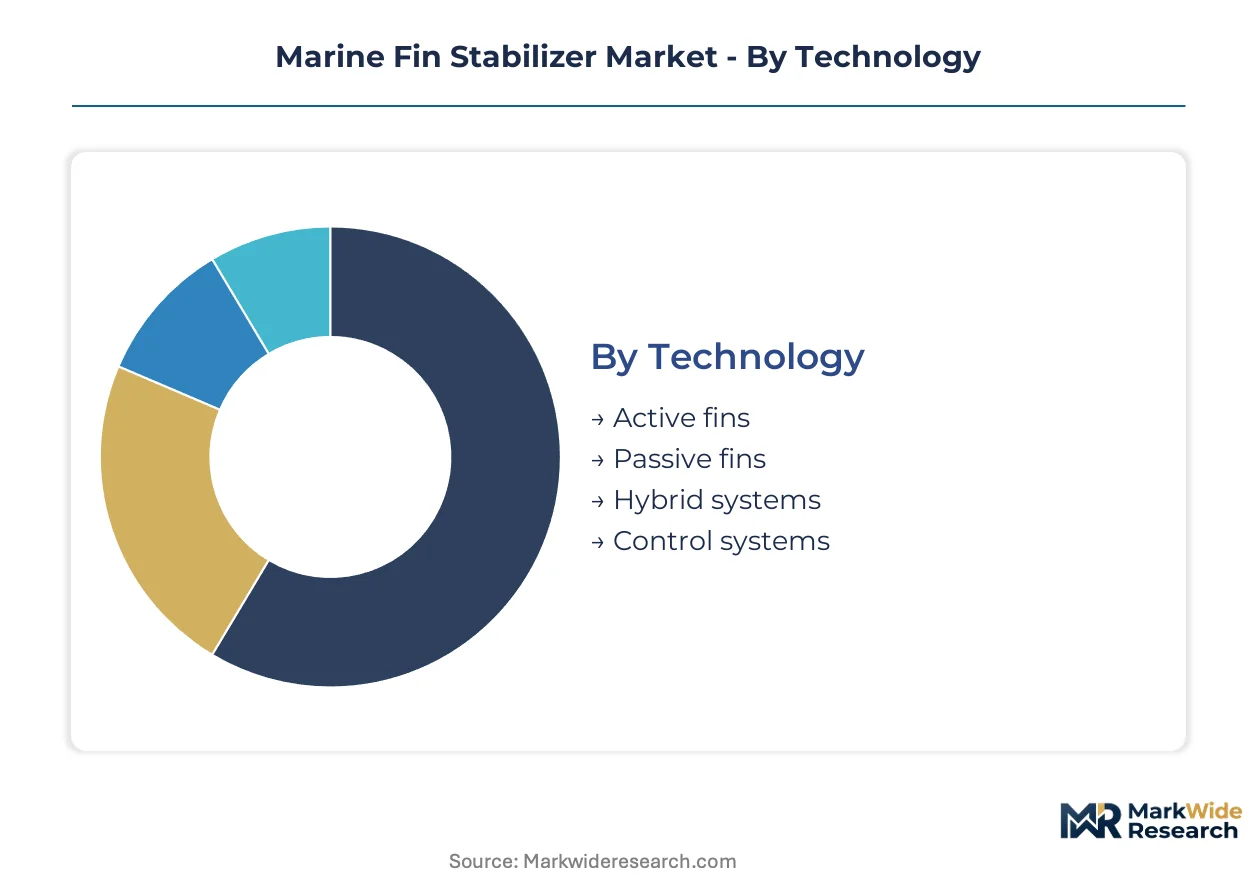
Fin stabilizer procurement splits sharply between bespoke superyacht integrations and standardized commercial fleet retrofits. Technology choice, installation timing, and vessel size class determine supplier engagement models and margin structures across marine segments.
Technology:
Customization intensity spans from fully programmable active systems to fixed-geometry passive designs with no electronic architecture.
- Active fins:Hydraulic or electric actuators adjust fin angle in real-time based on gyroscopic sensor feedback, enabling roll compensation under variable sea states. Italian superyacht builders in Viareggio specify these for vessels exceeding 80 meters LOA where passenger comfort specifications are stringent. IMO stability mandates are compressing adoption timelines for commercial passenger fleets.
- Hybrid systems:Battery-buffered electric actuation reduces continuous hydraulic pump load, cutting fuel consumption during transit. Feadship and Amels are specifying these for 100-meter-plus deliveries to meet EU MDR efficiency documentation requirements. This configuration gains share fastest among new builds where operational expenditure scrutiny intensifies.
- Passive fins:Fixed-geometry foils generate stabilizing moments through hydrodynamic shape alone, eliminating actuator maintenance. Common in small commercial fishing vessels and legacy hulls where capital constraints dominate.
- Control systems:Software-defined sensor fusion architectures with predictive roll algorithms. EU MDR technical documentation requirements are forcing architecture redesigns for cybersecurity risk assessment compliance.
Leading the category by volume: Active fins. Growing fastest: Hybrid systems.
End User:
Margin profiles diverge between price-sensitive commercial operators and specification-driven luxury builders.
- Commercial vessels:Ferry operators and offshore support fleets prioritize IMO compliance and total cost of ownership. Greek and Danish operators are prioritizing MDR-compliant suppliers in tender evaluations.
- Luxury yachts:Custom builds demand integrated vessel control nodes with real-time roll compensation. Dutch and Italian studios now model fin envelope clearances in initial tank testing rather than post-hoc accommodation.
- Research vessels:Scientific mission profiles require minimal acoustic signature and precise station-keeping stability. Specialized composite fin constructions with embedded nickel-copper alloy leading edges address biofouling concerns during extended deployments.
- Naval ships:Military specifications emphasize redundancy, shock resistance, and electromagnetic compatibility. Procurement runs through national defense procurement channels with extended qualification cycles.
Volume concentration: Commercial vessels. Margin expansion: Luxury yachts.
Installation Type:
Timing relative to hull construction determines structural integration depth and certification pathway complexity.
- New build:Fin envelope engineering occurs during initial hull design, optimizing tank and machinery space allocation. Dominates superyacht procurement where appendage-hull interaction modeling is front-loaded.
- Retrofit:Active fin installation into hulls designed for passive stabilization requires structural reinforcement and tank reconfiguration. Aging passenger fleets face IMO stability compliance deadlines that strain shipyard capacity.
- Integrated systems:Stabilizer control merges with propulsion and dynamic positioning networks. Specified for offshore support vessels where ANVISA-aligned safety protocols in Brazil create specification pull.
- Modular systems:Pre-engineered packages reduce installation time for mid-life commercial vessel upgrades. Appeals to operators seeking compressed installation windows without custom engineering.
Revenue share leader: New build. Fastest expansion: Retrofit.
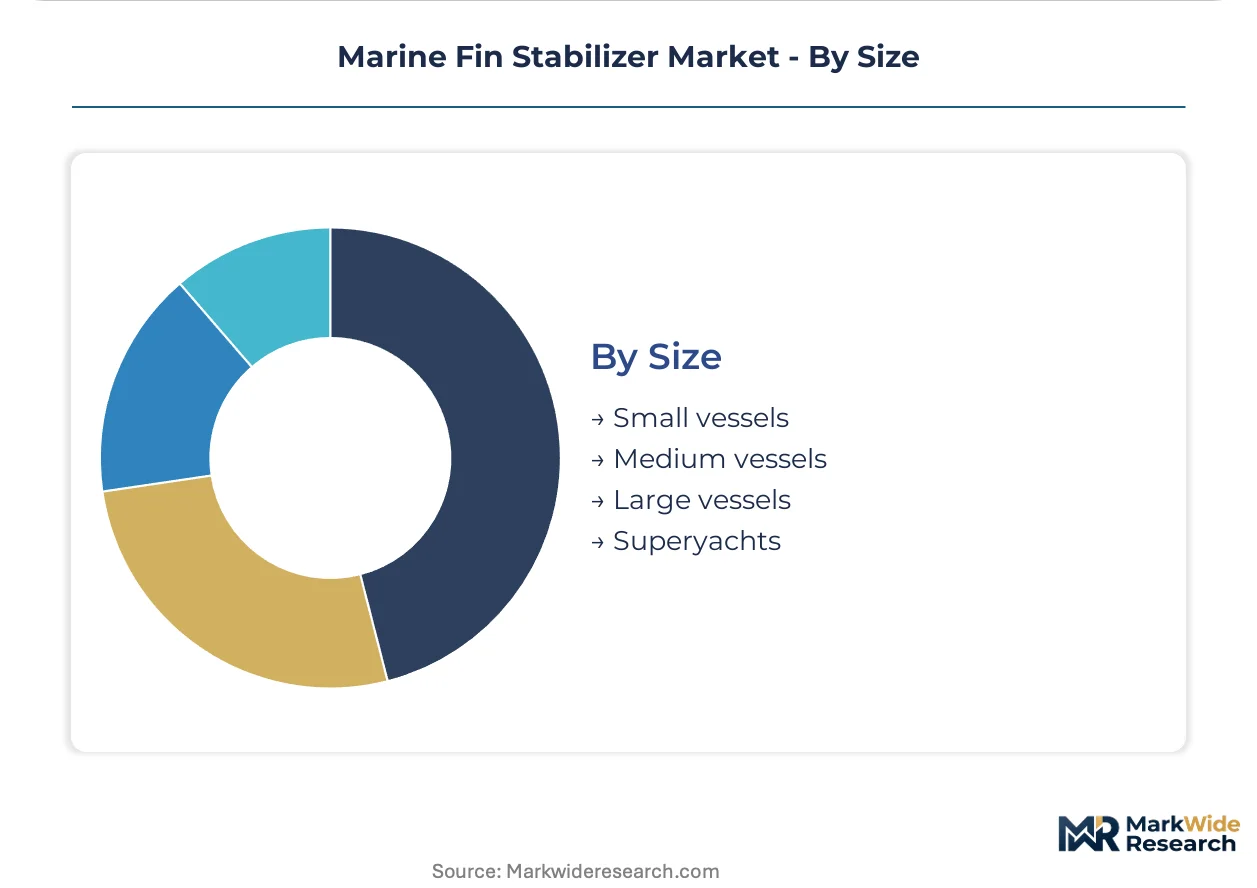
Size:
Hydrodynamic scaling laws and structural load requirements segment engineering approaches across displacement categories.
- Superyachts:Custom composite matrix construction with carbon-fiber-reinforced epoxy formulations reduces topside weight and lowers center of gravity. Procurement concentrates around aerospace-qualified composite suppliers with marine corrosion expertise.
- Large vessels:Cruise ships and expedition yachts require redundant actuator arrays and segmented fin designs. Wärtsilä Corporation extends its propulsion portfolio into stabilizer systems for this category.
- Medium vessels:Offshore support and coastal ferry applications balance performance and capital cost. SKF Group anchors European supply through bearing and motion control integration.
- Small vessels:Fishing boats and pilot craft often specify passive fins or simplified active systems with reduced sensor arrays. Price sensitivity limits supplier margins.
Technology investment intensity peaks: Superyachts. Volume foundation: Large vessels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's superyacht manufacturing cluster around Viareggio and Livorno operates as a de facto special economic zone for marine motion control equipment, concentrating specification authority and engineering talent density unmatched elsewhere.
Italy
Viareggio and Livorno builders specify integrated active fin packages for vessels exceeding 80 meters LOA, driving premium procurement volumes. EU MDR technical documentation requirements force control system architecture redesigns for cybersecurity compliance. Fincantieri's Monfalcone yard coordinates specification capture through embedded engineering teams.
United States
Florida-based engineering centers dominate North American luxury yacht fit-outs with real-time roll compensation systems. US Coast Guard supplemental rules for passenger vessel roll reduction filter down to stabilizer specification sheets. Quantum Marine Stabilizers anchors this concentration through its Fort Lauderdale engineering base.
Germany
Precision servo-hydraulic actuator manufacturing clusters in Bavaria and Baden-Württemberg create supply concentration for European stabilizer OEMs. KBA maritime equipment standards align with EU MDR material traceability mandates. Lürssen's Bremen and Wolgast facilities specify integrated systems for naval and commercial hulls.
Netherlands
Dutch superyacht studios in Amsterdam and Vlissingen model fin envelope clearances during initial tank testing rather than post-hoc accommodation. Feadship and Amels specify hybrid carbon-fiber-reinforced epoxy fin structures for 100-meter-plus deliveries. ANVISA-aligned safety protocols for Brazilian offshore support vessels create export specification pull.
China
Yangtze River Delta shipyards integrate stabilizer specification into newbuild contracts for domestic cruise and ferry operators. MIIT marine equipment certification timelines compress vendor qualification windows. Shanghai and Ningbo facilities face IMO stability compliance deadlines for aging passenger fleet retrofits.
Marine Fin Stabilizer Market Vendor Landscape
Top-tier vendors anchor specification authority at superyacht builders, while mid-tier fabricators compete on retrofit installation speed and commercial fleet compliance deadlines. The market structures around three strategic archetypes: integrated marine propulsion conglomerates, specialist motion control engineering houses, and composite materials-integrated system suppliers. Competitive positioning hardens through direct yard integration channels and hybrid electric-hydraulic technology licensing.
Among specialist motion control engineering houses, Quantum Marine Stabilizers and Naiad Dynamics represent the Florida-based concentration targeting North American luxury specifications. SKF Group occupies a position within the bearing and motion control integration tier, anchoring European supply through its industrial rotation portfolio. Wärtsilä Corporation exemplifies the propulsion conglomerate archetype extending into large commercial hull stabilizer systems.
| Leading Market Players |
|---|
| Quantum Marine Stabilizers |
| ABT-TRAC |
| SKF Group |
| KoopNautic Holland |
| VEEM Ltd. |
| Naiad Dynamics |
| CMC Marine S.r.l. |
| Humphree AB |
| Wärtsilä Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned precision actuator specialists in Bavaria and Baden-Württemberg anchor European supply, translating engineering scarcity into sustained pricing power for servo-hydraulic components that stabilizer OEMs cannot readily substitute.
Pricing Analysis
Lead-time premiums command substantial markups for Italian superyacht builders facing compressed delivery schedules, while spot inventory of nickel-aluminum bronze castings trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified active systems from commercial retrofit packages and basic passive fins. Pricing pressure stems from hydraulic fluid cost volatility as base stock supply constraints tighten input costs. Commercial ferry operators in Greece and Denmark exhibit highest price sensitivity, prioritizing total cost of ownership over performance specifications.
Supply Chain Analysis
EU MDR local-content documentation requirements are reshaping sourcing patterns, forcing European yards to demonstrate material traceability through domestic-qualified suppliers. Germany, Japan, and Italy concentrate precision actuator and composite fin manufacturing. Supply chains draw from nickel-aluminum bronze foundries, carbon-fiber epoxy prepregs, and marine-grade hydraulic seal specialists. Single-source vulnerability clusters in German servo-hydraulic actuator production create structural risk. Distribution runs through embedded engineering teams at Fincantieri and Lürssen rather than traditional marine equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuator manufacturing capacity constraints in Germany and Japan prop pricing discipline, creating a supply-constrained market where qualified suppliers capture disproportionate value.
For Market Incumbents: Deepen backward integration into nickel-aluminum bronze foundry capacity to secure material traceability compliance under EU MDR mandates. Expand captive supply of precision hydraulic seals to offset actuator supply concentration risk from German and Japanese specialists. Quantum Marine Stabilizers and SKF Group should reinforce direct yard integration channels at Fincantieri and Amels before hybrid electric-hydraulic entrants gain specification traction. For New Entrants and Emerging Players: Begin with modular retrofit packages targeting aging Greek and Danish passenger fleets facing IMO stability compliance deadlines. Brazilian offshore support vessel newbuilds under ANVISA protocols represent the most penetrable geography, with specification pull for motion reduction systems in PSV and AHTS segments. Partner with Yangtze River Delta yards on MIIT-certified integrated systems to bypass entrenched European supply relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor aerospace-qualified composite suppliers with marine corrosion expertise in the Netherlands and Italy, where Feadship and Amels specifications consolidate procurement. Long-term viability hinges on control system software capabilities as EU MDR cybersecurity disclosure mandates reshape competitive requirements. Watch pending ISO 12217 amendments as the inflection signal for control architecture investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Electric-Hydraulic Development | Battery-buffered actuation opens fuel efficiency positioning against conventional hydraulic designs at Feadship and Amels. |
| Direct Yard Integration Channel | Embedded engineering teams at Fincantieri and Lürssen accelerate specification capture and compress distributor margins. |
| EU MDR Certification Investment | Cybersecurity risk assessment capabilities separate compliant suppliers from Greek and Danish ferry tender disqualifications. |
| Composite Matrix Manufacturing Scale-Up | Carbon-fiber-reinforced epoxy capacity captures superyacht procurement as 100-meter-plus deliveries multiply. |
| Brazilian Offshore Support Partnership | ANVISA-aligned safety protocols for PSV and AHTS newbuilds create specification pull for motion reduction systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with superyacht naval architects, commercial ferry procurement managers, marine equipment distributors, and hydraulic actuator manufacturing engineers. IMO stability criteria submissions, EU MDR technical documentation databases, MIIT marine equipment certification records, and shipyard production schedules provided demand-side validation. Bottom-up vessel delivery forecasts triangulated against top-down equipment spend estimates across the analysis window.
Data-stream reconciliation across new build order books, retrofit installation schedules, and technology adoption curves shaped the analytical framework. Segmentation dimensions modeled include technology tier, installation timing, vessel size class, and end-use application. CAGRs derived from equipment intensity ratios applied to hull delivery projections, with sensitivity testing around IMO compliance deadline shifts and superyacht order volatility.
Regulatory amendment delays, actuator supply disruptions, and composite material cost spikes are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Elevators Market
Marine
Marine Pipes Market
Marine
Buoys and Beacon Market
Marine
Marine Diesel Engine Market
Marine
Sailboat Propellers Market
Marine
Marine Engine Cooling Systems Market
Marine
US Fish Finders Market
Marine
Trim Tabs Market
Marine
Marine Lighting Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Europe ROV Market
Marine
Commercial Hovercraft Market
Marine
Global Maritime Information Market
Marine
Boat Steering Systems Market
Marine
Steel Ship Plate Market
Marine
Digital Nautical Charts Market