
 Ship Rudders Market | 2026-2036
Ship Rudders Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Rudders Market Analysis
Higher-grade nickel-aluminum-bronze specifications is bifurcating the competitive landscape between premium foundries and standard steel suppliers. Becker Marine Systems GmbH leverages its flap rudder technology leadership to command premium positioning in energy-efficient vessel retrofits. Nakashima Propeller Co. Ltd. anchors Japanese domestic demand through integrated propulsion-steering packages. Wärtsilä Corporation extends its global reach via comprehensive maneuvering solutions that bundle rudders with thrusters and control systems.
A ship rudder is a hydrofoil-shaped steering device mounted aft of a vessel's propeller, typically constructed from cast steel or nickel-aluminum-bronze alloys and engineered to withstand cavitation erosion and hydrodynamic loads exceeding 100 tonnes. Its primary function is to generate lateral force that controls heading, enables docking maneuvers, and maintains stability in heavy seas. Balanced and semi-balanced rudder types dominate newbuild contracts for large cargo ships and tankers due to reduced torque requirements and smaller steering gear footprints. Composite materials represent the fastest-expanding material segment as yards seek weight reduction for high-speed passenger ferries and naval craft. Spade rudders capture disproportionate margin pools in the luxury yacht and expedition cruise niches where custom hydrodynamic optimization commands substantial premiums.
IMO's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are compelling fleet operators to replace obsolete rudders with optimized profiles that reduce fuel consumption. Classification societies including Lloyd's Register, DNV, and Bureau Veritas have tightened cavitation damage assessment protocols, extending inspection intervals for certified high-performance designs. Stakeholders must weigh retrofit timing against charter rate cycles and emerging ammonia-fuelled propulsion architectures that will demand fundamentally different steering geometries.
Market Dynamics
IMO's EEXI and CII mandates are forcing container lines and bulk operators into accelerated rudder retrofit cycles, compressing replacement timelines from 15-year intervals to 7-10 years as fuel efficiency penalties escalate.
Growth Catalysts
- Nickel-aluminum-bronze alloy specifications:Classification societies including Lloyd's Register and DNV now reward extended inspection intervals for cavitation-resistant designs, pulling premium material demand from standard steel foundries.
- South Korean and Chinese shipbuilding clusters:Ultra-large container vessel and LNG carrier orderbooks at Hyundai Heavy Industries and Shanghai Waigaoqiao concentrate high-torque steering system procurement.
- EU Green Deal shipping amendments:The bloc's 2030 emissions reduction targets for maritime transport mandate optimized rudder profiles as a compliance pathway for existing fleet operators.
Market Restraints
- Nickel price volatility:Nickel-aluminum-bronze rudder stock costs fluctuate with LME nickel trading, squeezing foundry margins and deterring long-term contract pricing.
- East Asian foundry concentration:Over 70% of large-diameter rudder casting capacity sits in Chinese and South Korean facilities, creating single-source vulnerability for European and North American repair yards.
- Ammonia propulsion geometry uncertainty:Emerging ammonia-fuelled engine configurations require fundamentally different stern arrangements, freezing investment in conventional rudder designs until standards stabilize.
Strategic Opportunities
- Composite material penetration:Carbon-fiber reinforced polymer rudders for high-speed passenger ferries remain underdeveloped outside Scandinavian and Mediterranean yards, offering first-mover positioning.
- Integrated maneuvering packages:Convergence of flap rudders with tunnel thrusters and dynamic positioning software creates bundled service contracts that lock in multi-year aftermarket revenue.
- Japan's domestic retrofit wave:METI efficiency subsidies for coastal shipping fleets are accelerating demand for Becker flap rudder retrofits at Nagasaki and Kobe repair facilities.
Industry Challenges
- Cavitation erosion modeling expertise:Computational fluid dynamics specialists capable of predicting long-term blade damage remain scarce, extending design validation timelines for new profiles.
- Legacy steering gear integration:Retrofitting optimized rudders onto vessels with 1990s-era hydraulic systems demands custom torque arm modifications that complicate yard scheduling.
- Multi-class certification synchronization:Lloyd's Register, Bureau Veritas, and DNV maintain divergent weld inspection protocols for high-performance alloys, forcing redundant testing for internationally flagged fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Rudders Market |
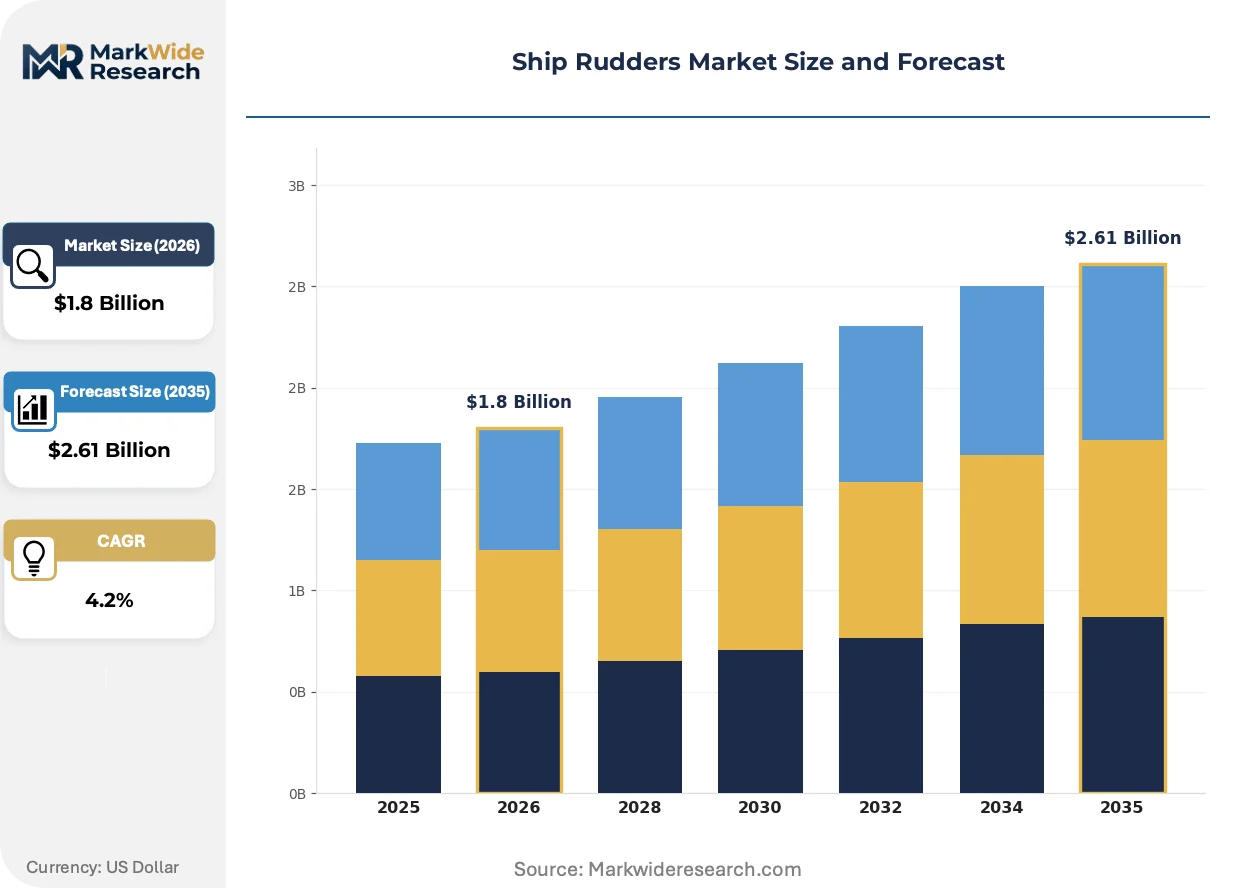
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rudder Type: Balanced Rudders, Unbalanced Rudders, Semi-Balanced Rudders, Spade Rudders Ship Type: Cargo Ships, Tankers, Fishing Vessels, Passenger Ships Material: Steel, Aluminum, Composite, Bronze Size: Small, Medium, Large, Extra Large |
| Companies Covered | Damen Marine Components, Becker Marine Systems GmbH, Nakashima Propeller Co. Ltd., Teignbridge Propellers International Ltd., Mecklenburger Metallguss GmbH, Hamworthy KSE Group Limited, Breeze Marine Group Ltd., Wärtsilä Corporation, Nufoss Services Pte Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Rudders Market Emerging Trajectories
Flap rudder hydrodynamics and composite material science are converging to redefine performance benchmarks, while regulatory pressure compresses adoption timelines across vessel categories.
Flap rudder technology is displacing conventional spade designs in the container shipping segment. Maersk and MSC retrofit programs specify Becker Marine Systems and Nakashima high-lift profiles to meet CII reduction targets. This displacement is compressing market share for standard semi-balanced rudders in vessels above 8,000 TEU capacity.
DNV's updated cavitation damage assessment protocols now mandate finite element analysis for all nickel-aluminum-bronze rudder approvals above 15 meters span. Shipyards in South Korea and China are responding by embedding computational fluid dynamics validation into standard design workflows. The protocols most heavily affect tanker newbuilds where inspection interval extensions justify premium alloy specifications.
Charterers now specify rudder efficiency coefficients in fixture negotiations, transferring technical performance risk from owners to operators. This behavioral shift unbundles steering system selection from traditional shipyard procurement packages. The pattern is most visible in Singapore and Hamburg-based container line technical departments where fuel consumption guarantees dominate vendor selection.
Ship Rudders Market Segmentation
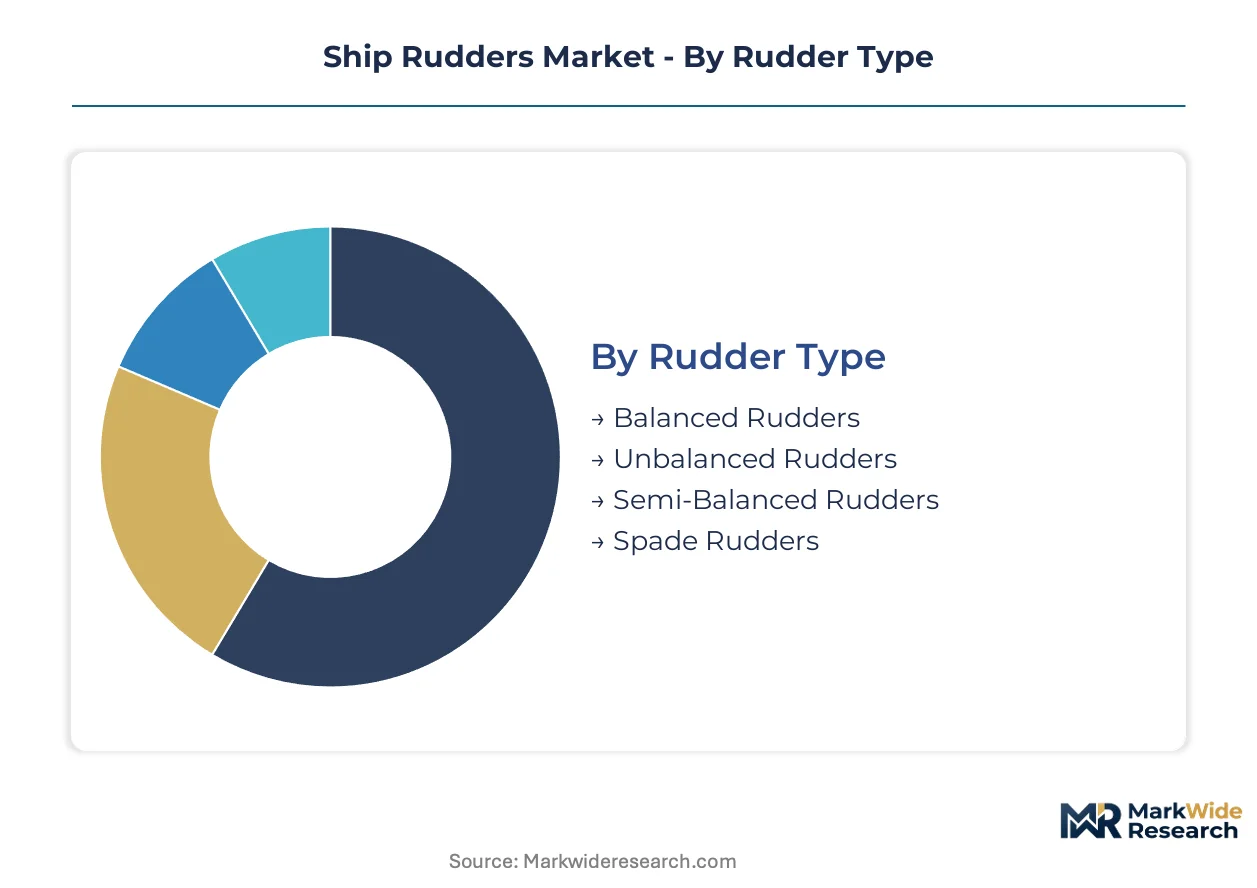
Ship rudder procurement decisions cascade through four interlocking dimensions: hydrodynamic geometry determines steering gear compatibility, vessel category dictates regulatory exposure, material selection governs inspection intervals, and dimensional scaling fixes foundry capacity allocation. Understanding substitution pressures across these axes reveals where suppliers defend margin and where commoditization accelerates.
Rudder Type:
Balanced configurations face intensifying displacement from flap-enhanced alternatives as fuel efficiency guarantees reshape contract terms.
- Balanced Rudders:Torque-reducing design positions the rudder stock aft of the blade's hydrodynamic center, shrinking steering gear footprints on bulk carriers and tankers. South Korean yards at Hyundai Heavy Industries specify these for 300,000+ DWT vessels where machinery space constraints dominate.
- Semi-Balanced Rudders:Hybrid geometry pairs partial torque relief with structural robustness, anchoring demand in Capesize bulkers and Panamax container ships where ice-class notation requirements complicate pure balanced designs. Chinese state yards favor this configuration for its foundry-forgiving tolerances.
- Unbalanced Rudders:Simple hinge-mounted construction persists in coastal fishing fleets and developing-country flag registries where capital constraints override hydrodynamic optimization.
- Spade Rudders:Full-span unsupported trailing edges command premium positioning in expedition cruise vessels and superyachts where custom CFD-optimized profiles justify 40% material cost premiums.
Balanced rudders anchor the volume base while flap-enhanced derivatives gain share at the steepest rate.
Ship Type:
Cargo vessel procurement concentrates investment timing, with charter rate cycles compressing or extending replacement windows across the fleet.
- Cargo Ships:Container lines at MSC and Maersk drive specification intensity, mandating Becker flap retrofits on 8,000+ TEU vessels to meet CII reduction targets. EU Green Deal amendments harden these requirements for Europe-Asia strings.
- Tankers:DNV's updated cavitation protocols most heavily affect this segment, where extended inspection intervals for nickel-aluminum-bronze rudders justify alloy premiums on VLCC newbuilds at Dalian and Okpo.
- Fishing Vessels:Steel semi-balanced designs dominate amid price-sensitive owner-operators in Southeast Asian and West African coastal fleets.
- Passenger Ships:High-speed ferry operators in the Mediterranean and Baltic specify carbon-fiber composite rudders where weight reduction translates directly to fuel savings on short-sea routes.
Cargo ships generate the absolute contract value while passenger vessels expand most quickly on composite penetration.
Material:
Foundry economics and classification society incentives are pulling specification toward corrosion-resistant alloys despite volatile input costs.
- Steel:Standard cast and forged grades retain dominance in repair markets and developing-yard newbuilds where Lloyd's Register basic approval suffices.
- Aluminum:Lightweight specifications penetrate naval patrol craft and coast guard interceptors requiring high sprint speeds.
- Composite:Carbon-fiber reinforced polymer rudders remain underdeveloped outside Scandinavian yards, offering first-mover positioning for weight-critical applications.
- Bronze:Nickel-aluminum-bronze alloys command extended inspection intervals under DNV and Lloyd's Register protocols, concentrating demand in LNG carrier and chemical tanker segments where downtime costs dwarf material premiums.
Steel retains the installed base while bronze climbs the fastest on regulatory incentive alignment.
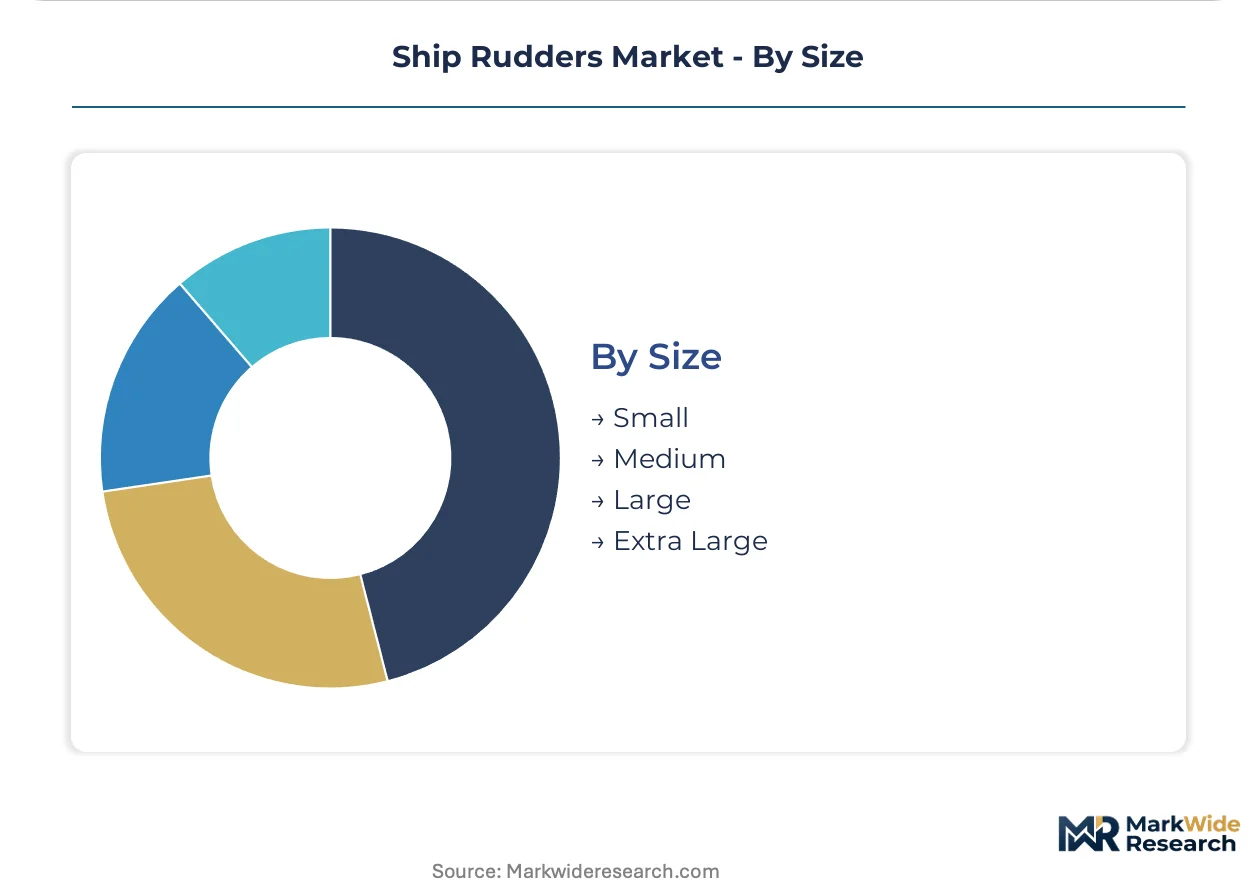
Size:
Foundry capacity constraints bifurcate supply, with extra-large castings requiring dedicated facilities concentrated in East Asian industrial clusters.
- Small:Tugs, pilot boats, and inland waterway craft source from fragmented regional foundries with minimal certification burden.
- Medium:General cargo and feeder container ships occupy the competitive mid-market where Chinese independent foundries compete on delivery speed.
- Large:Panamax and Aframax vessels require specialized heat-treatment facilities, concentrating supply at Shanghai Waigaoqiao and Samsung Heavy Industries.
- Extra Large:Ultra-large container vessels and 300,000+ DWT tankers demand single-piece castings exceeding 100 tonnes, executable only at Hyundai Heavy Industries, DSME, and selected Chinese state-owned facilities with vacuum degassing capability.
Large rudders generate the concentrated margin pool while extra-large specifications face the steepest supply-side constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and China exhibit the lowest price elasticity, absorbing nickel-aluminum-bronze premiums for extended inspection intervals. European and North American repair yards face acute cost sensitivity, driving steel specification retention despite higher lifecycle maintenance burdens.
South Korea
Ultra-large container vessel and LNG carrier orderbooks at Hyundai Heavy Industries and Samsung Heavy Industries concentrate demand for extra-large castings exceeding 100 tonnes. The Korea Register of Shipping aligns with DNV cavitation protocols, rewarding alloy specifications with reduced survey frequency. Busan-Ulsan industrial corridor hosts vacuum degassing foundries capable of single-piece nickel-aluminum-bronze production for 300,000+ DWT tankers.
China
State-owned yards at Shanghai Waigaoqiao and Dalian Shipbuilding Industry dominate Panamax and Aframax rudder procurement, leveraging integrated steel supply chains. The China Classification Society implements GB standards for rudder casting integrity while harmonizing with Lloyd's Register weld inspection protocols for export vessels. Yangtze River Delta foundries supply medium-diameter semi-balanced configurations for domestic bulk carrier newbuilds.
Japan
METI efficiency subsidies for coastal shipping fleets accelerate Becker flap rudder retrofits at Nagasaki and Kobe repair facilities. The Nippon Kaiji Kyokai extends inspection intervals for high-performance alloy designs, pulling specification upgrades from steel-dominated replacement cycles. Kansai-Osaka industrial zone maintains integrated propulsion-steering package capabilities for domestic chemical tanker operators.
Germany
EU Green Deal shipping amendments mandate optimized rudder profiles as compliance pathways for Hamburg and Bremen-based container lines serving Europe-Asia strings. Germanischer Lloyd protocols influence premium alloy adoption for cavitation-resistant designs on Rhine inland waterway retrofits. Mecklenburger Metallguss anchors North German foundry capacity for specialized medium-diameter castings.
Singapore
Bunkering hub status concentrates technical management decisions for Asia-Pacific flagged fleets, with charterers specifying rudder efficiency coefficients in fixture negotiations. The Maritime and Port Authority enforces port state control alignment with IMO EEXI verification procedures. Tuas industrial zone repair facilities handle flap rudder installations for CII-compliant retrofits on transshipment container vessels.
Ship Rudders Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across specification tiers. Premium foundries command extended inspection interval certifications while standard steel suppliers compete on delivery speed for repair markets. Three archetypes dominate: integrated marine propulsion conglomerates bundling rudders with thrusters and control systems; specialized flap rudder technology licensors extracting royalties from yard implementations; and regional foundry operators serving price-sensitive coastal fleet retrofits. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with alloy foundries investing in vacuum degassing equipment and flap rudder patent holders extending geographic coverage through yard partnerships.
Among European-based specialists, Becker Marine Systems GmbH exemplifies technology-led positioning through flap rudder intellectual property, while Mecklenburger Metallguss GmbH represents foundry-scale concentration in nickel-aluminum-bronze casting. Nakashima Propeller Co. Ltd. anchors Japanese domestic demand through integrated propulsion-steering packaging, occupying a position between pure component supply and full maneuvering system integration. Wärtsilä Corporation sits within the conglomerate archetype, leveraging comprehensive marine solutions portfolios that bundle steering hardware with automation and control technologies.
| Leading Market Players |
|---|
| Damen Marine Components |
| Becker Marine Systems GmbH |
| Nakashima Propeller Co. Ltd. |
| Teignbridge Propellers International Ltd. |
| Mecklenburger Metallguss GmbH |
| Hamworthy KSE Group Limited |
| Breeze Marine Group Ltd. |
| Wärtsilä Corporation |
| Nufoss Services Pte Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts at South Korean and Chinese yards lock in nickel-aluminum-bronze supply access while insulating premium foundries from LME nickel volatility. This contract structure binds classification society certification tiers to price visibility, forcing European repair yards into spot-market steel procurement with compressed margins.
Pricing Analysis
IMO's EEXI and CII mandates dictate the pricing tier structure across the ship rudder market, separating certified high-performance alloy specifications from standard steel alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects inspection interval differentials under Lloyd's Register and DNV protocols. Cost compression in the standard steel tier is intensifying because Chinese independent foundries compete aggressively on delivery speed for medium-diameter repair contracts. European and North American repair yards exhibit the highest price sensitivity, absorbing lifecycle maintenance burdens rather than alloy premiums.
Supply Chain Analysis
China and South Korea anchor large-diameter rudder casting capacity, with over seventy percent of extra-large single-piece production concentrated at Hyundai Heavy Industries, DSME, and Shanghai Waigaoqiao state facilities. The supply chain draws from nickel-aluminum-bronze ingot feedstock, vacuum degassing equipment, and specialized heat-treatment infrastructure. Single-source vulnerability for European and North American repair yards creates structural risk when East Asian foundry scheduling conflicts arise. Distribution runs through shipyard-integrated procurement departments and specialized marine component distributors serving retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ship rudder market is entering a cyclical recovery phase driven by accelerated retrofit cycles compressing replacement timelines from fifteen-year intervals to seven-to-ten years under IMO efficiency mandates.
For Market Incumbents: Secure extended inspection interval certifications from DNV and Lloyd's Register to defend margin position against standard steel competitors. Invest in vacuum degassing capacity additions at Busan-Ulsan corridor facilities to capture extra-large casting demand from ultra-large container vessel orderbooks. Lock in long-term nickel-aluminum-bronze supply agreements before LME price volatility intensifies procurement risk. For New Entrants and Emerging Players: Fast-track Lloyd's Register cavitation-resistant design approval to bypass incumbent certification moats in the composite rudder segment. Target Mediterranean and Baltic high-speed ferry operators with carbon-fiber reinforced polymer specifications where Scandinavian yards currently dominate. Pursue joint development agreements with Becker Marine Systems technology licensors to access flap rudder intellectual property without internal R&D burden. For Investors and Strategic Acquirers: Capital is best deployed toward specialized foundry operators with vacuum degassing capability and existing classification society relationships. The five-to-ten year viability window favors alloy-focused facilities over steel-dependent repair yards as regulatory pressure intensifies. Monitor ammonia propulsion geometry standardization as the critical inflection signal determining whether conventional rudder designs face stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Degassing Capacity Expansion | Enables single-piece nickel-aluminum-bronze castings exceeding 100 tonnes for ultra-large vessels at Hyundai Heavy Industries tier facilities. |
| Classification Society Certification Investment | Extends inspection intervals under DNV protocols, justifying alloy premiums on LNG carrier and chemical tanker newbuilds. |
| Flap Rudder Technology Licensing | Extracts royalties from yard implementations while Becker Marine Systems and Nakashima defend intellectual property positions. |
| Composite Material R&D Partnership | Accelerates carbon-fiber reinforced polymer penetration in Mediterranean high-speed ferry segments beyond Scandinavian yard dominance. |
| Integrated Maneuvering Package Development | Bundles rudders with tunnel thrusters and dynamic positioning software to lock in multi-year aftermarket revenue streams. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with shipyard procurement directors, classification society surveyors, foundry operations managers, and marine component distributors. Secondary validation drew from Lloyd's Register approval databases, DNV cavitation assessment protocols, Korea Register and China Classification Society standards filings, and customs trade records for nickel-aluminum-bronze ingot flows. Bottom-up vessel orderbook analysis triangulated against top-down foundry capacity estimates across the analysis window.
Across the projection horizon, the analytical framework modeled rudder type, ship category, material specification, and dimensional scaling segments. CAGRs were derived from orderbook-to-delivery conversion rates and retrofit cycle compression factors. Forecast inputs incorporated IMO regulatory amendment timelines, nickel price volatility bands, and ammonia propulsion architecture development milestones without specifying implementation dates.
Underlying assumptions cover regulatory enforcement continuity, classification society protocol harmonization, and foundry capacity expansion schedules, with deviation risk concentrated in ammonia-fuelled stern geometry standardization delays and prolonged nickel supply disruptions. Recalibration cycles align with material shifts in IMO mandate implementation timelines and East Asian shipbuilding cluster capacity utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Lighting Market
Marine
Marine Elevators Market
Marine
Ship Heat Exchanger Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Marine Pipes Market
Marine
Global Marine Gearbox Market
Marine
Marine Suspension Seat Bases Market
Marine
Marine Big Data Market
Marine
Boat Trolling Motor Market
Marine
Passenger Vessel Propeller Market
Marine
Marine Electronics Market
Marine
Japan Marine Composites Market
Marine
Yacht Shell Doors Market
Marine
Boat Steering Systems Market
Marine
Marine Asset Integrity Services Market
Marine
Flap Rudder Market