
 Marine Winch Motors Market | 2026-2036
Marine Winch Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Winch Motors Market Foresight
IEC 60092 shipboard electrical certification is unwinding the competitive landscape for marine winch motors, forcing manufacturers to redesign insulation systems and thermal management for salt-air endurance. ABB Group leverages its IEC-qualified medium-voltage motor portfolio to anchor contracts with European shipyards building offshore construction vessels. Johnson Electric sustains R&D intensity in compact DC winch drives for deck machinery on commercial fishing fleets. Siemens AG dominates the AC gear motor segment for tugboat winch applications through its NEMA and IEC dual-certified manufacturing lines.
Marine winch motors are electromechanical power units engineered to deliver sustained torque between 50 Nm and 50,000 Nm for cable hauling, anchor handling, and load positioning on vessels and offshore structures, typically housed in IP56 or IP66 enclosures with marine-grade anti-corrosion coatings. Electric winch motors lead the product type landscape due to their compatibility with shipboard DC and AC distribution systems, while brushless DC technology is gaining fastest in precision mooring and dynamic positioning winches where variable speed control reduces mechanical wear. AC gear motors command the deepest margin pools in heavy-lift offshore applications where integrated reduction stages eliminate separate gearbox procurement.
The International Electrotechnical Commission's IEC 60092 series and the International Maritime Organization's SOLAS safety framework govern insulation class, thermal protection, and emergency braking standards for winch motors installed on seagoing vessels. The EU's F-Gas Regulation indirectly shapes demand by accelerating electric winch adoption as hydraulic systems using fluorinated refrigerants face phase-down pressures in European-flagged fleets. Classification societies including DNV and Lloyd's Register enforce type-approval protocols that determine which motor designs gain access to insured commercial operations. Stakeholders must monitor the divergence between IEC and emerging regional certification requirements as shipbuilders in South Korea and China pursue national standards that may fragment qualification pathways for global motor suppliers.
Market Dynamics
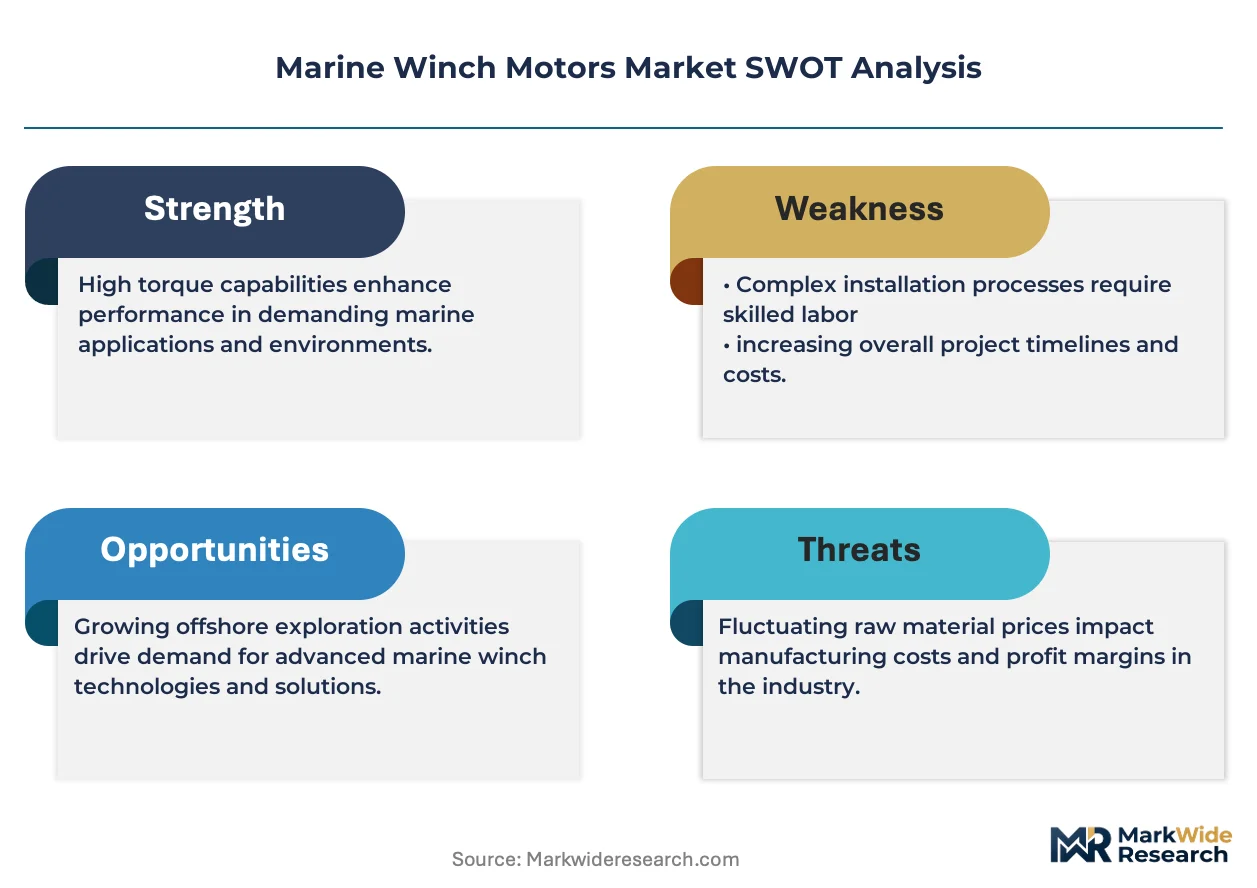
IEC 60092 certification tightening is forcing motor manufacturers to redesign insulation systems and thermal management architectures, compressing product development timelines while elevating qualification costs for salt-air endurance testing. This regulatory pressure is reshaping competitive positioning by favoring suppliers with existing IEC-qualified medium-voltage portfolios.
Growth Catalysts
- North Sea offshore wind buildout:Norwegian and UK installation vessel operators are procuring high-torque winch systems for subsea cable laying and turbine foundation deployment, driving specification upgrades across the supply chain.
- F-Gas Regulation phase-down:The EU's restrictions on fluorinated refrigerants in hydraulic systems are accelerating electric winch motor substitution in European-flagged fleets.
- Brushless DC motor advancement:Variable speed control technology is reducing mechanical wear in precision mooring and dynamic positioning winches, extending maintenance intervals for commercial operators.
Market Restraints
- Copper and rare-earth magnet cost volatility:NdFeB magnet prices fluctuate with Chinese export quotas, compressing margins for permanent magnet motor producers serving the marine segment.
- Supply concentration in East Asian foundries:Marine-grade cast iron housing production clusters in Jiangsu and Zhejiang provinces, creating single-source risk for European motor assemblers.
- IEC 60092-201 thermal class limitations:Class F insulation ratings cap continuous operating temperatures at 155°C, restricting power density in compact deck machinery applications.
Strategic Opportunities
- US Jones Act vessel renewal:Domestic content requirements for offshore construction vessels create captive demand for IEC-NEMA dual-certified motor suppliers establishing US assembly operations.
- Digital twin integration:Convergence of condition monitoring sensors with predictive maintenance platforms enables motor-as-a-service revenue models for fleet operators.
- South Korean shipbuilder localization mandates:National standards divergence from IEC creates first-mover advantage for suppliers pursuing KS certification alongside international qualifications.
Industry Challenges
- Marine electrical engineer scarcity:Specialized expertise in salt-air insulation design and IP66 sealing protocols commands premium compensation, constraining R&D team scaling.
- Classification society approval timelines:DNV and Lloyd's Register type-approval protocols extend 14-18 months for novel motor architectures, delaying commercialization.
- Legacy DC system integration:Shipboard DC distribution retrofits require harmonic filtering and voltage stabilization modules, complicating electric winch motor deployment on older vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Winch Motors Market |
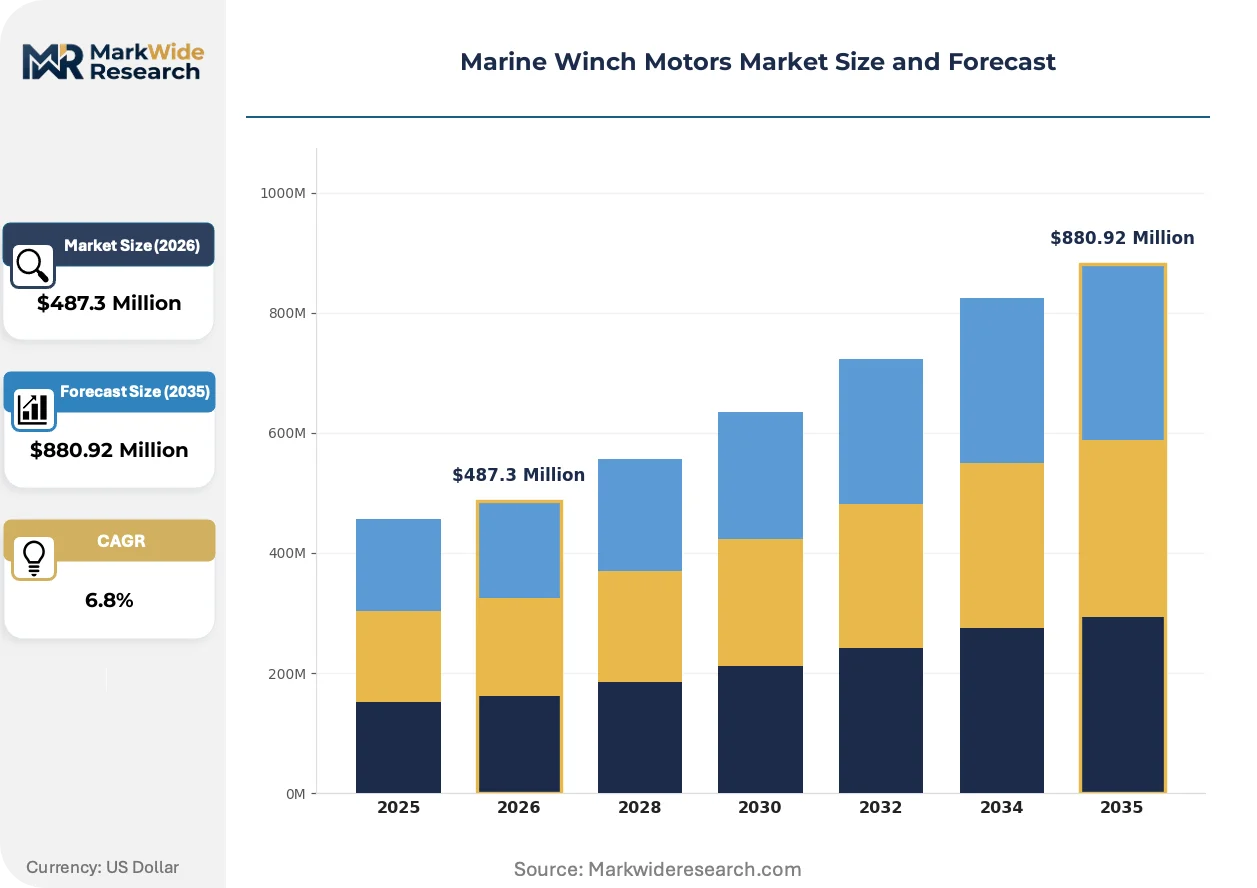
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Pneumatic, Mechanical Technology: AC Motors, DC Motors, Brushless Motors, Gear Motors Application: Commercial Vessels, Offshore Platforms, Fishing Boats, Tugs End User: Shipping Companies, Marine Contractors, Fishermen, Surveyors |
| Companies Covered | Johnson Electric, General Electric, ABB Group, Haacon Hebetechnik GmbH, Allied Motion Technologies, Siemens AG, Emerson Electric Company, Lewmar Limited, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Winch Motors Market Shifts & Advancements
Permanent magnet synchronous motor technology is supplanting wound-field designs across precision winch applications. Regulatory pressure on hydraulic fluid containment is accelerating electric system substitution. Procurement patterns are compressing supplier qualification cycles as shipyards consolidate vendor bases.
Integrated permanent magnet synchronous motors with built-in encoders are supplanting separately excited DC machines in anchor handling winches. Norwegian offshore vessel operators specify these systems for dynamic positioning operations requiring ±0.1 meter station-keeping accuracy. The technology is supplanting legacy gearbox-motor combinations by eliminating mechanical backlash and reducing deck footprint by 40 percent.
The EU F-Gas Regulation is prohibiting fluorinated greenhouse gases in hydraulic power units above 40 bar operating pressure. Shipyards building European-flagged offshore construction vessels must specify all-electric winch drives or alternative fluid systems by 2030. AC gear motor suppliers with IEC-qualified IP66 enclosures are capturing specification priority in German and Dutch yard contracts.
Shipowner procurement is consolidating around integrated system suppliers capable of delivering motor-reducer-control packages under single-source warranty. Independent motor manufacturers face displacement by deck machinery OEMs bringing electromechanical design in-house. This pattern is most visible in Singapore and Rotterdam hub ports where major towage operators negotiate fleet-wide service agreements spanning 50-100 vessel units.
Marine Winch Motors Market Segmentation
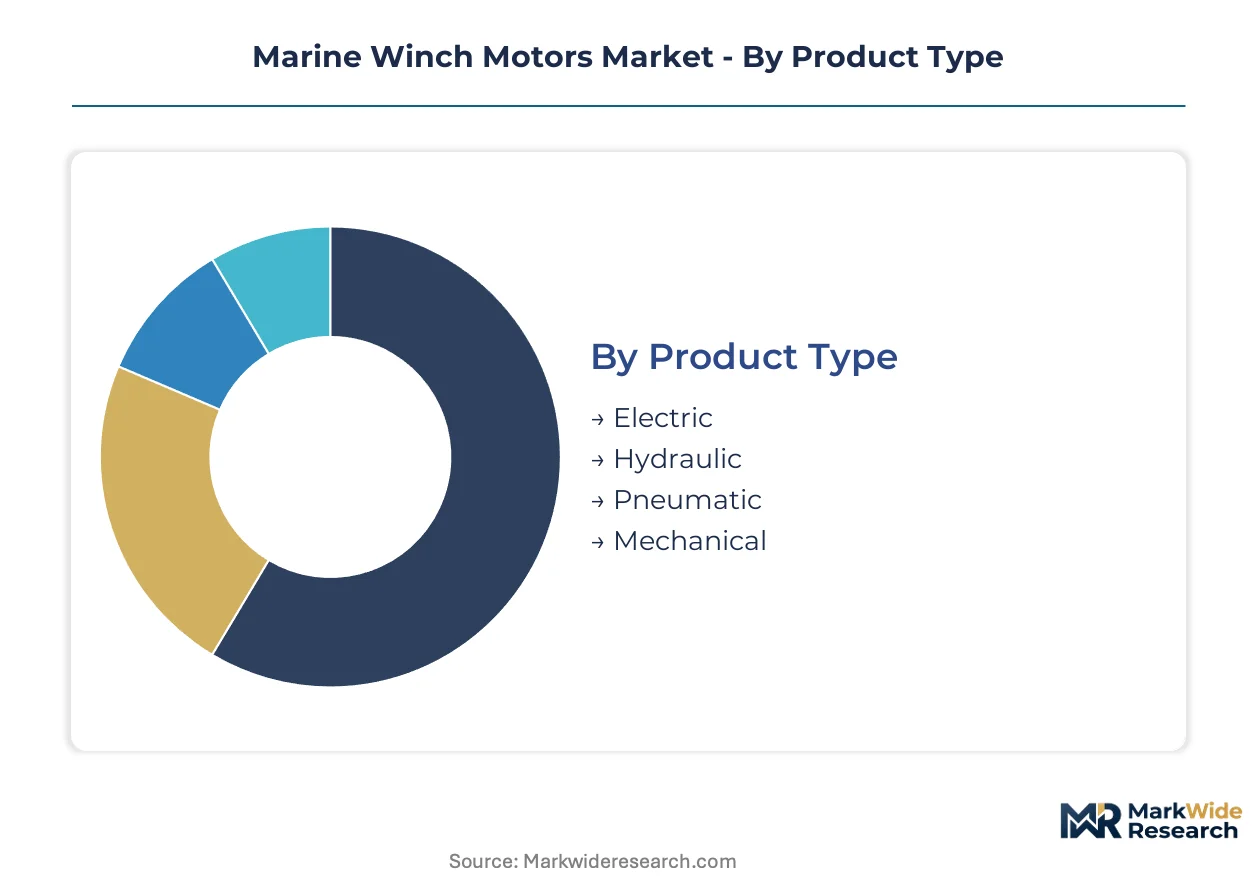
Marine winch motor procurement channels diverge sharply by vessel type and operational intensity. Shipyards building offshore construction vessels negotiate direct with motor OEMs for integrated drive packages, while commercial fishing fleets source through marine equipment distributors.
Product Type:
Channel mix varies by power density requirements, with high-torque applications flowing through system integrators and standard deck machinery moving through wholesale marine suppliers.
- Electric:Permanent magnet and AC induction architectures dominate newbuild specifications for offshore wind installation vessels operating in the North Sea. Norwegian vessel operators specify these systems for dynamic positioning winches requiring precise torque control during turbine foundation deployment.
- Hydraulic:Radial piston and gear pump drives retain installed base in legacy anchor handling fleets, though EU F-Gas Regulation phase-down is constraining replacement demand for European-flagged vessels.
- Pneumatic:Compressed air motors serve explosion-risk zones on tankers and chemical carriers where spark-free operation is mandatory.
- Mechanical:Hand-crank and spring-tension units persist on small craft and emergency backup systems.
By volume, Electric leads. By growth pace, Pneumatic is gaining share fastest in specialized safety applications.
Technology:
Cost tier stratification separates precision servo systems from commodity induction motors, with premium brushless architectures commanding three-to-four-fold price multiples over standard AC gear motor platforms.
- AC Motors:Squirrel-cage induction and synchronous reluctance designs anchor heavy-lift offshore applications. Integrated reduction stages eliminate separate gearbox procurement for subsea cable laying winches on North Sea installation vessels.
- DC Motors:Wound-field and permanent magnet brushed architectures sustain aftermarket demand for commercial fishing fleet deck machinery retrofits.
- Brushless Motors:Sensor-equipped permanent magnet synchronous systems deliver ±0.1 meter station-keeping accuracy for dynamic positioning operations.
- Gear Motors:Helical and planetary reduction-integrated units compress deck footprint by 40 percent versus separate motor-gearbox assemblies.
By volume, AC Motors leads. By expansion trajectory, Brushless Motors are climbing the fastest on precision mooring demand.
Application:
Customer type concentration shapes specification intensity, with marine contractors driving performance requirements and fleet operators prioritizing total cost of ownership.
- Commercial Vessels:Container ships and bulk carriers specify IP66-enclosed electric winch drives for mooring and cargo handling operations. SOLAS safety framework compliance elevates thermal protection and emergency braking standards.
- Offshore Platforms:Jack-up rigs and semi-submersibles demand high-torque systems for jacking and positioning operations. North Sea operators are expanding fleet renewal programs with IEC 60092-qualified medium-voltage motors.
- Fishing Boats:Trawler and purse seiner fleets favor compact DC winch drives for net and line handling.
- Tugs:Harbor and escort vessels require rapid-response winch systems for barge handling and emergency towing.
By volume, Commercial Vessels leads. By specification upgrade intensity, Offshore Platforms is ahead.
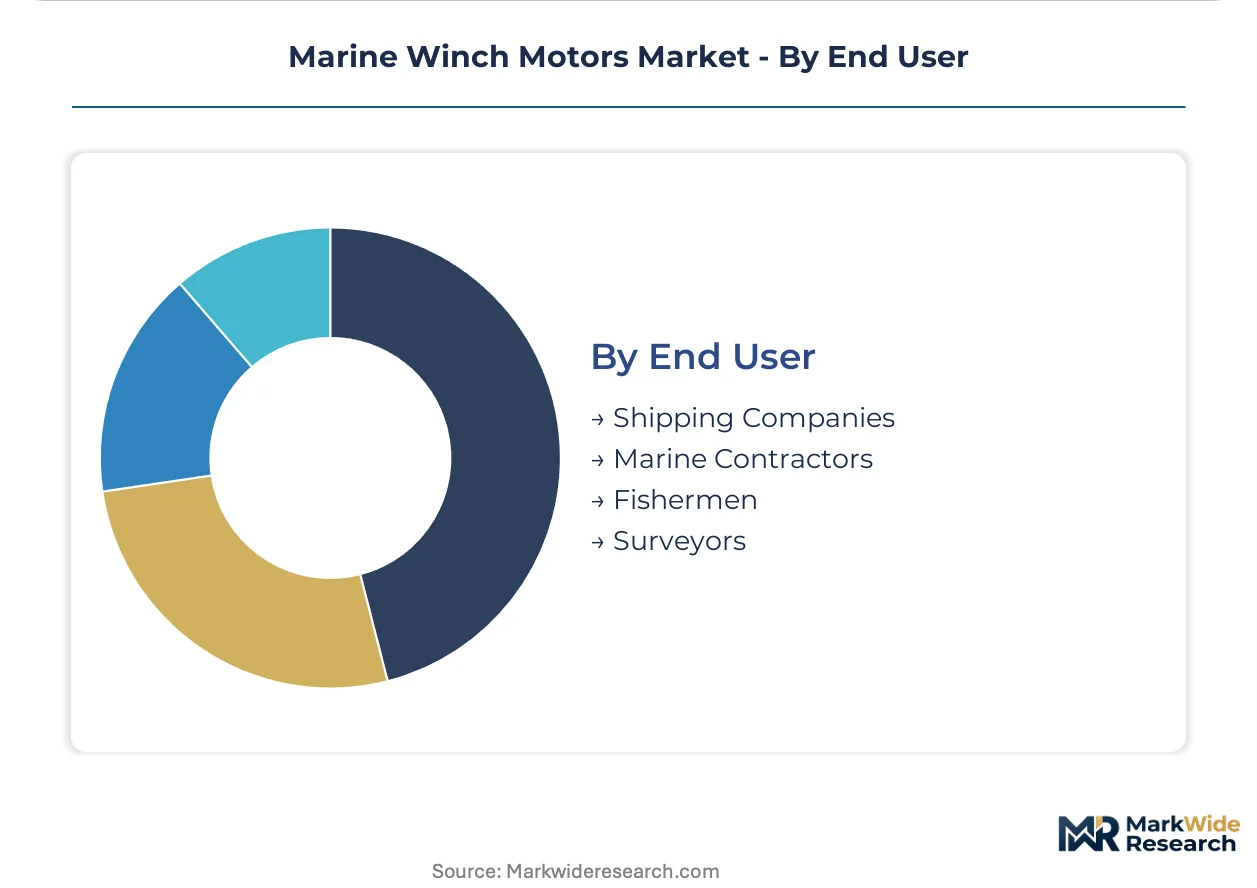
End User:
Margin structure inverts across user categories, with marine contractors accepting premium pricing for project-specific performance guarantees and fishermen driving commoditization through price-focused procurement.
- Shipping Companies:Container line and tanker fleet operators negotiate enterprise service agreements spanning 50-100 vessel units. Condition monitoring integration enables motor-as-a-service revenue models.
- Marine Contractors:Offshore construction and subsea installation specialists specify custom-engineered winch systems for cable laying and foundation deployment projects.
- Fishermen:Owner-operator fleets source through distributor networks with limited technical specification involvement.
- Surveyors:Oceanographic and hydrographic research vessels require precision winch control for sensor deployment and retrieval.
By volume, Shipping Companies leads. By technology specification intensity, Marine Contractors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation is accelerating electric winch motor substitution across European-flagged fleets, while national certification divergence in East Asia is fragmenting qualification pathways for global suppliers.
Norway
North Sea offshore wind installation vessels drive specification intensity for high-torque winch systems. The Norwegian Maritime Authority enforces strict IEC 60092 compliance for subsea cable laying equipment. Stavanger and Bergen host engineering clusters where vessel operators procure dynamic positioning winches for turbine foundation deployment.
Germany
German shipyards building offshore construction vessels prioritize AC gear motors with integrated reduction stages. The country's implementation of EU F-Gas restrictions prohibits hydraulic systems above 40 bar by 2030. Hamburg and Bremerhaven anchor procurement activity for all-electric deck machinery on wind farm service vessels.
United States
Jones Act vessel renewal programs create captive demand for IEC-NEMA dual-certified motors. The US Coast Guard enforces SOLAS-aligned safety standards for commercial winch installations. Gulf Coast shipyards in Louisiana and Texas are expanding assembly operations to satisfy domestic content requirements for offshore construction fleets.
China
Marine-grade cast iron housing production concentrates in Jiangsu and Zhejiang provinces, supplying European motor assemblers. The country's national standardization body is pursuing GB standard divergence from IEC protocols. Shanghai and Dalian shipyards are integrating localized winch drive specifications into newbuild contracts.
South Korea
Major shipbuilders are mandating KS certification alongside international qualifications for deck machinery suppliers. The Ministry of Trade, Industry and Energy supports localization of electromechanical component production. Busan and Ulsan industrial zones are developing captive supply chains for precision mooring winch systems.
Marine Winch Motors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with existing IEC-qualified medium-voltage portfolios. Market structure concentrates around suppliers capable of delivering motor-reducer-control packages under single-source warranty. Three archetypes dominate: integrated electromechanical system providers, compact DC drive specialists, and heavy-lift AC gear motor manufacturers. Competitive moves center on certification portfolio expansion and geographic assembly localization to satisfy domestic content requirements.
Among diversified industrial conglomerates, ABB Group and Siemens AG exemplify the integrated system provider archetype, leveraging dual IEC-NEMA certification to anchor contracts with European and North American shipyards. Johnson Electric occupies a position within the compact drive specialist tier, while Haacon Hebetechnik GmbH represents German engineering-focused fabrication. Nidec Corporation and Emerson Electric Company sit within the scale-driven industrial motor segment, supplying standardized platforms for commercial vessel retrofits.
| Leading Market Players |
|---|
| Johnson Electric |
| General Electric |
| ABB Group |
| Haacon Hebetechnik GmbH |
| Allied Motion Technologies |
| Siemens AG |
| Emerson Electric Company |
| Lewmar Limited |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent in Jiangsu and Zhejiang provinces compress marine-grade cast iron housing availability, elevating minimum order quantities for European motor assemblers while anchoring price floors for IP66-enclosed winch systems. This scale concentration allows Chinese suppliers to dictate payment terms, forcing downstream buyers to absorb working capital burdens or cede margin to intermediaries.
Pricing Analysis
Certification level creates the primary spread across marine winch motor tiers, with IEC 60092-qualified medium-voltage systems commanding substantial premiums over standard IP56 induction platforms. Three-tier pricing structure across premium, standard, and economy levels reflects insulation class, thermal protection ratings, and emergency braking integration. Pricing pressure stems from NdFeB magnet cost volatility tied to Chinese export quota adjustments, compressing margins for permanent magnet motor producers. Marine contractors exhibit lowest price sensitivity due to project-specific performance guarantees, while commercial fishing fleets drive commoditization through distributor-focused procurement.
Supply Chain Analysis
China and South Korea anchor marine winch motor component fabrication, with Jiangsu province housing foundries producing cast iron enclosures and Busan industrial zones specializing in precision mooring system assembly. NdFeB permanent magnets, marine-grade copper windings, and IEC-qualified insulation materials constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundry capacity, where any disruption cascades through European motor assembly lines. Distribution runs through marine equipment distributors serving commercial fleets and direct OEM relationships for offshore construction vessel shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine winch motors are shifting toward integrated electromechanical platforms where motor-reducer-control bundling under single-source warranty creates ecosystem lock-in, interoperability standards around IEC 60092 certification are hardening competitive moats for qualified suppliers.
For Market Incumbents: Fortify certification portfolios by pursuing dual IEC-NEMA qualification for Jones Act vessel access, while anchoring backward integration into marine-grade cast iron housing production to offset Jiangsu foundry concentration risk. Brushless DC system displacement of wound-field designs in precision mooring applications demands accelerated R&D in sensor-equipped permanent magnet synchronous architectures. Channel control through fleet-wide service agreements spanning 50-100 vessel units protects against deck machinery OEMs bringing electromechanical design in-house. For New Entrants and Emerging Players: Lead with US Gulf Coast assembly operations to satisfy domestic content requirements for offshore construction vessel renewal programs, where IEC-NEMA dual-certified suppliers face limited competition. White-space concentration sits in digital twin integration for condition monitoring and predictive maintenance platforms, enabling motor-as-a-service revenue models. Target marine contractors specifying custom-engineered winch systems for North Sea cable laying projects through direct engineering engagement rather than distributor channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated system providers capable of delivering motor-reducer-control packages under multi-year fleet service agreements. Long-term viability across the analysis window favors suppliers with captive IEC 60092 qualification pathways and established relationships with Norwegian offshore wind installation vessel operators. Acquisition priority targets compact DC drive specialists with brushless motor technology applicable to dynamic positioning winch retrofits. The signal to watch is divergence between IEC and emerging GB or KS national standards, which would fragment qualification costs for non-diversified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| IEC-NEMA Dual Certification Investment | Unlocks Jones Act vessel contracts requiring domestic content compliance alongside international safety standards. |
| Backward Integration into Foundry Operations | Reduces single-source exposure to Jiangsu and Zhejiang cast iron housing production clusters. |
| Digital Twin Platform Development | Enables predictive maintenance revenue streams for fleet operators managing 50-100 vessel units. |
| Brushless DC Technology Acquisition | Captures specification priority in precision mooring winches requiring ±0.1 meter station-keeping accuracy. |
| South Korean KS Certification Pursuit | Secures access to Busan and Ulsan shipbuilder supply chains under national localization mandates. |
Research Methodology
The analysis maps electric, hydraulic, pneumatic, and mechanical winch motor sub-sectors, each validated through shipyard procurement directors, marine equipment distributors, offshore vessel operators, and classification society surveyors. Primary interviews with IEC certification engineers and thermal management specialists combined with secondary validation against Lloyd's Register type-approval databases, DNV equipment qualification records, customs trade data for marine-grade cast iron imports, and SEC filings from diversified industrial motor manufacturers. Bottom-up vessel fleet segmentation triangulates against top-down offshore wind installation capacity projections.
Consistency checks validated volume and value outputs against external benchmarks including shipyard order books for offshore construction vessels, North Sea wind farm development timelines, and EU F-Gas Regulation implementation tracking. The analytical framework models technology segmentation across AC induction, DC wound-field, brushless permanent magnet, and gear-integrated architectures alongside application dimensions spanning commercial vessels, offshore platforms, fishing boats, and tugs. CAGRs derive from fitted growth curves applied to vessel newbuild and retrofit demand cycles, with NdFeB magnet price indices and IEC certification timeline assumptions as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained North Sea offshore wind investment, stable Chinese rare-earth export policies, or continued IEC 60092 harmonization would require recalibration. Forecasts reflect documented assumptions regarding shipyard consolidation patterns, classification society approval timelines, and F-Gas Regulation enforcement intensity across European-flagged fleets. Recalibration cycles align with material shifts in offshore wind installation vessel order activity, national standard divergence announcements, and marine electrical engineer labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Boat Console Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Commercial Hovercraft Market
Marine
Deep-V Boat Market
Marine
Global Maritime Information Market
Marine
Fishing Vessel Market
Marine
Jet Boat Market
Marine
Marine VFD Market
Marine
Recreational Vessel Battery Market
Marine
Marine Shaft Power Meter Market
Marine
Marine Base Steering Gear Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Pipes Market
Marine
Ballast Water Management Market
Marine
Marine Electronics Market