
 Automotive Throttle Cables Market | 2026-2036
Automotive Throttle Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Throttle Cables Market Analysis
Asset-light leasing arrangements for manufacturing equipment is tilting competitive dynamics toward suppliers that avoid heavy capital commitments. Continental AG leverages its integrated electronics-cable portfolio to sustain long-term OEM contracts. Orscheln Products anchors its position through specialized push-pull cable engineering for commercial vehicle segments. Denso Corporation competes by extending quality-testing capabilities that reduce warranty exposure for vehicle assemblers.
Automotive throttle cables are mechanical or electromechanical linkages, typically fabricated from stranded steel wire with polymer jacketing, that transmit pedal input to engine throttle bodies or electronic control modules. Their primary commercial purpose is ensuring precise, durable accelerator response across internal-combustion and hybrid powertrains. Cable assembly configurations dominate OEM supply contracts due to bundled integration with pedal modules and mounting hardware. Push-pull cable variants command premium positioning in heavy trucks where load-rated tensile strength and sealed conduit designs protect against contamination. Aftermarket channels for throttle control components retain margin resilience as repair shops prioritize rapid availability over unit cost.
NHTSA Federal Motor Vehicle Safety Standards govern accelerator control system integrity and emergency response characteristics in the United States. EPA regulations on evaporative emissions and engine calibration precision indirectly shape throttle cable material specifications and routing tolerances. The EU Green Deal and REACH chemical restrictions in Europe are pressuring suppliers to eliminate halogenated compounds from cable jacketing formulations. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating whether electromechanical throttle actuation will displace mechanical cable architectures in remaining vehicle segments.
Market Dynamics
Mechanical throttle architectures face systematic displacement as drive-by-wire systems penetrate mid-range vehicle segments, compressing addressable volume for traditional cable assemblies while forcing suppliers to diversify into electromechanical actuation modules or exit.
Growth Catalysts
- EPA tailpipe regulations:Heat-resistant polymer coatings now dominate new platform specifications as OEMs redesign engine bays to meet tighter thermal management requirements.
- Commercial vehicle fleet aging:Heavy-duty trucks operating beyond 15 years generate sustained aftermarket pull for push-pull cable replacements.
- Hybrid powertrain proliferation:Dual-mode throttle control systems require redundant mechanical backup cables alongside electronic primary actuation.
Market Restraints
- Steel wire input volatility:Stranded steel pricing fluctuates with scrap metal and energy costs, compressing margin predictability for cable fabricators.
- Supplier concentration in Germany:Tier-1 bundling contracts with Continental and Leoni lock out smaller competitors from OEM direct relationships.
- Electronic throttle substitution:Drive-by-wire modules eliminate mechanical linkages entirely in premium battery-electric platforms.
Strategic Opportunities
- India commercial vehicle expansion:Domestic truck and bus production growth creates demand for load-rated push-pull assemblies with localized sourcing requirements.
- Retrofit electrification kits:Classic vehicle conversion shops need custom-length throttle cables for hybridized vintage powertrains.
- EU Green Deal chemical phase-out:Halogen-free jacketing formulations qualify suppliers for preferential OEM selection under sustainability procurement criteria.
Industry Challenges
- Polymer formulation expertise gap:Compound chemistry specialists capable of heat-aging validation are scarce relative to mechanical engineering talent pools.
- Dual certification timelines:Simultaneous NHTSA FMVSS and EU type-approval processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Throttle Cables Market |
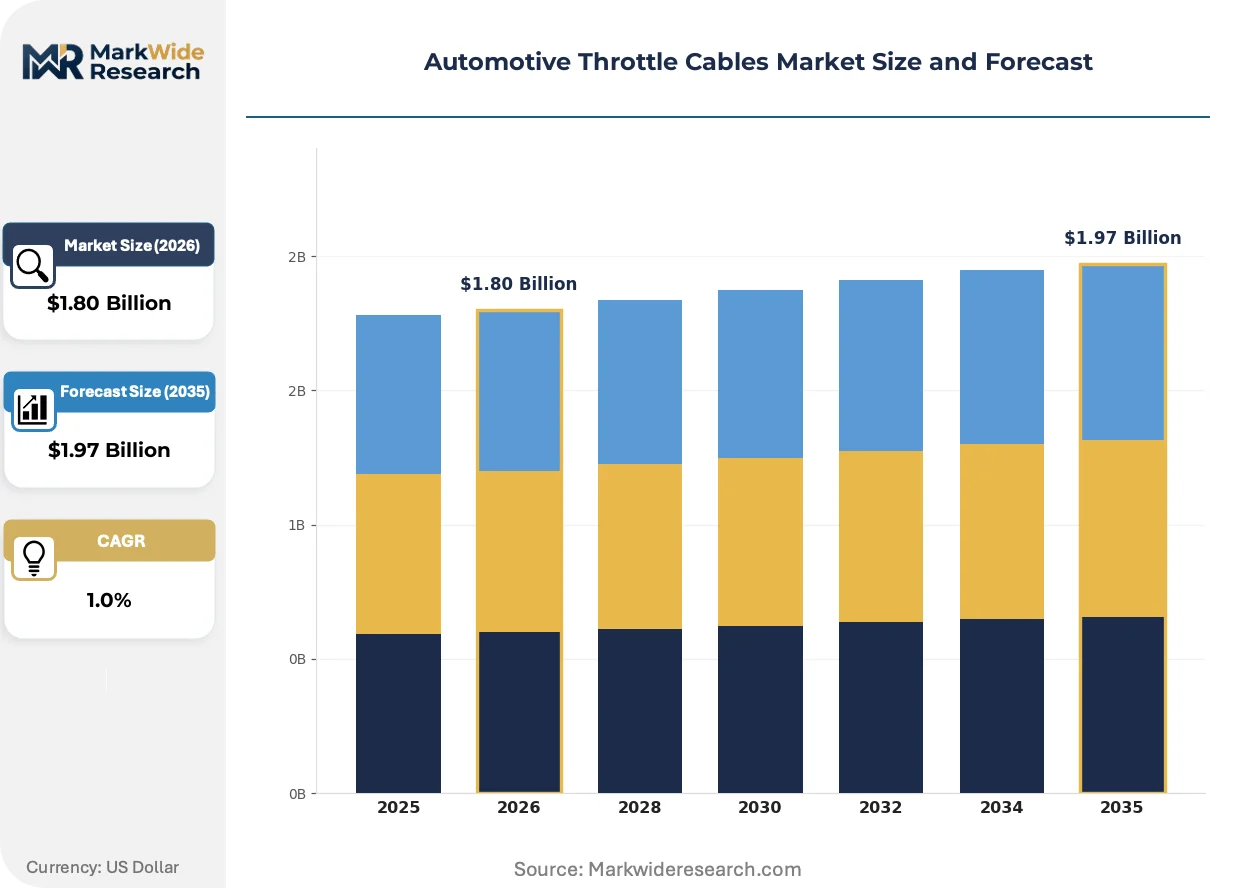
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Assembly, Push-Pull Cable, Pedal Assembly, Throttle Control Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Trucks, Motorcycles Manufacturing Stage: Raw Material Sourcing, Component Fabrication, Assembly, Quality Testing End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Delphi Technologies, Orscheln Products, Continental AG, SKF, Yazaki Corporation, Dura Automotive Systems, Magneti Marelli, Venhill, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Throttle Cables Market Emerging Trajectories
Material science advances and electronic control integration are bifurcating the supplier base between electromechanical specialists and mechanical cable optimizers, with regulatory chemistry mandates accelerating formulation turnover.
Self-lubricating polymer liners embedded within stranded steel cores reduce friction coefficients by half versus traditional uncoated assemblies. Tier-1 suppliers in Germany and Japan are qualifying these for 500,000-cycle durability targets. The technology is rendering obsolete conventional grease-packed conduit designs that require periodic maintenance access.
REACH chemical restrictions in Europe now prohibit specific halogenated flame retardants in cable jacketing from 2026. Compounders must reformulate with phosphorus-nitrogen alternatives without sacrificing 125°C continuous operating ratings. Asian suppliers serving EU export markets face accelerated R&D timelines to maintain component qualification status.
Fleet maintenance departments now specify pre-assembled throttle-pedal modules rather than discrete cable procurement. Distributors in the United States are consolidating inventory positions around bundled SKUs that reduce shop labor time. This pattern concentrates purchasing power with integrated module suppliers and marginalizes standalone cable specialists.
Automotive Throttle Cables Market Segmentation
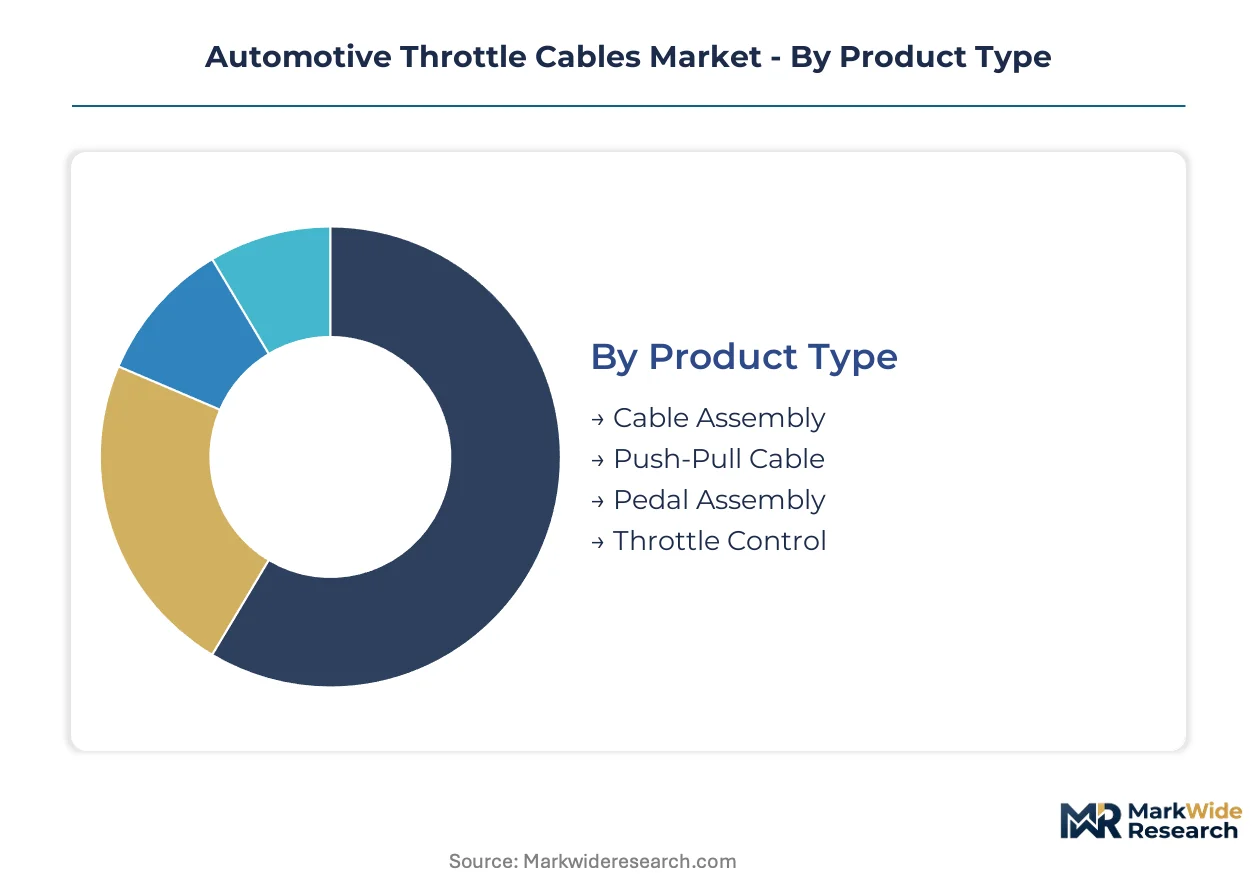
Throttle cable procurement patterns diverge sharply between integrated OEM supply chains and fragmented aftermarket channels. Each segmentation dimension reveals distinct margin structures, technical requirements, and competitive dynamics that suppliers must navigate simultaneously.
Product Type:
Mature mechanical formats dominate installed base volumes while electromechanical hybrids emerge in next-generation platforms.
- Cable Assembly:Bundled stranded steel wire with polymer jacketing, pre-terminated with end fittings for direct pedal-to-throttle integration. OEM contracts in Germany and the United States specify these for 85% of internal-combustion passenger vehicle platforms, though drive-by-wire substitution compresses forward volumes.
- Push-Pull Cable:Sealed conduit designs with load-rated tensile strength engineered for contamination resistance in commercial vehicle engine bays. Demand concentrates in heavy truck fleets operating beyond 15-year service lives, where aftermarket replacement cycles sustain margin resilience despite electronic throttle encroachment in new builds.
- Pedal Assembly:Integrated modules combining accelerator pedal, position sensor, and cable attachment points into single SKUs.
- Throttle Control:Electronic actuation modules and electromechanical hybrid systems displacing mechanical linkages in premium platforms.
Cable Assembly handles the majority of throughput; Push-Pull Cable is expanding most quickly in commercial aftermarket share.
Application:
Vehicle mass and duty cycle intensity determine cable specification tiers, with light-duty formats facing fastest electronic substitution.
- Passenger Vehicles:Standard-duty cable assemblies with 2.0-3.0mm diameter stranded steel cores and PA12 or TPE jacketing. OEM specifications in China and Japan now mandate redundant mechanical backup cables alongside electronic primary actuation for hybrid powertrains, preserving cable demand despite drive-by-wire proliferation.
- Heavy Trucks:Push-pull cables with 4.0-6.0mm cores, sealed conduits rated for 500,000 cycles, and operating temperature ranges to 150°C. Fleet aging across the United States and India generates sustained aftermarket pull where repair shops prioritize rapid availability over unit cost.
- Light Commercial Vehicles:Intermediate-duty configurations bridging passenger and heavy-duty specifications.
- Motorcycles:Compact cable assemblies with simplified end fittings and exposed routing tolerant of vibration and weather exposure.
Passenger Vehicles retains the largest addressable volume base; Heavy Trucks demonstrates the steepest expansion trajectory in aftermarket value per unit.
Manufacturing Stage:
Process steps cluster geographically around steel wire drawing centers and polymer compounding hubs, with quality testing emerging as the bottleneck capability.
- Raw Material Sourcing:High-carbon steel wire rod procurement and polymer resin selection for jacketing formulations. Scrap metal price volatility in European and Asian markets compresses margin predictability for cable fabricators lacking long-term supply contracts.
- Quality Testing:Heat-aging validation, cycle-life verification, and tensile strength certification required for NHTSA FMVSS and EU type-approval. Compound chemistry specialists capable of 125°C continuous operating validation are scarce relative to mechanical engineering talent pools, extending product launch cycles.
- Component Fabrication:Stranding, jacket extrusion, and end-fitting attachment processes.
- Assembly:Final bundling with mounting hardware and pedal modules into customer-specific configurations.
Component Fabrication handles the majority of employment and capital deployment; Quality Testing is climbing the fastest on supplier capability premiums.
End User:
Procurement authority concentrates with integrated vehicle assemblers while aftermarket channels retain pricing power through availability premiums.
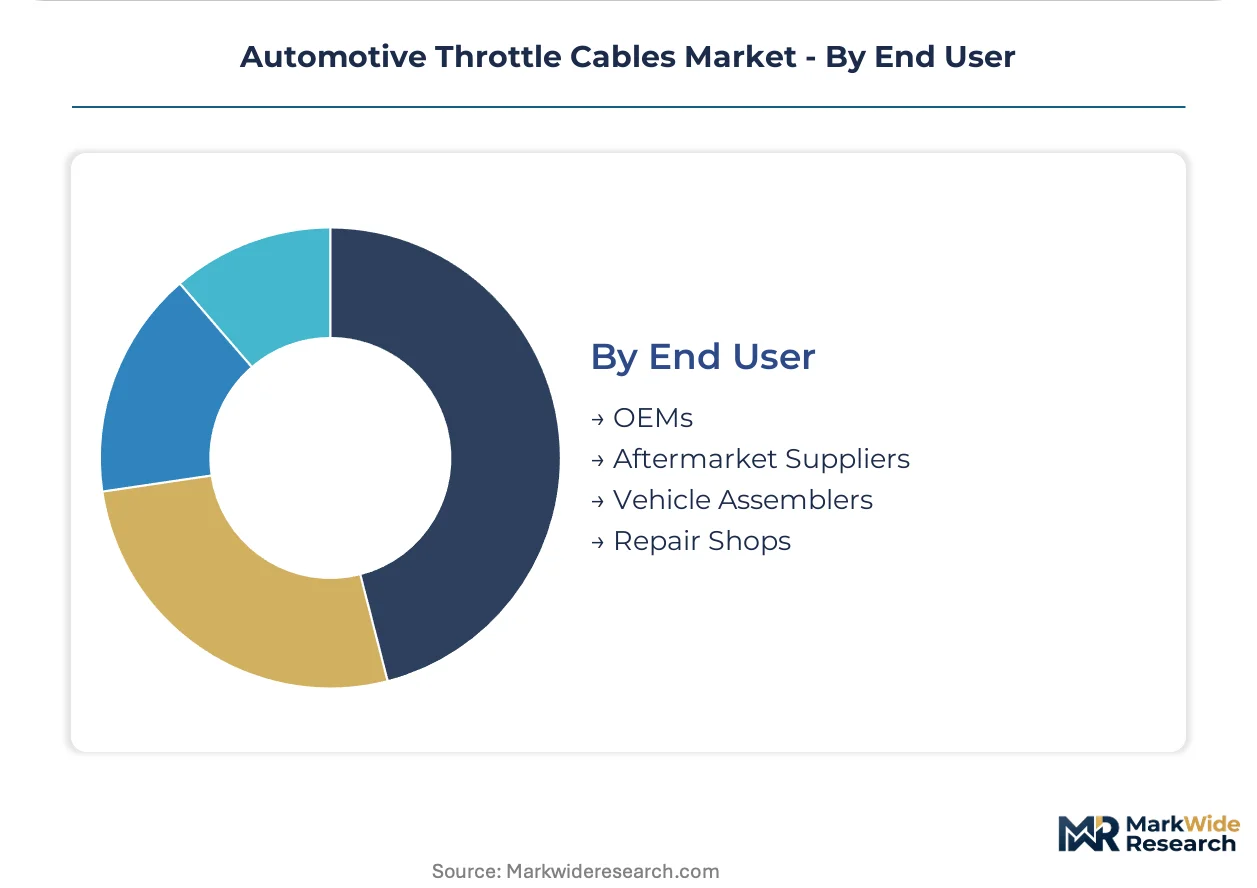
- OEMs:Direct specification of cable assemblies bundled with pedal modules and mounting hardware under multi-year platform contracts. Tier-1 bundling arrangements with Continental and Leoni in Germany lock out smaller competitors from direct OEM relationships, forcing specialization strategies.
- Repair Shops:Discrete cable procurement for aging vehicle fleet maintenance, prioritizing rapid parts availability over unit cost. United States distributors are consolidating inventory positions around pre-assembled throttle-pedal modules that reduce shop labor time, marginalizing standalone cable specialists.
- Aftermarket Suppliers:Independent distributors serving non-captive repair networks.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing qualified components.
OEMs command the majority of contract value; Repair Shops are gaining share fastest in aftermarket channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe regulations and NHTSA safety standards in the United States are accelerating material upgrades to heat-resistant polymer coatings, while the EU Green Deal and REACH chemical restrictions pressure European suppliers to eliminate halogenated compounds from cable jacketing formulations.
United States
Heavy-duty truck fleets operating beyond 15-year service lives generate sustained aftermarket pull for push-pull cable replacements. NHTSA Federal Motor Vehicle Safety Standards govern accelerator control system integrity and emergency response characteristics. Detroit's dense supplier networks anchor OEM procurement of cable assemblies bundled with pedal modules.
Germany
Tier-1 bundling contracts with Continental and Leoni lock out smaller competitors from direct OEM relationships. REACH chemical restrictions now prohibit specific halogenated flame retardants in cable jacketing from 2026. Stuttgart's automotive engineering clusters concentrate quality-testing capabilities for 125°C continuous operating validation.
China
Domestic truck and bus production growth creates demand for load-rated push-pull assemblies with localized sourcing requirements. GB standards and MIIT regulations shape throttle cable material specifications and routing tolerances. Yangtze River Delta manufacturing hubs dominate stranded steel wire drawing and polymer compounding capacity.
India
Commercial vehicle expansion drives procurement of sealed conduit designs rated for contamination resistance in severe operating environments. BIS certification requirements and the PLI scheme for automotive components incentivize domestic cable fabrication investments. Tamil Nadu's industrial corridors attract tier-1 suppliers establishing captive assembly operations.
Japan
Hybrid powertrain proliferation requires redundant mechanical backup cables alongside electronic primary actuation. METI industrial standards and JIS specifications govern cycle-life verification and tensile strength certification. Nagoya's automotive supplier ecosystem specializes in self-lubricating polymer liners embedded within stranded steel cores.
Automotive Throttle Cables Market Vendor Landscape
On the supply side, the industry is bifurcating between electromechanical specialists diversifying into drive-by-wire modules and mechanical cable optimizers defending aftermarket positions. Three strategic archetypes dominate: integrated tier-1 bundlers with electronics-cable portfolios, push-pull cable specialists serving commercial vehicle segments, and quality-testing leaders reducing warranty exposure for vehicle assemblers. Dominant competitive moves include asset-light leasing arrangements for manufacturing equipment and accelerated R&D timelines to maintain component qualification status under REACH chemical restrictions.
Within the integrated tier-1 tier, Continental AG exemplifies the bundling archetype through its combined electronics-cable positioning. Among specialized push-pull engineers, Orscheln Products occupies a position serving heavy-truck aftermarket demand. Denso Corporation represents the quality-testing leadership archetype, anchoring supplier capability premiums in heat-aging validation and cycle-life verification. These three companies collectively illustrate the competitive vectors shaping procurement authority concentration with vehicle assemblers.
| Leading Market Players |
|---|
| Delphi Technologies |
| Orscheln Products |
| Continental AG |
| SKF |
| Yazaki Corporation |
| Dura Automotive Systems |
| Magneti Marelli |
| Venhill |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese stranded steel wire drawing centers is compressing margin predictability for cable fabricators while simultaneously enabling aggressive pricing postures among tier-1 suppliers with long-term polymer supply contracts. This utilization dynamic rewards asset-light operators leasing extrusion equipment over capital-heavy integrated manufacturers.
Pricing Analysis
Certification level (NHTSA FMVSS and EU type-approval) creates the primary spread between premium and commodity tiers in this market. Contract-based long-term offtake dominates OEM procurement, with price differentiation hinging on heat-aging validation credentials and bundled pedal module integration. Cost compression in standard-duty cable assemblies is intensifying because repair shops now prioritize pre-assembled throttle-pedal modules over discrete cable procurement. Aftermarket channels demonstrate highest price sensitivity, while hybrid powertrain OEMs accepting redundant mechanical backup cables show lowest sensitivity due to warranty exposure concerns.
Supply Chain Analysis
High-carbon steel wire rod feeds from Yangtze River Delta mills, German specialty steel producers, and Indian induction furnace operators anchor upstream material flows. The supply chain draws from polymer compounding hubs in Germany, Japan, and China for jacketing formulations. Single-source vulnerability concentrates in heat-resistant polymer liner technology, where Japanese compounders hold proprietary self-lubricating formulations. Distribution runs through tier-1 bundlers directly to OEM platform engineering teams, with aftermarket channels consolidating around integrated module distributors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as fleet aging and hybrid proliferation fragment procurement authority between electromechanical module specialists and mechanical cable optimizers, creating defendable niches for focused players.
For Market Incumbents: Pre-empt drive-by-wire substitution by accelerating R&D timelines for halogen-free jacketing formulations that qualify under EU Green Deal procurement criteria. Consolidate quality-testing capabilities in Stuttgart and Nagoya clusters to reduce warranty exposure for vehicle assemblers, locking in multi-year platform contracts before electronic throttle modules capture mid-range segments. For New Entrants and Emerging Players: Pursue India's commercial vehicle expansion by establishing localized push-pull cable fabrication in Tamil Nadu industrial corridors under PLI scheme incentives. Target heavy-truck aftermarket demand where fleet maintenance departments specify sealed conduit designs rated for contamination resistance, penetrating through rapid availability guarantees rather than unit cost competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cable assembly fabrication as asset-light leasing arrangements displace owned extrusion capacity. Five-to-ten year viability favors acquiring specialized push-pull cable engineers with established commercial vehicle relationships rather than integrated tier-1 bundlers facing electronic substitution headwinds. Monitor REACH chemical restriction compliance timelines as the signal indicating which compounders will retain EU export qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Jacketing Reformulation | REACH compliance from 2026 forces compound chemistry R&D acceleration among Asian suppliers serving EU markets. |
| Quality Testing Capability Expansion | Heat-aging validation scarcity in Germany and Japan creates supplier capability premiums for NHTSA certification. |
| Push-Pull Cable Localization | India PLI scheme incentives attract tier-1 suppliers establishing captive assembly operations in Tamil Nadu corridors. |
| Self-Lubricating Polymer Integration | 500,000-cycle durability targets in Nagoya render conventional grease-packed conduit designs obsolete. |
| Pre-Assembled Module Bundling | United States distributors consolidating around bundled SKUs marginalize standalone cable specialists in repair channels. |
Methodological Framework
Operator-level perspectives from tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and commercial vehicle fleet maintenance directors anchored the qualitative base. Primary interview insights combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA tailpipe regulation filings, and REACH chemical restriction documentation. Bottom-up cable assembly volume estimates triangulated against top-down OEM platform content analysis.
Scenario-bracketing framed analytical approach across the modeling period, with volume and value outputs reflecting segmentation by propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derived from platform lifecycle projections and aftermarket replacement cycle intensity. Forecast inputs incorporated hybrid powertrain proliferation rates and commercial vehicle fleet aging patterns.
Sensitivities concentrate around electronic throttle substitution velocity and scrap metal price volatility in steel wire input markets. Forecasts reflect documented assumptions on regulatory divergence timelines and material specification evolution. Cross-checking against NHTSA FMVSS enforcement patterns and EU type-approval certification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market