
 Automotive Relay Market | 2026-2036
Automotive Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Relay Market Analysis
Japanese relay manufacturing capacity is broadening across Southeast Asian production bases to serve expanding electric vehicle programs. DENSO Corporation leverages its integrated semiconductor and relay assembly operations to secure preferential supply positions with Toyota and Honda electrification platforms. TE Connectivity Ltd. anchors its automotive relay portfolio through high-current contact technologies developed for 800-volt architectures. Robert Bosch GmbH competes via mechatronic relay modules that consolidate switching, protection, and diagnostic functions into single housings.
An automotive relay is an electromechanically or solid-state operated switch that controls high-current circuits through low-power input signals, typically rated between 12 volts and 48 volts in conventional vehicles and extending to 400-800 volts in electrified platforms. These devices manage power distribution, load switching, and circuit protection across vehicle electrical architectures, with electromechanical variants dominating legacy internal-combustion applications while solid-state relays gain share in battery-electric powertrains where silent operation and unlimited cycling life matter most. The application landscape reveals that safety systems command premium pricing due to ISO 26262 functional-safety certification requirements, whereas power distribution applications generate the highest unit volumes as vehicle electrical loads multiply. Electric vehicles represent the fastest-expanding vehicle type segment, though passenger cars still account for the majority of absolute relay consumption given fleet scale and multi-relay architectures per vehicle.
China's MIIT enforces GB/T standards for high-voltage relay performance in new energy vehicles, while the EU's F-Gas Regulation indirectly shapes relay material specifications through refrigerant circuit electrification trends. The US NHTSA FMVSS requirements for automatic emergency braking and advanced lighting systems mandate redundant relay pathways that increase per-vehicle counts. Stakeholders must monitor how 48-volt mild-hybrid proliferation versus full battery-electric penetration alters the optimal relay technology mix across their product roadmaps.
Market Dynamics
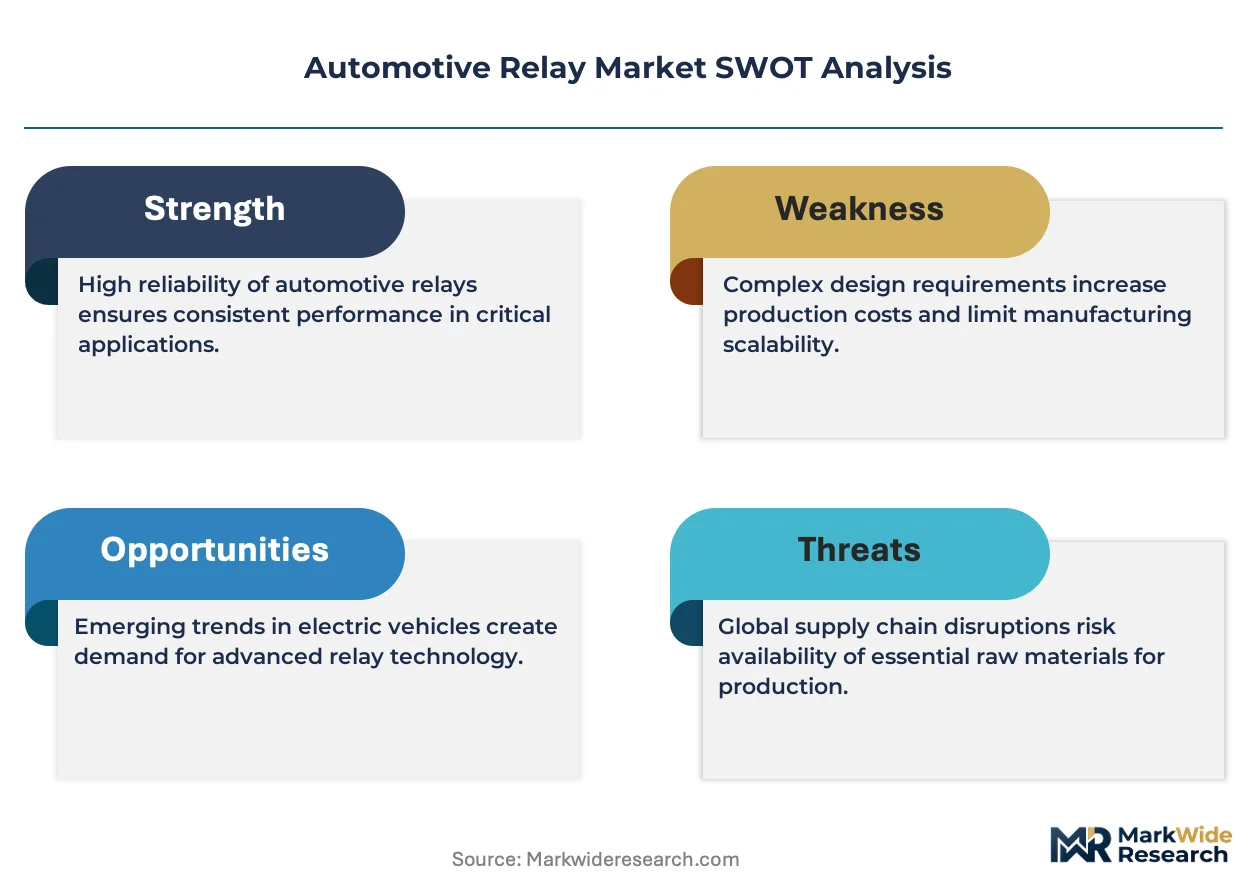
Electrification of vehicle powertrains is compressing relay specification cycles as 800-volt architectures displace legacy 12/48-volt systems, forcing suppliers to recalibrate contact materials and thermal management designs for high-voltage battery management integration.
Growth Catalysts
- China's dual carbon goals:NEV mandates under MIIT's GB/T standards tighten high-voltage relay performance specifications, accelerating qualification cycles for domestic and foreign suppliers.
- Powertrain electrification:Battery-electric platforms multiply relay counts per vehicle through redundant switching pathways in thermal management and charging subsystems.
- Germany's supplier corridor:Stuttgart-Wolfsburg production clusters concentrate demand for ISO 26262-certified safety relays with integrated diagnostic functions.
Market Restraints
- Silver-copper alloy cost volatility:Contact material price swings compress margin stability for electromechanical relay producers serving volume passenger car programs.
- Japanese production concentration:Southeast Asian capacity expansion lags demand acceleration, creating supply bottlenecks for 800-volt solid-state relay qualification.
- EU F-Gas Regulation friction:Refrigerant circuit electrification timelines create specification uncertainty for HVAC-integrated relay modules.
Strategic Opportunities
- India's PLI scheme:Automotive component manufacturing incentives attract relay assembly investment for export-oriented electric two-wheeler and three-wheeler platforms.
- Mechatronic convergence:Integration of switching, protection, and diagnostic telemetry into single housings opens premium pricing tiers in European safety-critical applications.
- Silent operation demand:Solid-state relay penetration in luxury battery-electric segments creates technology differentiation pathways beyond cycling life metrics.
Industry Challenges
- ISO 26262 certification timelines:Functional safety documentation requirements extend product development cycles by 18-24 months for new relay platforms.
- High-voltage talent scarcity:Arc suppression and ceramic sealing expertise concentrates among aging engineering cohorts in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Relay Market |
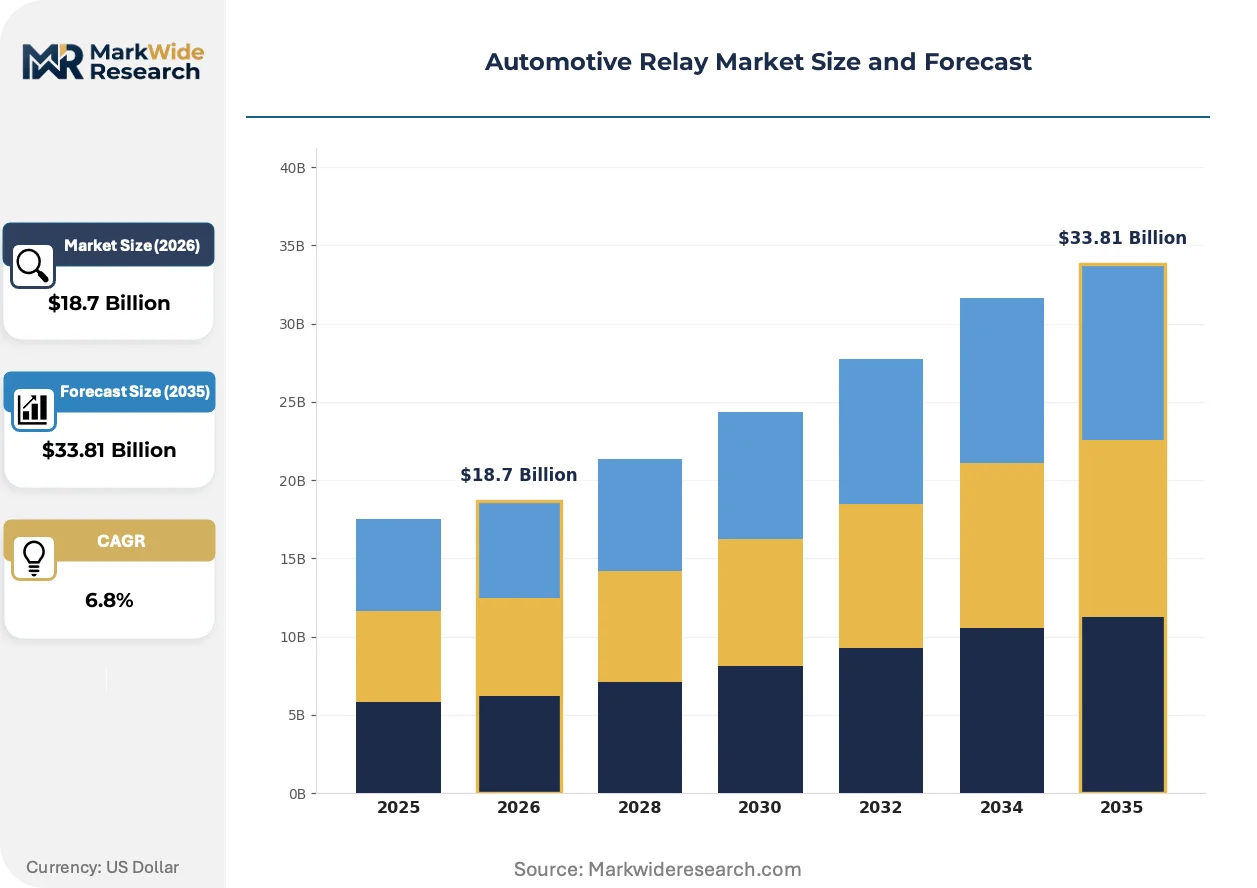
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Relays, Solid State Relays, Hybrid Relays, Latching Relays Application: Power Distribution, Lighting Control, Safety Systems, Infotainment Systems Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Motorcycles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | DENSO Corporation, TE Connectivity Ltd., Robert Bosch GmbH, Omron Corporation, Panasonic Corporation, HELLA GmbH & Co. KGaA, Fujitsu Limited, Littelfuse, Inc., Eaton Corporation plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Relay Market Emerging Trajectories
Component consolidation and intelligent switching are compressing traditional relay categories into multi-function modules, while regulatory pressure on vehicle safety systems accelerates certification complexity for electromechanical suppliers.
Intelligent relay modules with embedded current sensing and self-diagnostic capability are unifying discrete fuse, relay, and controller functions into single housings. Tier-1 suppliers are adopting these platforms for 800-volt electric vehicle power distribution units. This convergence is compressing tier-2 component counts and shifting value capture toward semiconductor-integrated suppliers.
The EU's F-Gas Regulation is accelerating refrigerant circuit electrification, mandating relay-compatible high-voltage compressor controls in thermal management systems. Automotive HVAC suppliers are redesigning switching architectures to accommodate R-1234yf and CO2 refrigerant pressures. German and French vehicle programs exhibit the fastest specification adoption timelines.
Fleet procurement of pre-validated relay subassemblies is displacing discrete component sourcing in commercial vehicle electrification programs. Tier-1 system integrators are consolidating supplier panels to reduce qualification overhead for battery-electric truck and bus platforms. North American heavy-duty vehicle manufacturing clusters show the most concentrated buyer consolidation behavior.
Automotive Relay Market Segmentation
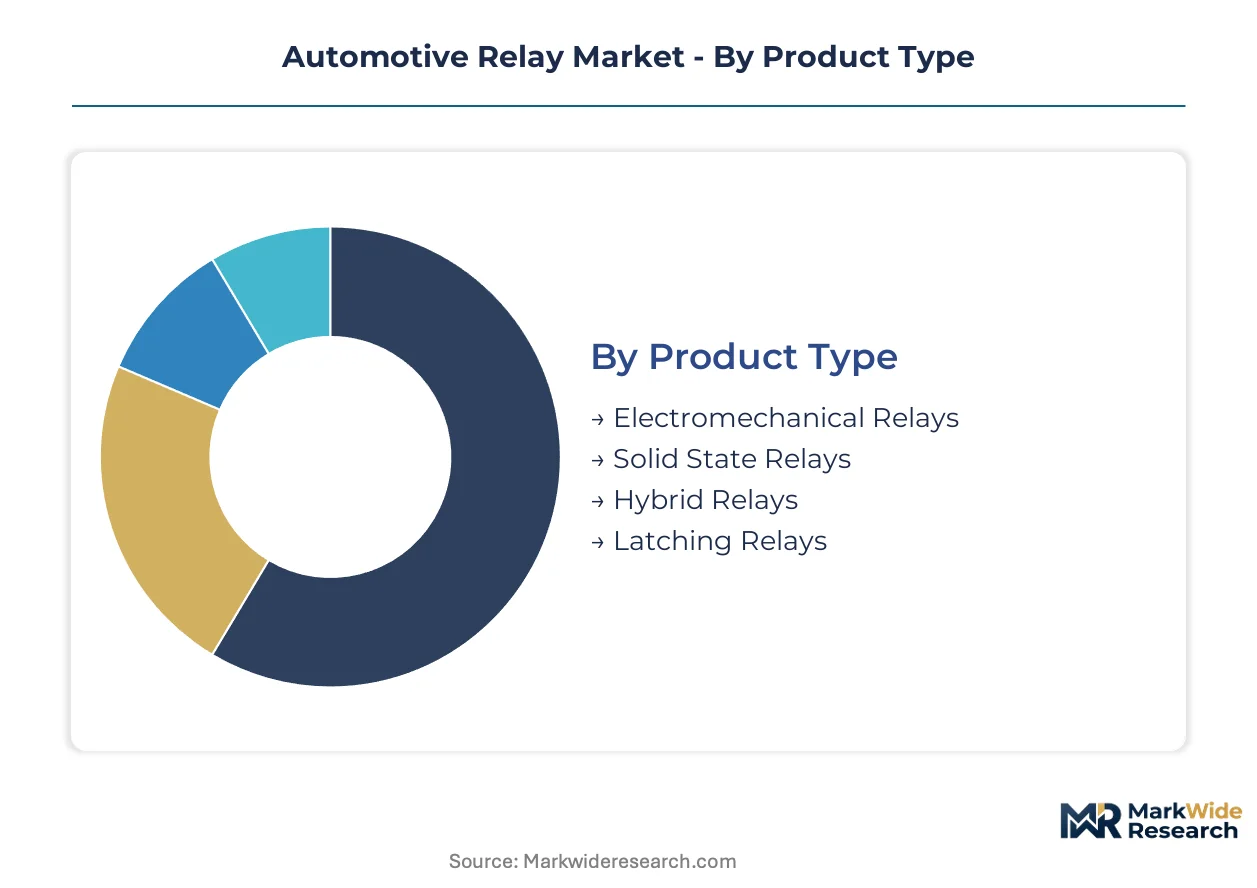
Automotive relay segmentation reveals how electrification pressures are fragmenting supplier portfolios across incompatible voltage architectures. Product type and application splits now determine which manufacturers capture value in 800-volt battery-electric platforms versus legacy 12/48-volt internal combustion programs.
Product Type:
Supply concentration for high-voltage contact materials favors integrated semiconductor-relay producers over discrete electromechanical specialists.
- Electromechanical Relays:These devices utilize magnetic coils to mechanically open and close contact circuits, with silver-copper alloy contacts dominating legacy 12-volt architectures. Demand concentrates in India's commercial vehicle corridors and Southeast Asian motorcycle manufacturing where cost minimization overrides cycling life requirements. Contact material price volatility constrains margin stability for volume producers serving these programs.
- Solid State Relays:Semiconductor-based switching eliminates mechanical wear and enables silent operation critical for luxury battery-electric passenger cabins. German and Japanese OEMs specify these for 800-volt thermal management and charging subsystems where unlimited cycling life justifies premium positioning. MIIT's GB/T high-voltage standards accelerate qualification timelines for domestic Chinese suppliers.
- Hybrid Relays:Combine electromechanical contact pairs with solid-state arc suppression for 48-volt mild-hybrid transition architectures. Adoption tracks European CO2 fleet compliance deadlines.
- Latching Relays:Maintain contact position without continuous coil power, suited for battery-electric parking lock and isolation applications where quiescent current draw must approach zero.
Electromechanical relays absorb the bulk of installed capacity; solid state relays are expanding most quickly.
Application:
Cost tier differentiation separates ISO 26262-certified safety applications from commodity power distribution volumes.
- Power Distribution:Manages battery-to-load current routing across fuse boxes and power distribution units, generating the highest unit volumes as vehicle electrical loads multiply. Chinese NEV platforms and German premium architectures drive specification divergence between 400-volt and 800-volt contact ratings.
- Safety Systems:Airbag deployment, anti-lock braking, and automatic emergency braking circuits demand redundant relay pathways under NHTSA FMVSS requirements. Stuttgart-Wolfsburg supplier clusters concentrate demand for integrated diagnostic functions that command premium pricing tiers.
- Lighting Control:Headlamp and LED matrix switching migrates toward solid-state solutions as adaptive driving beam complexity increases.
- Infotainment Systems:Low-current signal switching for display and amplifier power management, typically subordinate to domain controller integration trends.
Power distribution captures the greatest absolute unit volume; safety systems achieve the steepest pricing differentiation.
Vehicle Type:
Volume scale and relay count per vehicle diverge sharply between electrified platforms and internal combustion legacy.
- Passenger Cars:Multi-relay architectures per vehicle sustain absolute consumption dominance despite slower per-unit growth. European CO2 regulations and China's dual carbon goals accelerate powertrain electrification within this segment, multiplying redundant switching pathways for thermal management.
- Electric Vehicles:Battery-electric platforms require dedicated high-voltage relays for charging, pre-charge, and main contactor functions absent from internal combustion designs. Solid-state penetration rates climb fastest in this segment where silent operation and cycling endurance matter most.
- Commercial Vehicles:Fleet procurement consolidation in North American heavy-duty manufacturing favors pre-validated relay subassemblies over discrete sourcing.
- Motorcycles:India's PLI scheme attracts assembly investment for electric two-wheeler and three-wheeler export platforms with simplified relay requirements.
Passenger cars retain the greatest installed base; electric vehicles are gaining share fastest.
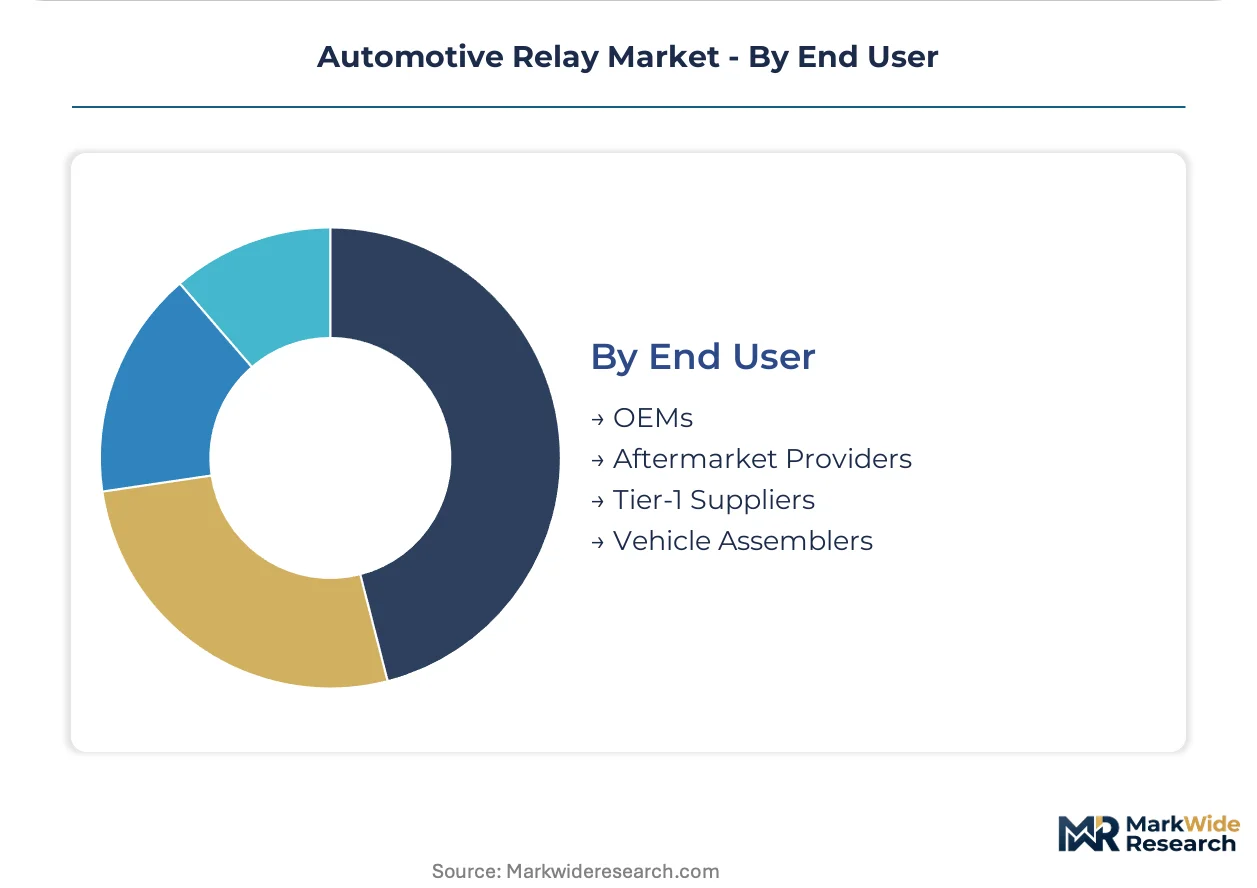
End User:
Customer type determines whether procurement flows through consolidated tier-1 panels or fragmented aftermarket channels.
- OEMs:Direct specification authority for platform-level relay architectures, increasingly mandating 800-volt qualification from captive or preferred suppliers. German and Japanese OEMs enforce the most stringent functional safety documentation requirements.
- Tier-1 Suppliers:System integrators consolidating supplier panels to reduce qualification overhead for battery-electric truck and bus platforms. Mechatronic relay modules with embedded diagnostics capture value migration from discrete components.
- Aftermarket Providers:Replacement demand concentrates in electromechanical variants for legacy vehicle parc maintenance, with pricing pressure from universal-fit imports.
- Vehicle Assemblers:Contract manufacturing arrangements in Southeast Asia and Mexico source relay subassemblies through tier-1 intermediaries rather than direct procurement.
OEMs and tier-1 suppliers command the supply chain; aftermarket providers serve the aging vehicle parc.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver-copper alloy deposits in Chile and Peru anchor contact material supply chains for electromechanical relay production, while manufacturing capacity clusters in Germany, Japan, China, and the United States shape regional competitive dynamics.
Germany
Stuttgart-Wolfsburg supplier corridors concentrate ISO 26262-certified safety relay demand for premium passenger car electrification. KBA enforcement of EU F-Gas Regulation accelerates refrigerant circuit relay redesigns for thermal management systems. Bavaria-based tier-1 integrators consolidate supplier panels around mechatronic modules with embedded diagnostics.
China
MIIT's GB/T high-voltage standards compress qualification timelines for domestic suppliers serving battery-electric platforms. Dual carbon goals and NEV mandates multiply relay counts per vehicle through redundant switching pathways. Yangtze River Delta production bases attract Southeast Asian capacity expansion from Japanese manufacturers seeking tariff-advantaged export positioning.
Japan
METI's JIS standards govern contact material specifications for hybrid and electric vehicle programs. Aging engineering cohorts concentrate arc suppression expertise in Nagoya and Tokyo manufacturing clusters. Southeast Asian production base expansion lags demand acceleration for 800-volt solid-state relay qualification.
United States
NHTSA FMVSS requirements for automatic emergency braking mandate redundant relay pathways that increase per-vehicle counts. Michigan and Ohio manufacturing clusters concentrate commercial vehicle fleet procurement of pre-validated relay subassemblies. IRA clean vehicle tax credits accelerate battery-electric platform adoption across heavy-duty truck programs.
India
PLI scheme incentives attract relay assembly investment for electric two-wheeler and three-wheeler export platforms. CEA grid electrification standards shape charging infrastructure relay specifications for urban mobility networks. Tamil Nadu and Maharashtra production corridors concentrate tier-1 system integrator sourcing for ASEAN-bound vehicle programs.
Automotive Relay Market Vendor Landscape
Global majors compete with regional champions across voltage architecture specialization, creating a tiered structure where integrated semiconductor-relay producers capture premium positioning in 800-volt platforms while discrete electromechanical specialists defend volume positions in legacy 12/48-volt applications. Three archetypes dominate: captive suppliers aligned with Japanese and German OEM electrification programs, independent component specialists serving tier-1 system integrators, and emerging Chinese domestic champions accelerating under MIIT qualification pressure. Competitive moves center on Southeast Asian capacity expansion and mechatronic module convergence that compresses discrete component counts.
Among Japanese-origin integrated suppliers, DENSO Corporation and Omron Corporation occupy positions anchored to Toyota and Honda electrification platforms, exemplifying the captive supplier archetype where semiconductor and relay assembly operations secure preferential supply relationships. TE Connectivity Ltd. represents the independent specialist tier with high-current contact technology positioning for 800-volt architectures. These three companies illustrate how geographic origin and customer alignment stratify competitive positioning across incompatible voltage transition timelines.
| Leading Market Players |
|---|
| DENSO Corporation |
| TE Connectivity Ltd. |
| Robert Bosch GmbH |
| Omron Corporation |
| Panasonic Corporation |
| HELLA GmbH & Co. KGaA |
| Fujitsu Limited |
| Littelfuse, Inc. |
| Eaton Corporation plc |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in Japan's Nagoya manufacturing belt anchor supply discipline through conservative capacity expansion and captive contact material inventories. Their reluctance to pursue leveraged growth preserves margin stability for ISO 26262-certified safety relays while constraining spot-market availability for commodity electromechanical variants.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from unbundled commodity producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Cost compression in electromechanical segments is intensifying because silver-copper alloy contact material volatility passes through to volume passenger car programs. Fleet procurement teams at North American commercial vehicle manufacturers exhibit highest price sensitivity, while German OEM platform engineers accept premium positioning for integrated diagnostic telemetry.
Supply Chain Analysis
Reverse-logistics flows for relay refurbishment remain underdeveloped, with end-of-life recovery concentrated in India's aftermarket channels for legacy vehicle parc maintenance. Manufacturing capacity clusters in Germany, Japan, and China feed from Chilean and Peruvian silver-copper deposits and Chinese rare-earth ceramic sealing materials. Single-source vulnerability concentrates in Japanese arc suppression engineering expertise. Distribution runs through tier-1 system integrator panels rather than direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-voltage solid-state relay qualification bottlenecks prop pricing power for qualified suppliers across the analysis window. Southeast Asian capacity expansion lags demand acceleration from Chinese NEV mandates.
For Market Incumbents: Deepen backward integration into contact material supply through captive offtake agreements with Chilean mining consortiums. Accelerate 800-volt solid-state relay certification investment to defend against emerging Chinese domestic champions capturing MIIT qualification timelines. Prioritize mechatronic module convergence that compresses tier-2 component counts and shifts value capture toward semiconductor-integrated platforms. For New Entrants and Emerging Players: Solid-state thermal management switching for luxury battery-electric cabins offers the most penetrable white-space target. India's PLI scheme incentives for electric two-wheeler relay assembly present secondary entry opportunity. Pursue qualification partnerships with Yangtze River Delta production bases to bypass Japanese capacity constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed Japanese electromechanical specialists with stranded 12-volt legacy capacity and Nagoya-based engineering cohorts. Five-to-ten year viability hinges on 800-volt platform penetration rates. Monitor MIIT GB/T standard revision announcements as inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| 800-Volt Platform Qualification | MIIT GB/T compliance unlocks supply positions with Chinese NEV manufacturers. |
| Mechatronic Module Integration | Bosch and HELLA consolidation of switching and diagnostic functions captures premium pricing tiers. |
| Southeast Asian Capacity Expansion | DENSO and Omron relocation mitigates tariff exposure for ASEAN-bound vehicle programs. |
| Solid-State Thermal Management Switching | Silent operation specifications from German luxury OEMs accelerate technology substitution. |
| Contact Material Backward Integration | Silver-copper alloy cost volatility hedging stabilizes margins for volume producers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and arc suppression engineering specialists combined with MIIT GB/T standard documents, NHTSA FMVSS rulemakings, and vehicle production databases. Bottom-up relay count-per-vehicle estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across propulsion architecture segmentation, voltage tier classification, and regional production cluster analysis shaped projection outputs throughout the forecast period. CAGRs derived from fitted adoption curves for 800-volt platform penetration and 48-volt mild-hybrid transition timelines. Modeled inputs included battery-electric vehicle production forecasts and ISO 26262 certification pipeline visibility.
Several conditions sit outside the modeled scope, including sudden F-Gas Regulation revision, raw material export restrictions from Chile or Peru, and breakthrough solid-state relay cost parity events. Forecasts reflect documented assumptions about Chinese NEV mandate enforcement continuity and German supplier corridor consolidation patterns. Practitioners should monitor MIIT qualification timeline announcements and Japanese engineering cohort retirement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Boat Wiring Harness Market