
 Smart Dash Cameras Market | 2026-2036
Smart Dash Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dash Cameras Market Insights
Embedded firmware engineering talent is collapsing across the consumer electronics tier, forcing dash camera makers to consolidate development around fewer platform architectures. Garmin Ltd leverages its in-house GPS chipset integration to sustain premium positioning in the dual-channel segment. Nextbase Global Ltd anchors its UK-European presence through proprietary emergency SOS connectivity, while Thinkware Corp dominates Korean domestic fleet contracts with thermal-hardened designs.
Smart dash cameras are windshield-mounted digital video recorders with integrated sensors, processors, and wireless modules that capture, store, and transmit continuous or event-triggered footage for liability documentation, driver behavior analysis, and incident reconstruction. Resolution thresholds now start at 1440p for front imagers, with advanced driver-assistance system overlays and AI-powered collision detection becoming baseline functional parameters. Dual-channel configurations lead unit shipments as consumers and fleet managers demand simultaneous front and rear coverage, while cloud storage subscriptions represent the fastest-expanding margin pool as manufacturers shift from hardware-only revenue to recurring service income. Night vision technology segments remain concentrated in premium tiers where Sony STARVIS sensor partnerships differentiate image quality under low-lux conditions.
FCC certification requirements govern wireless transmission modules in US-bound units, while EU Green Deal circular-economy directives are pressing manufacturers toward repairable designs and reduced rare-earth content in magnet assemblies. Japan's METI has issued technical conformity standards for dashboard-mounted devices that interfere with advanced driver-assistance system calibration, tightening product approval pathways. Stakeholders must weigh regulatory divergence against platform standardization bets as regional compliance costs escalate.
Market Dynamics
Fleet telematics mandates and insurance liability frameworks are compressing procurement cycles for cloud-connected dash camera systems, forcing manufacturers to consolidate around fewer platform architectures as embedded firmware engineering talent contracts.
Growth Catalysts
- FMCSA Hours-of-Service Enforcement:Commercial trucking operators across the United States face escalating compliance audits, accelerating replacement of legacy logging devices with integrated video telematics units that combine GPS tracking with continuous cabin recording.
- AI Collision Detection:Machine vision processors embedded in front imagers now trigger automatic incident flagging, reducing claims processing time for commercial auto insurers and creating pull-through demand from risk management departments.
- Municipal Fleet Modernization:Law enforcement agencies in Texas, California, and Florida are retiring analog dashboard systems, specifying dual-channel configurations with encrypted chain-of-custody protocols for evidence admissibility.
Market Restraints
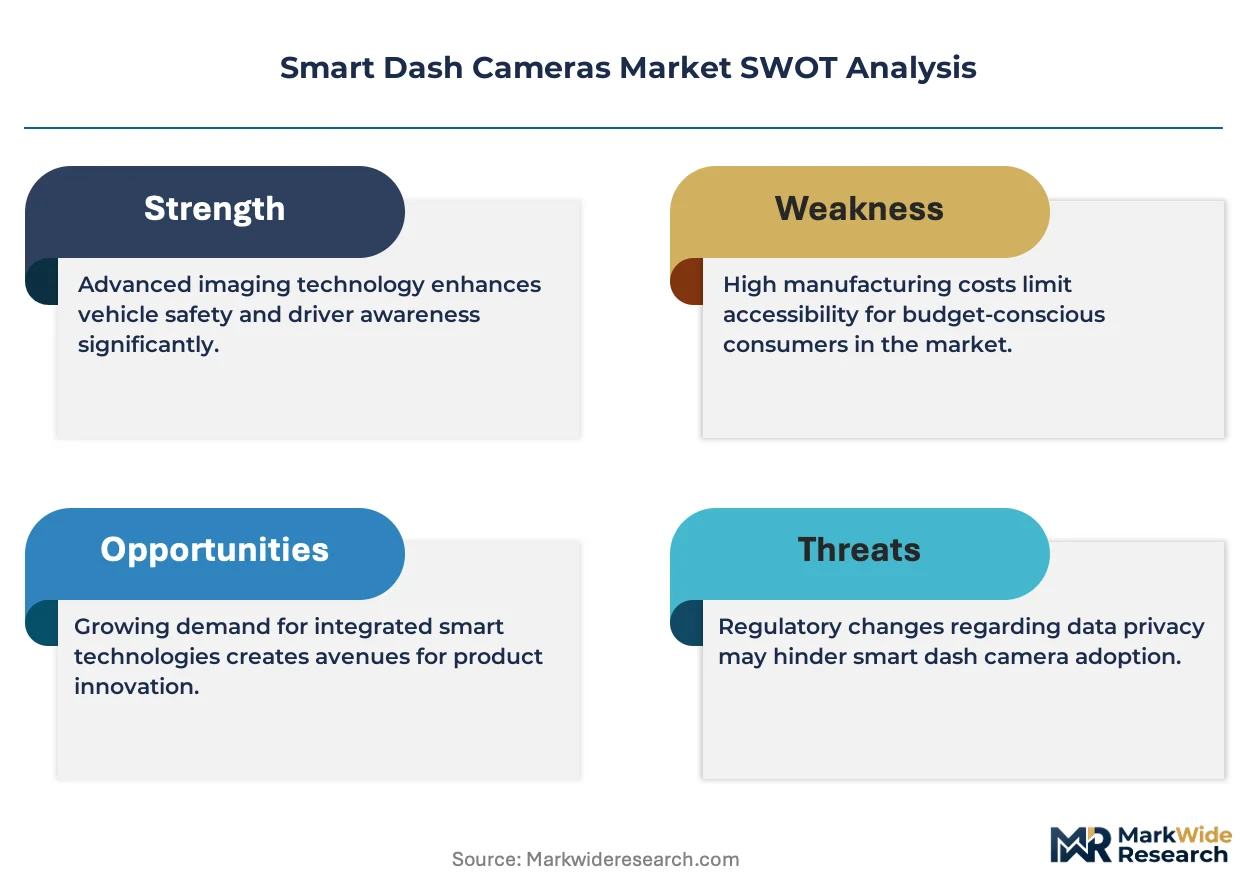
- Sony STARVIS Sensor Allocation:Premium night vision modules depend on concentrated CMOS supply from Japanese sensor fabs, exposing tier-one manufacturers to allocation volatility during semiconductor cycle peaks.
- FCC Certification Friction:Wireless transmission modules in US-bound units require electromagnetic compliance testing that extends product launch timelines by four to six months, compressing first-mover advantage windows.
- Smartphone Substitution:Consumer-tier buyers increasingly repurpose 4K-enabled handsets with suction mounts and third-party recording applications, eroding addressable market for entry-level standalone devices.
Strategic Opportunities
- EU Green Deal Circular-Economy Directives:Repairable design mandates and rare-earth reduction targets create first-mover positioning for manufacturers offering modular battery swaps and magnet-free mounting systems in German and French markets.
- Usage-Based Insurance Integration:Telematics data streams from dash cameras enable pay-per-mile underwriting models, opening white space with commercial auto carriers seeking behavioral risk scoring beyond traditional credit-based pricing.
- Thermal-Hardened Fleet Specifications:Oil field services and desert logistics operators in the Middle East require operating temperature ranges exceeding consumer-grade limits, supporting premium positioning for industrial-grade thermal engineering.
Industry Challenges
- Embedded Firmware Talent Scarcity:Consumer electronics engineering pipelines have contracted, forcing dash camera makers to compete for real-time operating system specialists against automotive and medical device recruiters.
- ADAS Calibration Interference:Japan's METI technical conformity standards for windshield-mounted devices require electromagnetic compatibility testing that delays product approval and fragments platform standardization bets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dash Cameras Market |
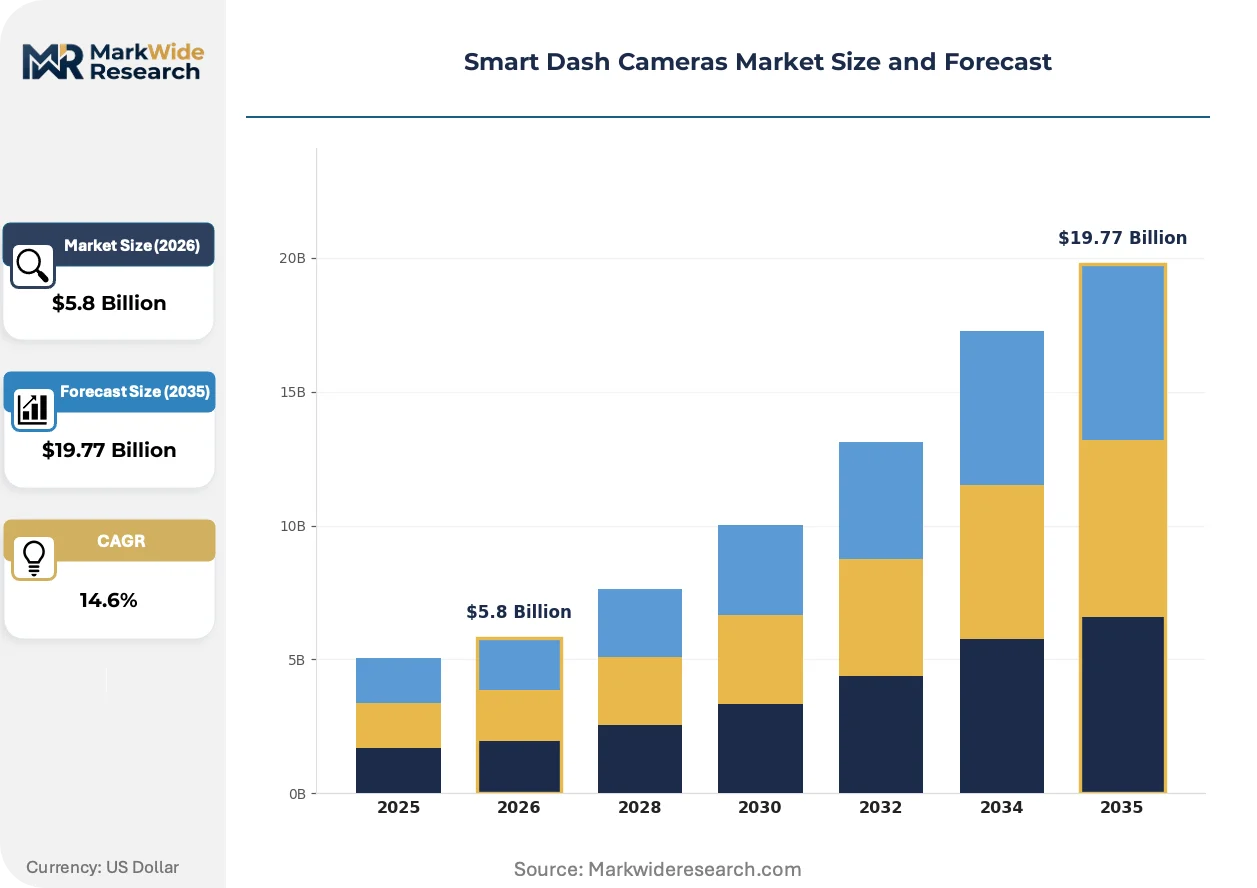
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Channel, Front-Facing, Rear-Facing, 360-Degree Technology: Wi-Fi, GPS, Cloud Storage, Night Vision End User: Personal Vehicles, Commercial Fleets, Ridesharing Services, Law Enforcement Installation Type: Wired, Wireless, Integrated, Portable |
| Companies Covered | Garmin Ltd, Nextbase Global Ltd, Thinkware Corp, Panasonic Corporation, Robert Bosch GmbH, Rexing, Pittasoft Co., Ltd, Viofo, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dash Cameras Market Trends and Innovations
Edge AI inference engines and solid-state storage architectures are compressing form factors while expanding real-time analytical capabilities. Manufacturers now compete on integration density rather than resolution specifications alone.
Multi-layer ceramic capacitors and system-in-package designs are miniaturizing power management circuits for dual-channel configurations. Fleet operators in the United States are specifying these compact units for cab installations where windshield real estate competes with toll transponders and satellite antennas. The resulting module shrinkage is enabling integrated rear-view mirror replacements that conceal recording hardware from driver distraction.
EU Green Deal circular-economy directives are mandating repairable designs and reduced rare-earth content in magnet assemblies. Manufacturers serving German and French markets must now document disassembly pathways and establish spare parts availability for seven-year minimums. Premium tier producers are responding with tool-free battery compartments and standardized screw patterns that reduce service technician training burdens.
Commercial fleet managers are consolidating vendor relationships around integrated video telematics platforms that bundle dash cameras with GPS tracking and driver behavior scoring. Tier-one trucking operators in Texas and California now specify single-source contracts for hardware, cloud storage, and analytics dashboards. This bundling is squeezing standalone dash camera distributors and compressing margins for hardware-only suppliers unable to provision recurring service revenue streams.
Smart Dash Cameras Market Segmentation
Smart dash camera procurement channels diverge sharply between consumer retail, fleet direct contracts, and municipal tender processes. Understanding these pathway distinctions clarifies why certain configurations dominate specific volume tiers while others command premium positioning.
Product Type:
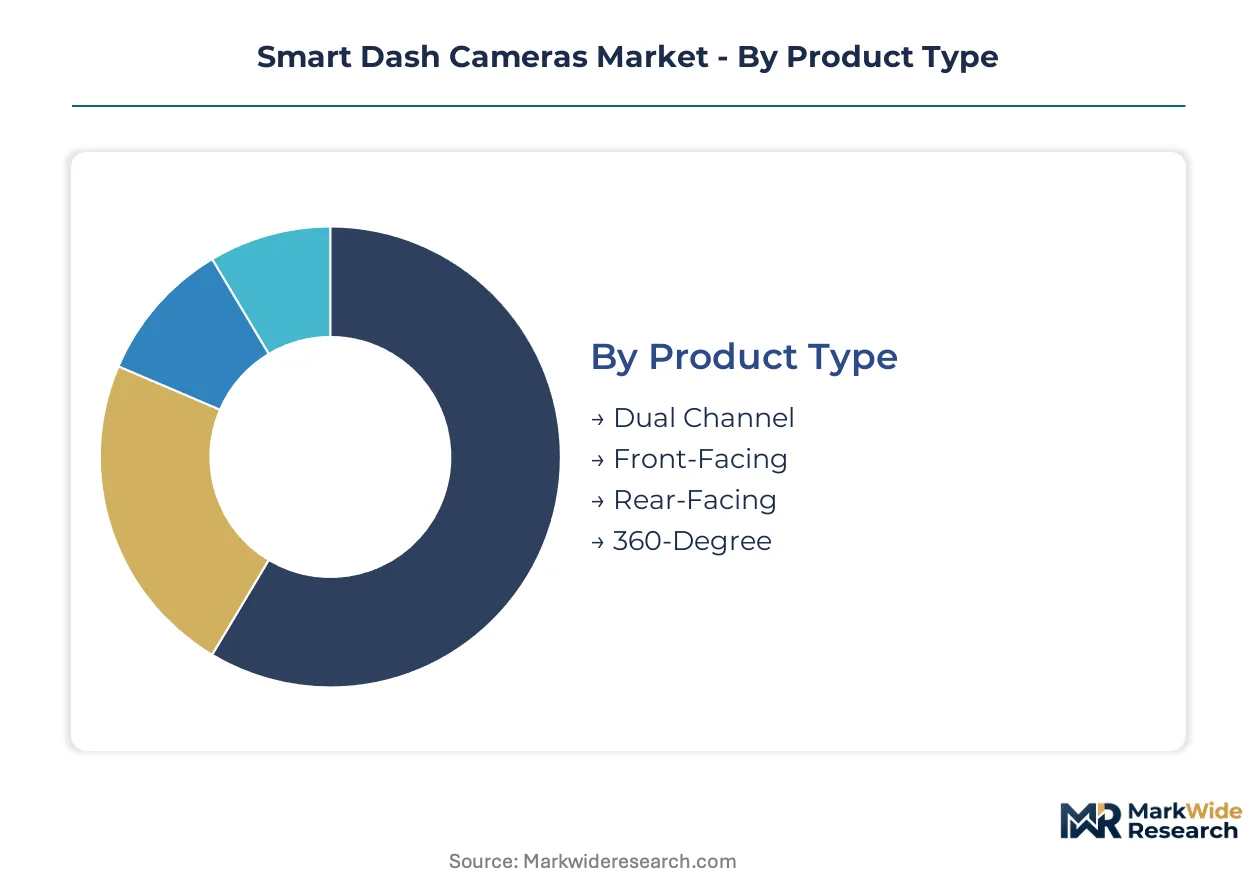
Dual-channel units flow predominantly through fleet telematics integrators and commercial vehicle upfitters, while single-lens configurations concentrate in big-box retail and direct-to-consumer e-commerce channels.
- Dual Channel:Simultaneous front and rear imagers with synchronized timestamping and unified storage management. Commercial trucking operators in the United States specify these for FMCSA hours-of-service compliance documentation, with encrypted dual-stream archiving becoming a standard fleet procurement requirement.
- Front-Facing:Single forward-oriented imager with 140-degree or wider field coverage. Personal vehicle owners in Germany and France purchase these through automotive aftermarket retailers, driven by insurance premium discount programs that mandate continuous forward recording.
- Rear-Facing:Supplementary cabin or rear-window imager designed for incident reconstruction from trailing vehicle perspective. Ridesharing drivers in California and Texas deploy these for passenger dispute documentation.
- 360-Degree:Multi-imager array with stitched panoramic output and object-tracking algorithms. Premium personal vehicle segments in Japan adopt these for parking surveillance and low-speed maneuver documentation under METI technical conformity frameworks.
Dual-channel configurations dominate installed base across commercial applications. Front-facing units are where expansion concentrates in consumer replacement cycles.
Technology:
Technology tiering follows a cost-to-capability ladder where basic connectivity modules anchor entry pricing and advanced sensor fusion commands three-to-four-fold premiums.
- Wi-Fi:Local wireless module enabling smartphone pairing for footage review and configuration. Personal vehicle owners in South Korea and the United States expect this as baseline functionality, with FCC certification adding four-to-six-month launch delays for US-bound units.
- GPS:Integrated geolocation chipset embedding coordinates and speed data into video metadata. Commercial fleet managers in Texas and California require this for driver behavior scoring and route verification, with Garmin Ltd leveraging in-house chipset integration for premium positioning.
- Cloud Storage:Subscription-based remote upload infrastructure with automated incident flagging. Commercial auto insurers in the United States are pulling this capability into underwriting workflows, creating recurring revenue streams that displace hardware-only margins.
- Night Vision:Low-lux sensor optimization, predominantly Sony STARVIS CMOS partnerships, enabling usable footage below 0.1 lux. Law enforcement agencies in Florida and municipal fleets in Arizona specify this for evidence-grade nighttime incident capture.
Wi-Fi and GPS modules saturate mid-tier configurations. Cloud storage subscriptions are climbing the fastest as manufacturers pivot from unit sales to service revenue.
End User:
End-user segmentation maps directly to procurement authority structures—individual purchase decisions, fleet procurement departments, platform-mediated driver requirements, and government tender offices.
- Personal Vehicles:Individual owner-operated passenger cars and light trucks. Consumers in the United Kingdom and Germany purchase these through automotive retailers and online marketplaces, with Nextbase Global Ltd's proprietary emergency SOS connectivity differentiating premium positioning.
- Commercial Fleets:Corporate-owned trucking, delivery, and service vehicle pools. Fleet operators across North America are consolidating vendor relationships around integrated video telematics platforms that bundle hardware with GPS tracking and analytics dashboards.
- Ridesharing Services:Driver-owned vehicles operating under platform-mediated transportation networks. Drivers in California and Texas face platform-mandated recording requirements for passenger safety documentation and dispute resolution.
- Law Enforcement:Municipal police departments and highway patrol agencies with evidence-chain requirements. Agencies in Texas, California, and Florida specify encrypted chain-of-custody protocols and tamper-evident mounting for courtroom admissibility.
Commercial fleets dominate hardware volume. Ridesharing services are gaining share fastest as platform mandates expand geographically.
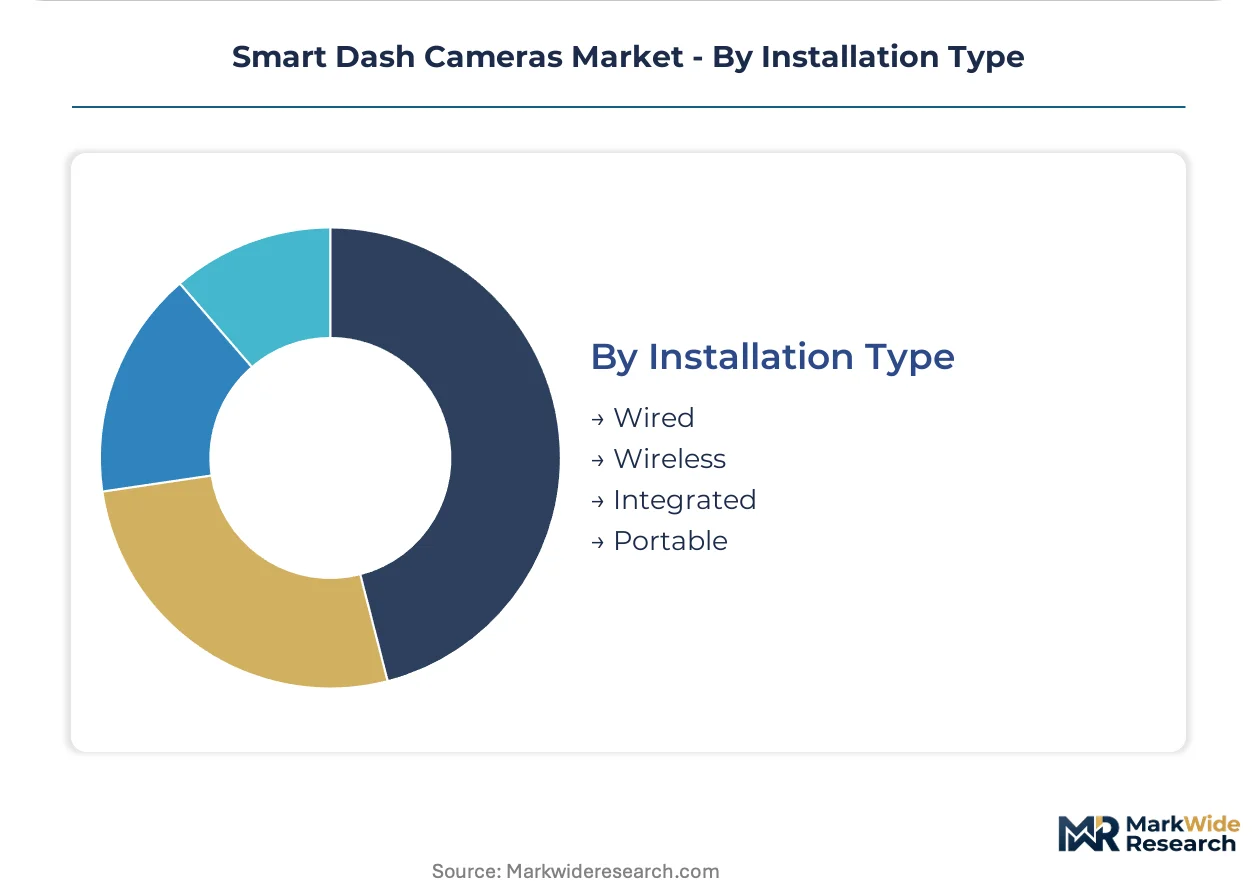
Installation Type:
Installation modality determines service revenue attachment and replacement cycle frequency, with hardwired configurations locking in longer hardware lifespans and portable units driving repeat purchase velocity.
- Wired:Hardwired connection to vehicle electrical system with ignition-sensing activation. Fleet upfitters in the United States prefer this for tamper resistance and continuous power management during extended parking surveillance.
- Wireless:Battery-powered or capacitor-backed operation with magnetic or adhesive mounting. Personal vehicle owners in Japan favor these for rental car compatibility and lease-vehicle restrictions on permanent modifications.
- Integrated:Factory-embedded or rear-view mirror replacement designs concealing hardware from driver distraction. EU Green Deal repairability mandates are pressuring manufacturers toward modular battery compartments and standardized screw patterns for these concealed installations.
- Portable:Suction-mounted or clip-on units transferable between vehicles. Entry-tier consumers in emerging markets and multi-vehicle households select these for flexibility, though smartphone substitution erodes this segment's addressable market.
Wired configurations dominate fleet-installed base. Integrated designs are expanding most quickly as windshield real estate competition intensifies with toll transponders and satellite antennas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements for wireless transmission modules anchor procurement dynamics in the United States, while EU Green Deal circular-economy directives and Japan's METI technical conformity standards fragment compliance pathways across major demand centers.
United States
Commercial fleet operators in Texas and California are accelerating procurement of cloud-connected units as FMCSA hours-of-service enforcement tightens. FCC electromagnetic compliance testing extends product launch timelines by four to six months for US-bound units. Fleet upfitters in the Midwest specify hardwired configurations for tamper resistance and continuous parking surveillance.
Germany
Automotive aftermarket retailers drive consumer adoption through insurance premium discount programs mandating continuous forward recording. EU Green Deal repairability mandates require seven-year spare parts availability and documented disassembly pathways. Manufacturers serving Bavaria and Baden-Württemberg are responding with modular battery compartments and standardized screw patterns.
Japan
METI technical conformity standards for windshield-mounted devices require electromagnetic compatibility testing that delays product approval. Premium personal vehicle segments in Tokyo and Osaka adopt 360-degree multi-imager arrays for parking surveillance. Sensor partnerships with domestic fabs concentrate in the Kanto industrial corridor.
South Korea
Domestic fleet contracts favor thermal-hardened designs for extreme operating conditions. Personal vehicle owners in Seoul and Busan expect Wi-Fi smartphone pairing as baseline functionality. The country's national electronics regulator enforces wireless module certification that shapes platform standardization bets.
United Kingdom
Proprietary emergency SOS connectivity differentiates premium positioning in consumer channels. Automotive retailers in London and the Midlands distribute single-lens configurations through insurance-linked discount programs. The country's national communications regulator governs wireless transmission standards for connected units.
Smart Dash Cameras Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Smart Dash Cameras Market. Consolidation pressures are intensifying as embedded firmware engineering talent contracts and platform standardization bets escalate. Three archetypes dominate: GPS-integrated chipset specialists, proprietary connectivity developers, and thermal-hardened industrial engineers. Competitive moves center on strategic partnerships for cloud infrastructure and backward integration into sensor supply.
Among Asia-Pacific fabricators, Thinkware Corp exemplifies the thermal-hardened industrial tier, while Garmin Ltd and Nextbase Global Ltd anchor Western positioning through differentiated integration strategies. These three occupy positions that reflect divergent bets on chipset control, emergency connectivity, and environmental resilience. Their collective presence illustrates how geographic clustering around regulatory requirements produces distinct competitive vectors rather than convergent global standards.
| Leading Market Players |
|---|
| Garmin Ltd |
| Nextbase Global Ltd |
| Thinkware Corp |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Rexing |
| Pittasoft Co., Ltd |
| Viofo |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
FCC electromagnetic compliance testing gates both supplier qualification and price differentiation simultaneously, extending launch timelines for US-bound units while compressing first-mover premiums. Manufacturers absorb these certification costs into premium-tier positioning, leaving economy configurations exposed to smartphone substitution erosion.
Pricing Analysis
Price spreads between Japanese sensor-integrated units and basic Wi-Fi configurations widen as Sony STARVIS allocation volatility concentrates premium night vision in top tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales cloud bundling. Cost compression in entry segments intensifies because smartphone suction-mount applications erode standalone device viability. Fleet procurement departments show least price sensitivity due to insurance liability framework mandates, while personal vehicle owners in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs through transpacific container lanes constrain just-in-time delivery for North American fleet upfitters. Manufacturing concentrates in China, South Korea, and Taiwan for CMOS sensors, printed circuit boards, and wireless modules. Final assembly draws from Japanese fabs for Sony STARVIS components and German automotive-grade connector suppliers. Single-source vulnerability in premium sensor allocation exposes tier-one manufacturers to semiconductor cycle peaks. Distribution runs through fleet telematics integrators, commercial vehicle upfitters, and automotive aftermarket retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation around integrated video telematics platforms has shifted buyer power toward large-scale commercial operators, fragmenting standalone hardware distributors. This concentration demands strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Consolidate cloud infrastructure partnerships to defend recurring revenue streams against hardware-only margin compression. Deepen backward integration into GPS chipset design following Garmin Ltd's captive supply model. Prioritize thermal-hardened engineering capabilities for Middle East oil field services contracts where specification barriers exclude consumer-grade competitors.
For New Entrants and Emerging Players: Cloud storage subscription gaps in municipal law enforcement tender processes offer white-space entry points. Target encrypted chain-of-custody protocol development for Texas and Florida police department specifications. Pursue usage-based insurance integration as the go-to-market angle, partnering with commercial auto carriers seeking behavioral risk scoring beyond traditional pricing models.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge AI inference engine development as solid-state storage architectures demand specialized firmware talent. Long-term viability favors platform-standardization bets over hardware-only plays. Monitor FCC certification backlog duration as the inflection signal for US market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Storage Subscription Pivot | Recurring revenue streams displace hardware-only margins for fleet telematics integrators. |
| Sony STARVIS Partnership Deepening | Premium night vision differentiation secures law enforcement evidence-grade procurement specifications. |
| Thermal-Hardened Engineering Investment | Desert logistics and oil field services operators demand operating ranges exceeding consumer limits. |
| EU Green Deal Design Compliance | Modular battery compartments and standardized screw patterns satisfy German and French repairability mandates. |
| ADAS Calibration Interference Mitigation | METI electromagnetic compatibility testing delays product approval without specialized shielding engineering. |
Research Methodology
A standing panel of fleet telematics procurement directors, automotive aftermarket category managers, commercial auto insurance underwriters, and embedded firmware engineering leads provided ongoing calibration. Primary interviews combined with secondary validation from FCC equipment authorization databases, EU Green Deal circular-economy directive filings, and FMCSA compliance audit records. Bottom-up unit shipment modeling triangulated against top-down fleet digitization expenditure estimates across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including vehicle production databases, commercial fleet registration data, and cloud infrastructure capex disclosures. Segmentation dimensions spanned product type, technology tier, end-user procurement authority, and installation modality. CAGRs derived from logistic adoption curve fitting applied to FMCSA enforcement timeline trajectories and insurance liability framework expansion patterns.
Material uncertainties — semiconductor allocation volatility, regulatory approval delays, and smartphone substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about fleet telematics mandate continuity and cloud storage subscription attach rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Smart Key Market